
 Seismic Reinforcement Materials Market | 2026-2036
Seismic Reinforcement Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Seismic Reinforcement Materials Market Analysis
Multi-source procurement for carbon fiber sheets and steel bracing systems is pivoting toward vertically integrated domestic suppliers as lead times from Asian manufacturers extend. Sika AG leverages its captive polymer chemistry capabilities to control formulation quality across European retrofit projects. Simpson Strong-Tie Company Inc. anchors North American distribution through contractor-direct channels and code-compliant connector catalogs. ArcelorMittal competes on heat-treated rebar volume, sustaining mill-direct pricing power in seismic zones.
Seismic reinforcement materials encompass engineered products designed to improve structural ductility and energy dissipation capacity during ground motion events, including grade 60 rebar with minimum yield strength of 60 ksi, epoxy-coated steel, and carbon fiber-reinforced polymer laminates with tensile modulus exceeding 230 GPa. These materials primarily serve to prevent progressive collapse and limit inter-story drift in reinforced concrete and steel frame structures subjected to design basis earthquakes. Steel dominates retrofitting applications across aging infrastructure portfolios, while fiber-reinforced polymer solutions capture premium positioning in bridge column wrapping where weight reduction and corrosion immunity justify higher material costs. Prefabricated modular bracing systems represent the fastest-expanding deployment mode, as offsite fabrication compresses installation schedules in dense urban corridors where lane closures face strict municipal limits.
Japan's METI enforces periodic seismic evaluation mandates for public buildings, directly sustaining demand for certified retrofitting materials through designated performance grade classifications. In the United States, FEMA publishes seismic rehabilitation guidelines while state-level building codes in California incorporate ASCE 41 provisions that specify minimum material strength requirements for retrofit acceptance. The European Union's Construction Products Regulation harmonizes CE marking obligations for structural steel and composite systems, conditioning market access on third-party testing against EN standards. Stakeholders must monitor evolving code cycles that progressively tighten ductility demands and assess whether their material certification portfolios align with jurisdiction-specific approval pathways.
Market Dynamics
Bridge contractors across Japan are accelerating fiber-reinforced polymer adoption as METI's updated seismic retrofitting guidelines tighten performance thresholds for public infrastructure. This regulatory compression is redrawing competitive boundaries between steel-rebar incumbents and composite-material specialists.
Growth Catalysts
- California Building Code Cycle:ASCE 41 provisions mandate minimum material strength thresholds for retrofit acceptance, sustaining procurement intensity across aging urban infrastructure portfolios.
- Prefabricated Modular Bracing:Offsite fabrication compresses installation schedules in dense municipal corridors where lane closures face strict duration limits.
- Epoxy-Coated Steel Corrosion Immunity:Coastal bridge columns in high-salinity environments specify coated reinforcement to extend service life beyond conventional unprotected grades.
Market Restraints
- Carbon Fiber Supply Concentration:Asian precursor manufacturers control upstream acrylonitrile conversion, exposing European retrofit contractors to extended lead times and allocation risk.
- Heat-Treated Rebar Energy Intensity:ArcelorMittal's mill-direct pricing power reflects natural gas and electricity input volatility that compresses margin buffers for distributors.
- Fiber-Reinforced Polymer Installation Skill Gap:Certified applicator scarcity limits deployment velocity despite material performance advantages over conventional steel bracing.
Strategic Opportunities
- European CE Marking Harmonization:The EU Construction Products Regulation's third-party testing requirements create barrier-to-entry protection for certified composite-system suppliers.
- Urban Corridor Micro-Retrofitting:Seismic isolation bearing retrofits for mid-rise concrete buildings represent underpenetrated demand within California's aging housing stock.
- Digital Twin Integration:Convergence of structural health monitoring sensors with reinforcement design software enables predictive maintenance contracts for bridge owners.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:FEMA guideline alignment with state-level amendments fragments approval pathways, delaying project mobilization.
- Legacy Steel Frame Compatibility:Inter-story drift calculations for 1970s-era moment-resisting frames require custom engineering that extends design-phase duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seismic Reinforcement Materials Market |
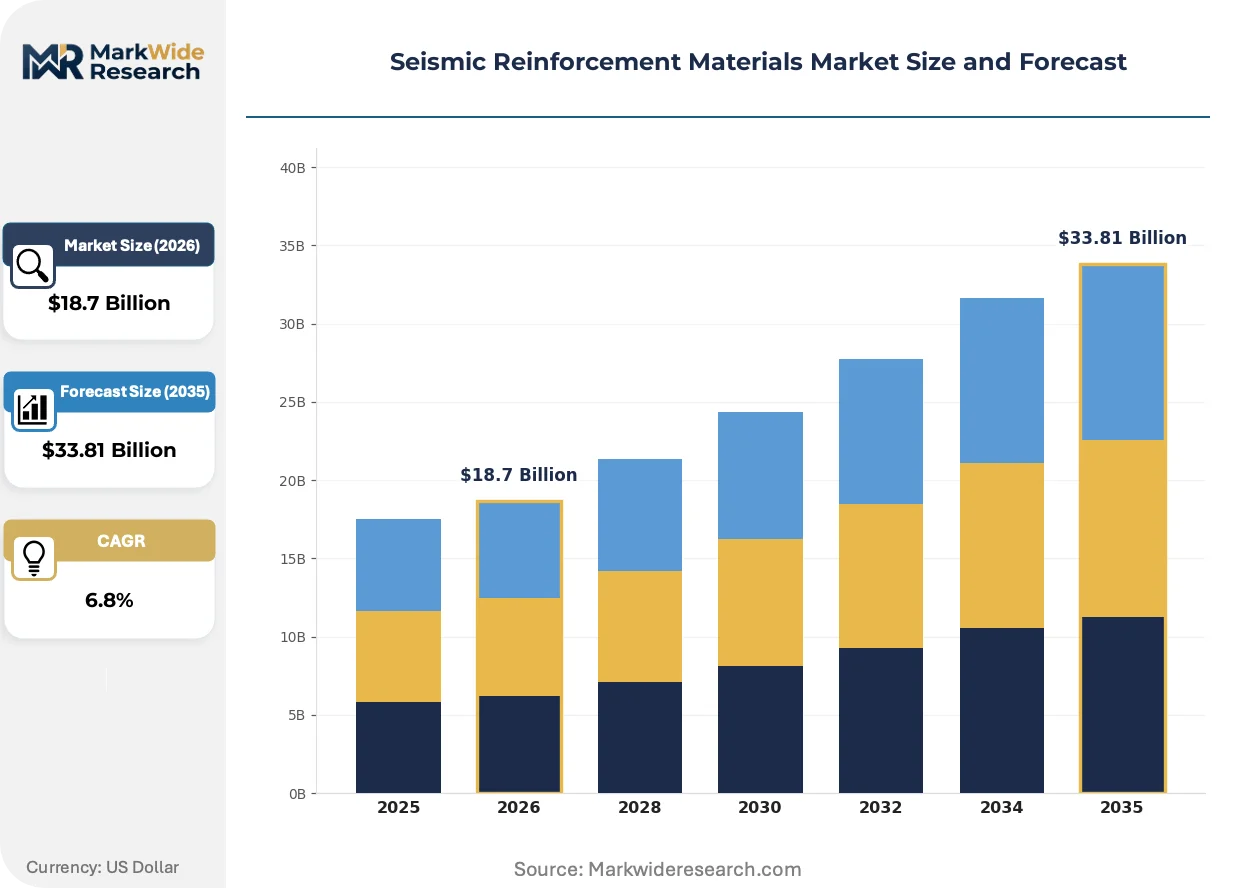
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Fiber-Reinforced Polymer, Carbon Fiber, Glass Fiber Application: Buildings, Bridge Construction, Retrofitting, Infrastructure End User: Contractors, Engineers, Government Agencies, Developers Deployment Mode: Onsite, Prefabricated, Modular Systems, Smart Solutions |
| Companies Covered | Sika AG, BASF SE, Hilti Group, 3M, ArcelorMittal, Toray Industries Inc., Freyssinet, Simpson Strong-Tie Company Inc., Hitech Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seismic Reinforcement Materials Market Emerging Trajectories
Seismic reinforcement is pivoting from reactive retrofitting toward predictive lifecycle management. Sensor-embedded materials and accelerated construction methods are compressing project timelines while expanding the addressable building stock beyond code-mandated public structures.
Shape-memory alloy tensioning devices are electrifying post-tensioned concrete rehabilitation. Bridge owners in high-seismic zones deploy nickel-titanium actuators that automatically restore prestress after seismic events. This self-healing capability is reducing post-earthquake inspection burdens and accelerating service restoration.
METI's periodic seismic evaluation mandates for Japanese public buildings now incorporate performance-based design criteria. Contractors must demonstrate energy dissipation capacity through full-scale testing rather than prescriptive compliance. Prefabricated steel bracing manufacturers are investing in captive shake-table facilities to secure designated performance grade classifications.
Contractor-direct specification is displacing distributor intermediation in North American seismic zones. Simpson Strong-Tie's code-compliant connector catalogs enable design engineers to select certified hardware without intermediary markup. Municipal procurement offices in California's urban corridor now maintain pre-approved vendor lists that bypass traditional material distribution channels.
Seismic Reinforcement Materials Market Segmentation
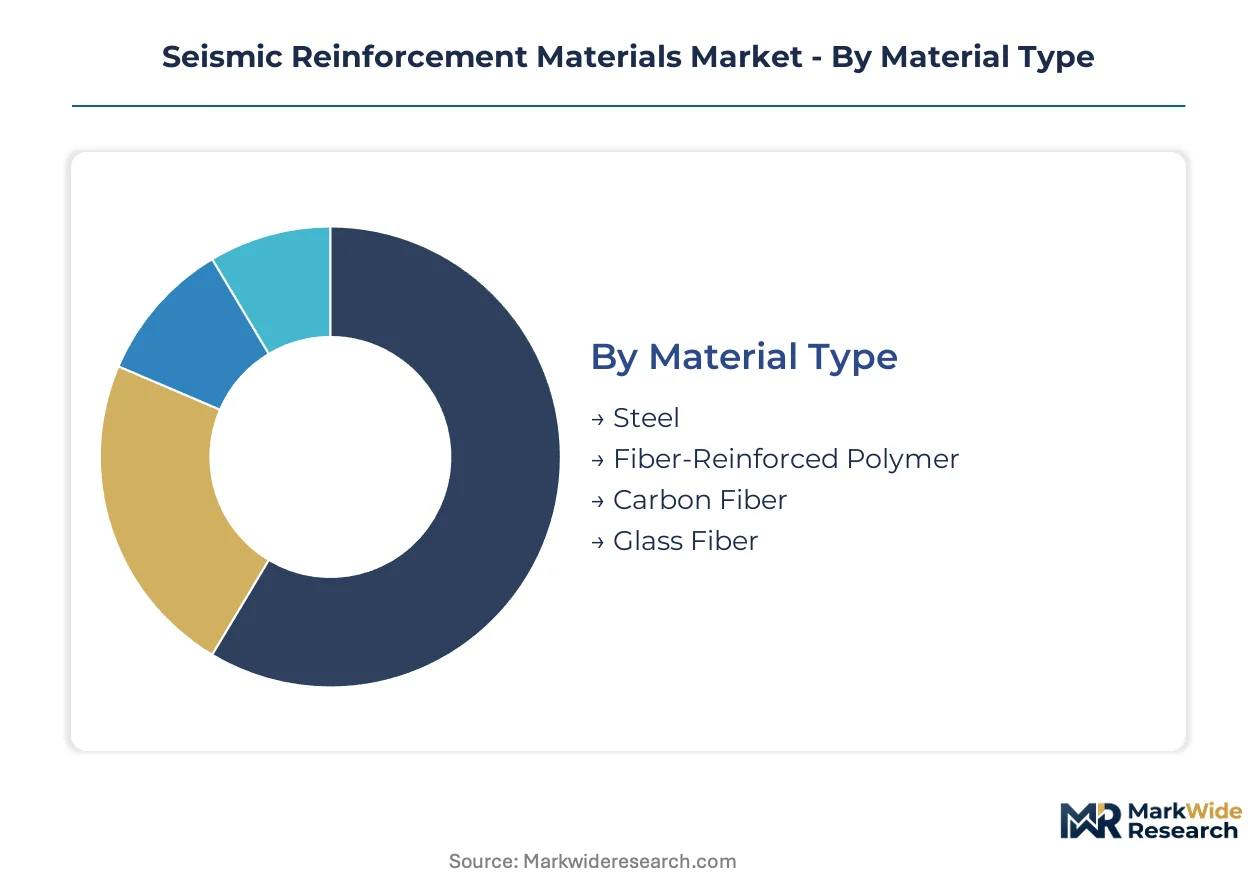
Seismic reinforcement materials serve distinct functional roles depending on structural substrate, installation environment, and regulatory compliance tier. Segmentation reveals where material substitution accelerates and which deployment modes compress project economics.
Material Type:
Standalone steel products dominate retrofitting where load-bearing capacity requirements exceed 60 ksi yield thresholds, while fiber-reinforced polymers embed within composite systems for corrosion-critical bridge columns.
- Steel:Grade 60 rebar and heat-treated bars deliver proven ductility for reinforced concrete moment frames. Procurement concentrates among California bridge contractors facing ASCE 41 strength mandates for public infrastructure rehabilitation. ArcelorMittal's mill-direct channels sustain volume leadership despite energy input volatility.
- Fiber-Reinforced Polymer:Epoxy-matrix composites with carbon or glass fiber reinforcement provide weight reduction and electrochemical immunity. Japanese bridge contractors under METI's updated guidelines specify FRP wraps for column confinement where steel corrosion risks service life.
- Carbon Fiber:High-modulus laminates exceeding 230 GPa tensile stiffness target premium structural upgrades. Asian precursor concentration exposes European contractors to allocation risk.
- Glass Fiber:Lower-cost composite reinforcement for non-critical structural elements and temporary bracing applications. Cost sensitivity limits deployment to secondary members.
Steel leads volumes today; fiber-reinforced polymer is gaining share fastest.
Application:
Cost tier stratification separates code-mandated public structures from discretionary private retrofits, with bridge construction commanding premium material specifications.
- Buildings:Mid-rise concrete structures in California's urban corridor drive demand for seismic isolation bearings and modular bracing. Municipal lane-closure restrictions compress installation schedules.
- Bridge Construction:Public infrastructure mandates under FEMA guidelines and state-level amendments specify minimum material strength for retrofit acceptance. Coastal high-salinity environments specify epoxy-coated reinforcement.
- Retrofitting:Aging 1970s-era moment-resisting frames require custom inter-story drift calculations. Legacy steel frame compatibility challenges extend design-phase duration.
- Infrastructure:Tunnels, dams, and utility structures beyond buildings and bridges. Performance-based design criteria from METI-style mandates are expanding addressable stock.
Bridge construction commands highest material specification intensity; building retrofits represent the largest addressable volume pool.
End User:
Customer type determines procurement channel structure, with government agencies bypassing distributor intermediation through pre-approved vendor lists.
- Contractors:Direct specification of code-compliant hardware accelerates in North American seismic zones. Simpson Strong-Tie's connector catalogs enable engineer selection without intermediary markup.
- Engineers:Design-phase material selection authority shapes project economics. Digital twin integration with structural health monitoring sensors enables predictive maintenance contracting.
- Government Agencies:Municipal procurement offices maintain certified vendor lists that fragment approval pathways across multi-jurisdictional code cycles.
- Developers:Private-sector building owners face discretionary retrofit decisions. Underpenetrated mid-rise housing stock in California represents expansion opportunity.
Contractor-direct procurement is displacing traditional distribution; government agency specification tightens compliance requirements.
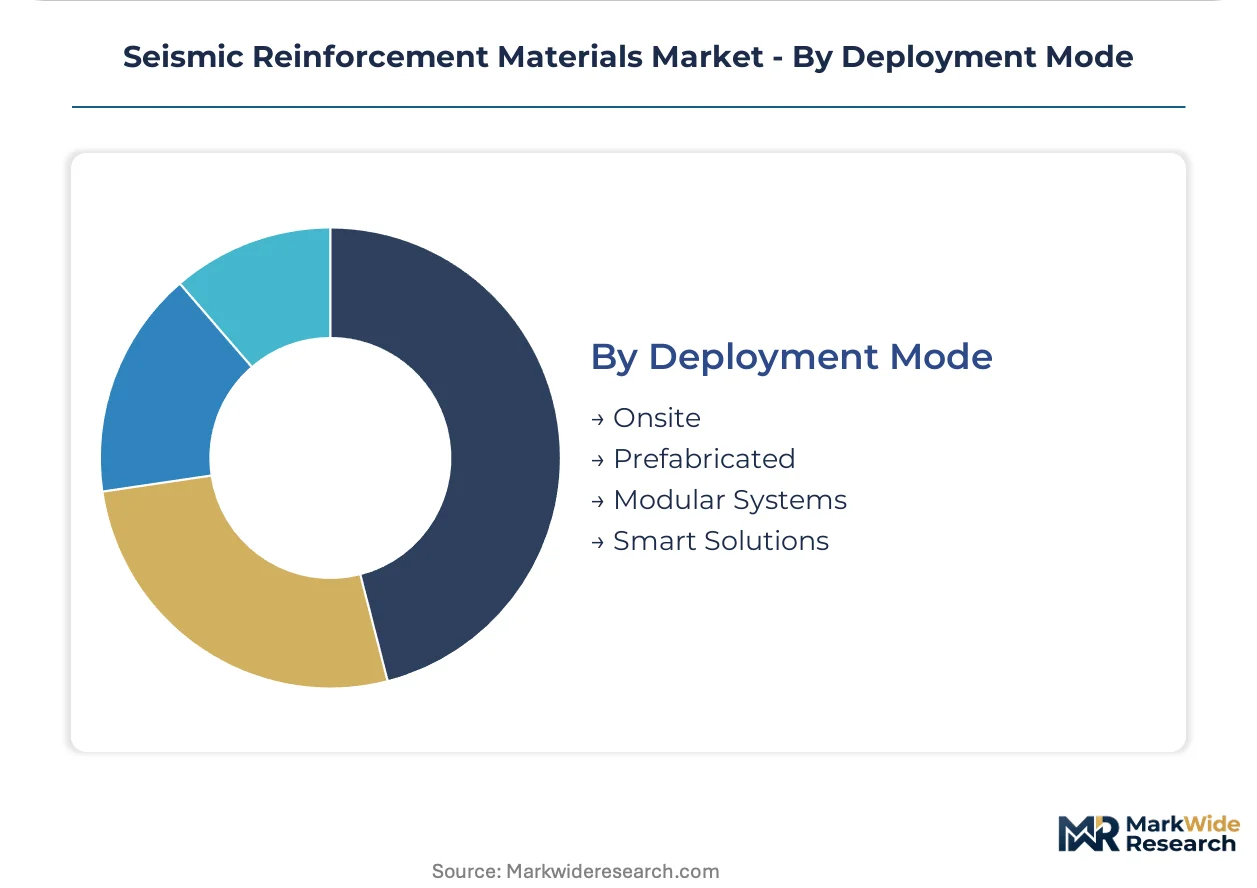
Deployment Mode:
Maturity gradient separates established onsite installation from emerging prefabricated and smart-enabled systems.
- Onsite:Traditional cast-in-place reinforcement with field welding and concrete placement. Labor intensity and lane-closure duration limits constrain urban corridor applicability.
- Prefabricated:Offsite fabrication of steel bracing modules compresses installation schedules. Japanese manufacturers invest in captive shake-table facilities for METI performance grade certification.
- Modular Systems:Standardized connector catalogs and pre-engineered components reduce design-phase duration. Code-compliant hardware selection bypasses custom engineering for legacy frames.
- Smart Solutions:Sensor-embedded materials and shape-memory alloy actuators enable post-seismic self-healing. Nickel-titanium tensioning devices reduce inspection burdens for bridge owners.
Onsite methods retain largest installed base; smart solutions are climbing the fastest despite certified applicator scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's urban corridor concentrates procurement intensity for seismic reinforcement materials, with aging infrastructure portfolios and strict building codes sustaining material demand across multiple continents.
United States
FEMA publishes seismic rehabilitation guidelines while state-level building codes in California incorporate ASCE 41 provisions. Municipal procurement offices maintain pre-approved vendor lists that bypass traditional distribution channels. Los Angeles and San Francisco anchor demand for grade 60 rebar and modular bracing systems.
Japan
Bridge construction contractors accelerate fiber-reinforced polymer adoption as METI's updated guidelines tighten performance thresholds. Periodic seismic evaluation mandates for public buildings sustain certified retrofitting material demand. Kanto and Kansai regions host captive shake-table facilities for performance grade certification.
Germany
The EU Construction Products Regulation harmonizes CE marking obligations for structural steel and composite systems. Third-party testing against EN standards conditions market access for seismic reinforcement suppliers. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate composite-system manufacturing.
China
Upstream acrylonitrile conversion for carbon fiber precursors concentrates among Asian manufacturers, exposing downstream contractors to allocation risk. GB standards govern structural material certification for domestic retrofit projects. Yangtze River Delta and Pearl River Delta regions dominate precursor chemical production.
Canada
Health Canada and provincial building codes align with seismic provisions for public infrastructure resilience. Coastal British Columbia specifies corrosion-immune reinforcement for high-salinity bridge environments. Vancouver and Toronto metropolitan areas drive procurement for epoxy-coated steel and isolation bearings.
Seismic Reinforcement Materials Market Vendor Landscape
Global majors compete with regional champions across certification pathways and distribution channels. The vendor base stratifies between mill-direct steel producers, captive polymer chemistry specialists, and contractor-direct hardware suppliers. Three archetypes dominate: integrated material formulators controlling upstream chemistry, mill-scale metallurgical producers leveraging energy-intensive heat treatment, and specification-driven connector catalog providers. Competitive moves concentrate on backward integration into precursor supply and shake-table certification investment.
Within the integrated-formulator tier, Sika AG exemplifies captive polymer chemistry capabilities, while BASF SE anchors European chemical supply for composite matrices. ArcelorMittal occupies a position among metallurgical producers with mill-direct channel control. These three represent distinct competitive vectors: formulation quality assurance, chemical feedstock security, and volume pricing power in seismic zones.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Hilti Group |
| 3M |
| ArcelorMittal |
| Toray Industries Inc. |
| Freyssinet |
| Simpson Strong-Tie Company Inc. |
| Hitech Materials Inc. |
| Others |
Supply Flow & Price Mechanics
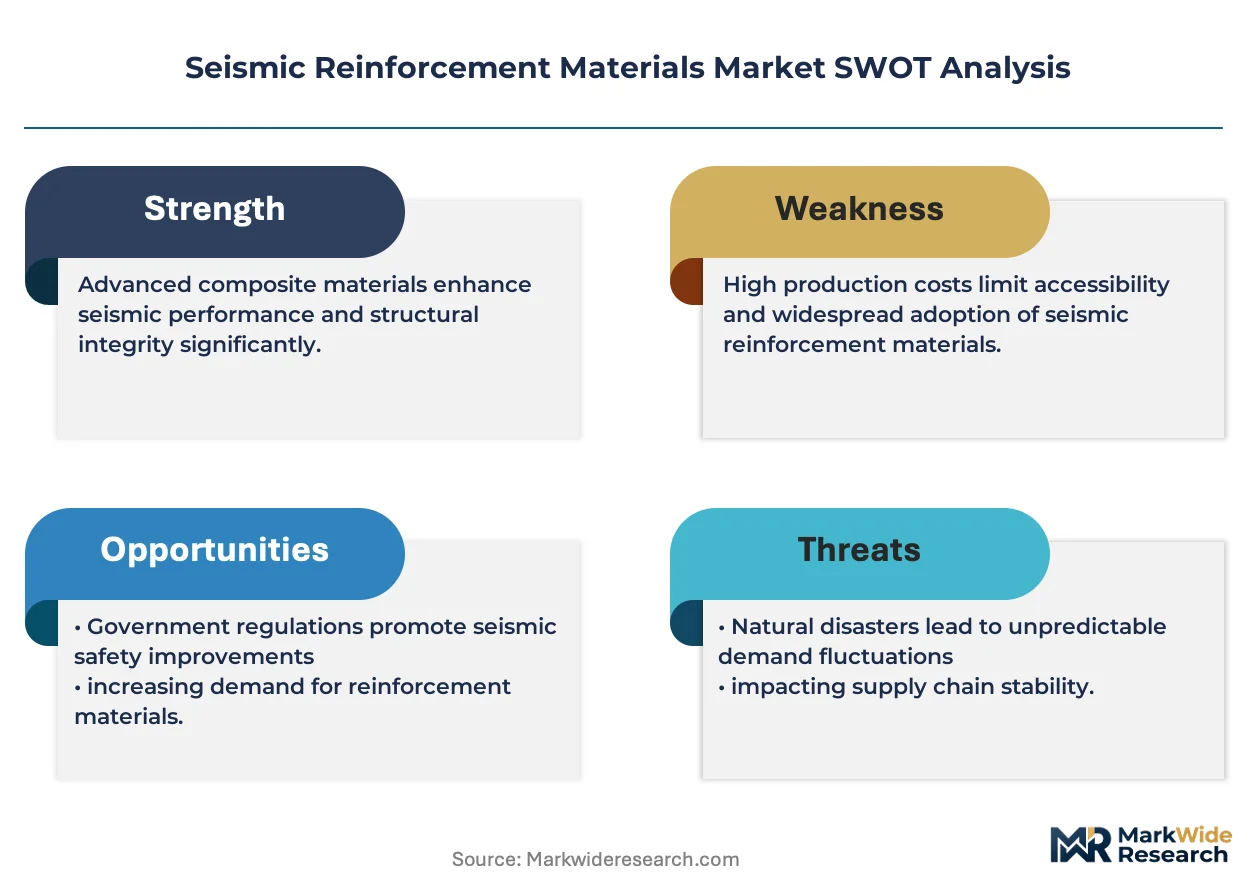
Captive polymer chemistry integration anchors pricing power for composite-system suppliers while exposing steel-centric competitors to energy-input volatility. Sika AG's in-house formulation control and ArcelorMittal's mill-direct channels illustrate how upstream ownership shapes margin defense across divergent material classes.
Pricing Analysis
Natural gas and electricity pass-through costs compress margin buffers for heat-treated rebar distributors serving seismic zones. Three-tier pricing structure across certified-performance, standard-grade, and economy-level reinforcement separates FEMA-compliant bridge materials from discretionary building retrofits. Cost compression in carbon fiber laminates is intensifying because Asian precursor concentration limits European contractor negotiating leverage. Municipal procurement offices demonstrate lowest price sensitivity due to code-mandated compliance thresholds, while private developers face acute cost pressure on discretionary retrofit decisions.
Supply Chain Analysis
Ocean freight and inland logistics costs for bulky steel bracing modules favor regional mill proximity over distant Asian sourcing. Upstream acrylonitrile conversion concentrates in China, Japan, and South Korea, exposing European retrofit contractors to allocation risk. Raw material dependencies span petroleum-derived epoxy resins, metallurgical-grade steel billets, and high-purity carbon fiber precursors. Single-source vulnerability in certified shake-table testing capacity fragments approval timelines for prefabricated systems. Distribution runs through contractor-direct channels in North America and designated performance-grade vendor lists in Japanese public procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seismic reinforcement materials function as a regulatory compounder where METI's updated performance-based guidelines and California's ASCE 41 adoption cycles structurally expand addressable demand.
For Market Incumbents: Anchor certification portfolios against multi-jurisdictional code fragmentation by investing in captive shake-table facilities for METI performance-grade classification. Defend against fiber-reinforced polymer substitution by accelerating heat-treated rebar energy efficiency programs that offset natural gas input volatility. Channel control through pre-approved vendor lists offers durable pricing power in municipal procurement corridors. For New Entrants and Emerging Players: Begin with seismic isolation bearing retrofits for California's underpenetrated mid-rise concrete housing stock, where legacy moment-frame compatibility challenges have slowed incumbent penetration. Target certified applicator training partnerships to overcome fiber-reinforced polymer installation skill gaps that constrain deployment velocity. A go-to-market angle anchored in digital twin integration with structural health monitoring sensors enables predictive maintenance contracting distinct from commodity material supply. For Investors and Strategic Acquirers: Consolidation pressure builds where certified composite-system suppliers face fragmented shake-table certification capacity and extended multi-jurisdictional approval timelines. Long-term viability favors targets with captive polymer chemistry capabilities and established CE marking pathways under the EU Construction Products Regulation. The signal to watch is METI-style performance-based design criteria adoption beyond Japan, which would expand addressable building stock for certified retrofitting materials.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive acrylonitrile sourcing insulates European composite manufacturers from Asian allocation constraints. |
| Shake-Table Certification Investment | Captive testing facilities secure METI performance-grade classifications required for Japanese public infrastructure bids. |
| Contractor-Direct Channel Expansion | Code-compliant connector catalogs bypass distributor markups in California's municipal procurement offices. |
| Smart Material Development Partnership | Sensor-embedded reinforcement enables predictive maintenance contracts with bridge owners seeking reduced inspection burdens. |
| Prefabricated Modular System Scale-Up | Offsite fabrication compresses installation schedules where urban lane-closure restrictions constrain onsite methods. |
Methodological Framework
Multiple input streams — primary interviews with bridge contractors and seismic design engineers, regulatory filing analysis, and trade flow databases — were reconciled to construct market estimates. Stakeholder engagement spanned procurement managers at California municipal agencies, Japanese METI certification officers, composite-system technical directors, and steel mill sales executives. Secondary validation drew from FEMA guideline publications, ASCE 41 code amendment records, EU Construction Products Regulation testing protocols, and customs data for carbon fiber precursor shipments. Bottom-up project pipeline analysis and top-down infrastructure spending forecasts were triangulated to cross-check volume assumptions.
Historical retrofit project completion patterns were cross-referenced against expert panel assessments of regulatory cycle timing. Segmentation modeling spanned material type, application intensity, end-user procurement channel, and deployment mode maturity across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating code-mandated replacement schedules and discretionary upgrade propensity. Industry-specific forecast inputs included shake-table certification queue lengths, acrylonitrile spot price volatility bands, and municipal lane-closure permit issuance trends.
Several conditions sit outside the modeled scope, including extreme seismic event frequency beyond historical baselines and abrupt regulatory harmonization across jurisdictions. Forecasts reflect assumptions about continued code enforcement intensity and material substitution elasticity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Global Industrial Foam Market