
 Reflective Thermal Insulation Coatings Market | 2026-2036
Reflective Thermal Insulation Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Reflective Thermal Insulation Coatings Market Insights
Industrial roofing demand is decoupling from traditional bituminous systems as facility operators prioritize thermal performance over upfront material cost. Akzo Nobel NV leverages its marine coatings heritage to transfer weathering expertise into industrial reflective formulations. PPG Industries anchors North American supply through dedicated architectural coil coating lines. Kansai Paint Co. Ltd. competes aggressively in Asian industrial projects with localized production of solvent-based high-build systems.
Reflective thermal insulation coatings are formulated with ceramic microspheres, aluminum flakes, or titanium dioxide pigments suspended in acrylic or polyurethane binders, engineered to achieve solar reflectance index values above 78 and thermal emittance exceeding 0.75 for rooftop and envelope applications. Water-based acrylic formulations dominate residential and light commercial specification due to lower volatile organic compound profiles and simplified cleanup protocols. Solvent-based polyurethane systems command premium positioning in industrial and automotive applications where chemical resistance and substrate adhesion across metal, concrete, and modified bitumen create differentiated performance thresholds.
US Department of Energy building standards, California Title 24 cool roof mandates, and EPA Energy Star roof certification programs collectively establish minimum reflectance benchmarks that filter non-compliant products from public and utility-incentivized projects. ASTM C1549 and ASTM E1980 testing protocols provide the measurement architecture governing product qualification and comparative marketing claims. Stakeholders must monitor evolving state-level stretch codes and utility rebate recalibrations that could abruptly reweight the economic case for retrofit versus new-build specification.
Market Dynamics
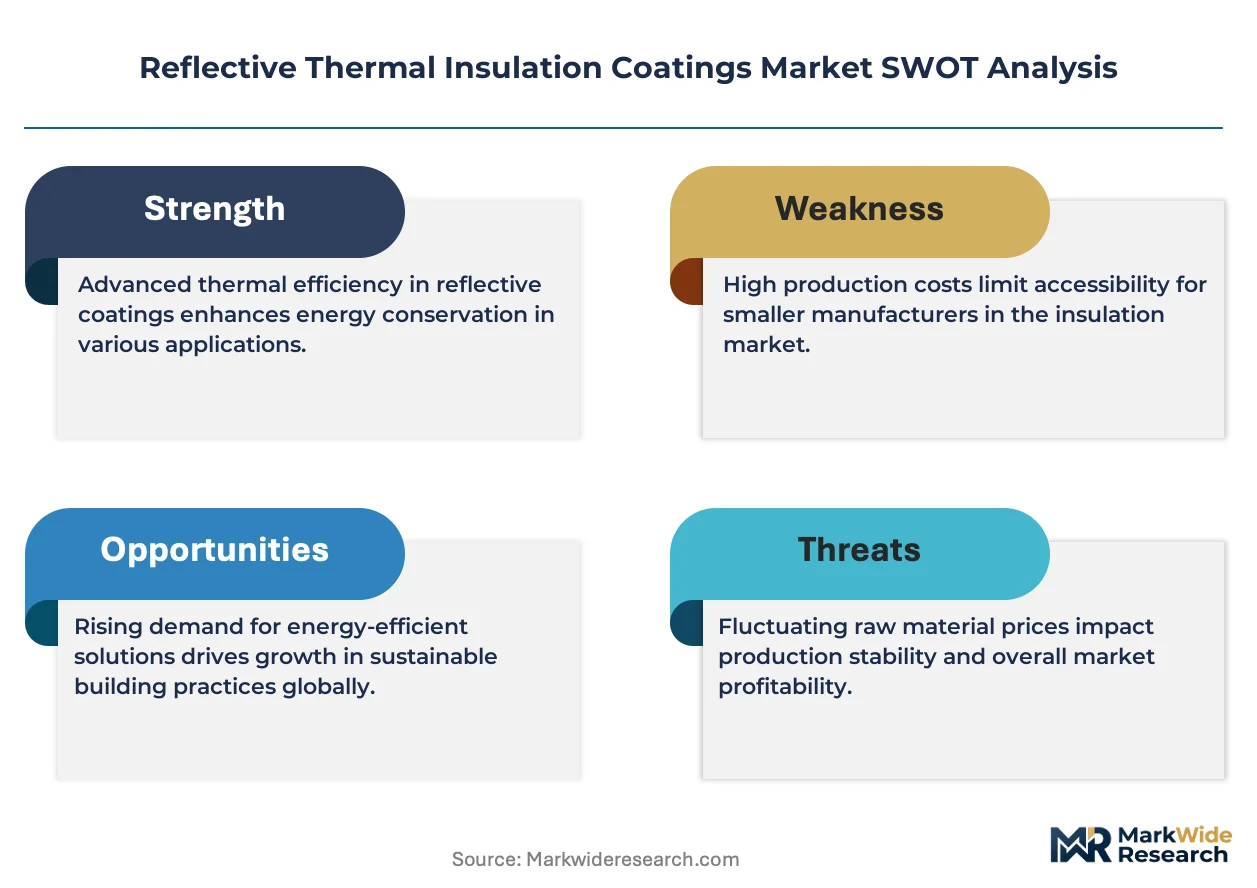
The Reflective Thermal Insulation Coatings Market is being fundamentally restructured by the US Department of Energy's escalating cool roof mandates, which are compressing specification cycles and forcing coating manufacturers to revalidate formulations against ASTM E1980 protocols on compressed timelines.
Growth Catalysts
- California Title 24 cool roof mandates:Building code amendments in California now require minimum solar reflectance index thresholds for low-slope commercial re-roofing, creating a compliance-driven replacement cycle across the Sun Belt.
- Industrial facility energy intensity targets:Data center operators and logistics warehouse owners are specifying high-emittance coatings to offset server rack cooling loads and reduce peak demand charges from utilities.
- Ceramic microsphere technology maturation:Hollow borosilicate microspheres with sub-100-micron diameters now achieve thermal conductivity below 0.06 W/m·K, enabling single-coat application protocols that cut labor hours by half.
Market Restraints
- Titanium dioxide pigment cost volatility:Rutile TiO2 prices fluctuate with chloride process feedstock availability, compressing gross margins for water-based acrylic formulations that require high pigment loading.
- Application seasonality in temperate climates:Solvent-based polyurethane systems face restricted application windows in northern US states where substrate temperatures fall below 50°F for five months annually.
- Modified bitumen substrate incompatibility:Existing built-up roofing systems with oxidized asphalt surfaces require intensive surface preparation or complete tear-off, inflating retrofit project costs.
Strategic Opportunities
- Mexico industrial corridor penetration:Automotive assembly plants in Guanajuato and aerospace facilities in Baja California lack cool roof adoption despite extreme cooling-degree-day intensity.
- Utility rebate program expansion:Demand response incentives from Arizona Public Service and Southern California Edison now cover reflective roof coatings as qualifying load reduction measures.
- Drone-assisted application services:Coating contractors are deploying UAV-mounted spray systems for steep-slope metal roofing in wind farm and telecommunications tower applications.
Industry Challenges
- ASTM C1549 certification backlog:Third-party testing laboratory capacity constraints are extending product qualification timelines from 8 weeks to 16 weeks, delaying commercial launches.
- Skilled applicator shortage:Spray polyurethane foam and coating contractors face 22% annual turnover rates, forcing manufacturers to expand in-house training academies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reflective Thermal Insulation Coatings Market |
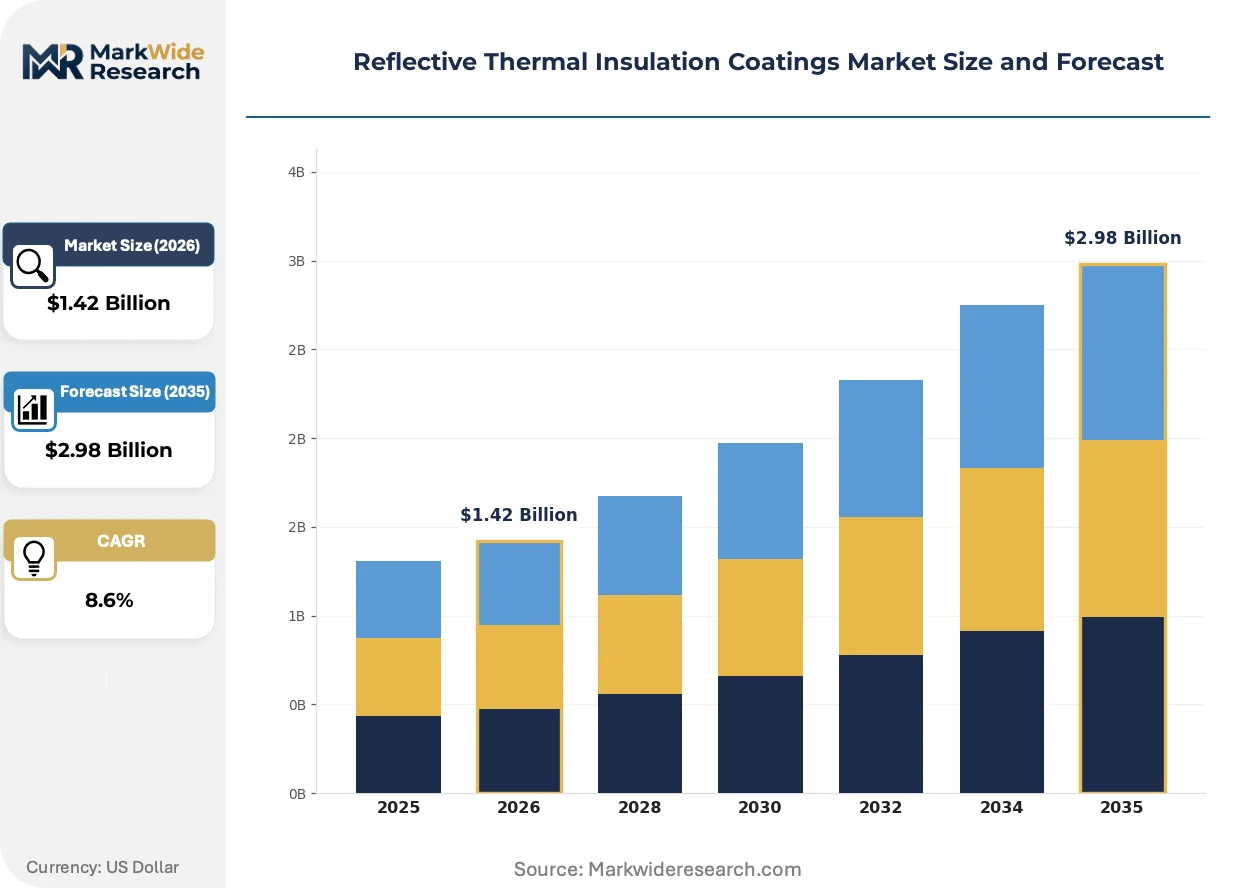
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Water-Based, Solvent-Based Application: Residential, Commercial, Industrial, Automotive End User: Building Owners, Contractors, Architects, Manufacturers Technology: Spray, Roll-On, Brush-On, Liquid |
| Companies Covered | Akzo Nobel NV, Asian Paints Ltd, Axalta Coating Systems Ltd, BASF SE, PPG Industries, Jotun AS, The Sherwin-Williams Company, Kansai Paint Co. Ltd., Mascoat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reflective Thermal Insulation Coatings Market Trends and Innovations
Formulation chemistry and application methodology are converging to compress project timelines while extending service life guarantees. Manufacturers are integrating predictive weathering data and real-time substrate monitoring to differentiate performance claims.
Phase-change material microencapsulation is rewriting thermal mass dynamics in envelope coatings. Warehouse operators in Texas and Florida are specifying PCM-integrated acrylic systems that absorb peak solar gain and release heat during evening hours. This technology is compressing the performance gap between reflective coatings and insulated roof assemblies without structural load penalties.
EPA Energy Star roof certification program revisions are tightening emittance minimums for steep-slope residential products. Coating manufacturers serving the single-family reroof segment are reformulating with infrared-reflective complex inorganic color pigments to maintain aesthetic variety while meeting the new 0.75 thermal emittance threshold. California and Florida contractors report specification delays as distributors clear inventory of pre-revision formulations.
Facility managers are unbundling coating procurement from roofing contractor relationships and establishing direct specifications with material suppliers. Industrial real estate investment trusts in the Dallas-Fort Worth metroplex now mandate pre-approved coating manufacturer lists across their property portfolios. This behavior shift is compressing regional distributor margins while rewarding manufacturers with national account service capabilities.
Reflective Thermal Insulation Coatings Market Segmentation
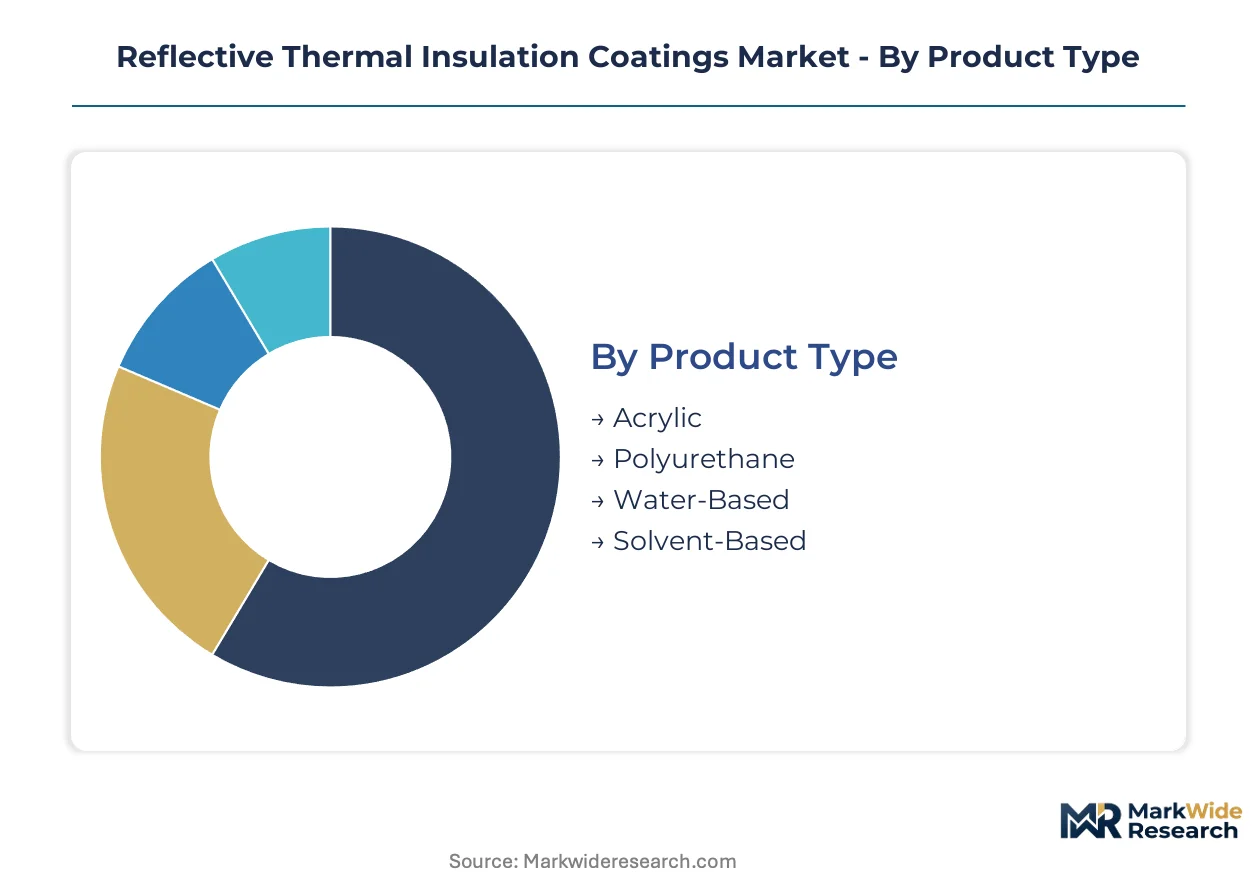
Reflective thermal insulation coatings serve divergent performance requirements across building envelopes, industrial facilities, and transportation assets. Segmentation reveals how formulation chemistry and application methodology must align with substrate conditions, regulatory exposure, and lifecycle cost expectations.
Product Type:
Acrylic and polyurethane chemistries dominate specification decisions, with water versus solvent carrier selection filtering compliance-sensitive projects from heavy-duty industrial applications.
- Acrylic:Water-dispersed acrylic polymers loaded with titanium dioxide and ceramic microspheres achieve solar reflectance index values above 78. Facility managers in California and Florida specify these formulations for Title 24 compliance on low-slope commercial re-roofing where volatile organic compound restrictions apply.
- Polyurethane:Aliphatic polyurethane binders cross-link into films with superior chemical resistance and elastomeric recovery across metal, concrete, and modified bitumen substrates. Industrial warehouse operators in Texas and Arizona accept higher material costs for single-coat coverage that withstands forklift traffic and chemical washdown protocols.
- Water-Based:Lower volatile organic compound profiles simplify cleanup and reduce contractor liability exposure in occupied buildings.
- Solvent-Based:Superior substrate penetration and moisture tolerance extend application windows in humid coastal climates.
Mature deployment sits with acrylic systems. Newer deployment is concentrated in polyurethane formulations with enhanced ceramic microsphere loading.
Application:
Cooling-degree-day intensity and energy code stringency create sharp demand gradients across building categories.
- Residential:Single-family reroof segments in Sun Belt states drive volume for infrared-reflective complex inorganic color pigments that maintain aesthetic variety while meeting thermal emittance thresholds. EPA Energy Star certification revisions are forcing inventory clearance of pre-revision formulations.
- Commercial:Industrial real estate investment trusts in Dallas-Fort Worth and Phoenix now mandate pre-approved coating manufacturer lists across property portfolios, compressing regional distributor margins.
- Industrial:Data center operators and logistics warehouse owners specify high-emittance coatings to offset server rack cooling loads.
- Automotive:OEM paint shops apply reflective primers to reduce interior cabin temperatures and air conditioning load.
Volume concentrates in commercial low-slope roofing. Steepest expansion trajectory appears in industrial facility retrofits.
End User:
Procurement authority is shifting from general contractors toward direct material specification by asset owners and design professionals.
- Building Owners:Industrial real estate investment trusts unbundle coating procurement from roofing contractor relationships.
- Contractors:Spray polyurethane foam and coating contractors face skilled applicator shortages with annual turnover rates near 22 percent.
- Architects:Design professionals specify ASTM E1980-compliant formulations to secure utility rebate eligibility.
- Manufacturers:Automotive and appliance OEMs integrate reflective coatings into product thermal management strategies.
Specification authority is migrating toward building owners. Technical validation responsibility remains with architects.
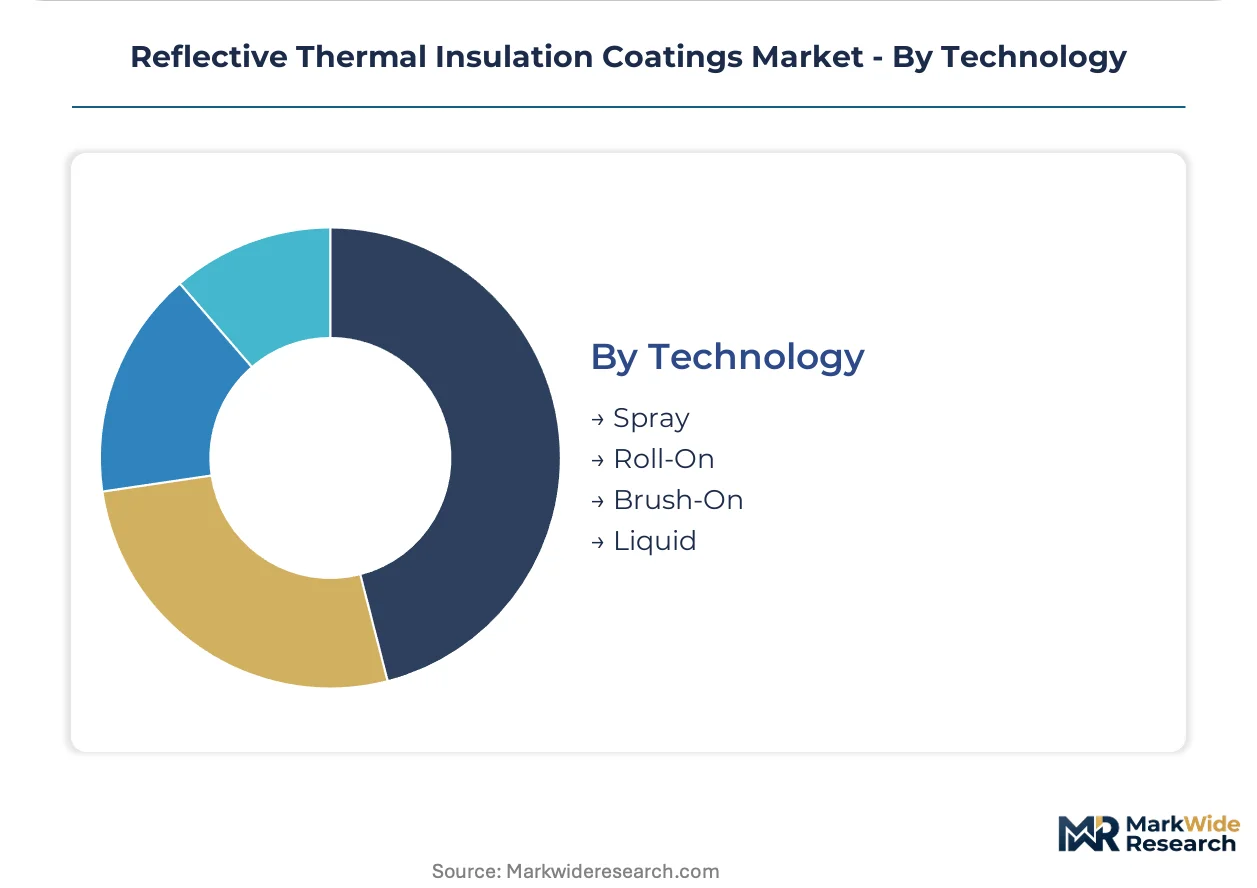
Technology:
Application equipment and substrate accessibility dictate method selection more than coating chemistry.
- Spray:Airless and plural-component spray rigs achieve mil-thickness control for high-build polyurethane systems on industrial roofing.
- Roll-On:Conventional roller application persists in residential and light commercial segments where labor cost minimization outweighs speed.
- Brush-On:Detail work around penetrations and flashings requires brush application for complete film formation.
- Liquid:Low-viscosity penetrating primers prepare oxidized asphalt surfaces for subsequent reflective topcoats.
Drone-assisted spray technology is gaining share fastest in steep-slope metal roofing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Mexico's Bajío region and special economic corridors in India's Gujarat state are concentrating coating procurement for automotive and aerospace export facilities.
United States
Cooling-degree-day intensity across Texas, Arizona, and Florida drives specification of high-emittance roof systems. The US Department of Energy's escalating cool roof mandates compress qualification timelines for ASTM E1980-compliant formulations. Dallas-Fort Worth industrial real estate investment trusts now mandate pre-approved coating manufacturer lists across property portfolios.
China
Dual carbon goals and provincial building efficiency standards accelerate adoption in Yangtze River Delta manufacturing zones. The Ministry of Ecology and Environment enforces volatile organic compound restrictions that filter solvent-based systems from urban construction projects. Shenzhen and Shanghai data center operators specify ceramic microsphere-loaded coatings to offset server cooling loads.
Germany
Industrial facility energy intensity targets and EU Green Deal compliance drive retrofit demand in Baden-Württemberg automotive plants. REACH regulations govern titanium dioxide pigment formulations used in water-based acrylic systems. Stuttgart-area logistics warehouses specify polyurethane coatings for chemical resistance against forklift battery washdown protocols.
India
Bureau of Indian Standards certification requirements and cooling load reduction mandates expand specification in Gujarat and Maharashtra industrial corridors. The Bureau of Energy Efficiency's building code amendments establish minimum reflectance thresholds for commercial construction. Ahmedabad automotive suppliers and Pune logistics facilities drive procurement of high-build solvent systems.
Japan
METI energy conservation standards and thermal performance targets reshape specification in Osaka-Kobe manufacturing belts. JIS testing protocols provide measurement architecture for product qualification claims. Nagoya-area automotive paint shops apply reflective primers to reduce interior cabin temperatures and air conditioning load.
Reflective Thermal Insulation Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation ownership concentrated among diversified chemical conglomerates and regional coating specialists. The vendor base organizes around three strategic archetypes: marine coatings heritage players transferring weathering expertise, architectural coil coating specialists anchoring North American supply, and Asian industrial project competitors with localized solvent-based production. Dominant competitive moves include capacity expansion in Mexican industrial corridors and technology licensing partnerships for ceramic microsphere integration.
Within the diversified chemical conglomerate tier, Akzo Nobel NV and BASF SE exemplify formulation ownership strategies that span marine, industrial, and architectural applications. Among North American coating specialists, PPG Industries occupies a position tied to dedicated architectural coil coating infrastructure. Asian industrial competitors include Kansai Paint Co. Ltd., which represents localized production approaches for solvent-based high-build systems.
| Leading Market Players |
|---|
| Akzo Nobel NV |
| Asian Paints Ltd |
| Axalta Coating Systems Ltd |
| BASF SE |
| PPG Industries |
| Jotun AS |
| The Sherwin-Williams Company |
| Kansai Paint Co. Ltd. |
| Mascoat |
| Others |
Pricing and Supply Chain Analysis
Ceramic microsphere loading technology maturation simultaneously compresses per-application labor costs and concentrates formulation ownership among binders with captive microsphere supply. This dual shift reweights pricing power toward manufacturers integrating hollow borosilicate sourcing while forcing spot-market pigment buyers into defensive margin positions.
Pricing Analysis
Short lead-time premiums dominate coating procurement, with ASTM E1980 certification backlog extending qualification timelines and forcing buyers to pay 15-25% markups for pre-qualified inventory. Three-tier pricing structure across premium, standard, and economy levels separates single-coat polyurethane systems with extended guarantees from water-based acrylics and unbranded commodity formulations. Price differentiation hinges on ceramic microsphere concentration and SRI certification tier. Cost compression in water-based acrylics is intensifying because titanium dioxide pigment volatility forces reformulation cycles. Industrial real estate investment trusts show lowest price sensitivity due to portfolio-scale procurement authority, while residential contractors remain most exposed to spot material costs.
Supply Chain Analysis
Titanium dioxide feedstock rests on chloride-process producers in the United States, China, and Australia, with rutile ore concentration creating single-source vulnerability for water-based acrylic manufacturers. Hollow borosilicate microspheres draw from specialty glass manufacturers in Germany and Japan, while aliphatic polyurethane isocyanates anchor in Belgium and the United States. Tariff exposure on Chinese TiO2 pigment imports threatens margin stability for mid-tier formulators. Distribution runs through national account direct specifications and regional roofing contractor networks, with industrial REITs bypassing traditional distributor tiers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reflective thermal insulation coatings represent a consolidation play as ASTM certification backlogs and raw material volatility force sub-scale formulators toward exit. Titanium dioxide cost compression and skilled applicator scarcity compound pressure on undifferentiated competitors.
For Market Incumbents: To counter ceramic microsphere supply concentration, secure backward integration into hollow borosilicate sourcing or long-term offtake agreements with German and Japanese specialty glass producers. Expand in-house applicator training academies to address 22% annual contractor turnover and lock channel loyalty. Prioritize ASTM E1980 pre-certification inventory builds to capture short lead-time premiums during qualification bottlenecks.
For New Entrants and Emerging Players: Enter via drone-assisted application services for steep-slope metal roofing in wind farm and telecommunications tower segments, where incumbent coverage remains thin. Target Mexico's Bajío industrial corridor automotive and aerospace facilities, where cooling-degree-day intensity exceeds adoption rates. Lead with utility rebate program enrollment as the go-to-market anchor, securing Arizona Public Service and Southern California Edison qualification before product launch.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified chemical conglomerates seeking marine-to-industrial coatings technology transfer. Long-term viability favors formulators with captive ceramic microsphere supply and national account service infrastructure. Watch utility rebate program recalibrations and state-level stretch code adoptions as inflection signals for retrofit versus new-build demand mix shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Microspheres | Captive hollow borosilicate supply insulates margins from specialty glass producer concentration. |
| ASTM E1980 Pre-Certification Inventory Build | Pre-qualified stock captures short lead-time premiums during 16-week testing backlogs. |
| In-House Applicator Training Academy Expansion | Direct contractor development addresses 22% annual turnover and locks channel preference. |
| Utility Rebate Program Pre-Qualification | Arizona Public Service and SCE enrollment secures specification access for incentivized projects. |
| Mexico Industrial Corridor Capacity Addition | Guanajuato and Baja California proximity reduces logistics costs for automotive OEM supply. |
Research Methodology
Trade association filings, customs import records, and EPA Energy Star certification databases formed the secondary backbone, cross-referenced against primary interviews with industrial facility managers, roofing contractor operations heads, coating formulator R&D directors, and utility demand-side management officers. Bottom-up volume estimates from substrate application rates and top-down value triangulation from manufacturer revenue disclosures were reconciled across the analysis window.
Historical trendline analysis of coating specification cycles, raw material cost indices, and regulatory adoption curves informed the projection framework. Segmentation dimensions modeled include chemistry type, substrate category, application method, end-use sector, and regional cooling-degree-day intensity. CAGRs were derived from elasticity-adjusted demand curves and replacement cycle compression factors, with ceramic microsphere technology maturation and Title 24 code expansion serving as primary demand accelerators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under titanium dioxide supply disruption or abrupt utility rebate recalibrations. Forecasts reflect documented assumptions regarding regulatory adoption timelines and substrate compatibility resolution. A small set of named triggers—ASTM laboratory capacity expansion, Mexican industrial energy code amendments, and drone application regulatory clearance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Thin Insulation Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market