
 Organic Pigment Dispersions Market | 2026-2036
Organic Pigment Dispersions Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Pigment Dispersions Market Intelligence
Waterborne acrylic resins is restructuring cost structures across coating and ink value chains as formulators phase out solvent-carrier systems. BASF SE leverages integrated pigment-dispersant manufacturing to capture margin from captive acrylic polymer supply. DIC Corporation anchors its position through phthalocyanine pigment specialization serving Asian printing ink producers. Sudarshan Chemical Industries competes on azo pigment scale, with Indian domestic capacity supporting regional export flows.
Organic pigment dispersions comprise finely milled organic colorants stabilized in liquid carrier media, typically achieving particle sizes below 500 nanometers through bead milling or high-shear homogenization processes to ensure optical clarity and tinctorial strength in end applications. Phthalocyanine pigments dominate volume in architectural and industrial coatings where blue-green shade stability commands premium positioning. Azo pigments sustain broad adoption across packaging printing inks where cost-performance balance drives procurement decisions. Polyurethane dispersants represent the fastest-growing stabilizer category as waterborne high-performance coatings demand superior pigment wetting and flocculation resistance.
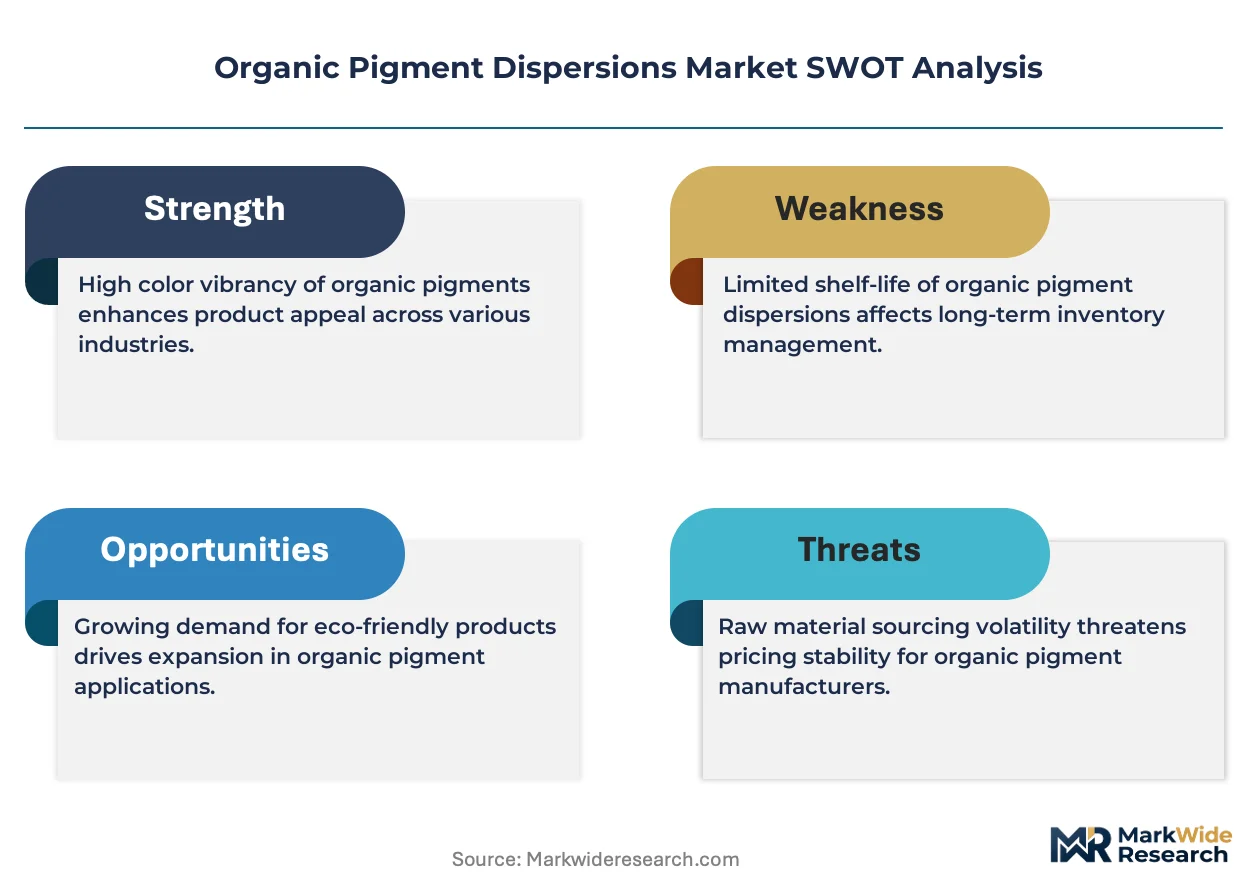
EPA VOC regulations and REACH Annex XVII restrictions constrain solvent-based dispersion formulations, redirecting R&D investment toward compliant waterborne and zero-VOC systems. ECHA substance evaluation under REACH and evolving GB standards in China further fragment compliance requirements across supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration strategies with regional enforcement timelines.
Market Dynamics
Waterborne coating systems are compressing solvent-based dispersion demand as automotive OEMs and architectural formulators face tightening VOC limits across manufacturing geographies. This substrate shift is restructuring raw material procurement, dispersant chemistry R&D priorities, and pigment wetting performance specifications simultaneously.
Growth Catalysts
- REACH Annex XVII VOC limits:European architectural coatings mandate zero-VOC formulations, forcing solvent-to-waterborne conversion across German and Italian production lines.
- Automotive OEM color complexity:Multi-coat effect finishes in premium vehicle segments require high-performance phthalocyanine dispersions with superior flocculation resistance.
- India coating cluster expansion:Maharashtra and Gujarat industrial zones attract integrated dispersion capacity to serve domestic architectural and automotive demand.
Market Restraints
- Crude-derived acrylic monomer volatility:Propylene and acrylic acid price swings compress margin stability for waterborne dispersion producers.
- Phthalocyanine blue concentration:Three Asian suppliers control majority of crude copper phthalocyanine supply, creating pigment availability risk.
- Waterborne drying speed limitations:Slower film formation versus solvent systems constrains high-speed coil coating line adoption.
Strategic Opportunities
- India domestic capacity gap:Import-dependent azo pigment dispersion supply creates localization opportunity for integrated Indian producers.
- UV-curable ink convergence:Hybrid waterborne-UV systems in packaging printing enable energy-cure speed with aqueous dispersion safety profiles.
- China dual carbon policy:MEE enforcement of carbon intensity targets accelerates waterborne conversion subsidies in Jiangsu and Zhejiang coating hubs.
Industry Challenges
- Formulation chemist scarcity:Waterborne pigment stabilization expertise lags solvent-era workforce retirement curves.
- Multi-jurisdiction registration timelines:Divergent ECHA substance evaluation and EPA PMN review cycles delay new dispersant commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Pigment Dispersions Market |
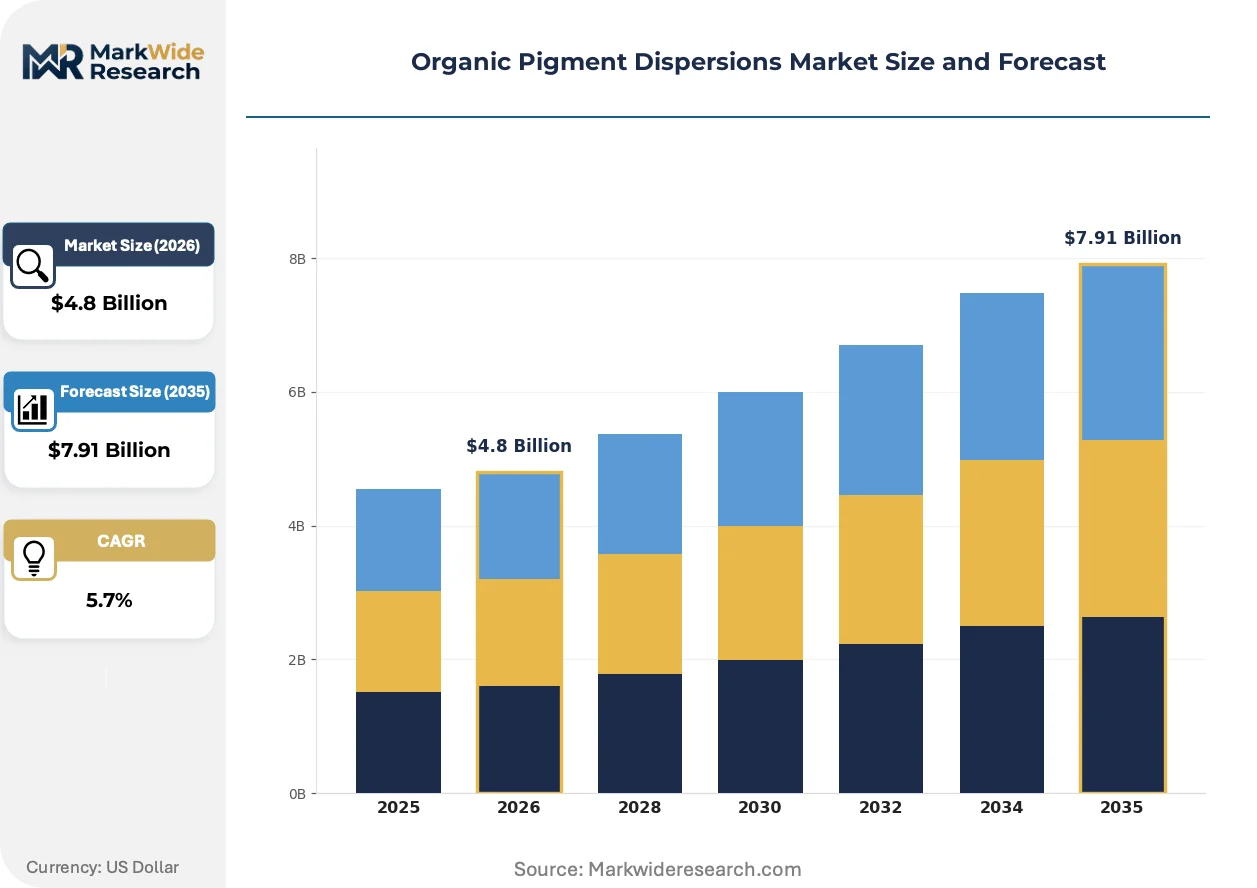
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azo Pigments, Phthalocyanine Pigments, Quinacridone Pigments, Dyes & Colorants Application: Printing Inks, Paints & Coatings, Plastics, Textiles End User Industry: Packaging Manufacturers, Plastic Fabricators, Paint Producers, Textile Processors Dispersing Agent Type: Polyurethane Dispersants, Acrylic Dispersants, Nonionic Surfactants, Anionic Surfactants |
| Companies Covered | BASF SE, DIC Corporation, Sudarshan Chemical Industries, Chromaflo Technologies, Cabot Corporation, Heubach GmbH, Penn Color, Pidilite Industries, Lanxess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Pigment Dispersions Market Strategic Shifts & Innovations
Hybrid stabilizer chemistries and digital color matching platforms are compressing traditional formulation cycles while regulatory pressure accelerates aqueous system development across industrial coating segments.
Polyurethane-polyacrylate hybrid dispersants is unifying pigment wetting performance with film-forming resin compatibility in automotive basecoat applications. Tier-one automotive coaters in Germany and Japan are qualifying these systems for metallic effect finishes. The technology is unifying previously separate dispersant and binder functions, reducing formulation complexity and raw material SKU counts.
EPA VOC regulations under 40 CFR 59 are forcing architectural coating reformulation across US Midwest and Southeast manufacturing regions. Compliance deadlines for consumer-facing products compress R&D timelines for dispersion suppliers serving Sherwin-Williams and PPG distribution networks. South Carolina and Ohio production facilities face the most concentrated compliance investment requirements.
Direct mill-base procurement by large coating formulators is consolidating traditional distributor channels. Regional dispersion blenders in Italy and Spain lose volume to captive supply agreements between multinational coaters and integrated pigment houses. This pattern concentrates most visibly in European architectural coatings where AkzoNobel and BASF negotiate direct supply frameworks.
Organic Pigment Dispersions Market Segmentation
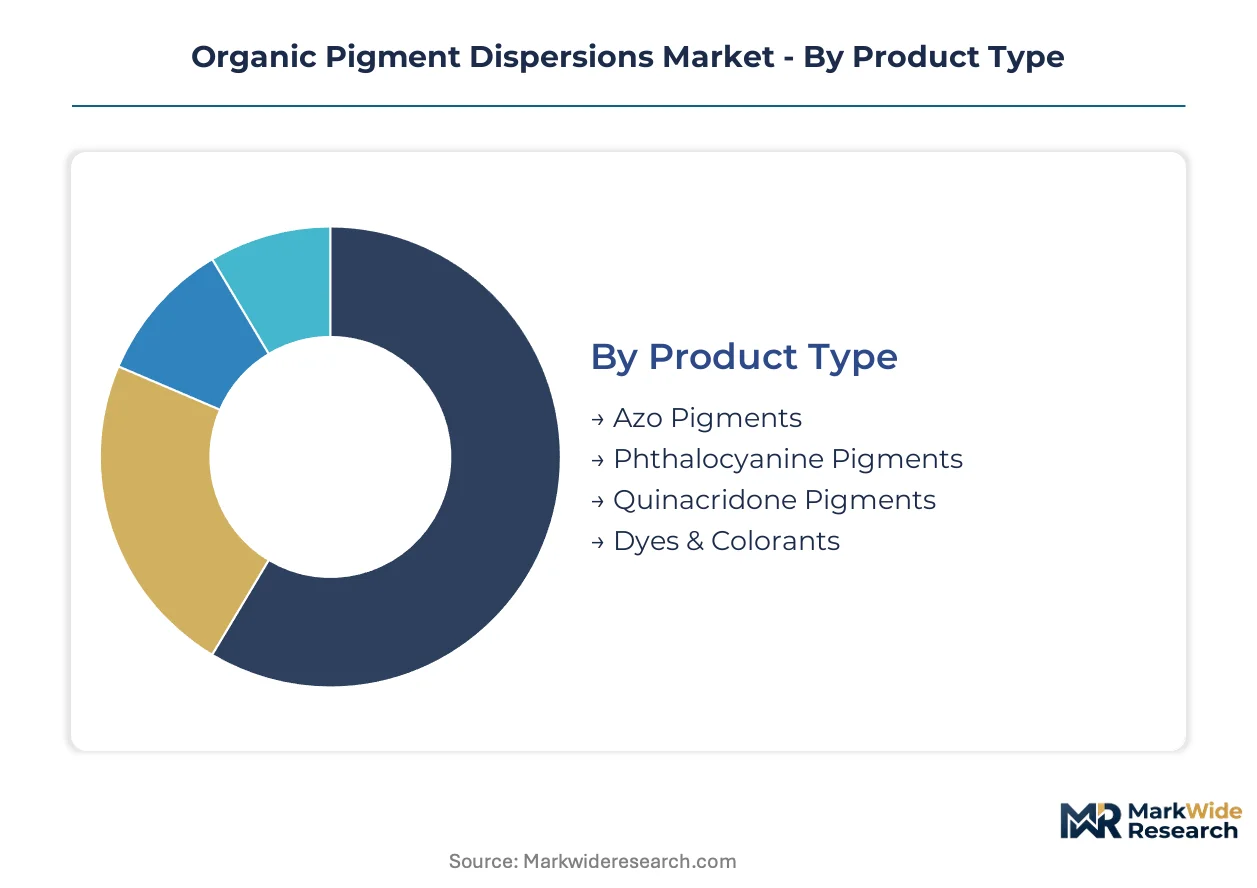
Segmentation in organic pigment dispersions reveals how formulation chemistry, end-use performance requirements, and regulatory compliance intersect across distinct value chain positions. Each dimension exposes different margin structures and competitive dynamics that suppliers must navigate.
Product Type:
Integration depth varies sharply across pigment chemistries, with some serving as standalone colorants and others requiring complex stabilization systems for embedded applications.
- Phthalocyanine Pigments:Copper-centered macrocyclic structures deliver exceptional lightfastness and thermal stability in blue-green shade ranges. Demand concentrates in automotive OEM basecoats across Germany and Japan where multi-coat effect finishes require superior flocculation resistance.
- Azo Pigments:Nitrogen-based chromophores achieve cost-performance balance through diazo coupling chemistry in yellow-orange-red spectra. Packaging printing inks in India and China drive procurement volumes where unit economics dominate purchasing decisions.
- Quinacridone Pigments:Polycyclic structures provide high-value violet-red shades for specialty coatings.
- Dyes & Colorants:Molecularly dispersed colorants penetrate textile fiber substrates through exhaustion processes.
Volume placements concentrate in azo pigments; the faster expansion belongs to phthalocyanine systems serving premium automotive segments.
Application:
Cost tier stratification separates commodity-scale applications from precision-formulated segments where technical service commands pricing power.
- Paints & Coatings:Waterborne architectural and industrial formulations require sub-500 nanometer particle sizes for optical clarity. REACH Annex XVII VOC limits in Germany and EPA 40 CFR 59 compliance deadlines across Ohio and South Carolina force solvent-to-waterborne conversion investments.
- Printing Inks:Flexographic and gravure systems demand rapid pigment wetting with minimal foam generation. Asian packaging hubs in Maharashtra and Gujarat absorb dispersion capacity as domestic label and flexible packaging production scales.
- Plastics:Masterbatch concentrates require heat stability above 280°C for injection molding compatibility.
- Textiles:Exhaust and padding applications need affinity-matched dispersants for synthetic fiber substrates.
Revenue concentration sits with paints and coatings; packaging ink applications are climbing fastest on e-commerce logistics expansion.
End User Industry:
Customer type fragmentation creates divergent procurement patterns between multinational formulators and regional processors.
- Paint Producers:Integrated dispersion procurement by AkzoNobel, BASF, and PPG compresses distributor channels. Direct mill-base agreements consolidate supply relationships in European architectural coatings where formulation consistency outweighs spot purchasing flexibility.
- Packaging Manufacturers:Flexible packaging converters in Jiangsu and Zhejiang provinces drive waterborne dispersion demand as China's MEE enforces carbon intensity targets.
- Plastic Fabricators:Masterbatch compounders specify heat-stable concentrates for automotive interior components.
- Textile Processors:Dye houses in Gujarat industrial zones prioritize azo pigment cost efficiency for export garment production.
Procurement scale concentrates among paint producers; packaging manufacturers are expanding most quickly on sustainability-driven substrate shifts.
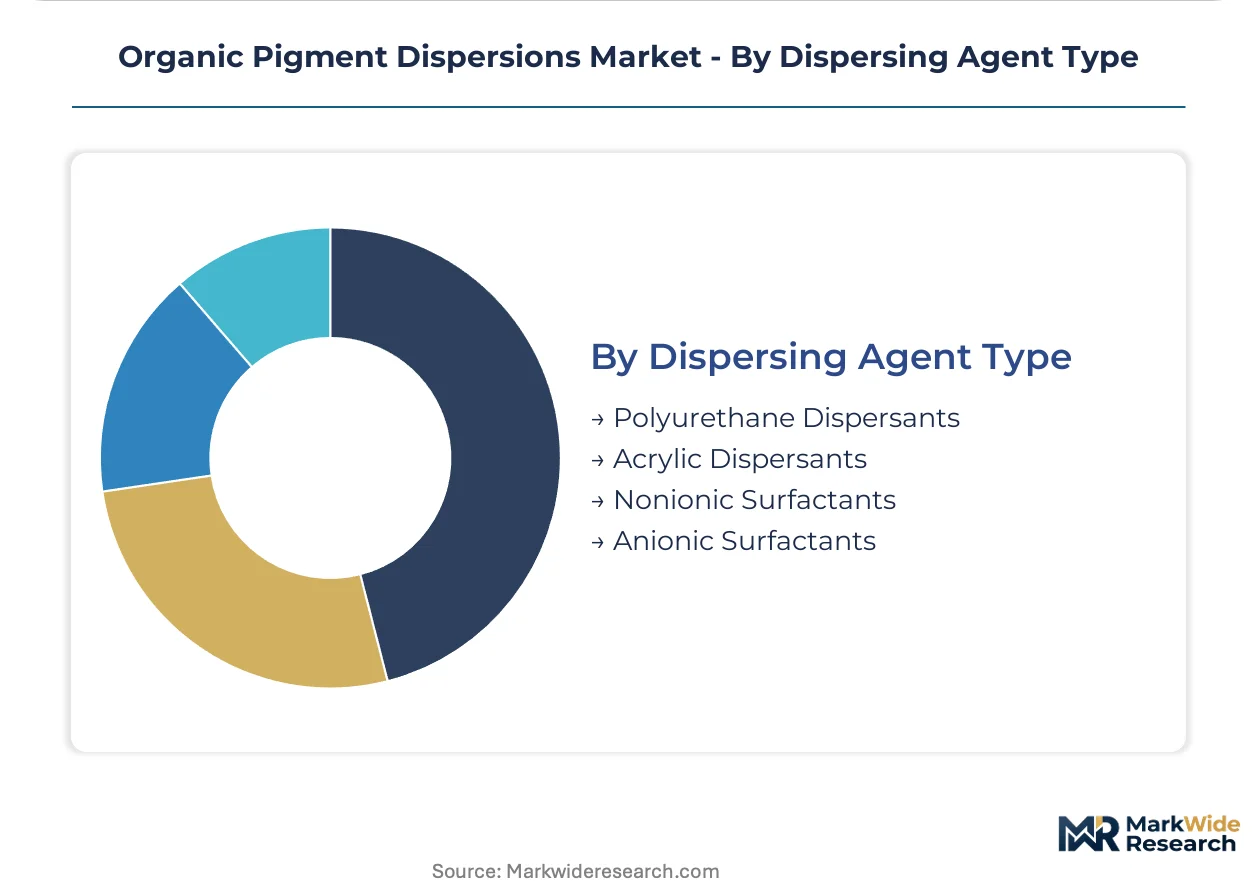
Dispersing Agent Type:
Supply concentration in acrylic monomer chains and polyurethane prepolymer feedstocks shapes competitive positioning across stabilizer categories.
- Polyurethane Dispersants:Block copolymer architectures deliver superior pigment wetting and flocculation resistance in high-performance waterborne coatings. Automotive basecoat qualifications in Germany and Japan accelerate adoption as hybrid polyurethane-polyacrylate chemistries unify dispersant and binder functions.
- Acrylic Dispersants:Carboxyl-functional polymers anchor cost-effective stabilization in architectural coatings. Crude-derived propylene and acrylic acid price volatility compress margin stability for producers serving Midwest and Southeast US manufacturing regions.
- Nonionic Surfactants:Ethoxylated structures provide steric stabilization for pH-sensitive formulations.
- Anionic Surfactants:Sulfonate and carboxylate chemistries dominate legacy solvent-based systems facing regulatory phase-out.
Installed base concentrates in acrylic dispersants; polyurethane systems are gaining share fastest on automotive waterborne conversion timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for organic pigment dispersions concentrates in Germany, China, and India as regional coating production clusters expand technical specifications for high-performance colorants. Waterborne formulation mandates are redirecting investment flows across these manufacturing geographies.
Germany
Automotive OEM basecoat demand and architectural coating exports drive phthalocyanine dispersion procurement. REACH Annex XVII VOC limits force zero-VOC formulation conversion across German production lines. The North Rhine-Westphalia industrial corridor hosts integrated dispersion capacity serving AkzoNobel and BASF direct supply agreements.
China
Packaging printing ink scale and automotive coating localization absorb azo and phthalocyanine dispersion output. MEE enforcement of carbon intensity targets accelerates waterborne conversion subsidies in Jiangsu and Zhejiang coating hubs. The Yangtze River Delta concentration of flexible packaging converters drives waterborne dispersion demand as sustainability mandates tighten.
India
Domestic architectural coating expansion and automotive finishing line growth create import substitution opportunities for azo pigment dispersions. Maharashtra and Gujarat industrial zones attract integrated dispersion capacity to serve domestic demand. The Gujarat cluster prioritizes cost-efficient azo pigment supply for export garment production dye houses.
United States
Architectural coating reformulation and automotive refinish demand sustain polyurethane dispersant growth. EPA 40 CFR 59 compliance deadlines compress R&D timelines for dispersion suppliers serving Midwest and Southeast manufacturing regions. South Carolina and Ohio production facilities face concentrated compliance investment requirements for waterborne system qualification.
Japan
Automotive effect finish complexity and precision inkjet applications command premium phthalocyanine dispersion specifications. METI industrial standards guide waterborne coating adoption timelines across domestic automotive supply chains. The Kansai industrial belt maintains specialized dispersion blending for metallic effect basecoat qualifications.
Organic Pigment Dispersions Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated pigment houses capturing direct mill-base agreements while regional blenders serve spot purchasing demand. Market structure tilts toward consolidation in phthalocyanine pigments where crude copper phthalocyanine supply concentrates, while azo pigment dispersion remains more fragmented. Three archetypes dominate: integrated chemical conglomerates with captive acrylic polymer supply, specialized pigment houses with diazo coupling expertise, and regional dispersion blenders with formulation service capabilities. Competitive moves center on backward integration into dispersant chemistry and geographic expansion into India coating clusters.
Among integrated chemical conglomerates, BASF SE anchors the premium tier through Ludwigshafen-based pigment-dispersant manufacturing. DIC Corporation occupies a position exemplifying phthalocyanine specialization serving Asian printing ink value chains. Sudarshan Chemical Industries represents the scale-driven archetype with Indian domestic azo pigment capacity supporting regional export flows. These three entities collectively illustrate how geographic origin and integration depth determine competitive positioning across waterborne formulation transitions.
| Leading Market Players |
|---|
| BASF SE |
| DIC Corporation |
| Sudarshan Chemical Industries |
| Chromaflo Technologies |
| Cabot Corporation |
| Heubach GmbH |
| Penn Color |
| Pidilite Industries |
| Lanxess |
| Others |
Cost & Logistics Intelligence
Tier-one automotive coaters and multinational architectural formulators command contract-based long-term offtake agreements that compress spot-market liquidity. REACH Annex XVII compliance costs and EPA 40 CFR 59 reformulation investments create pricing stratification across premium, standard, and economy tiers.
Pricing Analysis
Volume placements concentrate in commodity azo pigment dispersions where margin compression runs through packaging ink procurement in India and China. Price differentiation hinges on REACH certification tier and captive acrylic polymer supply. Pricing pressure stems from crude-derived acrylic monomer volatility compressing waterborne dispersion margins. Regional blenders in Italy and Spain exhibit highest price sensitivity; German automotive OEMs accept premium positioning for phthalocyanine flocculation resistance.
Supply Chain Analysis
India's PLI scheme for chemical manufacturing and China's MEE carbon intensity enforcement are redirecting sourcing decisions toward domestic-content-qualified suppliers. Crude copper phthalocyanine concentrates in China, India, and Japan; acrylic acid and propylene feedstock dependencies tether margin stability to petrochemical volatility. Single-source vulnerability in phthalocyanine blue crude supply creates pigment availability risk. Distribution runs through direct mill-base agreements between integrated pigment houses and multinational coaters, bypassing traditional regional blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where REACH Annex XVII and EPA 40 CFR 59 create regulatory moats favoring integrated players with captive dispersant chemistry and pre-qualified registration dossiers.
For Market Incumbents: Deepen backward integration into polyurethane dispersant prepolymer feedstocks to defend margin position against acrylic monomer volatility. Expand waterborne qualification capacity in Maharashtra and Gujarat to capture India domestic substitution demand. Prioritize ECHA substance evaluation pre-submission for next-generation hybrid stabilizer chemistries. For New Entrants and Emerging Players: Digital color matching platforms offer a technology-first wedge into mid-tier architectural coating formulators underserved by integrated houses. Target India's import-dependent azo pigment dispersion gap through Gujarat-based production with BIS certification pathway. Pursue toll-manufacturing partnerships with established dispersant houses to bypass multi-jurisdiction registration timelines. For Investors and Strategic Acquirers: The window for entry favors regional dispersion blenders with formulation service capabilities and existing EPA PMN clearances. Long-term viability centers on waterborne conversion exposure across automotive and architectural end-uses. Monitor ECHA substance evaluation enforcement intensity as inflection signal for compliant asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dispersant Chemistry | Captive polyurethane prepolymer supply insulates BASF and DIC from acrylic monomer volatility. |
| Capacity Expansion in India Coating Clusters | Maharashtra and Gujarat facilities serve domestic architectural demand while reducing import dependence. |
| Hybrid Stabilizer R&D Investment | Polyurethane-polyacrylate chemistries unify dispersant and binder functions for automotive basecoat qualifications. |
| Direct Mill-Base Supply Agreements | AkzoNobel and PPG procurement consolidation eliminates distributor margins for regional blenders. |
| Regulatory Pre-Registration Dossier Investment | ECHA and EPA clearance acceleration compresses new entrant commercialization timelines. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coating formulators, pigment procurement leads, dispersant R&D directors, and regulatory affairs managers at REACH-compliant houses were cross-validated against Cefic sector reports, EPA enforcement disclosures, and ECHA substance evaluation databases. Bottom-up capacity estimates and top-down demand projections were reconciled through iterative triangulation.
Data-stream reconciliation across pigment chemistry splits, dispersant type classifications, and end-use industry demand curves shaped the analytical framework. Segmentation dimensions included product type, application, dispersing agent chemistry, and regional production hub clustering. CAGRs were derived from slope-intercept modeling of historical volume trajectories and regulatory conversion timeline assumptions. Automotive OEM color complexity indices and architectural coating waterborne penetration rates served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including speculative raw material price shocks beyond historical volatility bands and unilateral regulatory timeline accelerations. Forecasts reflect documented assumptions regarding REACH enforcement consistency and MEE subsidy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Phthalocyanine Blue Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Acid Orange Market