
 Italy Industrial Insulation Market | 2026-2036
Italy Industrial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Industrial Insulation Market Insights
Power generation is hardening as the dominant end-use vertical for Italian industrial insulation, displacing legacy oil and gas procurement patterns. Owens Corning leverages its fiberglass specialization to serve combined-cycle plant retrofits across the Po Valley. Knauf Insulation anchors the mineral wool segment through dense distribution coverage of Northern Italy's manufacturing belt. Saint-Gobain competes with integrated technical insulation systems targeting chemical processing facilities near Porto Marghera.
Industrial insulation comprises engineered materials designed to reduce thermal transfer in process equipment, piping, and mechanical systems operating between minus 50 degrees Celsius and 850 degrees Celsius, typically manufactured from mineral fibers, cellular polymers, or microporous silica composites. The primary purpose centers on process temperature stability, personnel protection, and energy efficiency in continuous industrial operations. Mineral wool leads installed volume across aging Italian refinery infrastructure, while polyurethane foam captures margin pools in cryogenic LNG applications at Adriatic terminals. Fiberglass dominates the power generation renewal cycle given its balance of thermal resistance and mechanical durability in high-vibration turbine environments.
CE marking under the EU Construction Products Regulation and Italy's transposed energy efficiency directives shape material certification pathways and installation compliance costs. The National Institute of Metrological Research enforces thermal conductivity testing protocols that filter substandard imports from non-EU suppliers. Stakeholders must monitor the EU ETS carbon price trajectory and its accelerating effect on industrial energy audits and insulation upgrade cycles.
Market Dynamics
EU Green Deal energy conservation mandates are tightening thermal performance requirements across Italian manufacturing, forcing insulation upgrade cycles in aging refinery infrastructure and power generation assets. This regulatory compression is redrawing competitive positioning between mineral wool, fiberglass, and advanced microporous systems.
Growth Catalysts
- EU ETS carbon pricing:Rising carbon costs accelerate industrial energy audits and insulation retrofit investments in Lombardy's power generation cluster.
- Combined-cycle plant renewals:Aging gas turbine infrastructure across the Po Valley drives demand for high-temperature fiberglass systems with vibration resistance.
- Adriatic LNG expansion:Cryogenic terminal development at Ravenna and Trieste anchors polyurethane foam procurement for sub-zero applications.
Market Restraints
- Mineral fiber input volatility:Basalt and slag supply concentration in Eastern Europe exposes Italian manufacturers to energy cost pass-through fluctuations.
- CE marking compliance friction:EU Construction Products Regulation testing protocols filter substandard imports, extending certification timelines for non-EU suppliers.
- Microporous silica cost premium:High-performance aerogel composites face substitution pressure from lower-cost cellular polymers in sub-400°C applications.
Strategic Opportunities
- Southern Italy industrial corridor:Underpenetrated chemical processing in Calabria and Sicily offers whitespace for technical insulation system deployment.
- EU F-Gas Regulation phase-down:Blowing agent restrictions on cellular foams create opening for water-blown polyurethane and mineral fiber alternatives.
- Digital thermal auditing convergence:Integration of infrared drone inspection with predictive maintenance platforms enables outcome-based insulation performance contracts.
Industry Challenges
- Certified installer scarcity:Complex CE marking installation protocols create bottlenecks for high-temperature industrial applications requiring specialized applicator credentials.
- Legacy asset integration:Retrofitting 1970s-era refinery infrastructure with modern multi-layer systems demands custom engineering and extended shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Industrial Insulation Market |
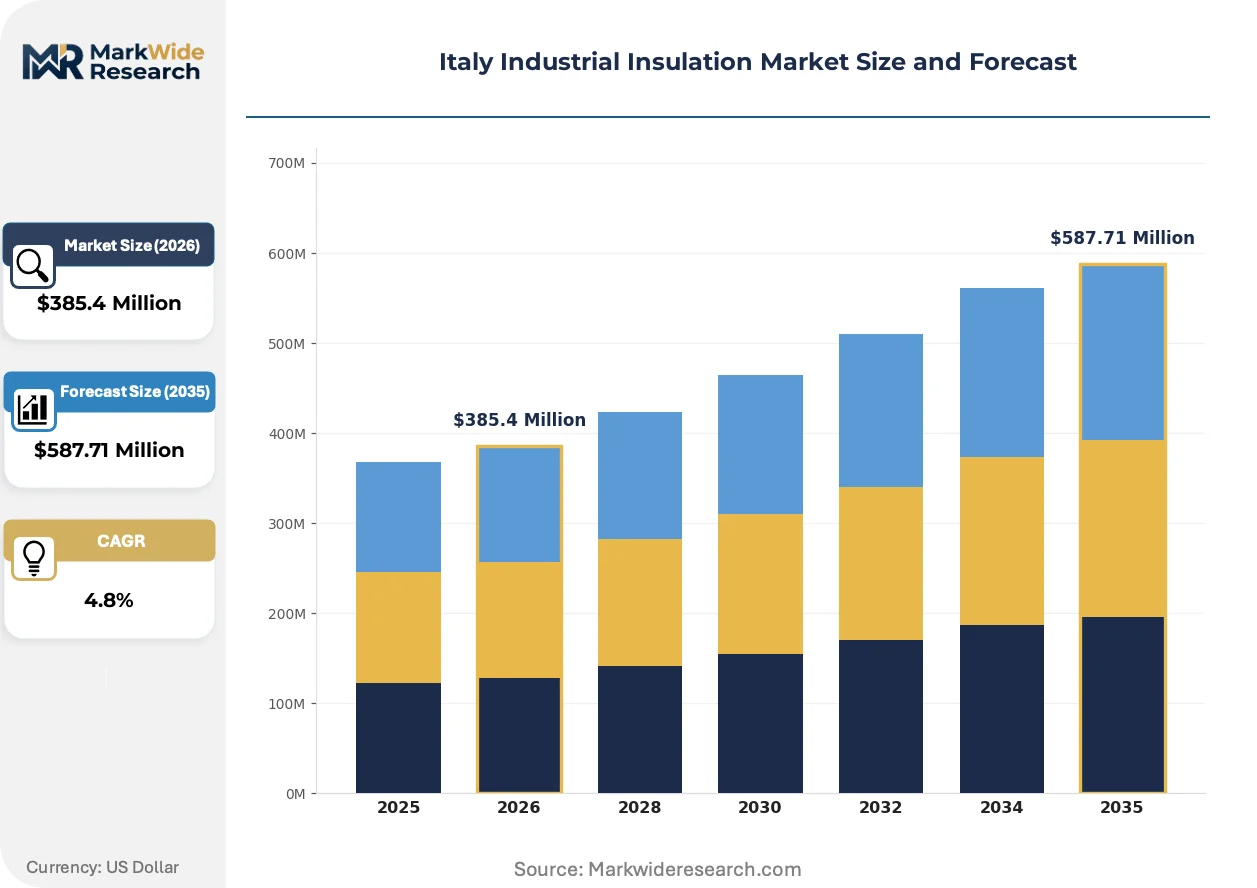
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Wool, Polyurethane Foam, Polystyrene, Fiberglass Application: Pipeline, Equipment, Mechanical Systems, Energy Conservation End User: Oil & Gas, Power Generation, Manufacturing, Chemical Installation Method: Spray, Board, Blanket, In-Situ |
| Companies Covered | Owens Corning, Knauf Insulation, Saint-Gobain, Rockwool International A/S, BASF SE, Armacell, Johns Manville, L’ISOLANTE K-FLEX, Duna-Corradini, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Industrial Insulation Market Trends and Innovations
Material science advances and regulatory tightening are converging to reshape specification patterns across Italian process industries. Three developments are actively reconfiguring competitive dynamics and buyer decision frameworks.
Microporous silica composites are rewriting performance benchmarks for ultra-high-temperature applications above 650°C. Petrochemical facilities near Porto Marghera are specifying these materials for reformer and cracker unit linings, compressing the addressable market for traditional ceramic fiber blankets and forcing mineral wool suppliers toward mid-temperature positioning.
EU Green Deal implementation through Italy's transposed energy efficiency directives is mandating thermal conductivity disclosures in public procurement. The National Institute of Metrological Research enforcement of standardized testing protocols is filtering specification lists, with chemical processing and power generation verticals now requiring third-party validated performance data before contract award.
Integrated service contracting is consolidating purchasing authority at the EPC and major operator level. Procurement departments at ENI and Edison are bundling insulation specification with installation and long-term thermal performance guarantees, marginalizing traditional distributor channels in Northern Italy's manufacturing belt and compressing margins for mid-tier material-only suppliers.
Italy Industrial Insulation Market Segmentation
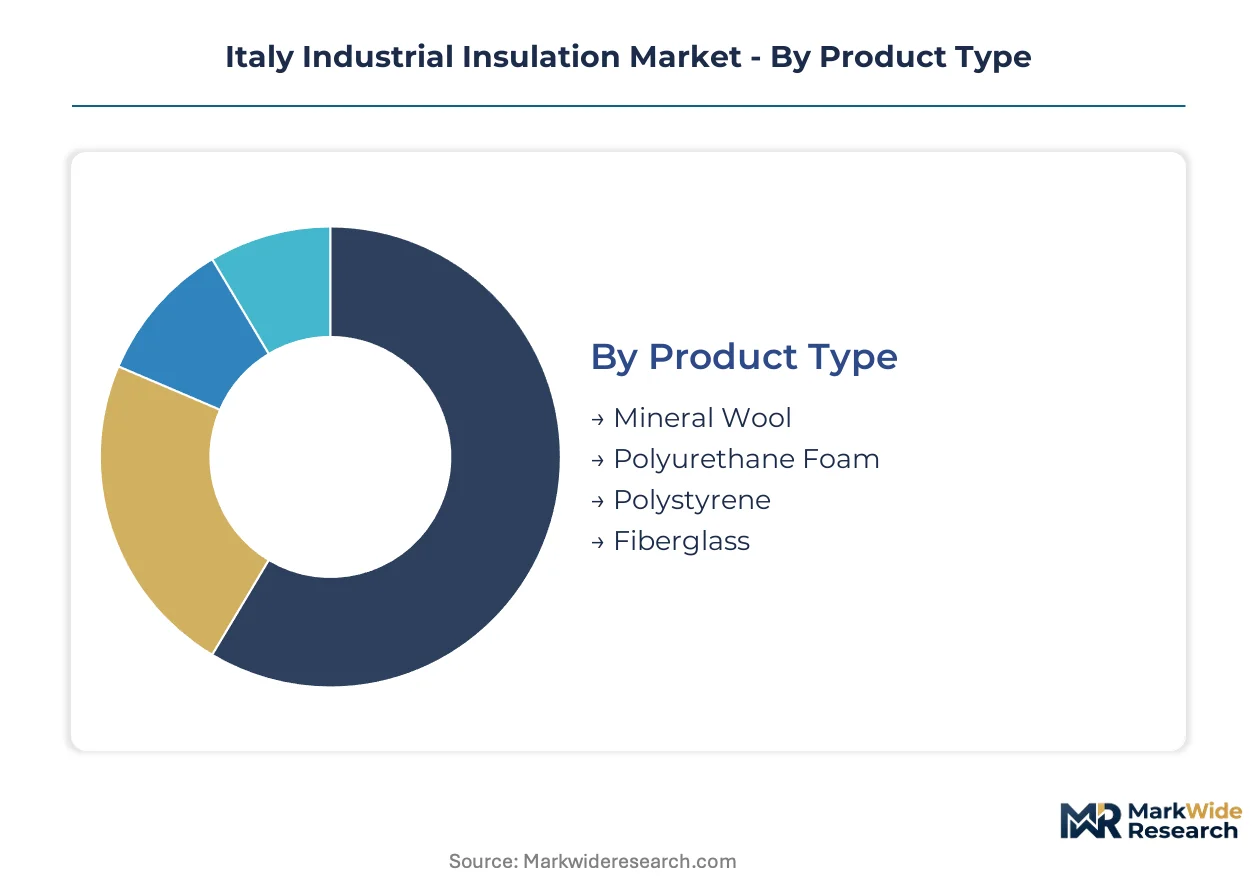
Material specification patterns in Italian industrial insulation diverge sharply by thermal performance envelope and CE marking pathway. Certification burden and end-use operating temperature dictate procurement decisions across refinery, power, and chemical verticals.
Product Type:
CE marking under the EU Construction Products Regulation sorts these materials by reaction-to-fire classification and thermal conductivity testing protocols enforced by the National Institute of Metrological Research.
- Mineral Wool:Engineered from basalt or slag fibers, this material delivers fire resistance up to 850°C with proven durability in aging Italian refinery infrastructure. Demand concentrates in Ravenna's petrochemical corridor where reformer unit linings require A1 non-combustible certification under CPR Annex V.
- Polyurethane Foam:Closed-cell cellular polymer systems excel in cryogenic applications down to minus 50°C. Procurement is accelerating at Adriatic LNG terminals near Ravenna and Trieste, though EU F-Gas Regulation phase-down restrictions on hydrofluorocarbon blowing agents are forcing formulation shifts toward water-blown alternatives.
- Polystyrene:Expanded and extruded variants serve sub-100°C mechanical insulation with cost advantages in HVAC and secondary process piping. ENI maintenance contracts specify this material for non-critical utility systems across Lombardy power generation assets.
- Fiberglass:Continuous filament glass wool dominates combined-cycle turbine environments across the Po Valley, balancing thermal resistance with vibration tolerance in high-speed rotating equipment.
Leading the category by volume: Mineral Wool. Expanding most quickly: Polyurethane Foam.
Application:
Installation geometry and accessibility constraints determine labor cost structures and material form factor selection across Italian industrial sites.
- Pipeline:Pre-formed sections and flexible blankets wrap process piping across Porto Marghera chemical complexes, with prefabrication reducing shutdown windows during retrofit campaigns.
- Equipment:Vessel and tank insulation demands custom-cut multi-layer systems. Edison's combined-cycle fleet specifies removable mattress designs for turbine casings in Lombardy, enabling faster maintenance access than permanent linings.
- Mechanical Systems:Pumps, compressors, and heat exchangers require precision-fit insulation with integrated weatherproofing. Calabria's underpenetrated chemical processing corridor shows whitespace for technical system deployment.
- Energy Conservation:Building envelope and steam distribution optimization projects qualify for Italian transposed energy efficiency directive incentives, driving audit-triggered upgrade cycles in 1970s-era manufacturing facilities.
Highest retrofit intensity: Equipment. Steepest expansion trajectory: Energy Conservation.
End User:
Procurement authority concentration varies dramatically, with integrated operators bundling specification and installation while fragmented manufacturing buyers purchase through distributor channels.
- Oil & Gas:Downstream refining and LNG terminal operators specify materials for hydrocarbon containment and cryogenic transfer systems. Ravenna's Adriatic import infrastructure anchors polyurethane foam procurement for sub-zero storage tanks.
- Power Generation:Combined-cycle and cogeneration assets across the Po Valley represent the dominant demand vertical, displacing legacy oil and gas procurement patterns with fiberglass-intensive turbine renewal programs.
- Manufacturing:Steel, cement, and food processing facilities require mid-temperature insulation for kilns, ovens, and refrigerated storage. Northern Italy's manufacturing belt sources through dense Knauf Insulation distribution coverage.
- Chemical:Petrochemical crackers and reformers near Porto Marghera specify microporous silica composites above 650°C, compressing addressable market for traditional ceramic fiber blankets.
Procurement volume leader: Power Generation. Gaining share fastest: Chemical.
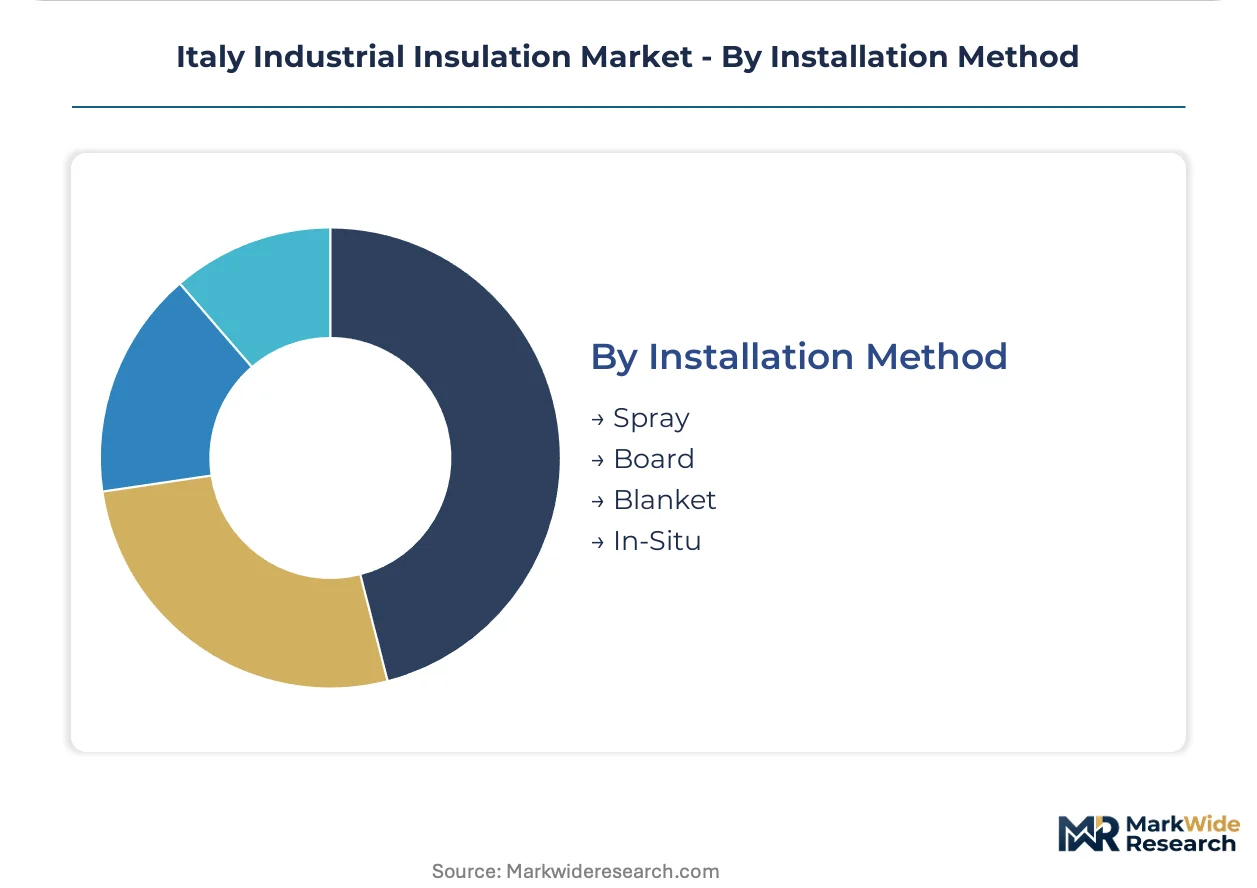
Installation Method:
Applicator certification scarcity under complex CE marking protocols creates bottlenecks for high-temperature industrial deployments, favoring methods with lower skilled-labor dependency.
- Spray:Polyurethane foam application achieves seamless coverage on irregular substrates. LNG terminal construction at Trieste employs certified spray crews for cryogenic tank insulation, though F-Gas Regulation compliance extends equipment calibration requirements.
- Board:Rigid polystyrene and mineral wool panels suit flat surfaces and vessel heads with standardized cutting patterns, reducing field fabrication time in Lombardy power plant retrofits.
- Blanket:Flexible mineral wool and ceramic fiber wraps conform to curved piping and equipment. 1970s-era refinery infrastructure demands custom-engineered blanket systems with extended shutdown windows for installation.
- In-Situ:Cast or foamed-in-place systems create monolithic insulation layers for complex geometries. Microporous silica composites deploy in-situ for ultra-high-temperature cracker unit linings at Porto Marghera.
Dominant by installed volume: Blanket. Climbing the fastest: Spray.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Zona Economica Speciale (ZES) framework drives industrial insulation demand concentration across designated development corridors, with tax incentives clustering manufacturing investment in Adriatic port zones and Southern regeneration areas.
Lombardy
Combined-cycle power generation assets dominate procurement across the Po Valley, with Edison and ENI bundling turbine insulation contracts under long-term service agreements. The region's National Institute of Metrological Research testing protocols enforce thermal conductivity disclosures in public tenders. Milan's manufacturing belt anchors fiberglass-intensive renewal programs for aging gas infrastructure.
Emilia-Romagna
Ravenna's petrochemical corridor generates concentrated demand for mineral wool in reformer unit linings and polyurethane foam for LNG terminal cryogenics. EU Green Deal transposition through Italy's energy efficiency directives mandates insulation upgrades in 1970s-era refinery infrastructure. The Porto di Ravenna expansion anchors sub-zero storage tank procurement for Adriatic import infrastructure.
Veneto
Porto Marghera chemical processing facilities specify microporous silica composites above 650°C, compressing addressable markets for traditional ceramic fiber systems. CE marking under the EU Construction Products Regulation filters supplier qualification through reaction-to-fire classification requirements. The Venetian industrial cluster drives technical insulation system deployment for cracker and reformer unit retrofits.
Calabria
Underpenetrated chemical processing infrastructure offers whitespace for insulation system vendors targeting Southern Italy's industrial regeneration. ZES Calabria tax incentives attract petrochemical investment requiring mid-to-high temperature insulation specification. The Gioia Tauro port zone anchors prospective LNG terminal development with cryogenic foam procurement potential.
Sicily
Aging refinery infrastructure at Augusta-Priolo demands custom-engineered blanket systems with extended shutdown windows for installation. EU ETS carbon pricing accelerates energy audit cycles and insulation retrofit investments in legacy hydrocarbon processing assets. The island's industrial corridor represents untapped demand for technical insulation system deployment.
Italy Industrial Insulation Market Competitive Landscape
Top-tier vendors anchor specification authority at integrated operator level, while mid-tier material suppliers face margin compression from bundled service contracting. Owens Corning, Knauf Insulation, and Saint-Gobain concentrate procurement influence through dense distribution coverage and technical system integration. Strategic archetypes include: fiberglass specialists serving power generation vibration environments; mineral wool fabricators with slag supply backward integration; and microporous composite developers targeting ultra-high-temperature petrochemical applications. Competitive moves center on EPC partnership consolidation and predictive maintenance platform integration.
Among North American-originated multinationals, Owens Corning and Johns Manville occupy positions within the power generation specialization tier, leveraging filament glass expertise for turbine environment durability. European fabricators Knauf Insulation and Rockwool International A/S exemplify the mineral wool volume segment, with Saint-Gobain representing integrated technical system capability for chemical processing above 650°C. BASF SE and Armacell anchor cellular polymer positioning for cryogenic LNG terminal applications. Italian specialist L'ISOLANTE K-FLEX and regional compounder Duna-Corradini sit within the flexible insulation and custom formulation tiers respectively.
| Leading Market Players |
|---|
| Owens Corning |
| Knauf Insulation |
| Saint-Gobain |
| Rockwool International A/S |
| BASF SE |
| Armacell |
| Johns Manville |
| L'ISOLANTE K-FLEX |
| Duna-Corradini |
| Others |
Pricing and Supply Chain Analysis
Basalt and slag fiber price indices in Eastern Europe cascade through Italian mineral wool manufacturing, compressing margin pools at mid-tier fabricators while concentrating pricing power among backward-integrated suppliers. CE marking compliance costs under the EU Construction Products Regulation stratify procurement tiers, with certified-system premiums widening against spot-market cellular polymer alternatives.
Pricing Analysis
Short lead-time premiums of certified microporous silica systems command substantial markups over standard mineral wool blankets in Ravenna petrochemical retrofits. Project-based contracting dominates, with price differentiation anchored in EN 1096-1 reaction-to-fire certification tier and volume-scale procurement at ENI and Edison. Cost compression in standard-grade fiberglass intensifies as Owens Corning and Knauf Insulation expand Po Valley distribution density. Fragmented manufacturing buyers in Northern Italy's steel and cement sectors exhibit highest price sensitivity, while integrated chemical processors prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Certified installer scarcity across Lombardy and Emilia-Romagna constrains deployment velocity for high-temperature applications requiring specialized applicator credentials. Raw material supply concentrates in Germany, Poland, and the Czech Republic for mineral fiber feedstocks, with polyurethane foam precursors drawing from Belgian and Dutch chemical complexes. Logistics chokepoints at Adriatic port terminals expose cryogenic insulation projects to customs clearance delays. Distribution runs through EPC contractor channels and major operator direct procurement, marginalizing traditional distributor networks in bundled service contracting arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy Industrial Insulation Market operates as a cost-of-compliance arena where EU Green Deal transposition through Italy's energy efficiency directives erects certification barriers that filter substandard imports and protect entrenched suppliers with established CE marking pathways.
For Market Incumbents: Anticipate microporous silica substitution pressure above 650°C by accelerating R&D investment in hybrid composite formulations that bridge performance gaps at lower certification burden. Defend Lombardy power generation share through captive installation service bundling that locks out material-only competitors. Prioritize backward integration into slag supply from Eastern European steel production to insulate margin compression from energy cost pass-through volatility. For New Entrants and Emerging Players: Calabria's underpenetrated chemical processing corridor offers whitespace for technical insulation system deployment with lighter incumbent saturation. ZES Calabria tax incentives attract petrochemical investment requiring mid-temperature specification where certification timelines favor nimble challengers. Target outcome-based thermal performance contracting with infrared drone audit integration as differentiated go-to-market positioning against traditional material-supply models. For Investors and Strategic Acquirers: Distressed-cycle entries favor mineral wool fabricators with slag supply backward integration in Poland and Czechia as carbon border adjustment mechanisms reshape input cost structures. Long-term viability hinges on EU ETS price trajectory sustaining industrial energy audit frequency across the projection horizon. Monitor ENI and Edison procurement centralization signals as inflection indicators for distributor channel margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slag Supply | Captive basalt fiber feedstock from Polish steel production insulates margin compression from energy volatility. |
| CE Marking Certification Investment | EN 1096-1 reaction-to-fire classification opens specification pathways at Porto Marghera chemical facilities. |
| Installation Service Bundling | Direct EPC contractor relationships at Edison and ENI disintermediate distributor channels in Lombardy. |
| Digital Thermal Audit Platform | Infrared drone inspection integration enables predictive maintenance contracts at Ravenna LNG terminals. |
| Southern Italy Geographic Expansion | ZES Calabria tax incentives anchor petrochemical investment with cryogenic foam procurement potential. |
Research Methodology
Multi-period observation of EU ETS carbon price trajectories, ENI and Edison procurement contract awards, and National Institute of Metrological Research certification timelines anchored the trend analysis, supplemented by interviews with plant engineers at Lombardy combined-cycle facilities, procurement leads at Ravenna petrochemical complexes, EPC contractors specializing in industrial retrofits, and thermal audit service providers. Secondary validation drew from EU Construction Products Regulation filings, Italian transposed energy efficiency directive implementation documents, customs trade data for mineral fiber imports, and SEC disclosures from publicly traded insulation manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic energy intensity projections.
Segment-weighting across material type, application geometry, end-use vertical, and regional industrial cluster density structured the analytical framework. Modeled dimensions included thermal performance envelope, CE marking pathway complexity, and installation method labor intensity. CAGRs derived from elasticity-adjusted energy audit cycle frequencies and retrofit investment correlations with carbon pricing. Industry-specific inputs incorporated EU F-Gas Regulation phase-down timelines and ZES incentive program uptake rates across Southern Italy.
Revisions become necessary when EU ETS price trajectories deviate substantially from modeled pathways, when CE marking protocols extend certification timelines unpredictably, or when Adriatic LNG terminal construction schedules shift. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and industrial energy audit penetration rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Expanded Perlite Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Active Insulation Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
North America Phase Change Materials Market