
 Paraffin Market | 2026-2036
Paraffin Market Size, Share, and Industry Trends Forecast 2026-2036
Paraffin Market Intelligence
Aftermarket formulation services is reshaping how margin pools migrate across the paraffin value chain. ExxonMobil leverages its integrated refining footprint to sustain cost-advantaged feedstock access. Sasol anchors its position through Fischer-Tropsch wax technology leadership. CEPSA competes via specialized slack wax upgrading capabilities at its Spanish refineries.
Paraffin denotes a mixture of saturated aliphatic hydrocarbons with carbon chain lengths typically spanning C18 to C36, derived from petroleum refining slack wax through solvent dewaxing or hydrofinishing processes; it functions primarily as a phase-change material, moisture barrier, and mold-release agent across industrial and consumer applications. Fully refined paraffin commands the dominant share of pharmaceutical and food-grade specifications where odor and oil-content thresholds sit below 0.5 percent. Microcrystalline wax represents the fastest-expanding product category, driven by adhesive and rubber-processing formulations that demand higher melting points and finer crystal structures.
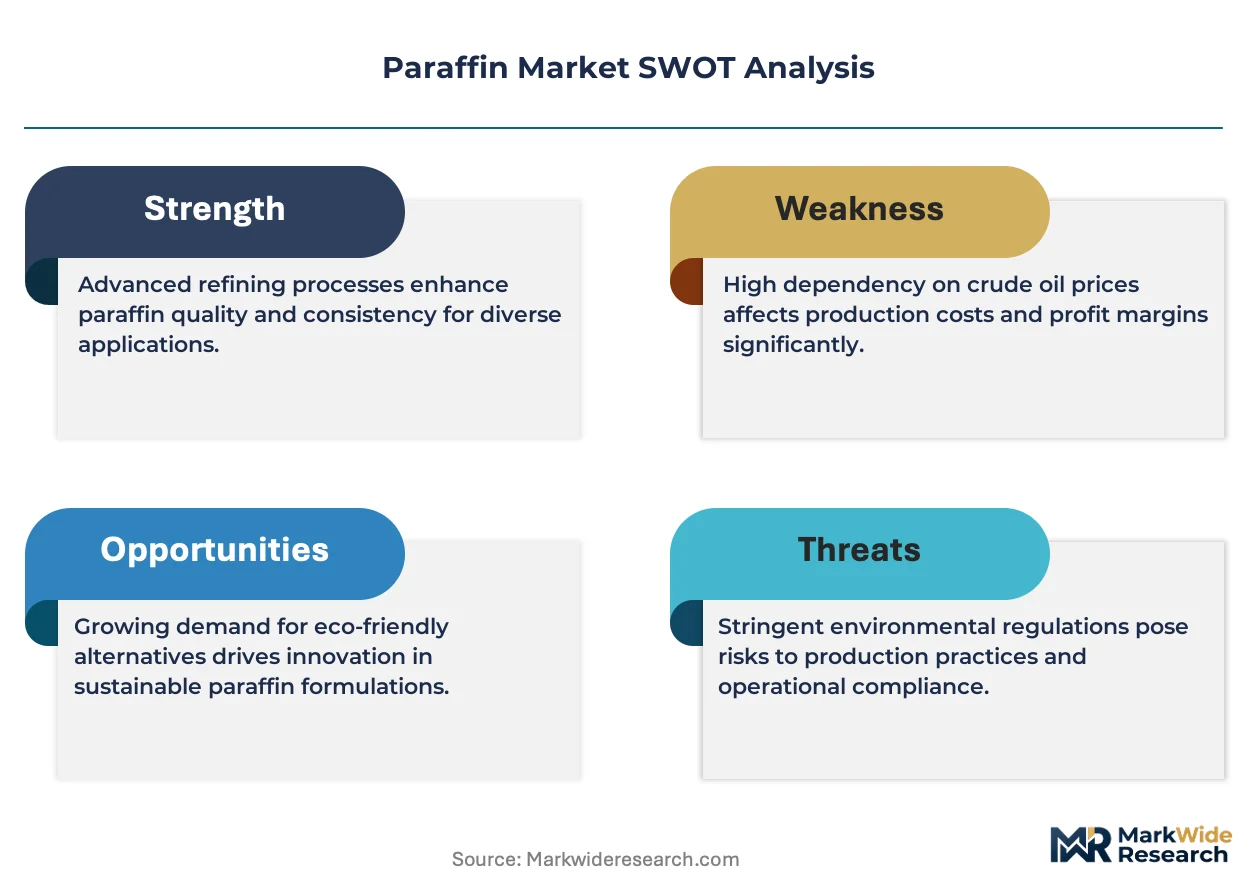
REACH registration requirements in Europe and FDA 21 CFR 172.886 food-contact rules in the United States constrain market access for producers lacking certified refining pathways. China's GB standards for cosmetic-grade wax and India's BIS specifications for candle manufacturing add further compliance layers across major consumption zones. Stakeholders must monitor how bio-based wax alternatives and circular feedstock certifications reshape procurement criteria ahead of regulatory tightening.
Market Dynamics
Refinery consolidation and slack wax supply tightening are compressing feedstock availability while REACH registration deadlines force capacity rationalization among smaller European producers.
Growth Catalysts
- Candle manufacturing expansion:China's GB standards for cosmetic-grade wax are normalizing quality baselines that enable export-grade production scaling.
- Fischer-Tropsch technology maturation:Gas-to-liquid processes are diversifying feedstock origins beyond petroleum dependence.
- Pharmaceutical-grade specification tightening:FDA 21 CFR 172.886 compliance is filtering sub-scale producers and concentrating volume with certified refiners.
Market Restraints
- Crude oil price volatility:Slack wax pricing tracks vacuum gasoil differentials that swing with OPEC+ production decisions.
- European supply concentration:REACH registration costs exceed €100,000 per substance, freezing marginal producers out of EU market access.
- Bio-based wax substitution:Soy and carnauba alternatives capture premium packaging segments willing to absorb 15-30% cost premiums.
Strategic Opportunities
- India candle export manufacturing:BIS specifications alignment with Gulf state import rules positions Indian refiners for Middle East procurement contracts.
- Microcrystalline wax in rubber processing:Tire manufacturers seek higher melting-point formulations for high-performance compound stability.
- Dual carbon goals in China:MEE carbon intensity benchmarks are incentivizing hydrofinishing retrofits that yield lower-emission paraffin output.
Industry Challenges
- Hydrofinishing catalyst expertise scarcity:Deep desulfurization and color-stabilization know-how concentrates among retired refinery specialists.
- Pharmaceutical-grade certification timelines:FDA drug master file approvals stretch 18-24 months, freezing capacity allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraffin Market |
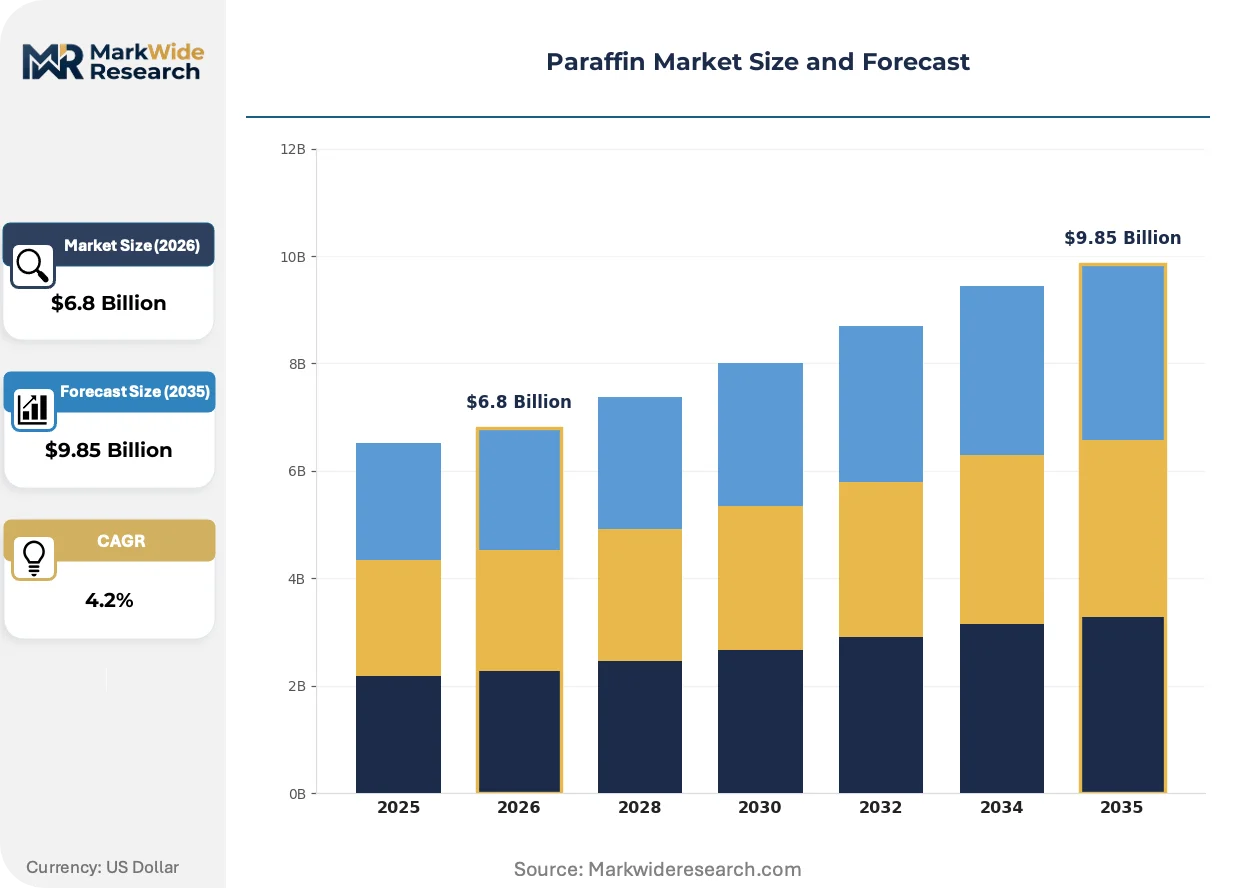
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Refined, Semi Refined, Poorly Refined, Microcrystalline Application: Candles, Cosmetics, Pharmaceuticals, Electrical Insulation, Lubricants Packaging Type: Blocks, Liquid, Granules, Pellets End Use Industry: Consumer Goods, Personal Care, Pharmaceutical Firms, Electrical Equipment Manufacturers |
| Companies Covered | CEPSA, ENEOS Corporation, ExxonMobil, HollyFrontier, Eni, Sasol, China National Petroleum Corporation, International Group, Calumet Specialty Products Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraffin Market Strategic Shifts & Innovations
Solvent dewaxing process intensification and synthetic wax blending are compressing traditional technical-grade margins while opening formulation-service revenue pools.
Advanced hydrofinishing catalysts with zeolite support structures are collapsing the cost gap between semi-refined and fully refined paraffin grades. Adhesive manufacturers in South Korea and Japan are accelerating adoption of these upgraded streams for hot-melt formulations. The technology is collapsing legacy tiering between food-grade and technical-grade pricing bands.
REACH authorization list expansion under ECHA's 2024-2026 work program is tightening oil-content thresholds for lubricant-derived waxes. Refiners must now document Substance of Very High Concern screening across full carbon-chain distributions. Pharmaceutical and food-contact segments are responding by dual-sourcing from Fischer-Tropsch and petroleum routes to hedge regulatory disqualification risk.
Direct refinery-to-formulator contracting is displacing merchant trading houses in slack wax procurement. Candle manufacturers in Poland and Turkey are establishing offtake agreements with specific hydrofinishing units rather than spot-market purchasing. This concentration is most visible in Central European markets where logistics costs favor captive supply relationships over Baltic spot arbitrage.
Paraffin Market Segmentation
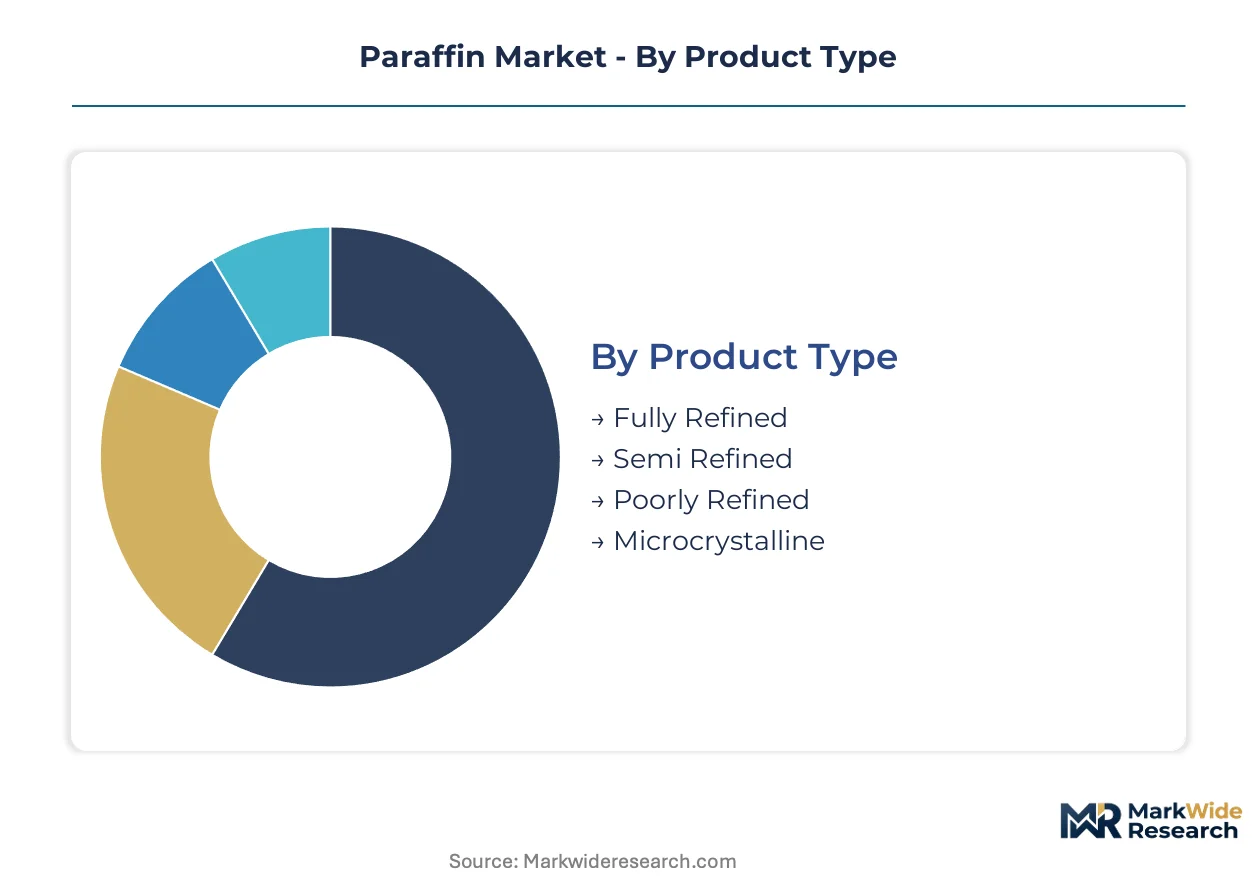
Paraffin segmentation reflects the tension between commodity-grade volume and certified-grade margin extraction. Refiners configure hydrofinishing intensity and downstream formulation services differently across each tier.
Product Type:
Refining depth determines specification ceilings and regulatory access across pharmaceutical, food-contact, and technical applications.
- Fully Refined:Oil content sits below 0.5 percent with complete odor removal through multi-stage hydrofinishing. FDA 21 CFR 172.886 compliance and REACH SVHC screening concentrate demand among certified refiners serving pharmaceutical tablet coatings and food packaging in Germany and the United States.
- Microcrystalline:Finer crystal structures and higher melting points derive from heavy slack wax fractions through advanced solvent dewaxing. South Korean adhesive manufacturers and Japanese tire compounders are absorbing premium pricing for rubber-processing stability and hot-melt viscosity control.
- Semi Refined:Moderate oil retention suits candle manufacturing and general moisture-barrier applications where odor thresholds are less stringent.
- Poorly Refined:Higher oil content limits use to industrial rust prevention and low-specification coating applications with minimal regulatory exposure.
The dominant share belongs to Fully Refined, while Microcrystalline is closing the gap fastest.
Application:
End-use specifications fragment procurement patterns across consumer discretionary, regulated medical, and industrial durability segments.
- Candles:China's GB standards for cosmetic-grade wax are normalizing quality baselines that enable export-grade production scaling to Middle East and European retail channels.
- Pharmaceuticals:FDA drug master file approvals stretch 18-24 months, freezing capacity allocation decisions among refiners seeking oral-solid-dosage and topical-ointment certifications.
- Cosmetics:REACH authorization list expansion under ECHA's work program is tightening oil-content thresholds for skin-contact formulations.
- Electrical Insulation:Transformer and cable manufacturers specify dielectric strength and oxidation stability that favor fully refined streams with documented carbon-chain distribution.
- Lubricants:Rust-prevention and metalworking fluid applications absorb semi-refined and poorly refined volumes through direct refinery-to-blender contracting.
Candles command the volume lead, though Pharmaceuticals is expanding most quickly on certification scarcity premiums.
Packaging Type:
Physical form factors align with melting equipment, handling automation, and logistics cost structures across downstream operations.
- Pellets:Dust-free flow properties suit automated dosing systems in high-volume candle manufacturing and hot-melt adhesive compounding.
- Blocks:Traditional format persists in artisan candle production and small-batch cosmetic formulation where manual handling dominates.
- Liquid:Bulk tanker delivery eliminates solidification energy costs for continuous-process rubber and coating operations.
- Granules:Intermediate surface-area-to-volume ratio balances melt rate with storage stability in medium-scale pharmaceutical coating applications.
Pellets hold the dominant position, while Liquid formats are gaining share fastest in integrated refinery-to-formulator supply chains.
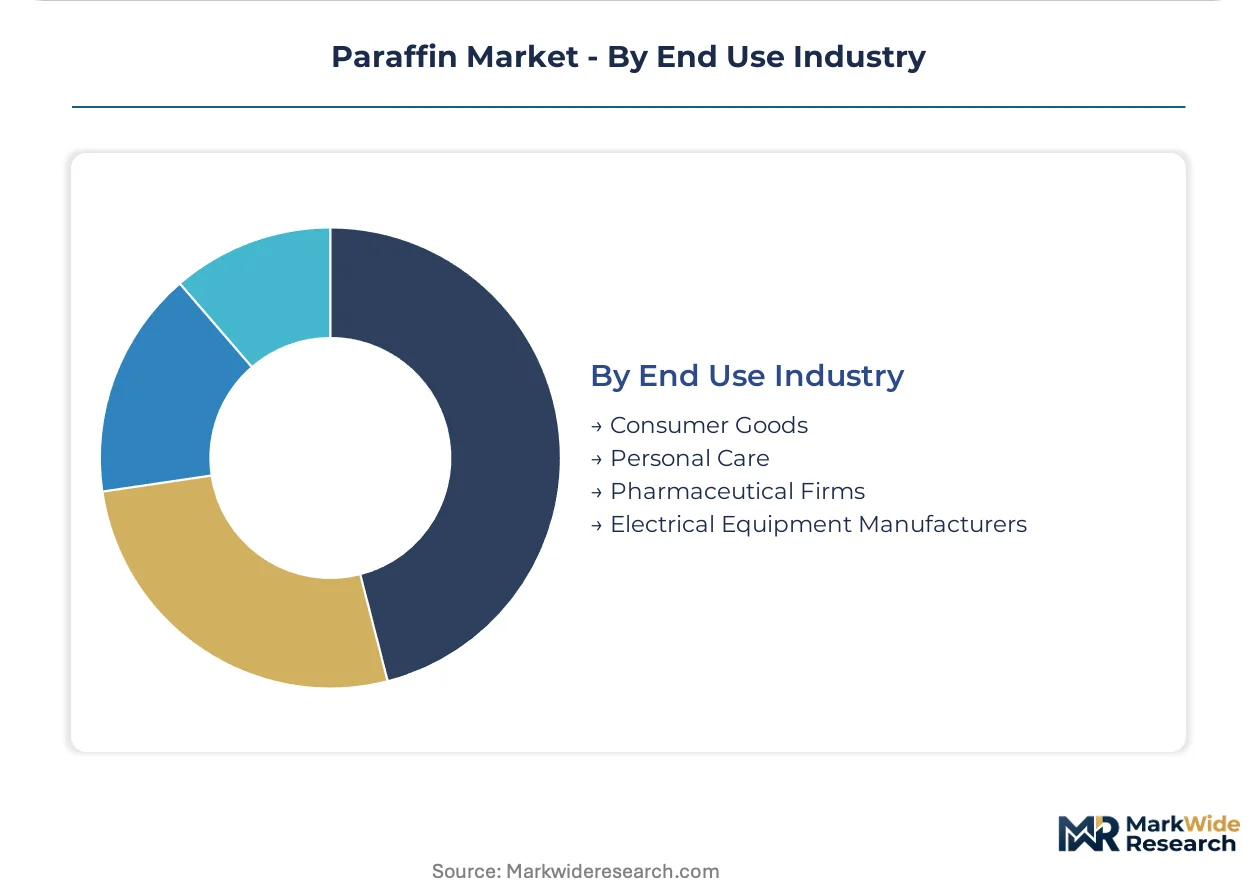
End Use Industry:
Customer concentration and procurement sophistication vary sharply between regulated pharmaceutical firms and fragmented consumer goods channels.
- Pharmaceutical Firms:Dual-sourcing from Fischer-Tropsch and petroleum routes hedges regulatory disqualification risk under REACH authorization expansion.
- Personal Care:India's BIS specifications for cosmetic-grade wax align with Gulf state import rules, positioning domestic refiners for Middle East procurement contracts.
- Consumer Goods:Candle and packaging manufacturers in Poland and Turkey are establishing offtake agreements with specific hydrofinishing units rather than spot-market purchasing.
- Electrical Equipment Manufacturers:Transformer OEMs in Japan and South Korea specify oxidation stability test protocols that filter out semi-refined supply.
Consumer Goods absorbs the largest volume, though Pharmaceutical Firms is climbing the fastest on certification-driven supplier consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes paraffin primarily for packaging and personal care formulations, while the United States directs larger shares toward pharmaceutical coatings and food-contact applications. European demand concentrates in certified-grade segments where REACH compliance filters supply. India's candle export manufacturing absorbs semi-refined volumes at scale.
China
Domestic wax consumption for packaging films and cosmetic formulations continues deepening across coastal provinces. MEE carbon intensity benchmarks incentivize hydrofinishing retrofits that yield lower-emission paraffin output. The Yangtze River Delta hosts integrated refinery-to-formulator supply chains serving hot-melt adhesive manufacturers.
United States
FDA 21 CFR 172.886 food-contact rules concentrate pharmaceutical-grade demand with certified refiners. Drug master file approvals stretch 18-24 months, freezing capacity allocation decisions among Gulf Coast hydrofinishing units. Texas and Louisiana host slack wax upgrading facilities supplying oral-solid-dosage coatings.
Germany
ECHA's 2024-2026 work program tightens oil-content thresholds for lubricant-derived waxes under REACH authorization expansion. Pharmaceutical and food-contact segments dual-source from Fischer-Tropsch and petroleum routes to hedge regulatory disqualification risk. The Rhine-Ruhr industrial corridor anchors certified refining capacity for tablet coating applications.
India
BIS specifications for candle manufacturing align with Gulf state import rules, positioning domestic refiners for Middle East procurement contracts. Maharashtra and Gujarat host slack wax processing units serving export-oriented candle manufacturers. Personal care applications in Tamil Nadu absorb cosmetic-grade volumes under emerging quality baselines.
Japan
METI oxidation stability test protocols filter out semi-refined supply for transformer and cable manufacturers. Tire compounders in the Kansai region specify microcrystalline wax for high-performance rubber processing. Osaka-based adhesive manufacturers accelerate adoption of upgraded hydrofinishing streams.
Paraffin Market Key Industry Players
Capability concentration sits with integrated refiners commanding hydrofinishing expertise; scale advantage sits with national oil companies capturing slack wax feedstock access. The vendor base organizes around three strategic archetypes: petroleum majors with captive refining, Fischer-Tropsch technology specialists, and regional slack wax upgraders. Dominant competitive moves include direct refinery-to-formulator contracting displacing merchant trading, and hydrofinishing catalyst licensing consolidating technical know-how.
Among petroleum majors, ExxonMobil anchors the integrated refining tier with cost-advantaged feedstock access. Sasol occupies a distinctive position through Fischer-Tropsch wax technology leadership. CEPSA exemplifies the regional specialist archetype, with Spanish refinery-based upgrading capabilities serving European certified-grade demand. These three represent the primary competitive vectors shaping procurement patterns across pharmaceutical, food-contact, and technical applications.
| Leading Market Players |
|---|
| CEPSA |
| ENEOS Corporation |
| ExxonMobil |
| HollyFrontier |
| Eni |
| Sasol |
| China National Petroleum Corporation |
| International Group |
| Calumet Specialty Products Partners |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta refinery cluster in China anchors global slack wax upgrading capacity, and its hydrofinishing intensity directly dictates pricing power across pharmaceutical and food-contact grades downstream. Cost compression runs through semi-refined tiers as merchant traders lose ground to direct refinery-to-formulator contracting.
Pricing Analysis
Long-term offtake agreements now dominate procurement for certified-grade paraffin, displacing spot-market purchasing that once governed candle and packaging segments. Three-tier pricing structure across fully refined, semi-refined, and poorly refined grades tracks oil-content thresholds and REACH registration status. Pricing pressure stems from bio-based wax substitution in premium packaging segments willing to absorb cost premiums for soy and carnauba alternatives. Small-scale candle manufacturers exhibit highest price sensitivity, while pharmaceutical firms prioritize certification security over unit economics.
Supply Chain Analysis
Export-control regimes on advanced hydrofinishing catalysts with zeolite support structures constrain technology transfer to emerging refiners in India and Southeast Asia. Supply concentrates in China, the United States, and Germany, with raw material dependencies on vacuum gasoil from integrated refineries and Fischer-Tropsch streams from gas-to-liquid facilities. Single-source vulnerability sits with retired refinery specialists possessing deep desulfurization expertise. Distribution runs through direct refinery-to-formulator channels in Central Europe and bulk tanker liquid delivery for continuous-process rubber operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as refinery consolidation tightens slack wax availability and REACH deadlines force capacity rationalization among marginal European producers.
For Market Incumbents: Pre-empt bio-based substitution by securing circular feedstock certifications ahead of regulatory tightening. Deepen backward integration into captive slack wax supply through refinery consolidation in the Yangtze River Delta. Prioritize hydrofinishing catalyst licensing to consolidate technical know-how before expertise scarcity intensifies. For New Entrants and Emerging Players: India's BIS-aligned candle export manufacturing represents the most penetrable entry point, given Gulf state procurement contract availability and quality baseline normalization. Microcrystalline wax for South Korean and Japanese tire compounders offers formulation-service revenue pools with premium pricing absorption. Enter through specialized slack wax upgrading partnerships with Spanish or Gulf Coast refiners lacking Fischer-Tropsch diversification. For Investors and Strategic Acquirers: Long-term, this sits as a certification-scarcity play because FDA drug master file approvals and REACH SVHC screening create durable moats around certified refiners. Target acquisition archetypes include regional slack wax upgraders with hydrofinishing retrofit potential and dual-source Fischer-Tropsch capability. Watch for MEE carbon intensity benchmark enforcement in China as the inflection signal accelerating lower-emission capacity investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slack Wax Supply | Captive feedstock access insulates ExxonMobil and Sasol from vacuum gasoil price volatility. |
| Hydrofinishing Catalyst Licensing | Zeolite-supported technology licensing collapses cost gaps between semi-refined and fully refined grades. |
| Circular Feedstock Certification | CEPSA's bio-based wax alternatives capture premium packaging segments under EU Green Deal procurement criteria. |
| Direct Refinery-to-Formulator Contracting | Polish and Turkish candle manufacturers bypass Baltic spot arbitrage through captive supply relationships. |
| Fischer-Tropsch Capacity Diversification | Dual-sourcing from petroleum and gas-to-liquid routes hedges REACH authorization disqualification risk. |
Research Approach
Initial hypotheses were tested against primary input from hydrofinishing unit managers, candle manufacturer procurement leads, pharmaceutical formulation directors, and adhesive compounder technical buyers and refined through secondary validation. Bottom-up and top-down triangulation drew from customs trade data, ECHA REACH registration databases, SEC refinery segment filings, and FDA drug master file disclosures. Primary fieldwork concentrated on Yangtze River Delta integrated supply chains and Rhine-Ruhr certified refining corridors.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning refining depth, application specification, packaging format, and end-use industry procurement sophistication. CAGRs derived from installed hydrofinishing capacity trajectories, slack wax availability curves, and certification timeline bottlenecks. Forecast inputs incorporated MEE carbon intensity benchmark adoption rates and ECHA authorization list expansion schedules.
Practitioners should monitor OPEC+ production decisions, REACH SVHC screening outcomes, and bio-based wax cost parity milestones for early signals of forecast revision. Forecasts reflect assumptions around refinery consolidation pace and catalyst technology transfer feasibility. Material shifts in crude oil price volatility or Fischer-Tropsch feedstock cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Tallow Amine Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Global Creosote Oil Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Squalane Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market