
 United Kingdom Active Pharmaceutical Ingredients (API) Market | 2026-2036
United Kingdom Active Pharmaceutical Ingredients (API) Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Active Pharmaceutical Ingredients (API) Market Analytics
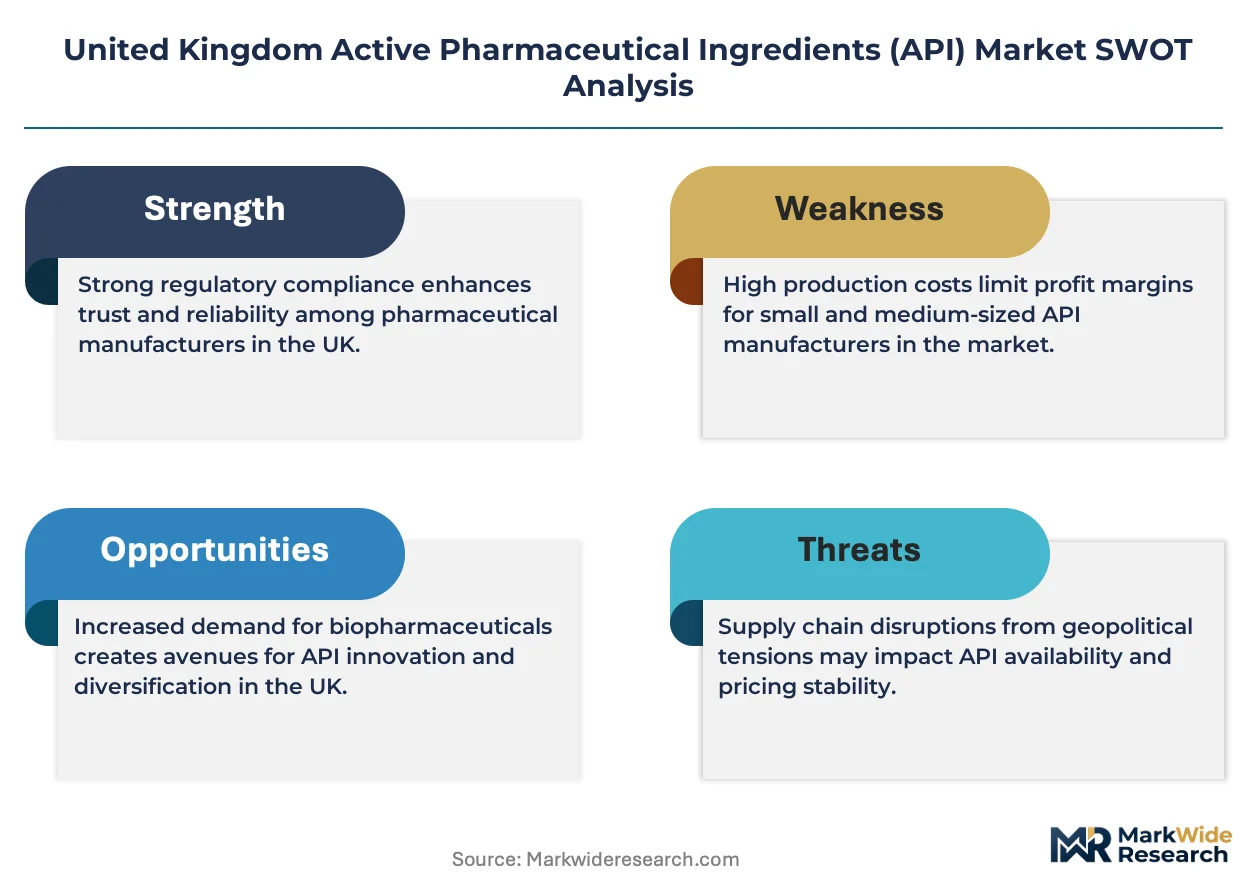
EMA divergence from MHRA equivalence agreements is consolidating the compliance burden for UK API sponsors. Pfizer Inc. leverages its Sandwich manufacturing campus to sustain domestic peptide synthesis capacity. Novartis AG anchors its radioligand API production at its Horsham facility, competing against continental radiopharmacy networks. BASF SE differentiates through its Ludwigshafen-derived custom synthesis expertise, extending services to UK biotech clients seeking complex small-molecule intermediates.
Active pharmaceutical ingredients comprise pharmacologically active substances formulated into finished drug products, typically synthesized through chemical routes or expressed via recombinant bioprocessing with purity thresholds exceeding 99.5% for most oral solid dosage applications. These compounds serve as the therapeutic core enabling pharmacodynamic activity across prescription medicines. Synthetic APIs occupy the dominant share by volume, though biotech APIs command premium pricing due to mammalian cell culture complexity and cold-chain handling requirements. Cancer applications attract the fastest capacity additions, driven by antibody-drug conjugate pipelines and personalized medicine investments. Injectable delivery modes carry higher aseptic manufacturing standards, concentrating margin pools among facilities with isolator technology and continuous processing capabilities.
The Medicines and Healthcare products Regulatory Agency enforces UK-specific good manufacturing practice inspections, while the Human Medicines Regulations transpose retained EU directives with post-Brexit amendments affecting importation documentation. MHRA batch release requirements now diverge from EMA centralized procedures, reshaping supply chain verification protocols for API importers. Stakeholders must monitor whether MHRA mutual recognition agreements with FDA and Health Canada expand to streamline multi-territory filing strategies for UK-manufactured active substances.
Market Dynamics
MHRA divergence from EMA batch testing protocols is forcing UK-based API sponsors into parallel compliance investments, reshaping capital allocation across the Golden Triangle manufacturing corridor.
Growth Catalysts
- Post-Brexit regulatory autonomy:The MHRA's independent batch release framework creates dedicated UK manufacturing incentives for sponsors seeking domestic market access without EMA centralized procedures.
- Antibody-drug conjugate pipelines:Oncology biologics manufacturing is drawing fresh capital investment into Cambridge-Oxford-London corridor facilities with mammalian cell culture capabilities.
- Continuous processing adoption:Isolator technology investments at UK contract development organizations are compressing aseptic manufacturing timelines for injectable APIs.
Market Restraints
- Input cost volatility:Solvent and starting material prices for complex small-molecule intermediates fluctuate with Ludwigshafen-derived supply chains.
- Regulatory friction:The Human Medicines Regulations' post-Brexit amendments impose duplicative importation documentation for API suppliers maintaining EU-UK dual filing.
- Technical limitation:Cold-chain handling requirements for biotech APIs restrict manufacturing site selection to facilities with validated cryogenic storage infrastructure.
Strategic Opportunities
- Radioligand production:The Horsham facility corridor anchors capacity for competing against continental radiopharmacy networks serving UK cancer centers.
- Peptide synthesis specialization:Sandwich manufacturing campus infrastructure supports domestic capacity for sponsors seeking to reduce continental European import dependency.
- CDMO partnership models:Emerging risk-sharing agreements between UK biotech clients and custom synthesis providers are redistributing development cost burdens.
Industry Challenges
- Skill scarcity in bioprocessing:Mammalian cell culture technicians with GMP experience command premium wages across Cambridge cluster facilities.
- Capex intensity for isolator retrofits:Legacy filling lines require substantial reinvestment to meet MHRA's updated aseptic processing guidelines.
- Compliance timeline compression:MHRA inspection backlogs are extending good manufacturing practice certification cycles for new API manufacturing entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Active Pharmaceutical Ingredients (API) Market |
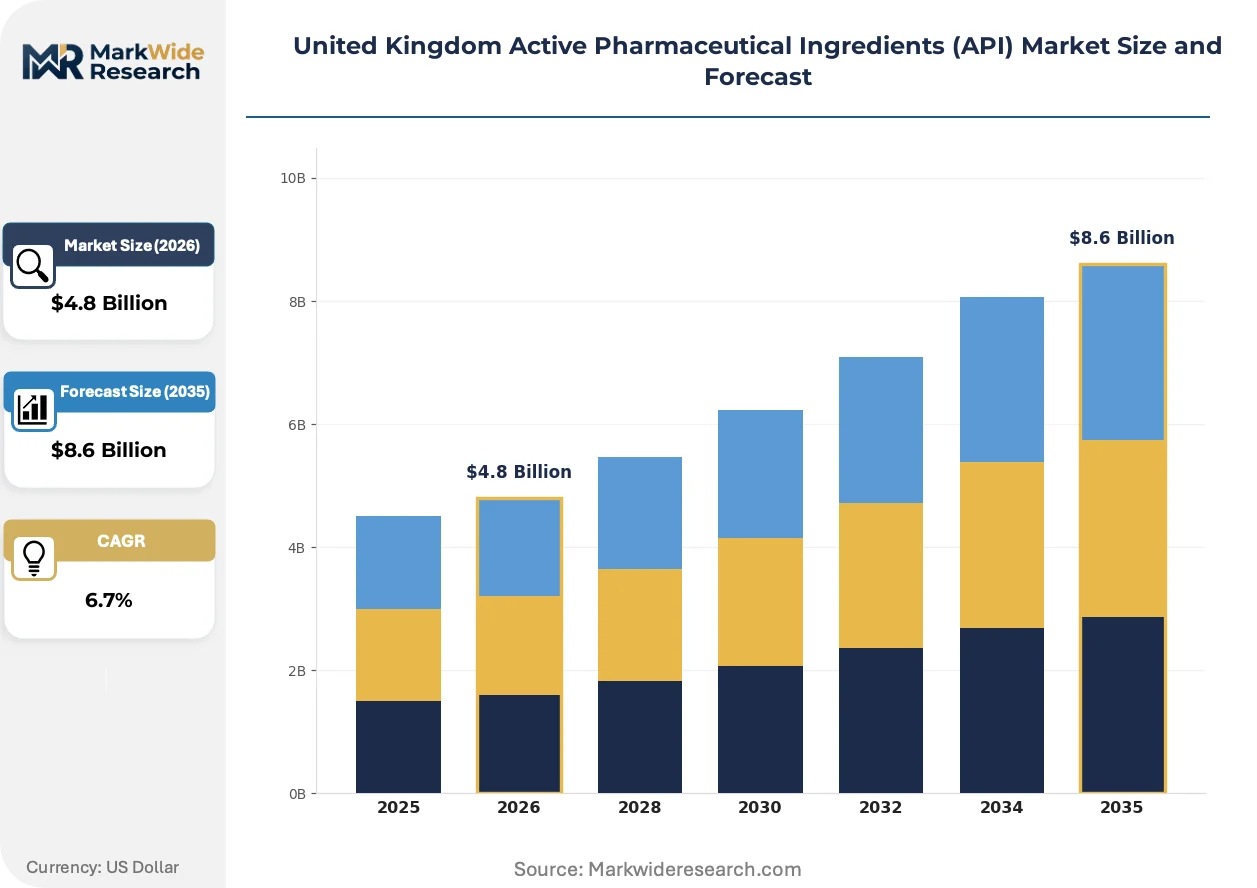
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Synthetic, Biotech, Natural, Radioisotopes Application: Cancer, Cardiovascular, Central Nervous System, Anti-infective Form: Powder, Liquid, Tablet, Capsule Delivery Mode: Oral, Injectable, Topical, Transdermal |
| Companies Covered | Pfizer Inc., Novartis AG, Viatris Inc., Teva Pharmaceutical Industries Ltd., BASF SE, Aurobindo Pharma, AbbVie Inc., Merck & Co., Inc., Sanofi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Active Pharmaceutical Ingredients (API) Market Evolving Landscape
Continuous manufacturing technologies are displacing batch processing across UK API facilities, while regulatory divergence accelerates investment in domestic analytical capabilities.
Single-use bioreactor systems are modularizing upstream bioprocessing workflows for antibody-drug conjugate production. Mid-size UK biotech sponsors are adopting these systems at twice the rate of continental European counterparts. This technology is modularizing facility design, enabling rapid product changeovers that compress campaign timelines from months to weeks.
The Human Medicines Regulations' retained EU directive amendments now mandate UK-specific importation documentation for active substances. This regulatory friction is fragmenting previously unified EU-UK supply verification protocols. Sponsors with Horsham and Sandwich manufacturing footprints are responding by duplicating analytical testing capacity rather than relying on EMA-accepted certificates.
Hospital procurement consortia are consolidating radioligand purchasing through centralized tendering mechanisms. Traditional distributor networks serving oncology departments face disintermediation as NHS trusts negotiate direct supply agreements with API manufacturers. This consolidation is most visible across London and South East England cancer centers, where volume commitments are reshaping supplier qualification criteria.
United Kingdom Active Pharmaceutical Ingredients (API) Market Segmentation
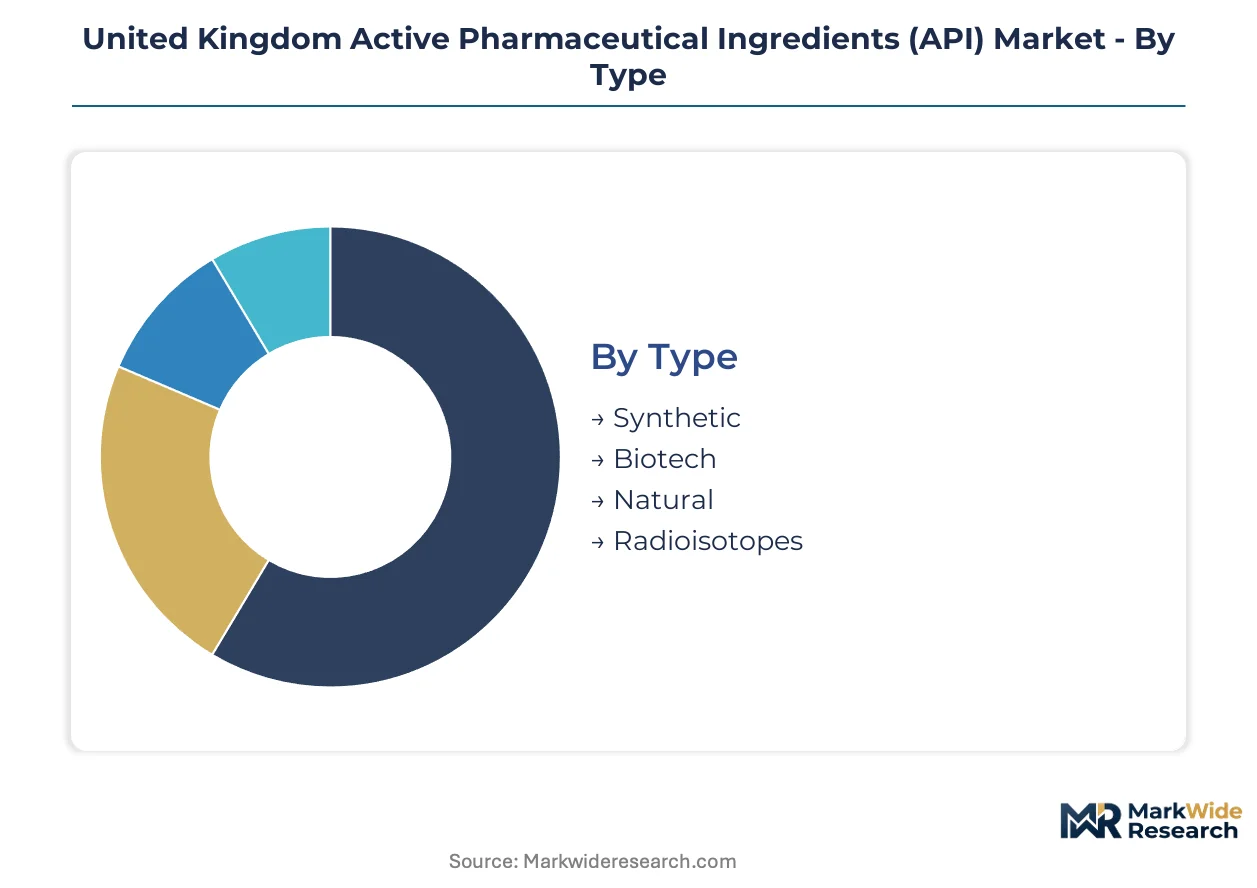
API segmentation in the United Kingdom reflects divergent manufacturing economics across molecular classes and divergent regulatory pathways across therapeutic areas. Sponsors allocate capital based on whether batch release requirements favor domestic MHRA certification or retained EMA equivalence.
Type:
Buyers in this category differentiate primarily by manufacturing complexity and cold-chain infrastructure requirements.
- Synthetic:Chemically synthesized small molecules dominate by volume, with purity thresholds exceeding 99.5% for oral solid dosage forms. Demand concentrates across the Golden Triangle corridor where Cambridge and Oxford facilities serve domestic sponsors seeking Ludwigshafen-derived intermediates without continental import dependency.
- Biotech:Recombinant proteins and monoclonal antibodies command premium positioning due to mammalian cell culture complexity and validated cryogenic storage mandates. The Cambridge cluster attracts fresh capital for antibody-drug conjugate manufacturing as oncology pipelines expand.
- Natural:Plant-derived alkaloids and fermentation products serve niche therapeutic applications with established pharmacopeial monographs.
- Radioisotopes:Short-half-life isotopes for diagnostic and therapeutic radiopharmacy require proximity to Horsham facility corridor and NHS cancer centers.
Synthetic APIs lead volumes today; biotech APIs are gaining share fastest.
Application:
Therapeutic area selection determines whether sponsors invest in isolator technology or standard aseptic processing infrastructure.
- Cancer:Oncology APIs span cytotoxic small molecules, biologics, and radioligands with the most stringent handling protocols. NHS procurement consolidation across London and South East England cancer centers is reshaping supplier qualification criteria toward manufacturers with dedicated oncology suites.
- Cardiovascular:Statins, anticoagulants, and antihypertensives represent mature demand with established generic competition and compressed margins.
- Central Nervous System:Neurology and psychiatry APIs require specialized containment for potent compounds and controlled substance scheduling compliance.
- Anti-infective:Antibiotics and antivirals face procurement pressure from NHS antimicrobial stewardship programs favoring narrow-spectrum agents.
Cardiovascular applications anchor current volumes; cancer applications show the steepest expansion trajectory.
Form:
Physical state selection constrains which contract manufacturers qualify based on powder handling capabilities or liquid filling line configurations.
- Powder:Crystalline and amorphous solids constitute the foundational feedstock for most oral dosage manufacturing, with particle size distribution specifications varying by dissolution profile requirements.
- Liquid:Solutions and suspensions demand validated container closure integrity testing, with demand concentrating among parenteral and pediatric formulation sponsors.
- Tablet:Direct compression and granulation intermediates require specific polymorph control to ensure batch-to-batch dissolution consistency.
- Capsule:Hard gelatin and HPMC capsule fills accommodate hygroscopic or taste-masked APIs with distinct stability packaging requirements.
Powder forms dominate current manufacturing volumes; liquid forms are expanding most quickly with biologics growth.
Delivery Mode:
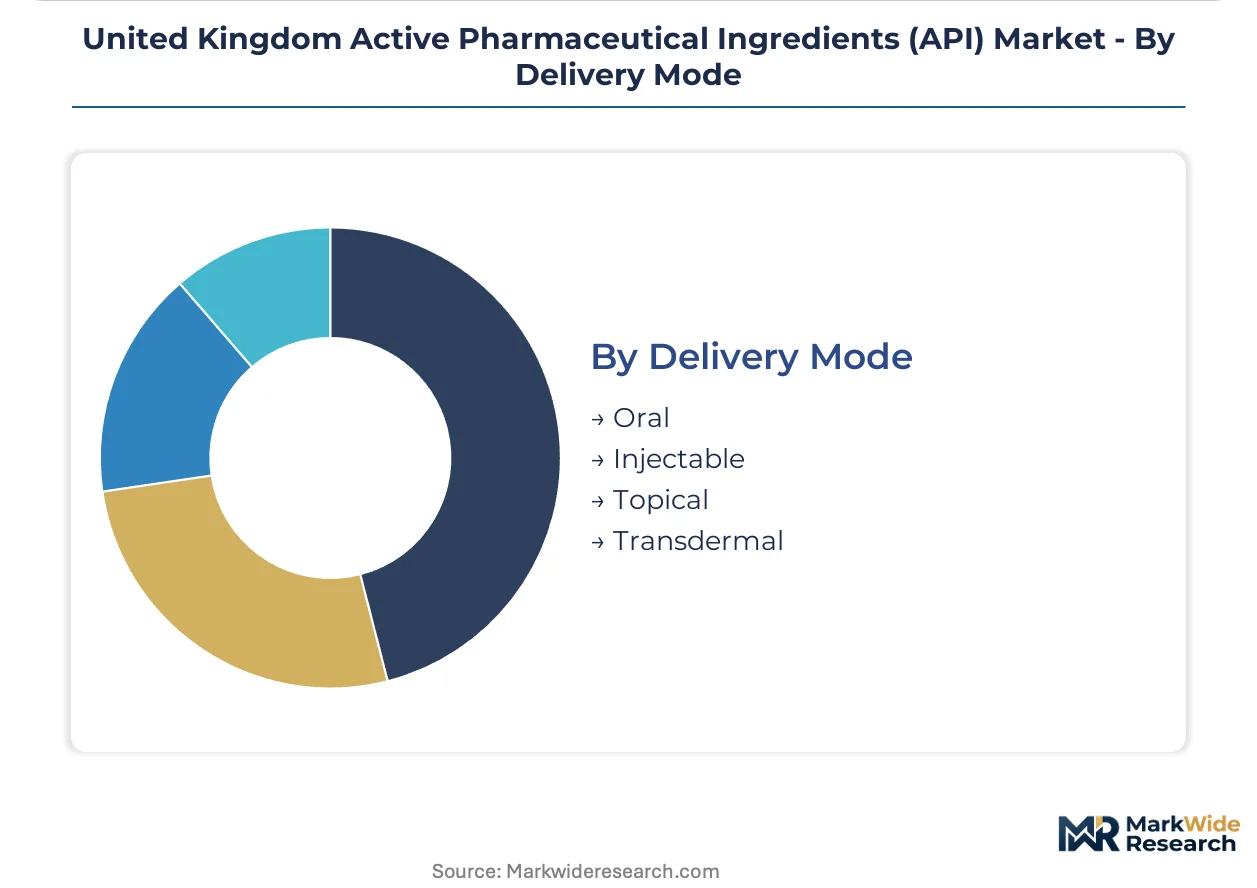
Route of administration determines aseptic processing standards and whether MHRA inspection cycles prioritize isolator-equipped facilities.
- Oral:Tablets, capsules, and solutions serve the broadest patient populations with established bioequivalence frameworks and lower barrier-to-entry manufacturing.
- Injectable:Parenteral APIs demand the highest aseptic assurance with isolator technology and continuous processing adoption compressing campaign timelines across UK CDMOs.
- Topical:Dermatological formulations require specialized content uniformity testing for semisolid dosage forms with limited UK manufacturing concentration.
- Transdermal:Patch and gel systems depend on adhesive matrix expertise and permeation enhancement chemistry with few domestic qualified suppliers.
Oral delivery anchors prescription volumes; injectable modes are climbing the fastest with biotech API expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bioprocessing talent concentrates across the Golden Triangle corridor, anchoring the United Kingdom's API manufacturing advantage. Cambridge, Oxford, and London host the densest clusters of mammalian cell culture technicians and regulatory affairs specialists in Europe. This workforce distribution shapes investment flows and facility siting decisions for domestic and foreign sponsors alike.
London and the South East
Radioligand demand from NHS cancer centers drives API production investment across Greater London and Surrey. The Human Medicines Regulations' post-Brexit importation documentation requirements favor domestic manufacturing over continental supply. Horsham anchors radiopharmaceutical production capacity serving South East England oncology networks.
East of England
Antibody-drug conjugate pipelines concentrate manufacturing demand in Cambridge cluster facilities with single-use bioreactor infrastructure. MHRA batch release divergence from EMA protocols incentivizes sponsors to co-locate analytical testing with production. Stevenage and Cambridge biotech parks attract fresh capital for mammalian cell culture capacity expansion.
South East England
Peptide synthesis capabilities at the Sandwich manufacturing campus reduce import dependency for complex small-molecule intermediates. The retained EU directive amendments impose parallel compliance burdens on sponsors maintaining dual UK-EU filing strategies. Kent's pharmaceutical corridor sustains legacy synthetic chemistry expertise alongside biologics retrofit investments.
North West England
Liverpool and Manchester biotech incubators are emerging as lower-cost alternatives to Golden Triangle facility rents for early-stage API development. The national pharmaceutical regulator's inspection backlogs extend certification timelines for new entrants regardless of location. Cheshire and Lancashire offer brownfield chemical manufacturing sites suitable for isolator technology retrofits.
Scotland
Glasgow and Edinburgh biomanufacturing facilities leverage Scottish Enterprise funding for bioprocessing capacity expansion. MHRA mutual recognition agreement negotiations with FDA and Health Canada could streamline multi-territory filing for UK-manufactured active substances. Grangemouth's petrochemical infrastructure supplies solvent feedstocks for synthetic API production.
United Kingdom Active Pharmaceutical Ingredients (API) Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with captive API supply. Large-cap sponsors with established manufacturing footprints dominate volume production, while specialized contract development organizations capture premium-margin biologics campaigns. Three archetypes define positioning: vertically integrated originators, standalone custom synthesis providers, and hybrid CDMO-biotech partnerships. Capacity expansion and regulatory compliance duplication represent the dominant competitive moves as sponsors adapt to post-Brexit batch testing divergence.
Among Switzerland-based originators, Novartis AG exemplifies the integrated archetype with radioligand production anchoring UK market presence. Pfizer Inc. occupies a distinct position through its Sandwich campus infrastructure sustaining domestic peptide synthesis capability. BASF SE, a German chemicals conglomerate, represents the custom synthesis tier extending Ludwigshafen-derived expertise to UK biotech clients. These three entities illustrate how geographic manufacturing footprints and regulatory compliance strategies differentiate competitive positioning across molecular classes and therapeutic applications.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| BASF SE |
| Aurobindo Pharma |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Sanofi |
| Others |
Value Network & Pricing Analysis
NHS procurement consolidation across London and South East England cancer centers is compressing supplier margins and forcing API manufacturers to unbundle analytical testing services from bulk production. This buyer-side concentration rewards sponsors with captive manufacturing footprints while squeezing custom synthesis providers dependent on spot-market intermediates.
Pricing Analysis
API pricing stratifies across premium certification tiers, standard GMP-compliant batches, and economy-grade non-sterile intermediates. Price differentiation hinges on MHRA batch release documentation completeness and isolator technology deployment. Cost compression in synthetic small-molecule tiers is intensifying because Ludwigshafen-derived starting material prices fluctuate with continental supply disruptions. NHS hospital procurement consortia exhibit highest price sensitivity; radioligand buyers at specialized cancer centers show lowest sensitivity due to half-life constraints and geographic proximity requirements.
Supply Chain Analysis
Bioprocessing technician scarcity across Cambridge, Oxford, and Stevenage clusters is tethering facility expansion timelines to workforce pipeline development rather than capital availability alone. UK API manufacturing draws from Indian and Chinese starting material suppliers, German chemical intermediates, and domestic mammalian cell culture media. Single-source vulnerability concentrates in cryogenic logistics providers serving biotech cold chains. Distribution runs through MHRA-certified wholesale dealers and direct-to-hospital agreements for radiopharmaceuticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UK API manufacturing rests on continuous processing adoption compressing unit costs and antibody-drug conjugate pipelines commanding premium pricing tiers.
For Market Incumbents: Deploy isolator technology retrofits to capture MHRA inspection priority for aseptic processing certification. Incumbent sponsors must consolidate Cambridge cluster bioprocessing talent through apprenticeship partnerships with local universities, insulating against wage inflation. Backward integration into peptide synthesis starting materials at Sandwich reduces continental import exposure from EMA divergence. For New Entrants and Emerging Players: CDMO partnership structures offer the most penetrable entry vector for mid-size biotech sponsors seeking risk-sharing development models. New entrants should target North West England incubators in Liverpool and Manchester for lower facility rents during early-stage scale-up. Qualification as MHRA-registered testing facilities for imported APIs exploits regulatory friction from post-Brexit documentation requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with contract development organizations possessing both synthetic chemistry and biologics capabilities under single quality systems. Long-term viability favors sponsors with dual UK-EU filing strategies already amortized. Monitor MHRA mutual recognition agreement progress with FDA and Health Canada as inflection signal for multi-territory manufacturing investments.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Retrofit | MHRA inspection priority accelerates GMP certification timelines for injectable API lines. |
| CDMO Risk-Sharing Agreement | Development cost redistribution attracts Cambridge cluster biotech sponsors with constrained capital. |
| Radioligand Production Capacity | Proximity to Horsham anchors supply contracts with NHS cancer center procurement consortia. |
| Continuous Processing Adoption | Campaign timeline compression from months to weeks improves asset utilization across Golden Triangle facilities. |
| Dual Regulatory Filing Strategy | Parallel MHRA and EMA documentation buffers against batch testing protocol divergence. |
Research Methodology
Bottom-up oncology therapeutic modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads, mammalian cell culture technicians, hospital procurement managers, and API manufacturing executives combined with secondary validation against MHRA inspection databases, EMA submission records, ClinicalTrials.gov entries, and NHS procurement tender archives. Triangulation between sponsor-reported pipeline data and facility-level capacity announcements ensures consistency across molecular class and delivery mode segmentation.
Historical trendline analysis of synthetic and biotech API production volumes established baseline growth patterns across the projection horizon. The forecast framework models segmentation dimensions including molecular type, therapeutic application, physical form, delivery mode, and regional regulatory cluster. CAGRs derive from capacity utilization trajectories at named Golden Triangle facilities, antibody-drug conjugate pipeline advancement rates, and MHRA inspection cycle duration trends. Industry-specific inputs incorporate radioligand half-life logistics constraints and cryogenic storage infrastructure deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MHRA-EMA mutual recognition negotiations, Ludwigshafen supply chain disruptions, and NHS procurement centralization pace. Forecasts reflect documented assumptions regarding regulatory divergence persistence and bioprocessing workforce pipeline development. Material deviation in MHRA batch testing equivalence agreements or Golden Triangle facility expansion approvals warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Quinoline Market