
 Complex Inorganic Color Pigments Market | 2026-2036
Complex Inorganic Color Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
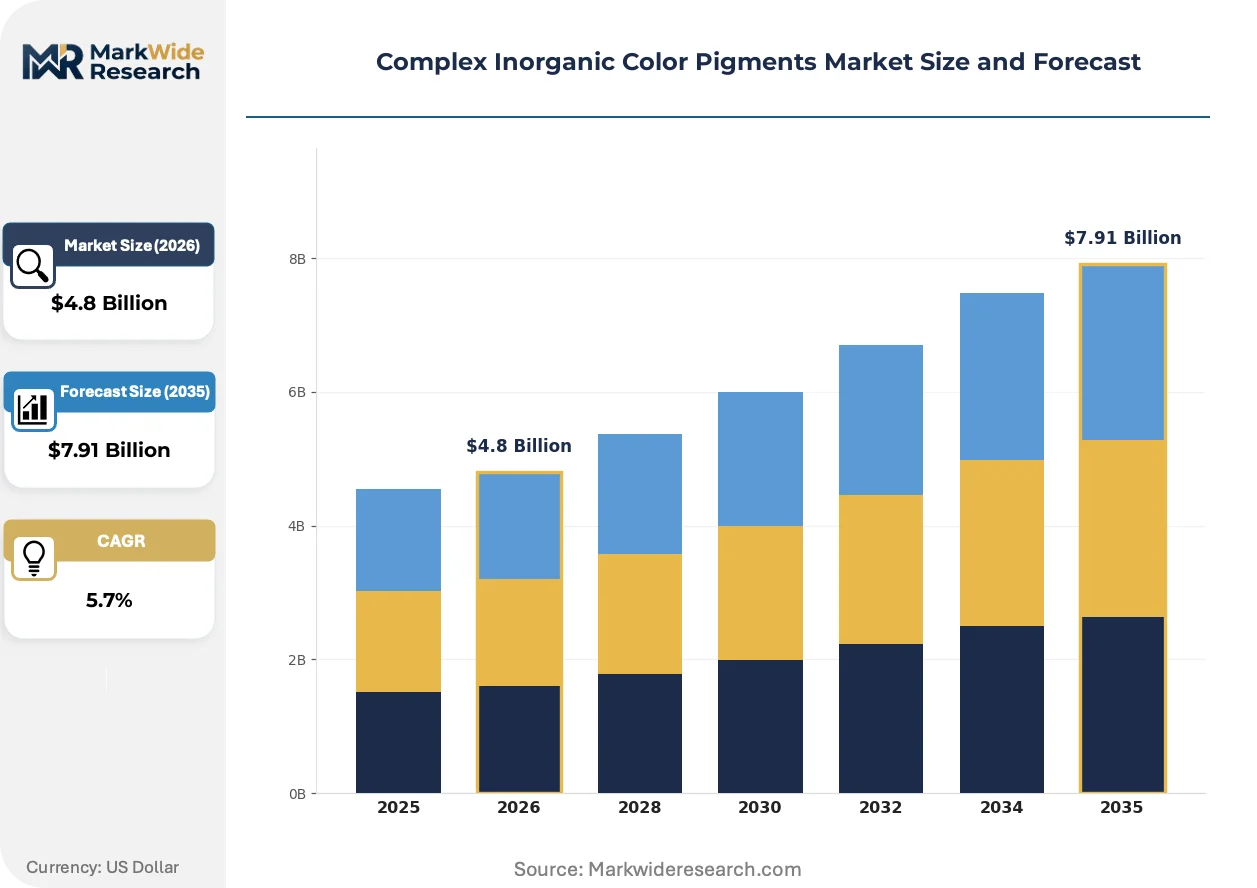
Complex Inorganic Color Pigments Market Analysis
Buyer concentration in the automotive coatings sector is consolidating as top-tier OEMs reduce approved supplier lists and mandate certified pigment batches for color consistency across global assembly plants. Ferro Corporation leverages its fused pigment technology to secure long-term supply agreements with multinational coatings formulators. BASF SE anchors its position through backward integration into precursor chemicals and proprietary surface-treatment processes. Shepherd Color Company differentiates via high-performance cobalt-aluminate and titanate pigments engineered for infrared-reflective applications.
Complex inorganic color pigments are synthetic, heat-stable ceramic materials produced by calcining metal oxides at temperatures exceeding 700°C, yielding crystalline structures with inherent UV resistance and chemical inertness for demanding industrial applications. These pigments serve primarily to impart durable coloration in substrates exposed to harsh thermal, chemical, or radiation environments where organic alternatives degrade. The coatings application segment leads current value generation due to architectural and automotive refinishing requirements, while plastics represents the fastest-expanding category as polymer processors substitute heavy-metal-containing colorants with compliant inorganic alternatives. Powder form dominates manufacturing throughput, though liquid dispersions command margin premiums in automated coatings systems where dust control and batch consistency are critical.
The EPA regulates heavy metal content under TSCA and hazardous air pollutant standards, compelling U.S. pigment manufacturers to validate alternative chemistries and maintain detailed substance documentation. ECHA enforces REACH registration and SVHC restrictions across European supply chains, restricting cadmium and lead-based pigments in consumer-accessible applications. China's MEE implements dual carbon goals and GB standards on industrial emissions, reshaping calcination energy sourcing and facility permitting for domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent substance restrictions threaten to fragment formulation portfolios and complicate global product registration strategies.
Market Dynamics
Automotive OEM color standardization is compressing supplier margins while demanding certified batch traceability across multi-continent assembly networks. Coatings formulators now face dual pressure from thermal management requirements and heavy metal compliance deadlines.
Growth Catalysts
- Infrared-reflective pigment demand:Dark exterior automotive palettes require heat-stable titanate and cobalt-aluminate chemistries that reduce cabin temperatures. OEMs in Germany and the United States now specify these pigments in exterior coating tenders.
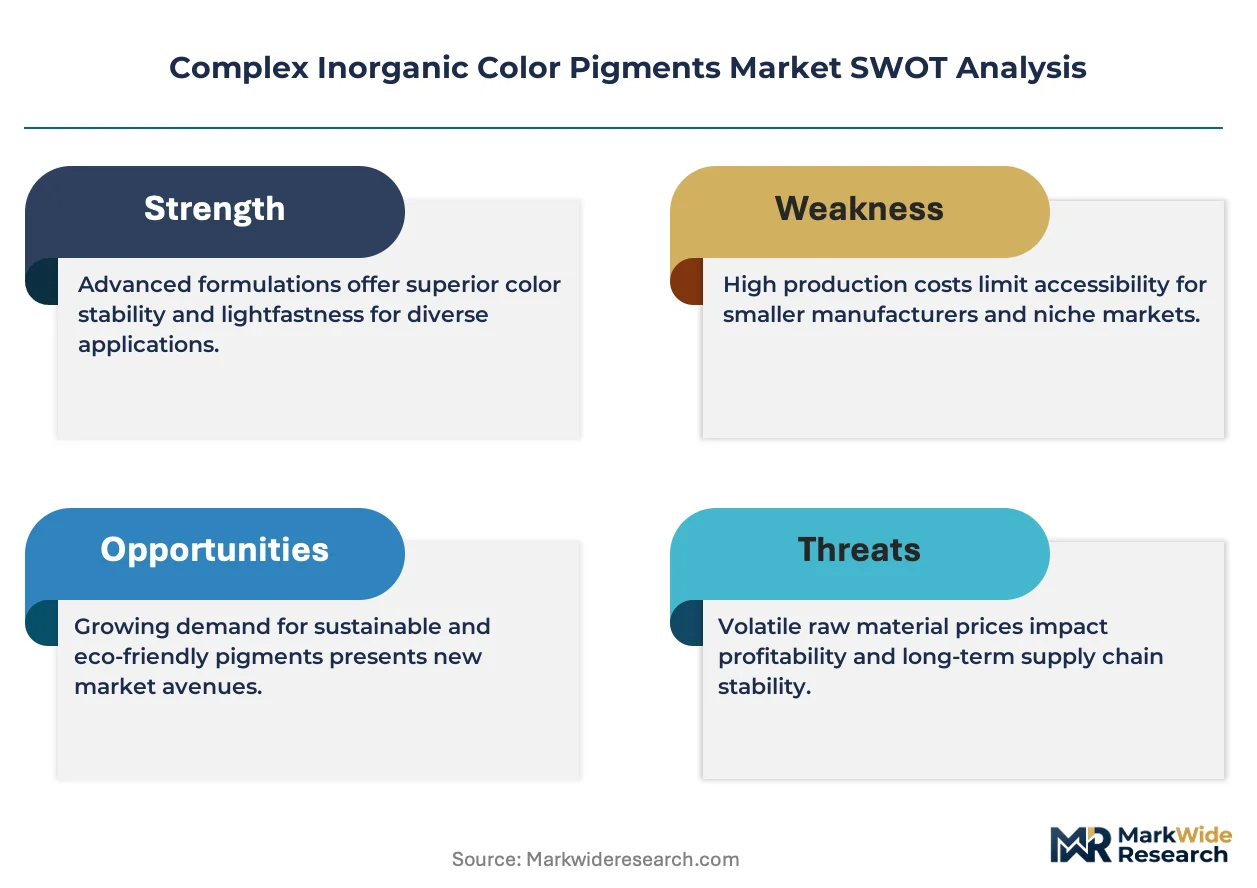
- REACH SVHC substitution mandates:ECHA restrictions on cadmium and lead compounds are forcing coatings manufacturers to reformulate with engineered mixed-metal oxides. This redirects R&D spending toward calcined ceramic alternatives.
- Construction absorption in China:Domestic building activity and automotive production are consuming expanded local pigment capacity. MEE emissions standards are simultaneously upgrading calcination technology across Shandong and Jiangsu production clusters.
Market Restraints
- Cobalt and titanium feedstock volatility:Mixed-metal oxide production depends on metal oxide precursors subject to mining supply disruptions. Price swings in these inputs compress pigment manufacturer margins unpredictably.
- Calcination energy intensity:Firing temperatures exceeding 700°C require substantial thermal input. China's dual carbon goals are restricting coal-fired kiln permits and raising operating costs for domestic producers.
- Organic pigment substitution in plastics:Polymer processors in packaging and consumer goods increasingly favor high-performance organic alternatives for lower-temperature applications where heat stability is less critical.
Strategic Opportunities
- India infrastructure buildout:Government highway and urban housing programs are creating demand for durable architectural coatings. BIS certification requirements favor imported complex inorganic pigments over non-compliant alternatives.
- 3D-printed ceramic components:Additive manufacturing of technical ceramics requires precisely engineered pigment dispersions for color consistency. Aerospace and medical device prototyping labs represent emerging volume.
- EU Green Deal industrial decarbonization incentives:REACH-registered producers investing in electric calcination or hydrogen-fired kilns can access preferential financing. Early movers capture OEM sustainability scorecard advantages.
Industry Challenges
- Colorimetric certification backlog:Batch-to-batch spectrophotometric validation for automotive approvals requires specialized technicians. Qualified personnel shortages in coatings laboratories extend qualification timelines.
- Legacy ERP integration with traceability systems:New blockchain and serialization requirements for pigment provenance clash with established manufacturing software. Mid-tier producers face disproportionate IT upgrade costs.
- Cross-jurisdiction substance registration divergence:EPA TSCA notifications, REACH dossiers, and China's MEE chemical inventories demand non-overlapping documentation. Maintaining parallel compliance teams strains administrative resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complex Inorganic Color Pigments Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Oxide, Titanium Dioxide, Chromium Oxide, Cobalt Blue Application: Coatings, Plastics, Construction, Inks End User: Automotive, Aerospace, Consumer Goods, Electronics Form: Powder, Liquid, Granules, Paste |
| Companies Covered | Ferro Corporation, BASF SE, Shepherd Color Company, DCL Corporation, Clariant AG, Venator Materials PLC, LANXESS AG, Tata Pigments Limited, Heubach GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complex Inorganic Color Pigments Market Emerging Trajectories
Surface engineering and digital color matching are compressing formulation cycles while expanding the performance envelope of ceramic pigments beyond traditional thermal and chemical stability.
Nano-scale surface treatment technology is unifying dispersion stability and weathering resistance in single-calcination architectures. Automotive refinish shops in Germany and Japan are adopting these grades for warranty-compliant color repair. The technology is unifying previously separate pigment and additive purchasing decisions into consolidated material specifications.
REACH authorization timelines for chromium-based pigments are compressing available formulation windows for yellow and orange shades. Coatings manufacturers serving the European architectural sector are accelerating qualification of bismuth vanadate and praseodymium zircon alternatives. The United Kingdom and Nordic markets show fastest transition velocity due to earlier national restrictions.
Automotive OEMs are consolidating approved pigment supplier lists from twelve-plus vendors to four or five certified partners. Tier-one coatings formulators now negotiate multi-year volume commitments in exchange for dedicated production lines and priority batch scheduling. This concentration is most visible in Germany, where Volkswagen Group and BMW procurement teams standardized global color specifications.
Complex Inorganic Color Pigments Market Segmentation
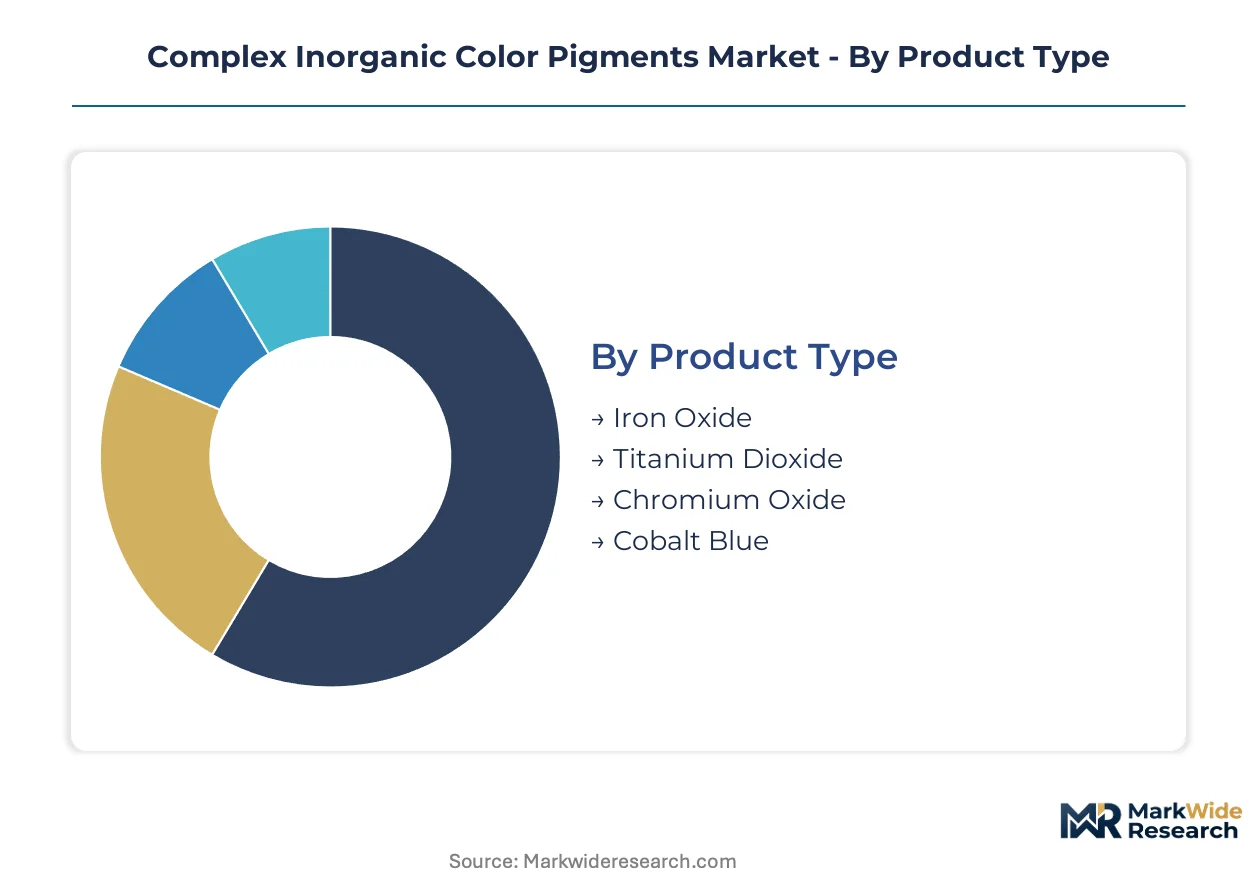
Segmentation in complex inorganic color pigments reflects divergent certification burdens across product chemistries and end-use specifications. Automotive OEMs mandate REACH-registered batches with spectrophotometric traceability, while construction applications prioritize BIS compliance in import-dependent markets.
Product Type:
REACH SVHC restrictions and EPA TSCA notifications impose distinct documentation loads by metal oxide chemistry, with cobalt and chromium compounds facing tighter scrutiny than iron-based alternatives.
- Iron Oxide:Calcined red, yellow, and black iron oxides deliver cost-effective UV stability for architectural coatings and concrete coloration. Demand concentrates in Chinese construction clusters where Shandong and Jiangsu producers expanded calcination capacity to serve domestic infrastructure absorption.
- Titanium Dioxide:Rutile and anatase crystal structures provide maximum hiding power and weathering resistance in automotive basecoats. German OEM specifications now require titanium dioxide grades with documented infrared reflectance for thermal management in dark exterior palettes.
- Chromium Oxide:Dense green pigment with exceptional chemical inertness for aerospace coatings and military specifications.
- Cobalt Blue:Aluminate spinel structure prized for color purity in ceramic glazes and high-temperature plastics.
Leading the category by volume: Iron Oxide. Expanding most quickly: Titanium Dioxide.
Application:
Margin structures diverge sharply by application, with coatings commanding premium pricing for certified batch traceability while construction absorbs commodity-grade volume at compressed returns.
- Coatings:Architectural and automotive refinishing applications require heat-stable pigments with documented calcination parameters and surface treatment specifications. Volkswagen Group and BMW procurement teams in Germany consolidated approved supplier lists to four certified partners with dedicated production lines.
- Plastics:Polymer processors substitute cadmium and lead-based colorants with compliant mixed-metal oxides for consumer-accessible applications. ECHA SVHC substitution mandates redirect formulation investment toward calcined ceramic alternatives across European compounding facilities.
- Construction:Concrete and mortar coloration consumes expanded domestic capacity in China where MEE emissions standards upgrade calcination technology.
- Inks:Screen and inkjet applications demand sub-micron particle distributions for printhead compatibility.
Dominating value generation: Coatings. Gaining share fastest: Plastics.
End User:
Procurement sophistication escalates from commodity spot purchasing in consumer goods to multi-year volume commitments with embedded spectrophotometric certification in automotive.
- Automotive:OEM color standardization compresses supplier margins while mandating batch traceability across multi-continent assembly networks. Tier-one coatings formulators negotiate priority scheduling in exchange for guaranteed offtake.
- Aerospace:Military and commercial aviation specifications demand chromium oxide and cobalt-based pigments with full material pedigree documentation.
- Consumer Goods:Packaging and household products drive substitution toward compliant inorganic alternatives as REACH restrictions tighten.
- Electronics:Ceramic substrate and component manufacturers require precisely engineered pigment dispersions for color consistency in technical ceramics.
Commanding highest certification burden: Automotive. Showing steepest volume climb: Consumer Goods.
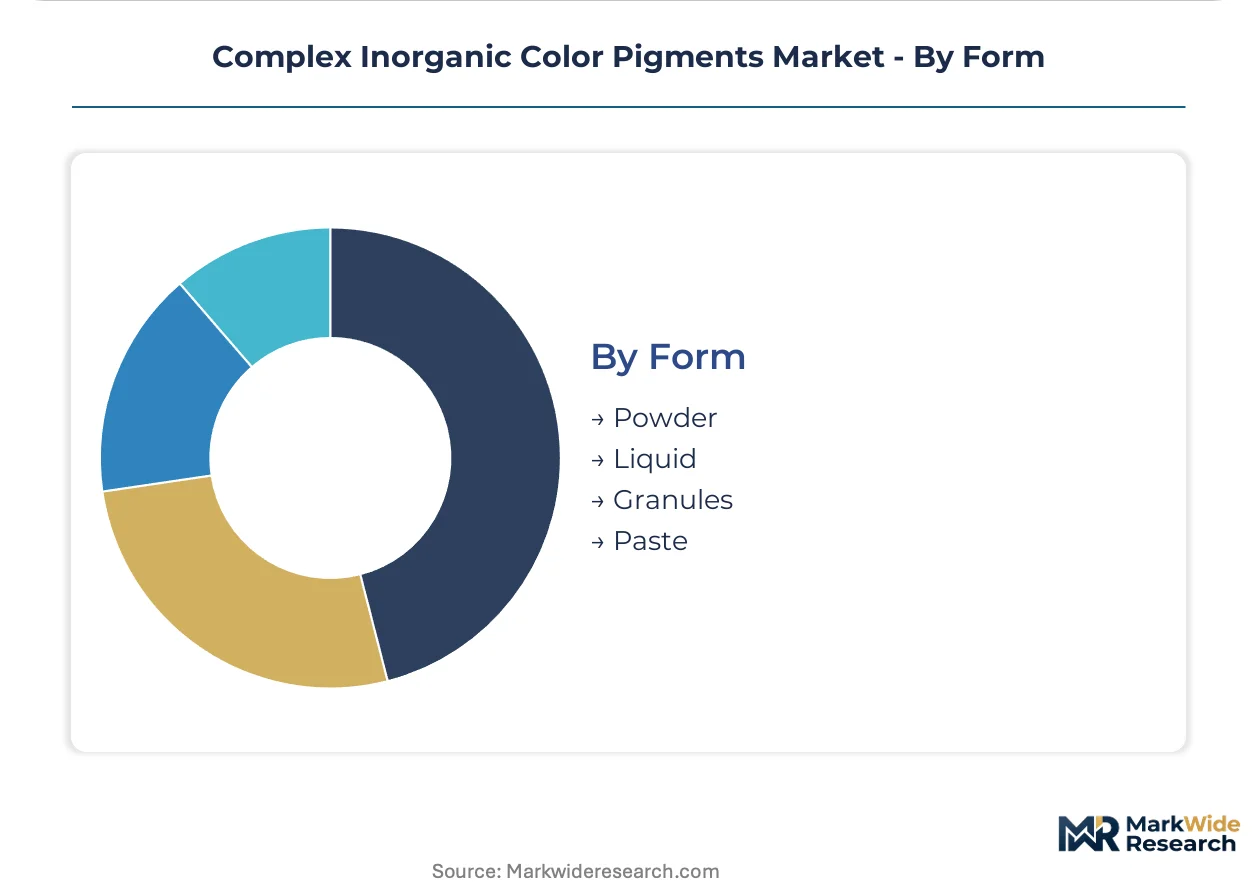
Form:
Supply chain configuration determines form selection, with powder dominating manufacturing throughput while liquid dispersions capture margin premiums in automated coatings systems.
- Powder:Standard calcined output requires milling and classification to specified particle distributions. Dust control investments burden mid-tier producers serving European and North American occupational safety standards.
- Liquid:Pre-dispersed pigment concentrates eliminate dust exposure and improve batch consistency in high-throughput coatings operations. Japanese and German automotive refinish shops adopted these grades for warranty-compliant color repair.
- Granules:Low-dust handling format for direct addition to plastic compounding extruders.
- Paste:High-solids dispersions for specialized ink and coatings applications requiring precise rheology control.
Leading the category by volume: Powder. Capturing margin expansion: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of complex inorganic pigment production, with automotive OEMs and construction contractors drawing from expanded domestic calcination clusters. Demand-side concentration in Asia-Pacific reshapes trade flows as European coatings formulators seek compliant alternatives to restricted chemistries.
China
Construction activity and domestic automotive manufacturing consume expanded pigment capacity from Shandong and Jiangsu production clusters. MEE emissions standards under dual carbon goals restrict coal-fired kiln permits and upgrade calcination technology. Shandong province hosts the densest concentration of iron oxide and mixed-metal oxide facilities serving infrastructure buildout.
Germany
Volkswagen Group and BMW procurement teams consolidated approved pigment supplier lists to four certified partners with dedicated production lines. REACH SVHC restrictions on cadmium and lead compounds redirect formulation toward engineered mixed-metal oxides. The Ruhr industrial corridor anchors coatings R&D and spectrophotometric certification laboratories.
United States
Automotive refinishing and aerospace coatings drive specification of heat-stable titanate pigments for thermal management in dark exterior palettes. EPA TSCA notifications and hazardous air pollutant standards compel validation of alternative chemistries. Ohio and Michigan host the primary formulation centers serving Detroit-area OEM assembly networks.
India
Government highway and urban housing programs create demand for durable architectural coatings requiring BIS certification. Import-dependent construction markets favor compliant complex inorganic pigments over non-compliant alternatives. Maharashtra and Gujarat absorb the bulk of pigment imports for concrete coloration and industrial coatings.
Japan
Automotive refinish shops adopt nano-scale surface-treated pigments for warranty-compliant color repair. METI industrial standards and JIS specifications govern pigment dispersion quality for high-throughput coatings operations. The Nagoya industrial corridor concentrates technical ceramics and precision coating formulation expertise.
Complex Inorganic Color Pigments Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty infrared-reflective and nano-surface-treated grades. The supplier base concentrates around calcination technology leaders with backward integration into precursor chemicals. Three archetypes dominate: diversified chemical conglomerates with captive raw material supply, mid-cap pigment specialists with fused ceramic expertise, and regional compounders serving construction markets. Capacity expansion and strategic partnerships represent the primary competitive vectors as OEMs reduce approved supplier lists.
Among diversified chemical conglomerates, BASF SE anchors the premium tier through proprietary surface-treatment processes. Ferro Corporation and Shepherd Color Company exemplify the specialist archetype, with the latter representing the high-performance cobalt-aluminate and titanate segment. These three entities occupy positions aligned with automotive OEM certification requirements and REACH-registered supply chains.
| Leading Market Players |
|---|
| Ferro Corporation |
| BASF SE |
| Shepherd Color Company |
| DCL Corporation |
| Clariant AG |
| Venator Materials PLC |
| LANXESS AG |
| Tata Pigments Limited |
| Heubach GmbH |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and MEE emissions standards gate qualified supply access and premium-tier pricing power, restricting coal-fired kiln permits to calcination facilities meeting upgraded environmental benchmarks while OEMs in Germany and the United States pay substantial premiums for REACH-registered and EPA-validated pigment batches with spectrophotometric traceability.
Pricing Analysis
Volume concentrates in commodity-grade iron oxide powders serving Chinese construction markets, while margin expansion accrues to liquid dispersions and nano-surface-treated grades for automotive refinish applications. Three-tier pricing structure across certified-automotive, REACH-compliant industrial, and economy construction levels separates batch-traceable pigments from standard-grade alternatives. Cost compression in commodity powders intensifies because Shandong and Jiangsu producers expanded calcination capacity simultaneously. Polymer processors in packaging show highest price sensitivity, while Volkswagen Group and BMW procurement teams accept substantial premiums for dedicated production lines and priority scheduling.
Supply Chain Analysis
REACH registration and automotive OEM qualification requirements filter the supplier base to calcination technology leaders with backward integration into cobalt and titanium oxide precursors. Production gravity centers on China, Germany, and the United States, with Shandong province hosting the densest iron oxide cluster and the Ruhr corridor anchoring European coatings R&D. Raw material supply draws from mining operations in the Democratic Republic of Congo for cobalt feedstock and Australian rutile for titanium dioxide. Single-source vulnerability in cobalt oxide precursors exposes pigment manufacturers to mining disruption and price volatility. Distribution runs through coatings formulators and polymer compounders with certified blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH SVHC substitution mandates and EPA TSCA notification requirements construct a formidable cost-of-compliance barrier, consolidating viable supply among calcination specialists with parallel registration teams across European, American, and Chinese regulatory jurisdictions.
For Market Incumbents: Deploy dedicated production line commitments as the primary lever to secure multi-year volume agreements with consolidating automotive OEMs. Ferro Corporation and Shepherd Color Company exemplify defensive positioning through fused pigment technology and infrared-reflective cobalt-aluminate specialization respectively. Capacity addition in Jiangsu province captures Chinese domestic absorption while MEE emissions standards upgrade legacy facilities. Certification investment in blockchain batch traceability systems addresses legacy ERP integration challenges facing mid-tier competitors. For New Entrants and Emerging Players: Launch via specialty infrared-reflective and nano-surface-treated pigment grades targeting automotive thermal management specifications. India's infrastructure buildout represents the most penetrable geography, with BIS certification requirements favoring imported complex inorganic pigments over non-compliant alternatives in Maharashtra and Gujarat highway programs. Technical ceramics for 3D-printed aerospace and medical device components offer white-space volume with lower qualification barriers than automotive OEM approvals. For Investors and Strategic Acquirers: Automotive OEM consolidation of approved supplier lists from twelve-plus vendors to four certified partners is the leading indicator that calcination specialists with backward integration into precursor chemicals will command sustained premium multiples. Long-term viability frames around producers with captive cobalt and titanium oxide supply, REACH-registered dossiers, and electric or hydrogen-fired kiln investments qualifying for EU Green Deal financing. Electric calcination technology adoption in German and Chinese facilities signals inflection toward decarbonization-aligned supplier selection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | BASF SE's captive supply of cobalt and titanium oxides insulates margin from mining volatility. |
| Electric Calcination Technology Deployment | EU Green Deal financing access rewards early movers with preferential OEM sustainability scoring. |
| Long-term Supply Agreement with Automotive OEM | Volkswagen Group and BMW procurement teams mandate dedicated production lines for global color consistency. |
| REACH-Compliant Product Line Expansion | ECHA SVHC substitution deadlines redirect coatings formulation toward engineered mixed-metal oxides. |
| Joint Venture in Indian Import Markets | BIS certification requirements favor compliant complex inorganic pigments in Maharashtra infrastructure absorption. |
Methodological Framework
Independent corroboration across regulatory filings, customs trade data, and coatings industry technical specifications underwrites the qualitative findings in this study. Primary interviews with calcination plant managers, automotive OEM procurement leads, polymer compounding technical directors, and coatings formulator R&D heads combined with secondary validation from ECHA REACH dossiers, EPA TSCA notifications, and SEC 10-K disclosures for diversified chemical conglomerates. Bottom-up capacity assessments across Shandong and Jiangsu production clusters triangulate against top-down demand modeling from automotive production and construction absorption data.
Rate-of-change decomposition across pigment chemistry, application segment, end-use industry, and regional regulatory cluster shapes the analytical framework. Segmentation dimensions modeled include iron oxide versus titanium dioxide versus cobalt-aluminate chemistries, coatings versus plastics versus construction applications, automotive OEM versus aerospace versus consumer goods end-users, and powder versus liquid dispersion formats. CAGRs derive from regression analysis of historical calcination capacity expansion correlated with downstream demand indicators including vehicle production and infrastructure investment flows. Feedstock price volatility in cobalt and titanium oxides and MEE emissions compliance costs constitute industry-specific forecast inputs.
Regulatory timeline acceleration, cobalt supply disruption from mining jurisdictions, and organic pigment substitution velocity in lower-temperature plastics applications are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding sustained automotive OEM consolidation of approved supplier lists and continued Chinese domestic capacity absorption. A model refresh is warranted upon material change in REACH authorization timelines for chromium-based pigments or MEE permitting intensity for coal-fired calcination facilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Global Cosmetic Dyes Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Aluminum Pigments Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Global Thermochromic Materials Market