
 Micro-Irrigation Systems Market | 2026-2036
Micro-Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Irrigation Systems Market Analysis
Pressure-compensating emitter specifications are collapsing the cost gap between commodity drip tape and precision micro-sprinkler installations. Jain Irrigation Systems Ltd. leverages its backward integration into polymer compounding to sustain margin control across India's sugarcane belt. Netafim Ltd. anchors technical credibility through its dominance in subsurface drip deployment for vineyard applications. The Toro Company competes on channel density, occupying positions with landscape contractors across the southwestern United States.
Micro-irrigation systems deliver controlled water and nutrient application through low-pressure networks of emitters, tubing, and filtration units engineered to operate at 10-30 psi with distribution uniformity exceeding 85 percent. These configurations reduce evaporation losses and enable fertigation integration in water-stressed cultivation zones. Drip irrigation leads product type revenue pools due to its maturity in row-crop vegetable systems, while sensor-based technology segments capture expanding replacement cycles as agricultural producers retrofit gravity-fed installations with soil-moisture feedback loops. Sprinkler systems retain structural importance in orchard and greenhouse applications where overhead cooling requirements intersect with irrigation demand.
EPA water efficiency mandates under the Clean Water Act shape product certification requirements for agricultural equipment sold in the United States, while India's BIS standards govern emitter flow-rate consistency for domestic procurement under PLI-linked horticulture programs. The EU Green Deal's Farm to Fork strategy accelerates pressure-compensating technology adoption across Mediterranean member states with deficit irrigation protocols. Stakeholders must monitor regulatory alignment between water-rights administration and equipment subsidy eligibility as a decisive factor in replacement-cycle timing.
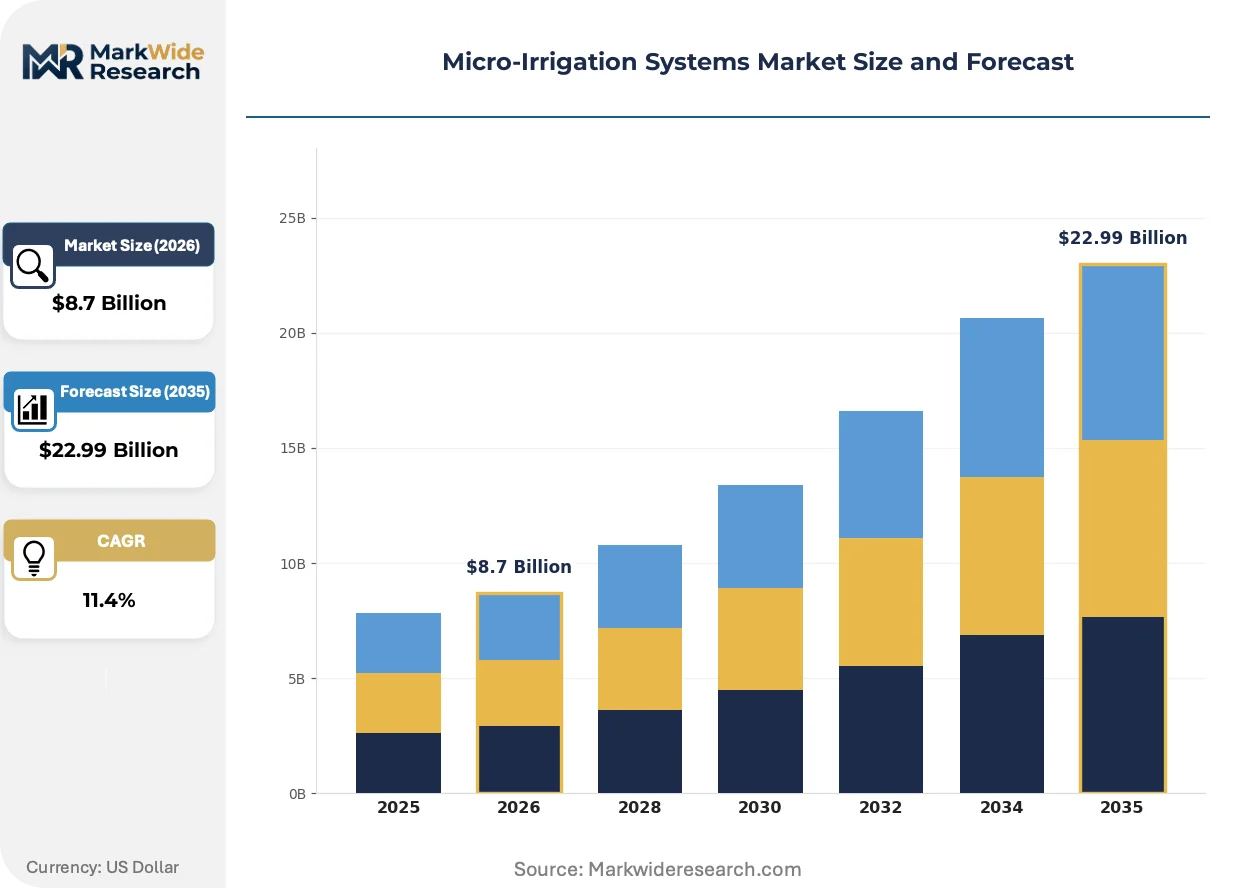
Market Dynamics
Water scarcity mandates across arid agricultural belts are forcing technology substitution faster than capital replacement cycles, compressing the payback period calculus for precision irrigation infrastructure.
Growth Catalysts
- EPA agricultural water efficiency guidelines:California's Central Valley specialty crop growers are accelerating drip retrofit programs to maintain water rights allocations under tightening federal oversight.
- Pressure-compensating emitter specifications:These technical standards collapse the installed-cost gap between commodity drip tape and precision micro-sprinkler systems across vineyard applications.
- India's PLI-linked horticulture programs:Domestic procurement incentives tied to BIS flow-rate consistency standards are channeling subsidy eligibility toward certified equipment manufacturers.
Market Restraints
- Polymer resin input volatility:Backward-integrated manufacturers maintain margin control while non-integrated suppliers face working capital compression during petrochemical price spikes.
- Emitter clogging from unfiltered water sources:Technical limitations in surface-water-fed installations require capital-intensive filtration infrastructure that extends project timelines.
- EU F-Gas Regulation compliance costs:Greenhouse cooling-irrigation hybrid systems face refrigerant containment retrofit requirements that inflate total installation expenditure.
Strategic Opportunities
- Subsurface drip deployment in vineyard applications:Arid-zone horticulture clusters in Israel and Australia present underpenetrated demand for root-zone moisture management systems.
- Soil-moisture feedback loop integration:Sensor-based technology segments capture replacement cycles as gravity-fed installations retrofit with telemetry-enabled automation.
- EU Green Deal Farm to Fork strategy:Deficit irrigation protocols across Mediterranean member states create regulatory tailwind for pressure-compensating technology certification.
Industry Challenges
- Fertigation chemistry certification timelines:Agricultural producers face extended compliance validation for nutrient-injection compatibility with polymer tubing formulations.
- Legacy gravity-fed system integration:Retrofit projects encounter hydraulic pressure mismatches when connecting low-pressure micro-irrigation networks to existing canal infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Irrigation Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Soaker Hoses, Micro Sprinklers Application: Fruits, Vegetables, Ornamental Plants, Greenhouses End User: Agricultural Producers, Commercial Growers, Hobbyists, Landscape Contractors Technology: Sensor-Based, Automated Systems, Gravity-Fed, Pressure Compensating |
| Companies Covered | Jain Irrigation Systems Ltd., The Toro Company, Netafim Ltd., Rain Bird Corporation, Lindsay Corporation, Rivulis Irrigation Ltd., Hunter Industries, Nelson Irrigation Corporation, T-L Irrigation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Irrigation Systems Market Emerging Trajectories
Digital automation layers are grafting onto mechanical irrigation infrastructure faster than original equipment design cycles anticipated, creating interoperability gaps that favor modular retrofit architectures over proprietary closed systems.
Pressure-compensating drip tape technology is decomposing the traditional segmentation between row-crop vegetable systems and permanent orchard installations. California almond growers are adopting these emitters at replacement-cycle velocity previously reserved for high-value vineyard applications. The technology is decomposing the premium pricing hierarchy that separated commodity agriculture from precision horticulture.
The EU Green Deal's Farm to Fork strategy is accelerating deficit irrigation protocol adoption across Mediterranean member states. Spanish and Italian olive cooperatives must demonstrate water-use efficiency metrics to maintain export certification under EFSA sustainability disclosure requirements. Pressure-compensating emitter specifications are becoming de facto procurement prerequisites for subsidized equipment programs.
Landscape contractors across the southwestern United States are unbundling after-sales service from equipment procurement, creating standalone maintenance subscription revenue streams. Toro Company's channel density positions it to capture recurring revenue from sensor calibration and emitter replacement cycles. This service unbundling is most visible in Arizona and Nevada municipal turf management contracts where water-budget compliance reporting has become a standalone deliverable.
Micro-Irrigation Systems Market Segmentation
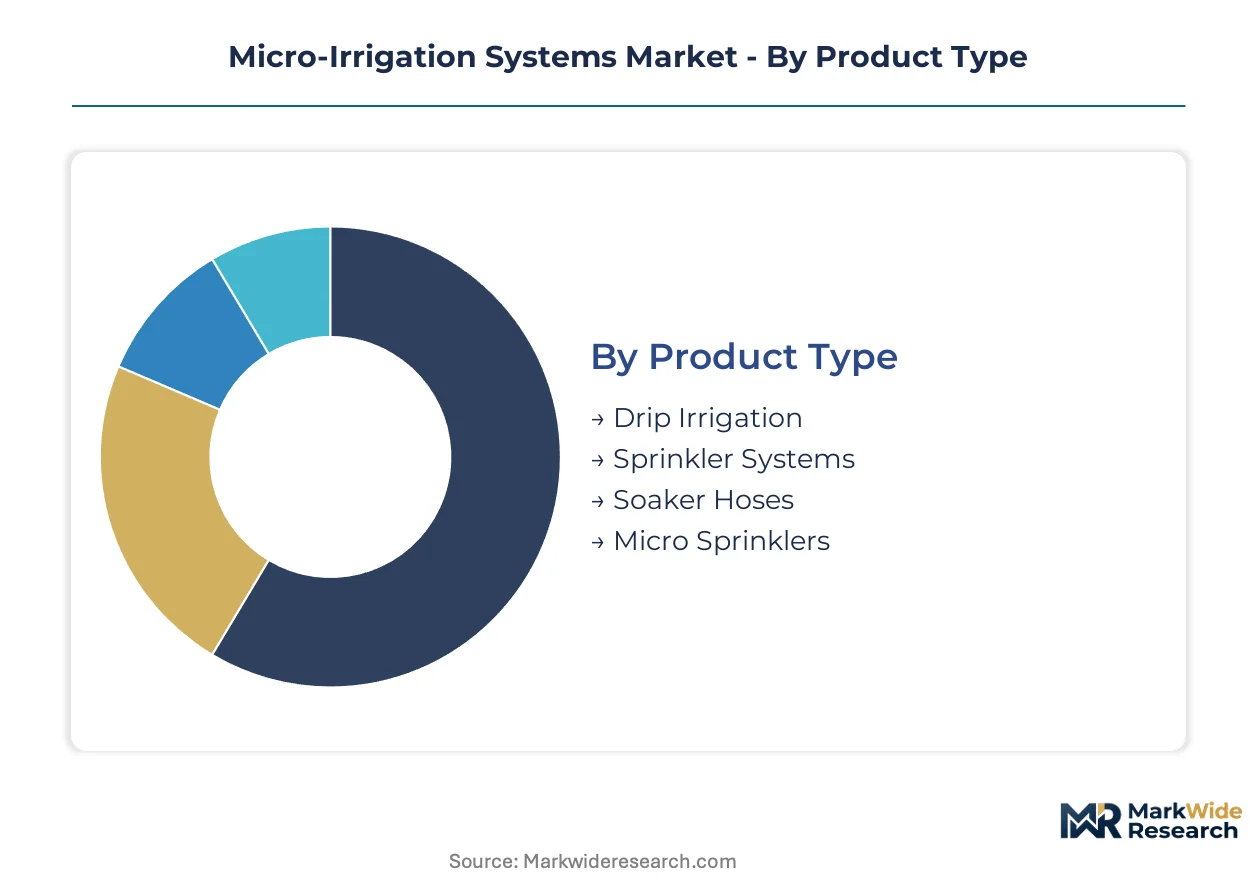
Segmentation in micro-irrigation systems reveals how technology maturity, crop economics, and water scarcity intensity create divergent margin structures across installation types. Product and application categories stratify sharply between commodity row-crop equipment and precision horticulture infrastructure.
Product Type:
Margin pools concentrate in pressure-compensating configurations where technical differentiation sustains pricing power against commodity drip tape alternatives.
- Drip Irrigation:Networks of polyethylene tubing with integrated emitters deliver water directly to root zones at 10-20 psi operating pressure. California almond growers and Indian sugarcane cooperatives anchor volume demand as EPA water efficiency guidelines and India's PLI-linked horticulture programs accelerate replacement of flood irrigation. Drip irrigation holds installed capacity. Pressure-compensating variants are rotating up the share rankings.
- Sprinkler Systems:Overhead distribution equipment operates at 30-50 psi with rotating or fixed spray patterns suited to orchard cooling and greenhouse humidity management. Spanish olive cooperatives under EU Green Deal Farm to Fork protocols drive specification upgrades toward uniform distribution uniformity metrics. Micro sprinklers capture the fastest-expanding trajectory among precision horticulture clusters in Israel and Australia.
- Soaker Hoses:Porous-wall tubing releases water through capillary seepage along entire length, serving ornamental and small-scale vegetable applications where capital constraints limit emitter-based infrastructure investment.
- Micro Sprinklers:Low-pressure rotary or static emitters project water 2-8 feet radius, bridging drip precision with sprinkler coverage for tree crops and greenhouse bench irrigation.
Drip infrastructure commands the replacement cycle velocity in arid-zone agricultural belts. Micro sprinkler specifications are climbing fastest in permanent crop installations.
Application:
Revenue concentration tracks crop water sensitivity and export certification requirements, with high-value horticulture commanding premium equipment specifications.
- Fruits:Vineyard and orchard applications demand subsurface drip and pressure-compensating micro-sprinkler systems for deficit irrigation protocols. Australian table grape producers and Israeli pomegranate growers specify root-zone moisture management to maintain export phytosanitary compliance.
- Vegetables:Row-crop tomato, pepper, and leafy green systems deploy surface drip tape with high emitter density for short-cycle cultivation. California Central Valley specialty crop growers retrofit gravity-fed installations with sensor-based automation to secure water rights allocations under tightening EPA oversight.
- Ornamental Plants:Nursery and floriculture operations require overhead cooling-irrigation hybrid systems with fine mist capability for humidity control and foliar feeding integration.
- Greenhouses:Controlled environment agriculture combines drip or micro-sprinkler distribution with fertigation chemistry and climate control, subject to EU F-Gas Regulation compliance costs for refrigerant-containing cooling systems.
Vegetable applications anchor unit volume throughput. Fruit sector specifications are rotating up the margin rankings.
End User:
Procurement patterns diverge between price-sensitive agricultural volume buyers and service-attached commercial operators seeking compliance documentation.
- Agricultural Producers:Farm-scale operators prioritize capital efficiency and subsidy eligibility, driving demand toward BIS-certified equipment in India and EPA-compliant configurations in the United States. India's sugarcane belt procurement concentrates among backward-integrated domestic manufacturers.
- Commercial Growers:Export-oriented horticulture enterprises specify pressure-compensating technology with telemetry integration to satisfy EFSA sustainability disclosure requirements and water-budget compliance reporting.
- Hobbyists:Residential and small-holding users purchase soaker hose and basic drip kit configurations through retail channels, representing price-sensitive demand with minimal service attachment.
- Landscape Contractors:Southwestern United States municipal turf management contracts unbundle equipment procurement from maintenance subscriptions, creating recurring revenue streams for sensor calibration and emitter replacement cycles.
Agricultural producers maintain installed base dominance. Commercial grower specifications are rotating up the technology adoption curve.
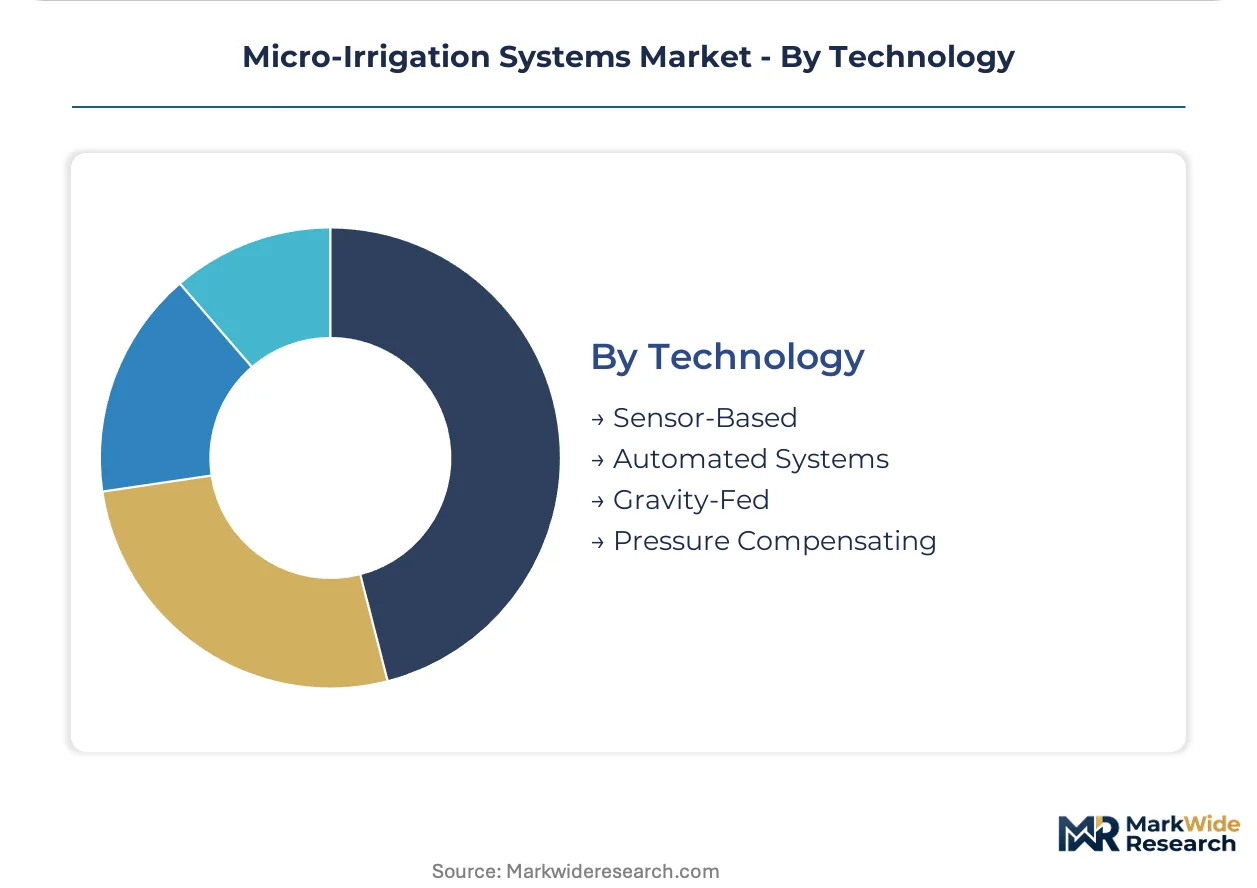
Technology:
Value capture shifts toward digital automation layers as retrofit architectures displace proprietary closed systems in replacement-cycle timing.
- Sensor-Based:Soil-moisture, weather, and crop-stress telemetry enable closed-loop irrigation scheduling with cloud-based analytics. California Central Valley almond growers deploy these systems to demonstrate water-use efficiency for rights administration compliance.
- Automated Systems:Valve controllers, pump stations, and fertigation injectors integrate with farm management software for unattended operation. Mediterranean olive cooperatives adopt automation to meet EU Green Deal deficit irrigation protocol documentation requirements.
- Gravity-Fed:Low-head surface water distribution without pressurization remains prevalent in South Asian smallholder systems, though retrofit pressure-compensating upgrades accelerate under subsidy programs.
- Pressure Compensating:Emitter designs maintain constant flow across elevation and pressure variations, collapsing the cost gap between commodity drip tape and precision micro-sprinkler installations in vineyard and orchard applications.
Pressure-compensating hardware holds installed capacity. Sensor-based automation is rotating up the replacement-cycle priority rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented horticulture belts in Israel and Australia generate trade surpluses in precision irrigation equipment, while import dependency characterizes emerging agricultural economies retrofitting gravity-fed infrastructure with pressure-compensating technology.
United States
California's Central Valley specialty crop growers anchor North American demand as EPA agricultural water efficiency guidelines tighten water rights allocations. The state's almond cooperatives retrofit flood irrigation with subsurface drip networks to maintain federal compliance documentation. Fresno and Kern counties concentrate deployment of sensor-based automation for groundwater sustainability reporting.
Israel
Arid-zone horticulture clusters drive technology substitution faster than capital replacement cycles across the Negev and Galilee regions. Netafim Ltd. anchors technical credibility through subsurface drip dominance in vineyard applications. The country's national water regulator mandates distribution uniformity standards that accelerate pressure-compensating emitter certification for export markets.
India
Maharashtra and Gujarat sugarcane cooperatives channel procurement toward BIS-certified equipment under PLI-linked horticulture programs. Jain Irrigation Systems Ltd. leverages backward integration into polymer compounding to sustain margin control across the Deccan Plateau. The central government's subsidy eligibility rules tighten emitter flow-rate consistency requirements for domestic manufacturers.
Australia
Murray-Darling Basin table grape producers specify root-zone moisture management to maintain export phytosanitary compliance with Asian markets. Victoria and South Australia irrigation districts retrofit canal infrastructure with low-pressure micro-sprinkler networks. The country's national agricultural regulator ties water license renewals to documented distribution uniformity metrics.
Spain
Andalusian and Catalonian olive cooperatives adopt deficit irrigation protocols under EU Green Deal Farm to Fork sustainability disclosure requirements. Pressure-compensating specifications become de facto procurement prerequisites for subsidized equipment programs. Seville and Granada provinces concentrate micro-sprinkler deployment for overhead cooling in high-density olive orchards.
Micro-Irrigation Systems Market Vendor Landscape
Concentration sits with vertically integrated polymer compounders and precision emitter specialists rather than diversified industrial conglomerates. The vendor base stratifies across three tiers: irrigation-focused multinationals with channel density in arid-zone agricultural belts, regional fabricators serving subsidy-linked domestic procurement, and digital automation layer providers retrofitting legacy mechanical infrastructure. Competitive moves center on backward integration into polymer resin supply and geographic expansion through distributor acquisition in water-stressed cultivation zones.
Within the precision horticulture tier, Netafim Ltd. and Jain Irrigation Systems Ltd. exemplify divergent strategic archetypes. Netafim represents the technology-origin specialist anchoring technical credibility through subsurface drip deployment. Jain Irrigation occupies the integrated-manufacturer position leveraging captive polymer supply chains. The Toro Company sits within the channel-density archetype, occupying positions with landscape contractors across the southwestern United States. Rivulis Irrigation Ltd. and Lindsay Corporation represent mid-scale specialists competing on regional service attachment rather than global manufacturing scale.
| Leading Market Players |
|---|
| Jain Irrigation Systems Ltd. |
| The Toro Company |
| Netafim Ltd. |
| Rain Bird Corporation |
| Lindsay Corporation |
| Rivulis Irrigation Ltd. |
| Hunter Industries |
| Nelson Irrigation Corporation |
| T-L Irrigation |
| Others |
Supply Flow & Price Mechanics
EPA agricultural water efficiency guidelines gate both supplier qualification and price differentiation across the North American micro-irrigation equipment market. California Central Valley almond cooperatives face dual compliance burdens—certification documentation for water rights retention and premium specifications for sensor-based automation—creating tiered procurement thresholds that separate subsidy-eligible domestic manufacturers from precision technology specialists.
Pricing Analysis
Agricultural producers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on BIS flow-rate consistency certification and telemetry integration depth. Cost compression in commodity drip tape is intensifying because Indian sugarcane cooperatives consolidate procurement under PLI-linked programs. Hobbyist retail channels exhibit highest price sensitivity; commercial growers with EFSA sustainability disclosure mandates show lowest.
Supply Chain Analysis
Inventory cycles stretch 8-14 weeks for pressure-compensating emitters as polymer resin feedstock volatility disrupts compounding schedules. Manufacturing concentrates in Israel, India, and the United States. Raw material dependencies center on polyethylene resin, EPDM rubber seals, and precision-molded ceramic emitters. Single-source vulnerability characterizes advanced emitter membrane formulations. Distribution runs through irrigation-specialist dealers and landscape contractor networks rather than general agricultural retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor calibration and emitter replacement subscriptions expand faster than hardware sales across southwestern United States municipal turf contracts. Toro Company's channel density positions demonstrate how unbundled after-sales service layers capture recurring revenue from water-budget compliance reporting.
For Market Incumbents: Shield margin pools in subsurface drip deployment through captive polymer compounding capacity against emerging digital automation specialists. Jain Irrigation's backward integration into Maharashtra polymer plants exemplifies defensive positioning. Invest in BIS certification maintenance as India's central government tightens flow-rate consistency eligibility rules for subsidy programs. For New Entrants and Emerging Players: Differentiate on soil-moisture telemetry integration for Australian Murray-Darling Basin table grape producers facing export phytosanitary compliance mandates. Target vineyard retrofit cycles in Israel's Negev region where Netafim's technical credibility creates pricing umbrella opportunities. Pursue direct partnerships with Spanish olive cooperatives under EU Green Deal deficit irrigation protocols rather than equipment-only sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sensor-based automation segments as modular retrofit architectures displace proprietary closed systems. Five-to-ten year viability favors mid-scale regional specialists with service attachment depth over pure manufacturing scale. Monitor EPA water rights allocation enforcement intensity as inflection indicator for North American replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Jain Irrigation's captive resin supply secures margin control against petrochemical price spikes. |
| Sensor-Based Automation Platform Launch | California almond growers deploy telemetry-enabled scheduling for groundwater sustainability reporting. |
| Regional Distributor Acquisition | Channel density in Arizona-Nevada municipal turf captures unbundled maintenance subscription revenue. |
| BIS Certification Investment | Indian domestic manufacturers secure PLI-linked horticulture program eligibility. |
| Subsurface Drip Technology Licensing | Israeli vineyard expertise transfers to Australian arid-zone horticulture clusters. |
Methodological Framework
The analysis maps drip irrigation, sprinkler systems, micro-sprinklers, and sensor-based automation segments, each validated through irrigation equipment procurement managers, agricultural cooperative technical directors, landscape contractor operations heads, and polymer compounding plant engineers. Primary interviews combined with secondary validation from EPA agricultural water efficiency guideline documentation, India's BIS flow-rate standards, EU Green Deal Farm to Fork strategy disclosures, and customs trade data for polyethylene tubing imports. Bottom-up equipment shipment analysis triangulated against top-down agricultural water rights expenditure estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, application crop category, end-user procurement archetype, and technology automation level. CAGRs derived from replacement cycle timing analysis, subsidy program budget trajectories, and water scarcity mandate enforcement intensity. Industry-specific inputs included distribution uniformity certification penetration rates and gravity-fed retrofit project pipelines.
The analysis sits within stated boundaries; outcomes outside sustained EPA guideline enforcement or PLI program continuity would require recalibration. Forecasts reflect documented assumptions regarding polymer resin price trajectories and emitter clogging mitigation technology advancement. Drought severity cycles and export certification rule changes represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Smart Farm Management Software Market