
 Smart Irrigation Software Market | 2026-2036
Smart Irrigation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Irrigation Software Market Insights
Software-hardware bundling is hardening as the dominant procurement pattern, with platform providers wrapping sensors, controllers, and analytics into unified subscriptions. Rain Bird Corporation leverages its controller manufacturing heritage to anchor bundled offerings for golf course operators. Netafim competes through drip irrigation specialization that extends into software-layer water optimization. Rachio differentiates via homeowner-focused mobile interfaces that simplify zone-based scheduling.
Smart irrigation software encompasses algorithms, sensor interfaces, and cloud platforms that automate water delivery based on soil moisture, weather forecasts, and evapotranspiration models, typically operating through IoT-connected valve controllers with sub-hourly data refresh rates. Cloud-based deployment leads in new installations due to lower upfront infrastructure requirements and centralized fleet management for agricultural producers. AI-driven analytics represents the fastest-expanding technology segment, as machine learning models improve yield-per-gallon predictions and reduce over-irrigation penalties.
EPA WaterSense certification shapes product eligibility for federal rebate programs, while state regulators in California enforce Model Water Efficient Landscape Ordinance compliance for new commercial developments. USDA conservation programs channel cost-share funding toward sensor network adoption among row-crop farmers. Stakeholders must monitor how groundwater sustainability agencies translate cutback mandates into enforceable software-based monitoring requirements.
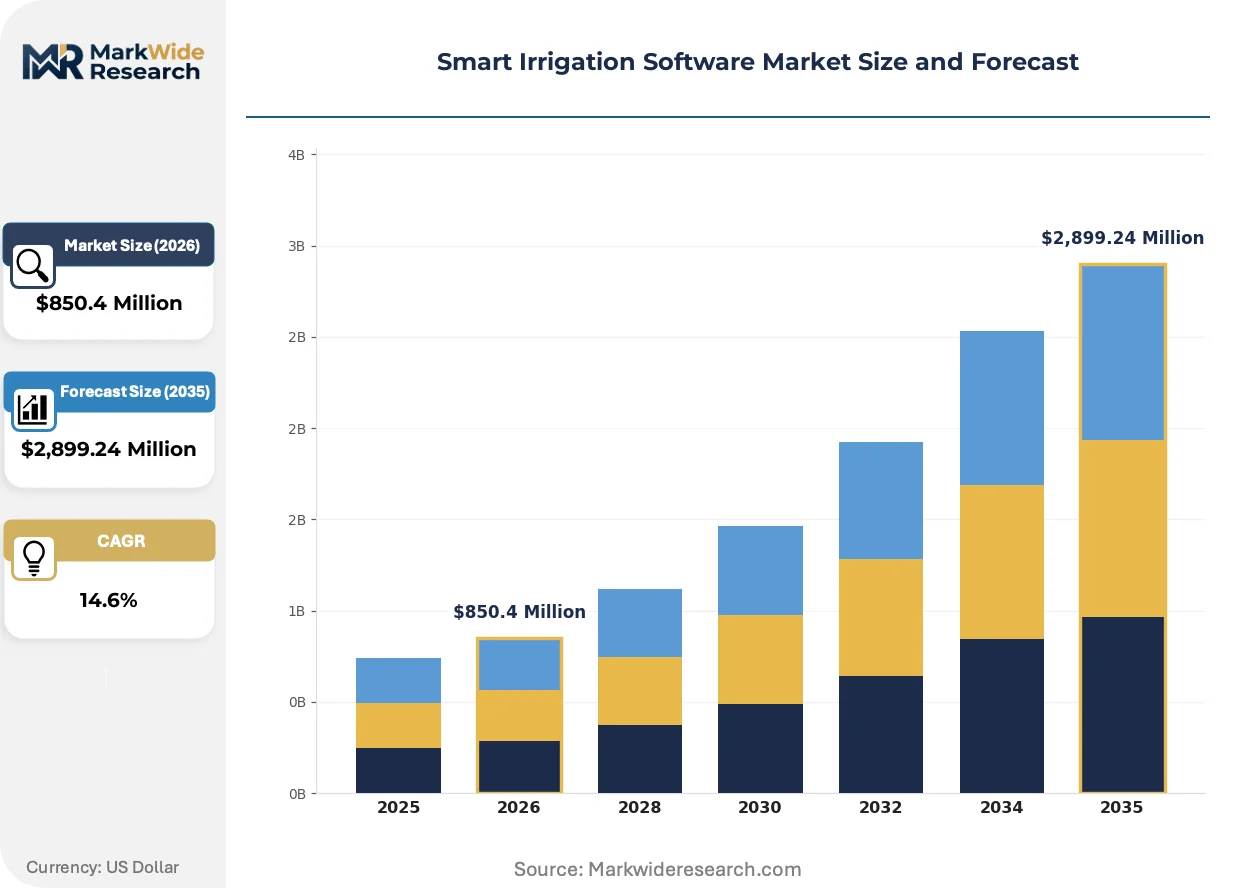
Market Dynamics
Software-hardware bundling is hardening procurement patterns across agricultural and commercial landscape sectors, with platform providers wrapping sensors, controllers, and analytics into unified subscriptions that lock in recurring revenue streams.
Growth Catalysts
- EPA WaterSense certification:Federal rebate eligibility hinges on this designation, channeling USDA conservation program funding toward sensor network adoption among row-crop farmers.
- California's Model Water Efficient Landscape Ordinance:State regulators enforce compliance for new commercial developments, mandating software-based monitoring systems in ground-up construction.
- Drip irrigation specialization:Precision water delivery hardware paired with optimization algorithms reduces over-irrigation penalties in drought-severity corridors.
Market Restraints
- Controller hardware cost volatility:Semiconductor supply concentration in East Asian foundries creates input price instability for valve actuation components.
- Rural connectivity gaps:Sub-hourly data refresh requirements strain cellular and LoRaWAN infrastructure in remote agricultural zones.
- Manual irrigation substitution:Low-cost timer-based systems retain share among price-sensitive residential installers in non-restricted water districts.
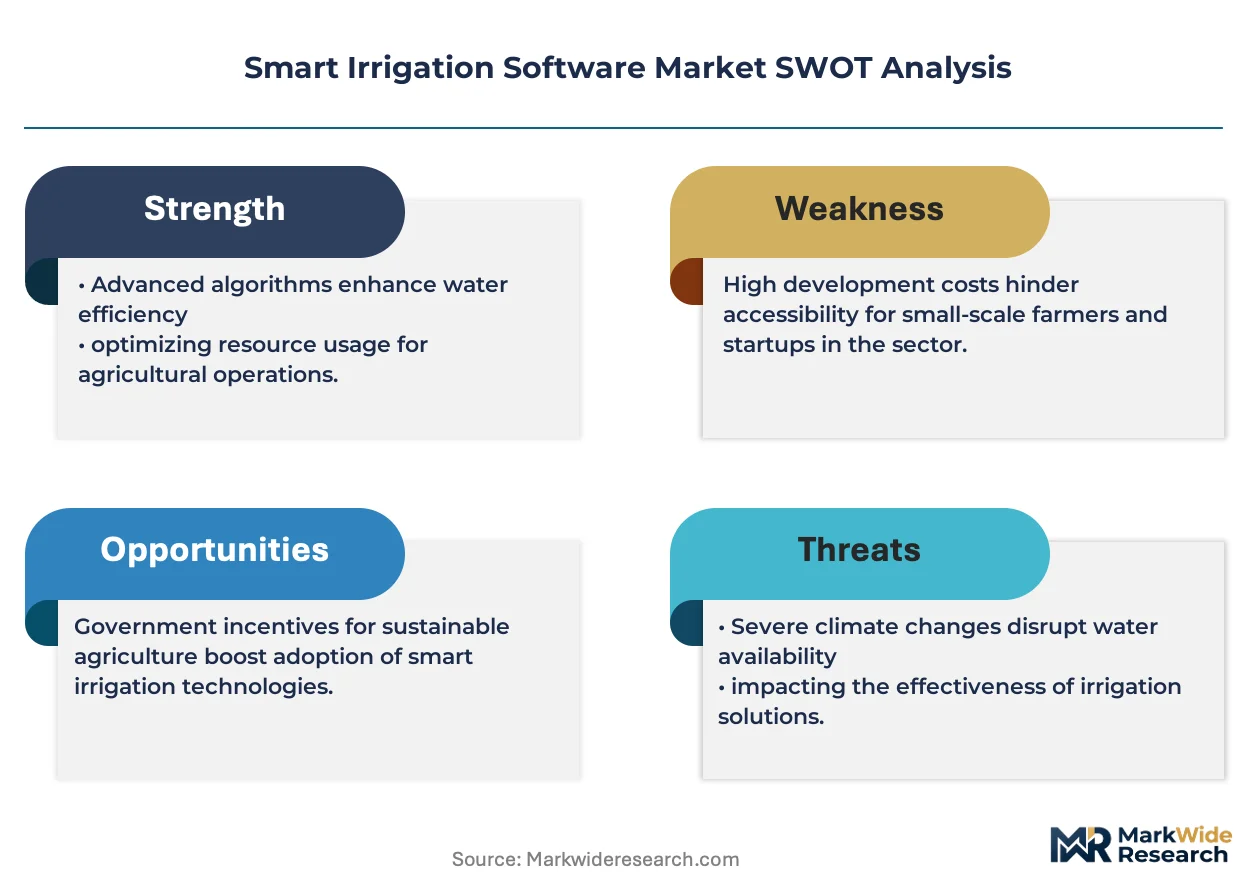
Strategic Opportunities
- Groundwater sustainability agencies:California's GSAs are translating cutback mandates into enforceable software-based monitoring requirements, creating compliance-driven demand.
- AI-driven analytics convergence:Machine learning models combined with evapotranspiration data streams improve yield-per-gallon predictions for specialty crop producers.
- Cloud-based deployment channels:Lower upfront infrastructure requirements open centralized fleet management to mid-scale agricultural producers previously priced out.
Industry Challenges
- Agronomic data science talent scarcity:Shortage of professionals bridging soil science, hydrology, and software engineering slows algorithm refinement cycles.
- Legacy controller integration friction:Retrofitting two-wire decoder systems with IoT modules requires specialized electrical expertise that installer networks lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Irrigation Software Market |
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $2,899.24 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Sensor Networks, Control Software Technology: Cloud-Based, IoT Solutions, AI-Driven Analytics, Mobile Applications End User: Agricultural Producers, Landscape Managers, Homeowners, Golf Courses Deployment: On-Premises, SaaS, Hybrid, Remote |
| Companies Covered | Rain Bird Corporation, The Toro Company, Hunter Industries, Netafim, HydroPoint Data Systems, Rachio, Galcon, Weathermatic, Jain Irrigation Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Irrigation Software Market Trends and Innovations
Machine learning inference at the edge is compressing decision latency for water delivery systems, while regulatory pressure on groundwater extraction accelerates telemetry deployment across agricultural basins.
Edge-deployed AI models processing soil moisture and weather data locally are overtaking cloud-only architectures for latency-critical valve actuation decisions. Large-scale vineyard operators in California's Central Valley are adopting these systems to sub-minute irrigation triggers during frost events. The shift is overtaking traditional polling-interval cloud updates that risk crop damage during rapid temperature swings.
California's Sustainable Groundwater Management Act implementation deadlines are forcing agricultural water districts to install real-time extraction monitoring. The state's Department of Water Resources requires sub-daily reporting from high-priority basins, compelling software platform upgrades. Specialty nut growers in the San Joaquin Valley are responding fastest, deploying sensor networks ahead of 2025 compliance checkpoints.
Subscription-based fleet management is replacing perpetual license sales for multi-site agricultural operators. Platform providers now bundle hardware, cellular connectivity, and algorithm updates into per-acre annual fees. This model concentrates among almond and pistachio cooperatives managing dispersed orchards across Kern and Fresno counties.
Smart Irrigation Software Market Segmentation
Smart irrigation software vendors structure product portfolios around water delivery hardware compatibility, data processing architecture, and customer operational scale. Segmentation clarity determines pricing architecture and channel strategy across agricultural, commercial landscape, and residential verticals.
Product Type:
Volume concentration sits with drip irrigation and sprinkler hardware-software bundles, while sensor networks command premium pricing for precision agriculture deployments.
- Drip Irrigation:Pressure-compensating emitters paired with flow-monitoring algorithms deliver water directly to root zones. California nut growers in the San Joaquin Valley dominate procurement, driven by groundwater sustainability agency mandates for measurable application efficiency.
- Sensor Networks:Soil moisture probes, weather stations, and telemetry gateways feed real-time data streams to optimization platforms. Specialty crop producers in water-stressed basins concentrate investment here, seeking sub-hourly irrigation triggers to avoid yield penalties from over- or under-watering.
- Sprinkler Systems:Rotor and spray head controllers with zone-based scheduling dominate turf management and row-crop applications.
- Control Software:Centralized platform layers unify valve actuation, data visualization, and compliance reporting across heterogeneous hardware estates.
Mature deployment sits with sprinkler systems. Newer deployment is concentrated in sensor networks.
Technology:
Cloud infrastructure underpins new agricultural installations, while edge AI gains traction where connectivity constraints or latency requirements demand local processing.
- Cloud-Based:Centralized data lakes and algorithm updates delivered via subscription eliminate on-site server maintenance. Mid-scale agricultural producers across the Central Valley favor this model for fleet management of dispersed orchards without capital-intensive infrastructure.
- AI-Driven Analytics:Machine learning models trained on evapotranspiration datasets and yield histories refine water application recommendations. Vineyard operators in frost-prone corridors deploy these systems for sub-minute irrigation decisions that cloud-only architectures cannot support.
- IoT Solutions:LoRaWAN and cellular-connected valve controllers enable remote actuation across large geographic footprints.
- Mobile Applications:Smartphone interfaces for zone scheduling and alert management dominate residential and small commercial installations.
Established deployment sits with IoT connectivity layers. Steepest expansion trajectory is found in AI-driven analytics.
End User:
Customer type determines feature complexity, with agricultural producers requiring compliance integration and homeowners prioritizing interface simplicity.
- Agricultural Producers:Row-crop and specialty crop operations demand groundwater extraction monitoring, USDA conservation program eligibility tracking, and multi-site fleet dashboards. California's Sustainable Groundwater Management Act deadlines are accelerating software procurement among almond and pistachio cooperatives.
- Golf Courses:Turf managers require precise moisture control across heterogeneous playing surfaces with minimal labor input. Rain Bird's bundled controller-software offerings anchor this segment through established superintendent relationships.
- Landscape Managers:Commercial grounds maintenance contractors seek centralized oversight of dispersed municipal and corporate properties.
- Homeowners:Residential users prioritize mobile-first zone scheduling with minimal configuration overhead.
Deeply penetrated deployment sits with golf courses. Emerging deployment is concentrated in agricultural producers.
Deployment:
Subscription models are displacing perpetual licenses as vendors pursue recurring revenue and customers seek lower upfront capital commitment.
- SaaS:Per-acre annual fees bundling hardware, connectivity, and algorithm updates eliminate capital expenditure barriers. Almond cooperatives across Kern and Fresno counties have standardized on this model for orchard network management.
- Hybrid:Local edge processing for latency-critical valve actuation combined with cloud-based analytics and reporting addresses connectivity gaps in remote agricultural zones.
- On-Premises:Self-hosted servers retain niche presence among operators with stringent data sovereignty requirements or unreliable internet infrastructure.
- Remote:Fully cloud-dependent architectures suit well-connected urban and suburban landscape installations.
Legacy deployment sits with on-premises installations. Gaining share fastest is hybrid architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of smart irrigation software concentrates in the United States and Israel, while consumption spreads across water-stressed agricultural regions worldwide. The United States generates the majority of platform development and controller hardware integration. Demand clusters in jurisdictions with binding groundwater restrictions and federal conservation incentives.
United States
EPA WaterSense certification drives procurement eligibility for federal rebate programs across commercial landscape and agricultural installations. California's Sustainable Groundwater Management Act mandates real-time extraction monitoring in high-priority basins, compelling software upgrades among Central Valley nut growers. Almond and pistachio cooperatives across Kern and Fresno counties deploy sensor networks ahead of 2025 compliance deadlines.
Israel
Drip irrigation heritage creates natural software-hardware bundling advantages for precision agriculture exports. National water efficiency standards enforced by the Israel Water Authority shape product development roadmaps for global markets. Netafim and Galcon anchor development clusters around Kibbutz Hatzerim and Caesarea, shipping bundled optimization platforms to drought-affected regions.
Australia
Murray-Darling Basin water buyback programs and extraction caps accelerate telemetry adoption among irrigated cotton and rice producers. The Bureau of Meteorology's water data services integrate with private platforms, standardizing evapotranspiration modeling inputs. Victorian and New South Wales almond orchards lead sensor network deployment in response to basin plan enforcement.
Spain
EU Common Agricultural Policy cross-compliance requirements channel funding toward efficient irrigation modernization in water-stressed southern regions. Andalusian olive and citrus cooperatives face tightening Guadalquivir basin extraction permits, driving software procurement for deficit irrigation scheduling. Seville-based agricultural technology clusters specialize in vineyard and orchard optimization platforms.
India
Pradhan Mantri Krishi Sinchayee Yojana subsidies reduce capital barriers for drip and sprinkler automation among smallholder farmers. State-level groundwater acts in Maharashtra and Gujarat mandate metering for agricultural tubewells, creating compliance-driven demand. Gujarat's Saurashtra region concentrates early adoption among cotton and groundnut cooperatives managing dispersed holdings.
Smart Irrigation Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware-software bundling and standalone analytics segments. Market structure tilts toward consolidation among agricultural producers seeking unified fleet management, while residential and small commercial segments retain fragmentation. Three archetypes dominate: controller manufacturers extending into software layers, drip irrigation specialists adding optimization algorithms, and cloud-native platforms targeting subscription revenue. Competitive moves center on strategic partnerships with sensor manufacturers and geographic expansion through distributor networks.
Within the controller-heritage tier, Rain Bird Corporation and The Toro Company exemplify hardware-anchored bundling strategies. Netafim occupies a specialist position rooted in drip irrigation engineering. Rachio represents the cloud-native archetype targeting residential simplicity. Hunter Industries and HydroPoint Data Systems sit within the mid-market commercial landscape segment. Jain Irrigation Systems anchors an emerging-market diversification play spanning equipment manufacturing and software integration.
| Leading Market Players |
|---|
| Rain Bird Corporation |
| The Toro Company |
| Hunter Industries |
| Netafim |
| HydroPoint Data Systems |
| Rachio |
| Galcon |
| Weathermatic |
| Jain Irrigation Systems |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with multi-generational controller manufacturing legacies anchor supply-side discipline, translating captive valve-actuation capabilities into pricing power that resists commoditization pressures from cloud-native entrants. Their ownership structure insulates pricing decisions from quarterly earnings pressure, enabling sustained investment in EPA WaterSense certification tiers that command federal rebate eligibility premiums.
Pricing Analysis
Margin tightening in hardware-software bundles reflects semiconductor input volatility concentrated in East Asian foundries. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels segments buyer willingness-to-pay, with USDA conservation program eligibility driving tier selection. Cost compression accelerates as cellular connectivity commoditizes, squeezing recurring revenue yields. Residential installers in non-restricted water districts exhibit highest price sensitivity, while California nut cooperatives facing groundwater sustainability agency mandates demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in India's Pradhan Mantri Krishi Sinchayee Yojana and Australia's Murray-Darling Basin procurement rules are reshaping sourcing patterns for telemetry hardware. Controller assembly concentrates in China, Israel, and the United States, with pressure-compensating emitter manufacturing anchored in Israel and drip line extrusion feeding from China. Semiconductor dependencies for valve actuation modules and LoRaWAN radio chips create single-source vulnerability exposure. Distribution runs through agricultural equipment dealers and irrigation specialty distributors with certified installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where California's Sustainable Groundwater Management Act creates a barrier-to-entry moat. Enforcement deadlines for sub-daily extraction reporting force software procurement, advantaging vendors with pre-certified telemetry platforms.
For Market Incumbents: Deploy backward integration into sensor manufacturing to secure supply continuity against semiconductor allocation constraints. Consolidate installer certification programs to lock channel access before emerging cloud-native platforms achieve EPA WaterSense accreditation. Threat substitution from low-cost timer-based systems in unrestricted districts demands proactive bundling of compliance reporting to demonstrate value capture. For New Entrants and Emerging Players: The mid-market gap between Rain Bird's premium bundled offerings and Rachio's economy residential interfaces presents white-space opportunity. Target agricultural producers in Australia's Victorian almond corridor where Bureau of Meteorology data integration requirements favor modular platform architectures. Go-to-market through cooperative procurement channels bypasses entrenched superintendent relationships dominating golf course verticals. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated specialists with captive drip irrigation manufacturing in Israel and California. Long-term viability hinges on groundwater regulation propagation beyond California to Arizona and Texas agricultural basins. Signal to monitor: EPA expansion of WaterSense certification to include AI-driven analytics tiers, which would accelerate platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-Software Bundling | Rain Bird leverages controller heritage to anchor unified subscriptions for golf course operators. |
| Edge AI Deployment | Vineyard operators in frost-prone California corridors adopt sub-minute irrigation triggers. |
| Regulatory Compliance Integration | California's GSAs translate cutback mandates into enforceable software-based monitoring requirements. |
| Subscription Fleet Management | Almond cooperatives across Kern and Fresno counties standardize on per-acre annual fee models. |
| Sensor Network Expansion | Specialty nut growers deploy telemetry ahead of Sustainable Groundwater Management Act deadlines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across platform engineering directors, agricultural cooperative procurement managers, EPA WaterSense certification officers, and irrigation equipment distributor principals. Secondary sources included USDA conservation program databases, California Department of Water Resources extraction reports, Israel Water Authority efficiency standards, and Bureau of Meteorology evapotranspiration datasets. Bottom-up segment sizing and top-down market reconciliation validated volume estimates.
Data-stream reconciliation across deployment model, end-user scale, technology architecture, and regional regulatory intensity shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro water stress indicators. Forecast inputs incorporated groundwater sustainability agency mandate timelines, semiconductor supply lead time assumptions, and cellular connectivity penetration curves across agricultural zones.
Inputs from EPA and state regulatory databases were available through the study window; gaps in real-time GSA enforcement variance introduce uncertainty bands around compliance-driven demand timing. Forecasts reflect documented assumptions regarding regulatory propagation and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Irrigation Controllers Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Agriculture Technology Market