
 Global Drip Emitters Market | 2026-2036
Global Drip Emitters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drip Emitters Market Analysis
Premium-grade emitter specifications with enhanced clogging resistance and uniform discharge coefficients is redrawing competitive boundaries across the Global Drip Emitters Market. Netafim Limited leverages its integrated disc-filter and emitter manufacturing to sustain technology leadership in pressure-compensating designs. Jain Irrigation Systems Ltd. anchors its position through backward integration into polymer compounding and precision molding operations. Chinadrip Irrigation Equipment (Xiamen) Co., Ltd. competes aggressively on manufacturing scale while extending distribution reach across Southeast Asian plantation agriculture.
Drip emitters are precision fluid-delivery devices constructed from UV-stabilized polyethylene or polypropylene, incorporating labyrinth flow paths or diaphragm mechanisms to regulate water discharge at pressures typically between 10 and 50 psi for targeted root-zone irrigation. The primary commercial purpose is to minimize evaporative losses and nutrient leaching in high-value crop production systems. Pressure compensating emitters command the strongest margin pools due to their technical complexity and performance advantages on undulating terrain, while flat emitters dominate volume in cost-sensitive row-crop applications. Agriculture absorbs the largest share of unit demand, though greenhouse installations generate superior per-hectare emitter density and replacement frequency.
The EPA's WaterSense program and the EU F-Gas Regulation's indirect pressure on water-intensive cooling alternatives are tightening performance certification requirements for irrigation equipment in North America and Europe. India's BIS quality standards and China's GB/T irrigation norms are raising import barriers and accelerating domestic manufacturing investment. Stakeholders must monitor how regulatory convergence on water-use efficiency intersects with raw-material volatility in polymer supply chains.
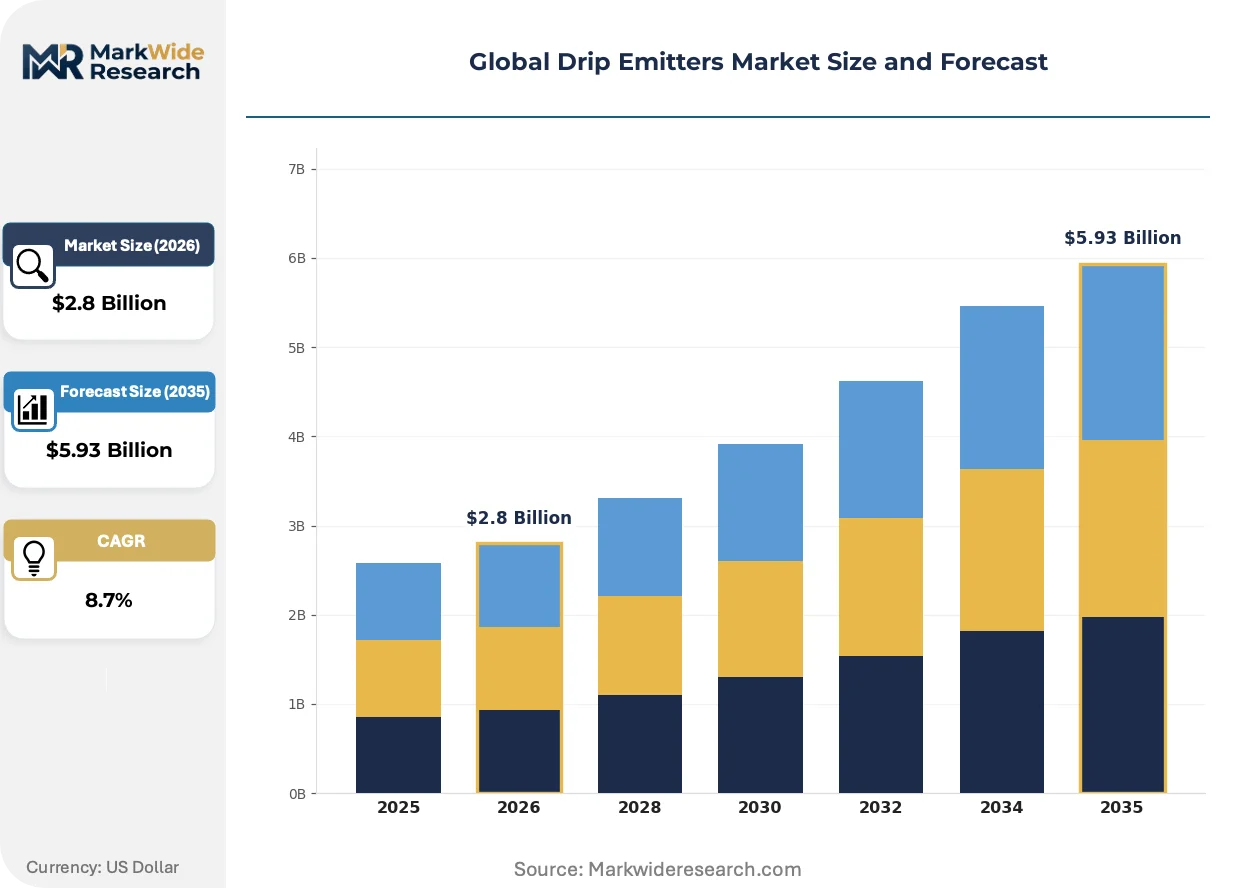
Market Dynamics
Pressure-compensating emitter technology is compressing price premiums across undulating terrain applications while regulatory water-efficiency mandates in California, Spain, and Australia force capital refresh cycles in mature installed bases.
Growth Catalysts
- EU Green Deal water-efficiency mandates:Binding targets for agricultural water use are compelling greenhouse operators in Spain's Almería belt to retrofit legacy flood systems with precision drip infrastructure.
- Israeli drip-technology cluster:Concentrated R&D and manufacturing capabilities in the Negev region generate continuous innovation in clogging-resistant labyrinth designs that export globally.
- SGMA groundwater regulations:California's Sustainable Groundwater Management Act imposes extraction limits that drive orchard and vineyard conversions to pressure-compensating systems.
Market Restraints
- Polymer feedstock volatility:UV-stabilized polyethylene and polypropylene prices fluctuate with crude oil and natural gas derivatives, compressing margins for molded emitter producers.
- China manufacturing concentration:Dominant polymer compounding and precision molding capacity in Fujian and Zhejiang provinces creates single-source vulnerability for global supply chains.
- Technical limitation in high-TDS water:Elevated total dissolved solids in groundwater sources accelerates emitter clogging, requiring costly pre-filtration infrastructure.
Strategic Opportunities
- Underpenetrated Southeast Asian plantation agriculture:Oil palm and rubber estates in Indonesia and Malaysia remain predominantly flood-irrigated, presenting retrofit volume potential.
- Technology convergence with soil-moisture sensors:Integration of pressure-compensating emitters with IoT-enabled moisture probes enables closed-loop irrigation automation in high-value greenhouse operations.
- Australian Murray-Darling Basin water-trading schemes:Market-based water allocation mechanisms incentivize efficiency investments that accelerate emitter replacement cycles.
Industry Challenges
- Precision molding skill gap:Manufacturing labyrinth flow paths and diaphragm mechanisms requires specialized polymer processing expertise that outpaces vocational training output in emerging production regions.
- BIS certification timeline:India's quality standards enforcement creates extended approval periods for imported emitter systems, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drip Emitters Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Emitters, Pressure Compensating Emitters, Inline Emitters, Foggers Application: Agriculture, Landscaping, Greenhouses, Horticulture End User: Commercial Growers, Residential Users, Municipalities, Golf Courses Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Rain Bird Corporation, Rivulis Irrigation Ltd., Netafim Limited, Valmont Industries Inc., Lindsay Corporation, Jain Irrigation Systems Ltd., Hunter Industries Inc., Chinadrip Irrigation Equipment (Xiamen) Co., Ltd., The Toro Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drip Emitters Market Emerging Trajectories
Active emitter intelligence and predictive maintenance capabilities are redefining value capture in precision irrigation, shifting competitive advantage from hardware durability to data-enabled performance assurance.
Self-cleaning turbulent-flow emitters with silicon-membrane pressure regulation are supplanting conventional labyrinth designs in high-value permanent crop installations. California almond and vineyard operators are adopting these systems at accelerated replacement cycles. The technology is compressing maintenance service revenue pools while expanding hardware margin capture.
REACH chemical compliance and the EU F-Gas Regulation's indirect pressure on water-intensive cooling alternatives are tightening material specifications for polymer stabilization additives. Compounders must reformulate UV inhibitors and antioxidants to meet substance restrictions. Greenhouse operators in the Netherlands and Belgium face accelerated equipment validation requirements.
Direct procurement from manufacturer technical sales teams is displacing traditional agricultural distribution channels for large-scale commercial growers. Major Spanish greenhouse cooperatives and Australian corporate farming operations now negotiate volume contracts bypassing regional dealer networks. This pattern concentrates most visibly in Israel's export-oriented technology sector and California's Central Valley integrated operations.
Global Drip Emitters Market Segmentation
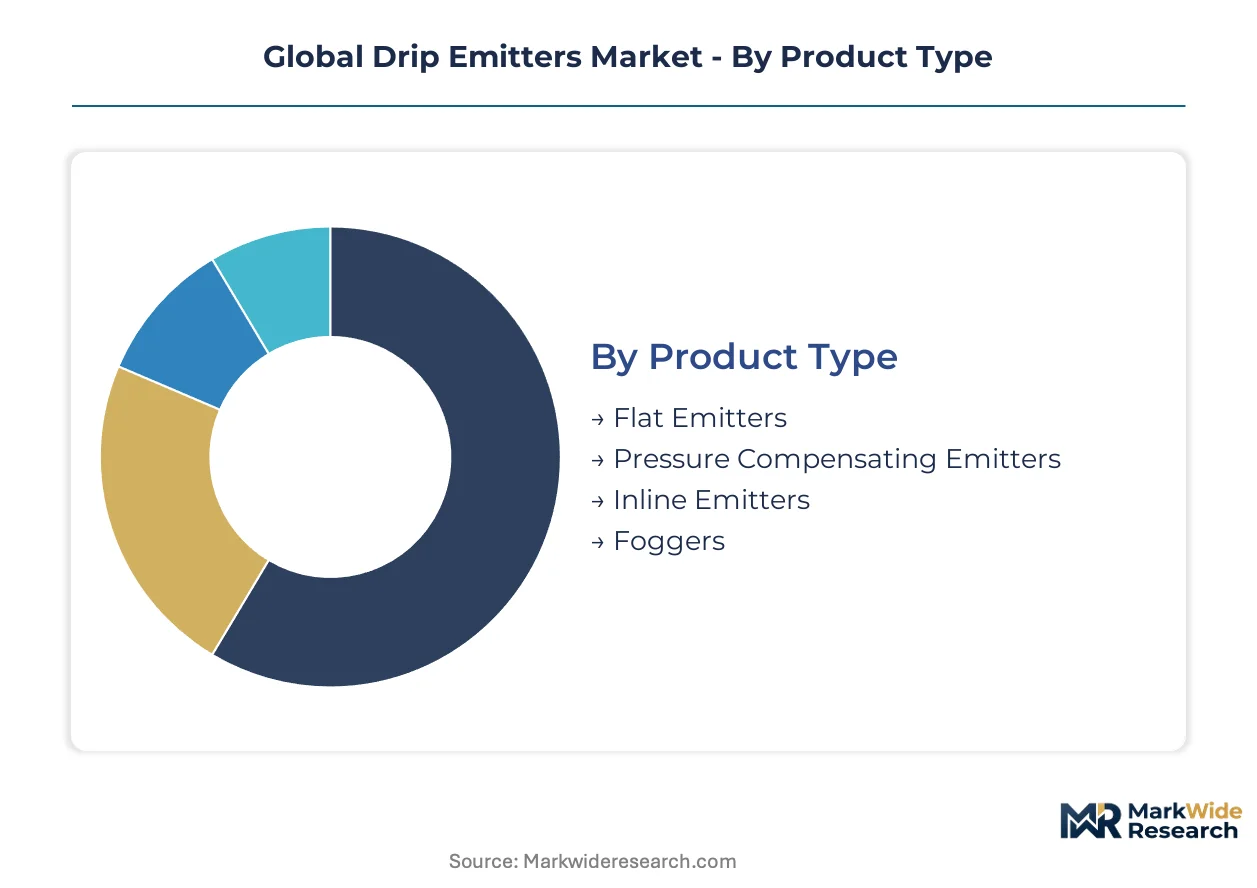
Drip emitter procurement patterns diverge sharply across product architectures, end-use intensities, and channel structures. Segment boundaries determine where manufacturers capture margin premiums versus competing on unit throughput.
Product Type:
Margin pools concentrate in pressure-regulating architectures that command specification premiums from permanent crop operators.
- Pressure Compensating Emitters:Diaphragm or labyrinth mechanisms maintain uniform discharge across 10-50 psi pressure differentials. Almond and vineyard operators in California's Central Valley specify these for undulating terrain where elevation changes exceed 15 meters.
- Flat Emitters:Molded polyethylene channels with turbulent flow paths serve cost-sensitive row-crop applications. Cotton and maize producers in Australia's Murray-Darling Basin deploy these at high density-per-hectare for seasonal replacement cycles.
- Inline Emitters:Extruded drip lines with integrated emitters suit mechanized harvesting operations.
- Foggers:Fine-mist nozzles for greenhouse humidity control and propagation environments.
Pressure Compensating Emitters hold installed capacity. Flat Emitters is rotating up the share rankings.
Application:
Revenue-per-hectare varies tenfold between open-field commodity production and controlled-environment horticulture.
- Greenhouses:High-density emitter networks with 20-30 cm spacing deliver fertigation precision for tomato and pepper producers in Spain's Almería belt. Replacement frequencies run 2-3 years versus 5-7 in open field.
- Agriculture:Broadacre orchards and vineyards drive absolute unit volume. Israeli drip-technology exports anchor penetration in Mediterranean climate zones facing groundwater extraction limits.
- Horticulture:Nursery stock and ornamental production requires flexible, portable emitter configurations.
- Landscaping:Municipal parks and commercial grounds maintenance specify vandal-resistant surface installations.
Greenhouses capture value per installation. Agriculture dominates cumulative deployed base.
End User:
Procurement sophistication separates volume buyers with technical specification teams from price-driven replacement purchasers.
- Commercial Growers:Corporate farming operations and agricultural cooperatives negotiate direct manufacturer contracts bypassing distribution markups. Australian water-trading scheme participants prioritize efficiency-certified equipment to maximize allocation value.
- Municipalities:Public sector procurement faces extended tender timelines and domestic content requirements under India's BIS standards and China's GB/T irrigation norms.
- Golf Courses:Turf managers balance playability with water-use reporting to regulatory authorities.
- Residential Users:Home garden installations through retail and online channels drive seasonal demand spikes.
Commercial Growers concentrate specification authority. Municipalities are expanding procurement scale.
Distribution Channel:
Channel economics reflect customer scale and technical service requirements.
- Direct Sales:Manufacturer technical teams serve greenhouse cooperatives and integrated farming operations with custom hydraulic design and filtration specification. Israel's export-oriented sector pioneered this model for international deployment.
- Wholesalers:Regional agricultural supply houses inventory standard emitter configurations for row-crop replacement demand.
- Retail:Brick-and-mortar agricultural dealers serve smallholder and residential segments with immediate availability.
- Online:E-commerce platforms penetrate price-transparent commodity emitter categories.
Direct Sales captures specification premium. Wholesalers rotates toward volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding and precision molding capacity clusters in China's Fujian and Zhejiang provinces, while emitter technology innovation concentrates in Israel's Negev corridor. Demand intensity varies sharply across regulatory environments and water-stressed agricultural zones.
United States
California's Central Valley almond and vineyard operators drive specification-grade pressure-compensating emitter procurement. The EPA's WaterSense program and SGMA groundwater extraction limits compel capital refresh cycles in mature orchard installations. Fresno County and the broader San Joaquin Valley anchor domestic demand concentration.
Spain
Almería's greenhouse belt generates Europe's highest per-hectare emitter density for tomato and pepper fertigation systems. EU Green Deal water-efficiency mandates force retrofit of legacy flood irrigation in protected horticulture. The Andalusian coastal corridor sustains concentrated technology deployment.
Israel
Negev-based drip-technology exporters supply precision irrigation infrastructure to Mediterranean climate zones facing groundwater limits. The national water authority's efficiency standards and concentrated R&D capabilities generate continuous innovation in clogging-resistant labyrinth designs. Kibbutzim and industrial parks around Beersheba anchor the technology cluster.
Australia
Murray-Darling Basin corporate farming operations negotiate direct manufacturer contracts for efficiency-certified equipment. Market-based water allocation mechanisms under the Basin Plan incentivize emitter replacement cycles to maximize trading value. Riverina and Sunraysia districts concentrate permanent crop installations.
China
Fujian and Zhejiang province manufacturers dominate global polymer compounding and precision molding capacity for cost-sensitive emitter production. GB/T irrigation norms raise import barriers and accelerate domestic manufacturing investment. Xiamen and Wenzhou anchor export-oriented fabrication clusters serving Southeast Asian plantation agriculture.
Global Drip Emitters Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Global Drip Emitters Market. The vendor base separates into three tiers: integrated technology developers with captive filtration and polymer capabilities, scale-driven manufacturers competing on unit throughput, and regional fabricators serving localized replacement demand. Dominant competitive moves include backward integration into polymer compounding operations and direct technical sales team deployment bypassing traditional distribution channels.
Within the integrated technology tier, Netafim Limited and Jain Irrigation Systems Ltd. exemplify archetypes combining emitter manufacturing with upstream polymer control and filtration system integration. Chinadrip Irrigation Equipment (Xiamen) Co., Ltd. occupies a position on the scale-driven manufacturing vector, leveraging concentrated Fujian province molding capacity for cost-competitive volume production. Rain Bird Corporation and The Toro Company represent North American-based diversified irrigation equipment portfolios where drip emitters sit within broader landscape and agricultural water management offerings.
| Leading Market Players |
|---|
| Rain Bird Corporation |
| Rivulis Irrigation Ltd. |
| Netafim Limited |
| Valmont Industries Inc. |
| Lindsay Corporation |
| Jain Irrigation Systems Ltd. |
| Hunter Industries Inc. |
| Chinadrip Irrigation Equipment (Xiamen) Co., Ltd. |
| The Toro Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Australian corporate farming operations and Israeli technology exporters lock in multi-year supply access while stabilizing unit price visibility against polymer feedstock volatility. These arrangements concentrate procurement authority with direct manufacturer relationships, compressing distributor margin capture across the Global Drip Emitters Market.
Pricing Analysis
California's SGMA groundwater regulations dictate the pricing tier structure across the Global Drip Emitters Market. Three-tier pricing structure across premium, standard, and economy levels separates pressure-compensating systems with enhanced clogging resistance from flat emitters for seasonal row-crop replacement. Cost compression in economy-tier flat emitters is intensifying because of concentrated Fujian province molding capacity and aggressive Southeast Asian export pricing. Commercial growers with direct technical sales relationships exhibit lowest price sensitivity, while municipal procurement under India's BIS standards faces extended tender timelines that amplify cost scrutiny.
Supply Chain Analysis
Inventory cycles for UV-stabilized polyethylene and polypropylene extend lead times for precision molding operations serving high-specification emitter orders. Supply concentrates in China's Fujian and Zhejiang provinces for polymer compounding and molding, Israel's Negev corridor for technology-intensive diaphragm designs, and Australia's Murray-Darling Basin for regional distribution hubs. Raw material dependencies draw from crude oil derivatives, natural gas feedstocks, and specialized UV inhibitor additives. Single-source vulnerability in Chinese molding capacity creates structural risk for global emitter availability. Distribution runs through direct manufacturer technical sales teams for commercial growers and regional agricultural wholesalers for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Drip Emitters Market rewards players who control precision polymer processing capabilities that outpace vocational training output in emerging production regions. Specialized labyrinth flow path engineering and diaphragm mechanism fabrication represent binding constraints on supply expansion.
For Market Incumbents: Shield technology leadership by deepening backward integration into polymer compounding operations and accelerating certification investment under REACH chemical compliance and India's BIS standards. Threat from scale-driven Chinese manufacturers with concentrated Fujian province capacity demands channel control through direct technical sales deployment bypassing traditional agricultural distribution networks. For New Entrants and Emerging Players: Lead with sensor-integrated pressure-compensating systems targeting underpenetrated Southeast Asian oil palm and rubber plantation agriculture. Indonesia and Malaysia present the most penetrable geography given predominant flood-irrigation infrastructure and rising water-efficiency awareness. Go-to-market angle centers on closed-loop automation packages combining emitters with IoT-enabled soil-moisture probes. For Investors and Strategic Acquirers: Polymer-compounding specialists with captive UV-stabilization capabilities represent the most defensible acquisition target archetype for long-term viability across the 5-10 year horizon. Signal to watch is regulatory convergence on water-use efficiency mandates in Mediterranean climate zones, which would accelerate capital refresh cycles and expand addressable market for specification-grade equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of UV-stabilized polyethylene secures margin control against crude derivative volatility. |
| Direct Technical Sales Deployment | Bypassing regional dealer networks captures specification premiums from Australian corporate farming operations. |
| Sensor-Emitter Integration Development | IoT-enabled moisture probe convergence enables closed-loop automation in Spain's Almería greenhouse belt. |
| REACH-Compliant Additive Reformulation | Reformulated UV inhibitors meet EU substance restrictions for Netherlands and Belgium greenhouse operators. |
| Southeast Asian Distribution Expansion | Extended reach across Indonesian and Malaysian plantation agriculture unlocks retrofit volume potential. |
Methodological Framework
The analysis maps pressure-compensating emitters, flat emitters, inline emitters, and foggers, each validated through interviews with irrigation system procurement managers, agricultural cooperative technical directors, polymer compounding plant engineers, and greenhouse operations supervisors. Primary fieldwork combined with secondary validation from customs and trade data, irrigation equipment distributor inventory records, SEC filings of diversified equipment manufacturers, and EPA WaterSense certification databases. Bottom-up emitter unit deployment estimates and top-down agricultural water-use efficiency spending projections were triangulated for consistency.
Model outputs were validated against external benchmarks including regional groundwater extraction limit enforcement timelines and polymer price indices. Segmentation dimensions modeled include product architecture, application intensity, end-user procurement sophistication, and channel structure across the projection horizon. CAGRs were derived from installed base replacement cycle analysis and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporate water-trading scheme participation rates in Australia's Murray-Darling Basin and EU Green Deal binding target compliance trajectories.
The analysis sits within stated boundaries; outcomes outside sustained polymer feedstock availability or accelerated regulatory enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding technology adoption curves and certification timeline durations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Bean Harvester Market
Agricultural Equipment
Industrial Potato Graders Market