
 Autonomous Farm Vehicle Market | 2026-2036
Autonomous Farm Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Farm Vehicle Market Insights
Modular autonomy kits is decoupling hardware ownership from software subscriptions across the farm equipment sector. John Deere leverages its precision-ag platform to anchor recurring revenue streams through subscription-based autonomy upgrades. CNH Industrial competes through integrated vehicle-to-cloud architectures that sustain aftermarket service margins. AGCO Corporation specializes in retrofit-compatible autonomy modules, allowing farmers to upgrade existing fleets without full equipment replacement.
Autonomous farm vehicles are self-propelled agricultural machines equipped with GPS guidance, LiDAR, computer vision, and sensor fusion systems capable of executing planting, tillage, spraying, and harvesting operations without continuous human operator presence; these vehicles typically operate at sub-25 mm pass-to-pass accuracy and integrate real-time kinematic positioning for centimeter-level field navigation. Their primary purpose is to reduce labor dependency, extend operational windows, and standardize input application across large acreages. Autonomous tractors dominate current deployment volumes due to their versatility across multiple field tasks, while harvesters command concentrated margin pools because of the complexity of grain-flow optimization and real-time yield-mapping integration. Sensor fusion technology represents the fastest-growing segment as manufacturers combine LiDAR, radar, and optical systems to achieve all-weather operational reliability.
The EPA regulates off-road diesel emissions from autonomous farm vehicles through Tier 4 Final and emerging Stage V equivalent standards, while the FAA governs agricultural UAV operations under Part 107 waivers that increasingly intersect with ground-based autonomous fleet coordination. OSHA field-safety guidelines for autonomous equipment operation shape manufacturer liability frameworks and operator-training requirements. Stakeholders must monitor how evolving EPA emissions rules and FAA airspace-integration policies will constrain or enable mixed-fleet autonomy architectures combining ground vehicles and aerial systems.
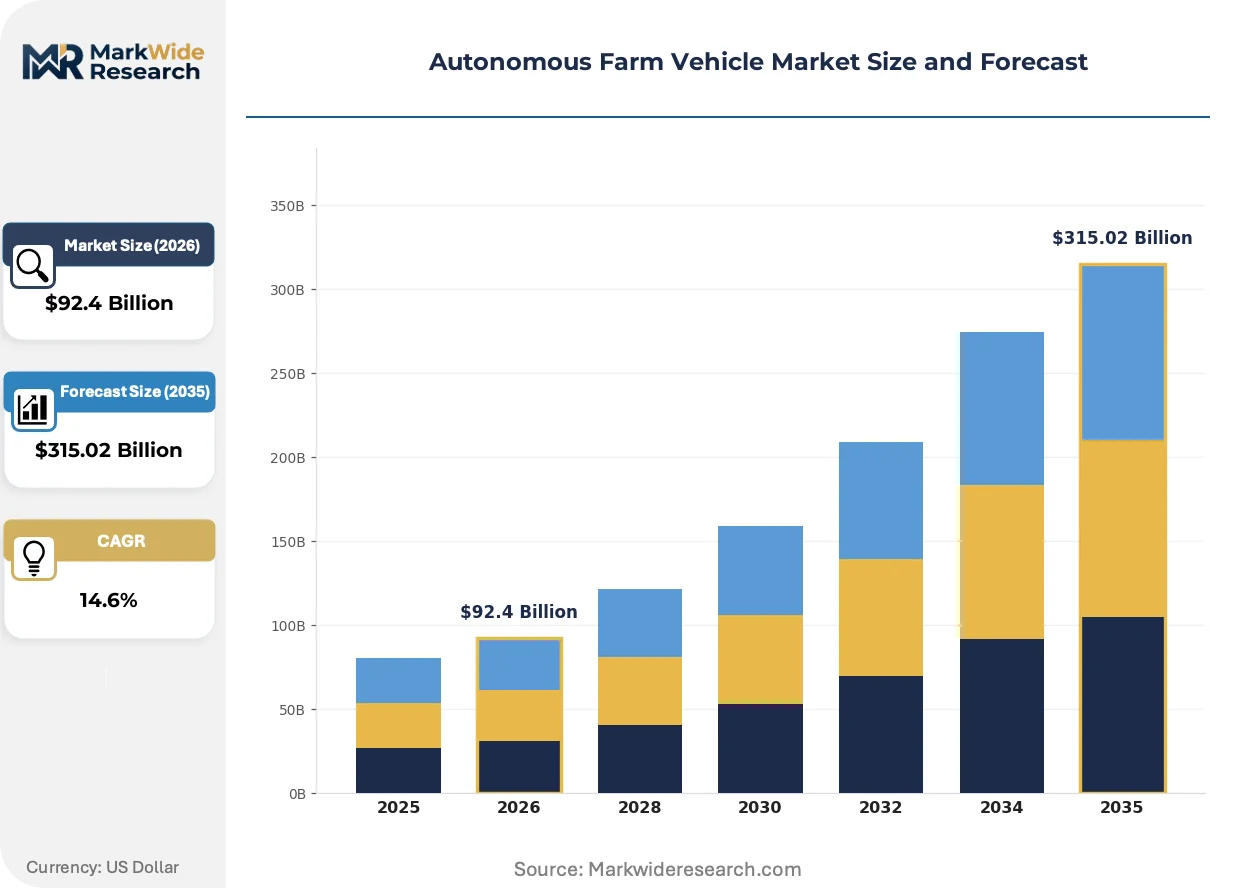
Market Dynamics
Modular retrofit architectures are fragmenting capital deployment patterns across farm equipment procurement. Tier 4 Final compliance costs and FAA Part 107 waiver complexity are compressing operational margins for mixed aerial-ground fleet operators while accelerating software subscription monetization.
Growth Catalysts
- Labor scarcity in Brazil's Mato Grosso:Soybean belt operators face acute seasonal worker shortages during critical planting windows. Autonomous fleet deployment extends operational coverage across 24-hour cycles.
- EPA Tier 4 Final mandates:Emissions compliance requirements are forcing engine control system upgrades that integrate natively with autonomy platforms. Retrofit pathways lower barrier to entry for existing tractor fleets.
- Sensor fusion convergence:LiDAR-radar-optical integration enables sub-25 mm pass-to-pass accuracy in adverse weather conditions. All-weather reliability expands addressable operating hours per season.
Market Restraints
- Lithium-ion battery supply concentration:Cell production for electric autonomous platforms clusters in East Asian manufacturing corridors. Geopolitical friction elevates input cost volatility and sourcing risk.
- FAA airspace coordination complexity:Part 107 waiver processing timelines create deployment friction for mixed aerial-ground operations. Regulatory lag constrains synchronized fleet architectures.
- High-definition mapping dependency:Centimeter-level RTK positioning requires proprietary field boundary data layers. Data licensing costs accumulate across multi-thousand-acre operations.
Strategic Opportunities
- India's Punjab-Haryana wheat belt:Smallholder consolidation and canal irrigation digitization create retrofit-ready installed base. Modular autonomy kits address equipment age without full replacement.
- Carbon credit verification integration:Autonomous input application generates auditable precision-agriculture data streams. Sustainability-linked financing instruments monetize operational transparency.
- 5G private network deployment:Low-latency vehicle-to-cloud architectures enable real-time fleet coordination. Telecom infrastructure partnerships reduce connectivity capital burden on operators.
Industry Challenges
- Mechatronics technician scarcity:Sensor calibration and fusion system maintenance require hybrid mechanical-electrical skill sets. Vocational training pipelines lag fleet deployment velocity.
- ISO 12100 machinery safety certification:Autonomous emergency stop and obstacle detection validation extends type-approval timelines. Compliance documentation burdens smaller equipment manufacturers.
- Legacy fleet CAN bus incompatibility:Pre-2015 tractors lack standardized diagnostic interfaces for autonomy module integration. Protocol bridging hardware adds cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Farm Vehicle Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $315.02 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Seeders, Sprayers Technology: GPS Guidance, LiDAR, Computer Vision, Sensor Fusion End User: Farmers, Agribusiness, Cooperatives, Research Institutions Application: Crop Production, Soil Management, Harvest Optimization, Precision Agriculture |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Case IH, New Holland, Autonomous Solutions, Clearpath Robotics, Claas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Farm Vehicle Market Trends and Innovations
Software-defined functionality is decoupling hardware lifecycles from feature evolution across agricultural equipment. Three concurrent developments are compressing traditional R&D-to-deployment timelines.
Sensor fusion stacks combining solid-state LiDAR, 77 GHz radar, and multispectral cameras are overtaking single-sensor guidance architectures in high-value row-crop applications. Large-scale corn and soybean operators in the US Corn Belt are accelerating procurement of triple-redundant perception systems. This convergence is overtaking legacy GPS-only guidance in premium tractor segments and compressing warranty exposure for nighttime operations.
EPA enforcement of Tier 4 Final and emerging Stage V equivalent standards is tightening real-time emissions monitoring requirements for off-road diesel autonomy platforms. Engine control module integration with fleet management systems now mandates encrypted telematics transmission. Autonomous harvester manufacturers face the steepest compliance redesign burden due to power density demands and exhaust after-treatment packaging constraints.
Farmers are unbundling equipment ownership from operational control through autonomy-as-a-service contracting. Large agribusiness operators in Brazil's Mato Grosso are piloting per-acre pricing models that transfer capital risk to technology providers. This restructuring is most visible in precision spraying applications where variable-rate input savings justify premium service fees.
Autonomous Farm Vehicle Market Segmentation
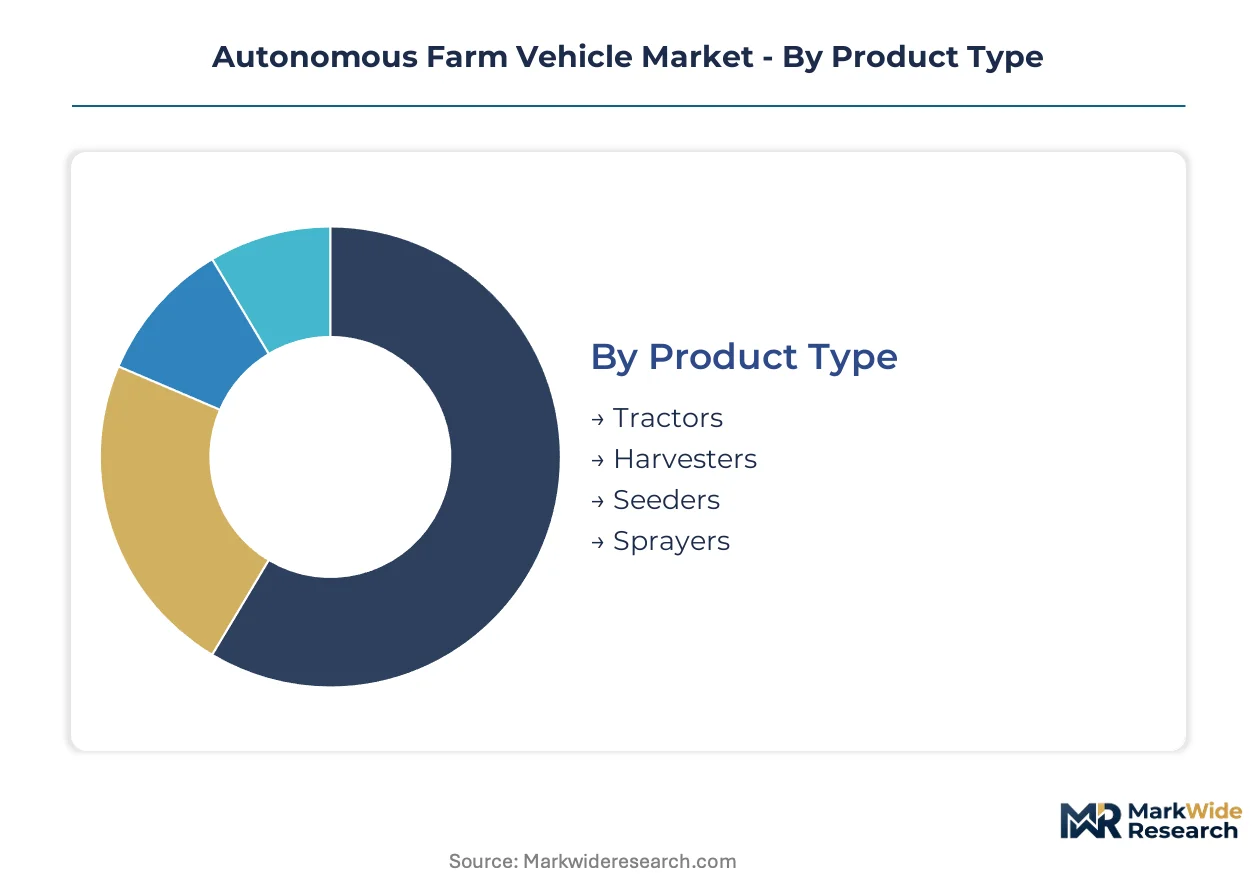
Segmentation in autonomous farm vehicles reveals divergent technology adoption curves across equipment types and operational scales. Product architecture choices determine whether deployments prioritize versatile multi-task platforms or specialized single-function machines. Understanding these splits enables targeted positioning for retrofit modules versus integrated factory autonomy.
Product Type:
Tractors command volume deployment while harvesters concentrate margin capture through complexity premiums.
- Tractors:Multi-functional platforms equipped with three-point hitch compatibility and PTO interfaces enable tillage, planting, and transport operations from a single chassis. Demand clusters in Brazil's Mato Grosso soybean belt where 24-hour autonomous operation offsets acute seasonal labor scarcity.
- Harvesters:Grain-flow optimization systems integrate real-time yield mapping with automated header height control and tank-level management. US Corn Belt agribusiness operators absorb premium pricing for combines with triple-redundant perception stacks that sustain nighttime harvesting reliability.
- Seeders:Precision planting units with individual row shut-off and variable-rate seed metering.
- Sprayers:Self-propelled chemical applicators with boom-leveling automation and drift-reduction nozzle control.
Mature deployment sits with tractors. Newer deployment is concentrated in harvesters.
Technology:
Single-sensor architectures face displacement as multi-modal fusion achieves all-weather reliability.
- Sensor Fusion:LiDAR-radar-optical integration generates redundant environmental perception for sub-25 mm pass-to-pass accuracy in adverse conditions. Large-scale corn and soybean operators in the US Midwest are accelerating procurement of triple-redundant stacks that compress warranty exposure for nighttime operations.
- GPS Guidance:RTK-corrected satellite positioning provides centimeter-level field navigation for established row-crop applications. Brazil's Mato Grosso fleet operators leverage existing correction network infrastructure to anchor baseline autonomy functionality.
- LiDAR:Solid-state scanning arrays for obstacle detection and field boundary mapping.
- Computer Vision:Convolutional neural networks for crop-row detection and anomaly classification.
Established penetration rests with GPS guidance. Climbing the fastest is sensor fusion.
End User:
Capital scale determines whether procurement favors ownership or service-based operational control.
- Agribusiness:Corporate farming enterprises with multi-thousand-acre footprints deploy integrated fleet management architectures. These operators in Brazil's Mato Grosso pilot per-acre autonomy-as-a-service contracts that transfer capital risk to technology providers.
- Farmers:Owner-operators with 500-2,000 acre holdings favor retrofit-compatible autonomy modules that extend existing equipment lifecycles. India's Punjab-Haryana wheat belt smallholders represent emerging demand for modular kits addressing equipment age without full replacement.
- Cooperatives:Member-owned purchasing consortia sharing equipment across multiple operations.
- Research Institutions:University and government agricultural extension facilities validating autonomous system performance.
Volume concentration aligns with agribusiness. Emerging activation is expanding among farmers.
Application:
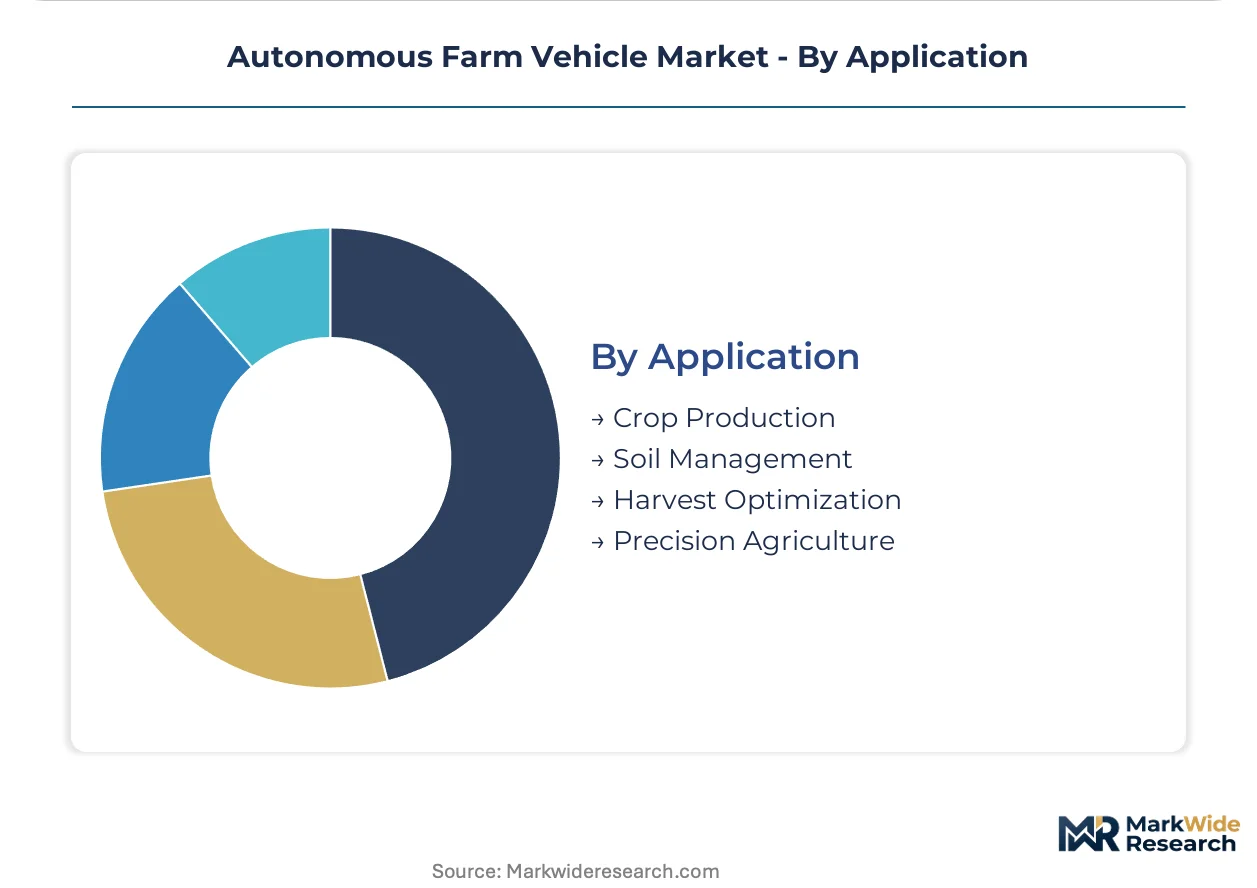
Input application precision generates measurable savings that justify autonomy premiums faster than mechanical operations.
- Precision Agriculture:Variable-rate input management using real-time soil and crop sensor feedback optimizes fertilizer, seed, and chemical placement. Carbon credit verification integration enables sustainability-linked financing instruments that monetize operational transparency from auditable data streams.
- Harvest Optimization:Grain loss monitoring and automated speed adjustment maximize throughput during narrow weather windows. US Corn Belt operators prioritize harvest autonomy for its direct revenue protection against weather-induced yield degradation.
- Crop Production:Integrated planting, cultivation, and protection task sequences.
- Soil Management:Tillage depth control and compaction avoidance through automated implement guidance.
Operational maturity centers on harvest optimization. Steepest expansion trajectory is precision agriculture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso state anchors concentration through its soybean belt special economic zones, where labor scarcity and farm scale create favorable conditions for autonomous fleet deployment. Tax incentives for precision agriculture technology accelerate procurement cycles across the region's agribusiness operators.
United States
The US Corn Belt drives demand through large-scale agribusiness operators expanding procurement of self-driving tractors and harvesters. EPA Tier 4 Final emissions standards tighten compliance requirements for vehicle autonomy systems. Iowa and Illinois field clusters concentrate deployment of triple-redundant perception stacks for nighttime harvesting reliability.
Brazil
Mato Grosso's soybean belt experiences acute seasonal worker shortages during critical planting windows. ANVISA agricultural chemical regulations intersect with autonomous spraying operations. The Cerrado region pilots per-acre autonomy-as-a-service contracts that transfer capital risk to technology providers.
Germany
Baden-Württemberg's precision engineering base supplies sensor fusion components for sub-25 mm pass-to-pass accuracy systems. EU Green Deal agricultural digitization mandates accelerate retrofit pathway development. Stuttgart industrial corridor manufacturers specialize in ISO 12100 machinery safety certification for autonomous emergency stop validation.
India
Punjab-Haryana wheat belt smallholder consolidation creates retrofit-ready installed base for modular autonomy kits. BIS equipment standards and PLI scheme incentives lower barrier to entry for existing tractor fleet upgrades. Ludhiana manufacturing clusters address equipment age without requiring full replacement.
China
Yangtze River Delta agricultural mechanization programs deploy electric autonomous platforms for carbon reduction targets. MIIT intelligent manufacturing standards and dual carbon goals shape vehicle-to-cloud architecture requirements. Jiangsu province field trials integrate 5G private networks for real-time fleet coordination.
Autonomous Farm Vehicle Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement channels. The vendor base spans integrated factory autonomy providers, modular retrofit specialists, and component subsystem suppliers. Three archetypes dominate: precision-agriculture platform owners, retrofit-compatible module fabricators, and sensor fusion technology developers. Strategic partnerships and software subscription monetization represent the dominant competitive moves.
Among North American platform owners, John Deere and CNH Industrial exemplify integrated vehicle-to-cloud architectures that sustain aftermarket service margins. AGCO Corporation occupies a position within the retrofit-specialist tier, representing modular autonomy modules that allow farmers to upgrade existing fleets. These three anchors illustrate the divergence between hardware-integrated and software-decoupled competitive strategies.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Case IH |
| New Holland |
| Autonomous Solutions |
| Clearpath Robotics |
| Claas |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISO 12100-validated factory autonomy and retrofit-compatible modular kits manifests in both pricing premiums and supply chain configurations. Tier 4 Final compliance integration commands 15-20% cost premiums through engine control module bundling, while sensor fusion component sourcing clusters in Germany's precision engineering corridor and East Asian battery manufacturing zones.
Pricing Analysis
Short lead-time premiums dominate pricing architecture for triple-redundant perception stacks sourced from Baden-Württemberg manufacturers. Subscription-based SaaS tiers for autonomy software separate John Deere's precision-ag platform from AGCO's retrofit modules. Price differentiation rests on RTK correction network access and encrypted telematics integration. Cost compression in electric autonomous platforms intensifies due to lithium-ion cell supply volatility. Brazil's Mato Grosso agribusiness operators demonstrate lowest price sensitivity given per-acre contracting models that transfer capital risk.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's MIIT intelligent manufacturing standards are reshaping component sourcing for vehicle-to-cloud architectures. Solid-state LiDAR arrays draw from Germany and Japan; lithium-ion cells feed from South Korea and China; precision GPS modules source from US and Swiss manufacturers. Single-source vulnerability concentrates in rare-earth magnet supply for electric drivetrains. Distribution runs through OEM captive service networks and certified retrofit installer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where sensor fusion technology and encrypted telematics transmission anchor competitive moats. Players pursue backward integration into perception hardware to escape East Asian battery supply bottlenecks.
For Market Incumbents: Hedge against modular retrofit specialists by deepening proprietary RTK network infrastructure and locking agribusiness operators into multi-year software subscriptions. Acquire ISO 12100 certification capabilities in Stuttgart engineering clusters to accelerate type-approval timelines. Sensor fusion patent thickets represent the priority defensive lever. For New Entrants and Emerging Players: India's Punjab-Haryana smallholder consolidation presents a white-space target for CAN bus bridging hardware compatible with pre-2015 tractor fleets. Brazil's per-acre autonomy-as-a-service pilots offer a second penetrable entry point through precision spraying applications. Pursue telecom partnership models that externalize 5G private network capital burden. For Investors and Strategic Acquirers: Re-rating potential sits with sensor fusion subsystem developers given EPA Tier 4 Final and FAA Part 107 waiver complexity accelerating OEM outsourcing. Long-term viability favors specialists with encrypted telematics integration capabilities. Watch for inflection when 5G private network deployment crosses critical mass in Yangtze River Delta field trials.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Stack Acquisition | Triple-redundant LiDAR-radar-optical integration secures nighttime harvesting reliability premiums in US Corn Belt. |
| RTK Network Infrastructure Buildout | Proprietary correction networks anchor recurring subscription revenue and raise switching costs for agribusiness operators. |
| 5G Private Network Partnership | Telecom alliances reduce connectivity capital burden while enabling real-time fleet coordination in Mato Grosso pilot zones. |
| ISO 12100 Certification Investment | Machinery safety validation accelerates type-approval timelines and limits liability exposure for autonomous emergency systems. |
| Carbon Credit Verification Integration | Auditable precision-agriculture data streams unlock sustainability-linked financing instruments for input application transparency. |
Research Methodology
Multi-period observation of EPA enforcement patterns, FAA waiver processing timelines, and OEM autonomy platform rollouts anchored the trend analysis, supplemented by interviews with precision-agriculture platform executives, fleet operations managers at Brazil's Mato Grosso agribusinesses, mechatronics technicians in Germany's Stuttgart corridor, and BIS certification specialists in India's Ludhiana manufacturing clusters. Secondary validation drew from EPA Tier 4 Final regulatory filings, FAA Part 107 waiver databases, MIIT intelligent manufacturing standards disclosures, and OEM SEC 10-K segment reporting. Bottom-up equipment deployment estimates triangulated against top-down addressable acreage calculations.
Segment-weighting approaches modeled technology adoption curves across sensor fusion, GPS guidance, and single-sensor architectures; product type splits between tractors, harvesters, seeders, and sprayers; end-user concentration across agribusiness, farmers, cooperatives, and research institutions; and application maturity spanning precision agriculture, harvest optimization, crop production, and soil management. CAGRs derived from equipment procurement velocity, retrofit penetration rates, and software subscription attach rates across the projection horizon. Forecast inputs incorporated lithium-ion battery supply constraints and 5G private network deployment schedules.
Revisions become necessary when EPA emissions rule amendments, FAA airspace integration policy shifts, or geopolitical disruptions to East Asian battery supply materialize. Forecasts reflect documented assumptions regarding labor scarcity persistence in Brazil's soybean belt and consolidation trajectories in India's wheat regions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Harvest Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Global AI in Agriculture Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market