
 Smart Agriculture Solutions Market | 2026-2036
Smart Agriculture Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Agriculture Solutions Market Outlook
The gap between premium precision-ag platforms and commodity farm management tools is recalibrating competitive strategy across the sector. Deere & Company leverages its integrated equipment-and-software stack to dominate high-acreage North American operations. Trimble Inc. sustains technology leadership through GNSS correction networks and data analytics specialization. AGCO Corporation competes via open-architecture platforms that accommodate mixed-fleet environments.
Smart agriculture solutions encompass sensor arrays, autonomous machinery, and cloud-based decision support systems that collect field-level data and execute variable-rate interventions with sub-meter accuracy. These systems reduce input waste through real-time soil moisture telemetry and prescription map generation. Software platforms command expanding margin pools as recurring subscription revenue displaces one-time hardware sales. IoT-enabled sensor networks represent the fastest-growing technology layer, while GPS-guided equipment retains the largest installed base among mature automation categories.
The EPA regulates drone spraying operations under Part 107 waivers, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices in controlled-environment agriculture. FDA food-traceability rules under FSMA Section 204 drive demand for farm-level digital record systems. Stakeholders must weigh compliance architecture against interoperability standards as regulatory fragmentation intensifies across export destinations.
Market Dynamics
Precision planting systems and autonomous spraying fleets are compressing operational timelines across large-scale row-crop operations, while carbon-reduction mandates in Germany and France force equipment retrofits and accelerate fleet turnover cycles.
Growth Catalysts
- EU Green Deal emissions standards:Germany's carbon-reduction mandates and France's tightening farm machinery regulations compel cooperative investment in electrified and precision-controlled equipment.
- Mato Grosso soybean belt deployment:Brazilian cooperatives are fielding autonomous spraying fleets at scale, validating variable-rate intervention economics for export-oriented producers.
- Sensor-to-cloud telemetry integration:Real-time soil moisture data streams now enable prescription map generation with sub-meter accuracy, cutting input waste for high-acreage operators.
Market Restraints
- Semiconductor supply concentration:GPS module and edge-computing chip sourcing remains concentrated in East Asian foundries, exposing equipment lead times to geopolitical friction.
- F-Gas Regulation compliance costs:The EU's controlled-environment agriculture refrigerant constraints raise capital requirements for greenhouse automation retrofits.
- Lithium-ion battery substitution limits:Energy density constraints in autonomous field robots restrict continuous operation windows below diesel-equivalent thresholds.
Strategic Opportunities
- India's PLI scheme for precision agriculture:Domestic manufacturing incentives for IoT-enabled farm equipment open white space for sensor array localization.
- Drone spraying under FAA Part 107 waivers:Expanded EPA regulatory clarity for aerial application creates new service-model channels beyond ground-based fleets.
- Blockchain-IoT convergence for FSMA traceability:FDA food-traceability rules under Section 204 drive demand for immutable farm-level digital record systems.
Industry Challenges
- GNSS correction network interoperability:Mixed-fleet operators face integration complexity when combining proprietary correction services from competing equipment platforms.
- Cyber-physical certification timelines:ISO 27001 and IEC 62443 compliance for autonomous machinery extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Agriculture Solutions Market |
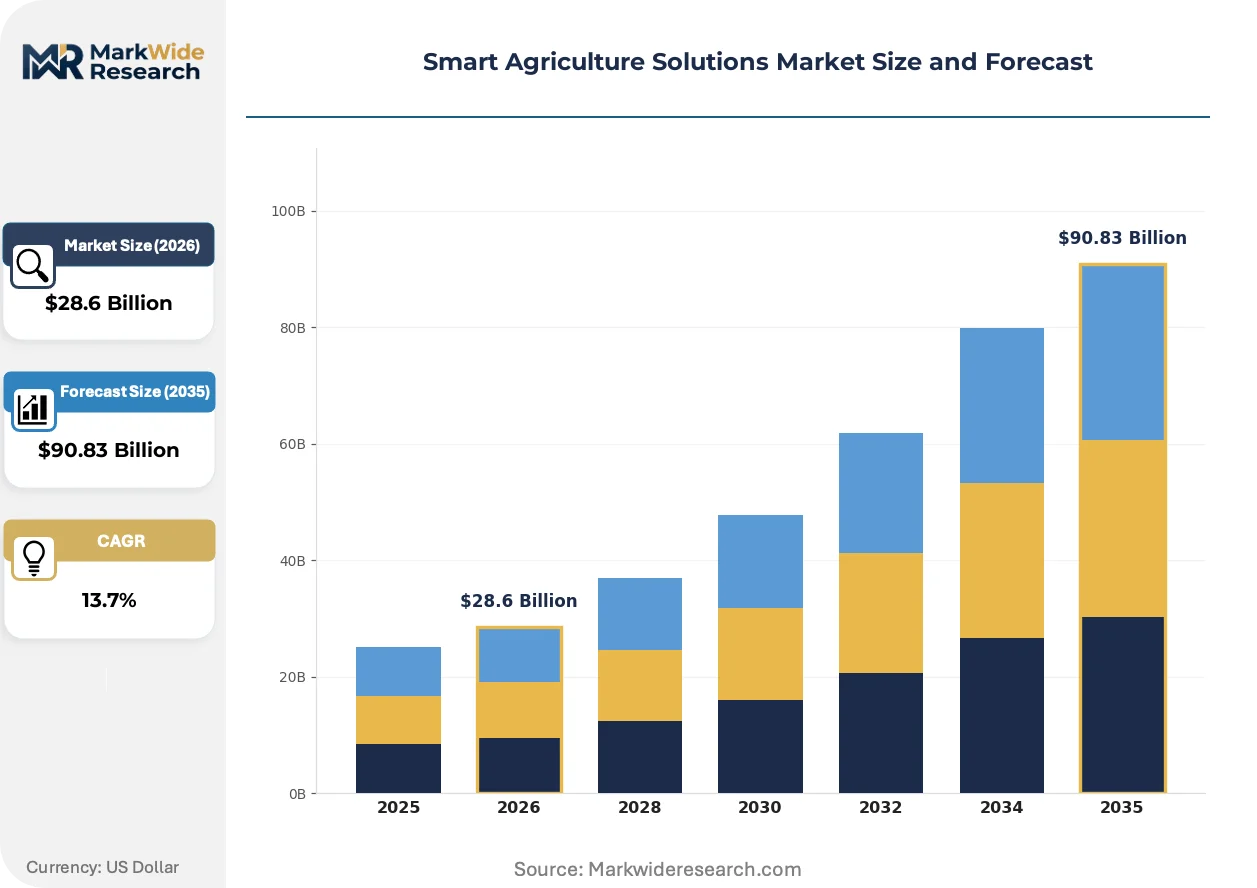
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Systems, Drones, Automation Equipment, Software Platforms Technology: IoT, AI, Machine Learning, GPS End User: Farmers, Agricultural Cooperatives, Food Processors, Research Institutions Application: Crop Monitoring, Irrigation Management, Livestock Tracking, Yield Prediction |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, Topcon Positioning Systems, Raven Industries, CNH Industrial, CLAAS KGaA mbH, DeLaval, Farmers Edge Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Agriculture Solutions Market Strategic Shifts
Cloud-based decision support systems are absorbing margin pools from hardware vendors, while regulatory fragmentation across export destinations forces multi-jurisdiction compliance architectures.
Computer vision-based weed identification is overtaking spectral imaging for targeted herbicide application. Midwestern corn and soybean operations are deploying camera-array sprayers at 3-4x the pace of multispectral sensor adoption. This compression of sensing hardware requirements is collapsing equipment price points and opening precision-ag access to mid-tier acreage holders.
The EU AI Act's risk-classification framework for autonomous agricultural machinery is reshaping product development roadmaps. Manufacturers must now document algorithmic decision trails for field robots operating near human workers. German and Dutch greenhouse operators face the steepest compliance burden, driving consolidation toward vendors with in-house regulatory affairs capacity.
Cooperative procurement consortia are displacing individual farm capital expenditure for autonomous fleet access. Mato Grosso and Iowa grain cooperatives now pool equipment subscriptions through shared-service platforms, unbundling ownership from operation. This shift concentrates buyer power and compresses vendor pricing leverage in high-volume soybean and corn production zones.
Smart Agriculture Solutions Market Segmentation
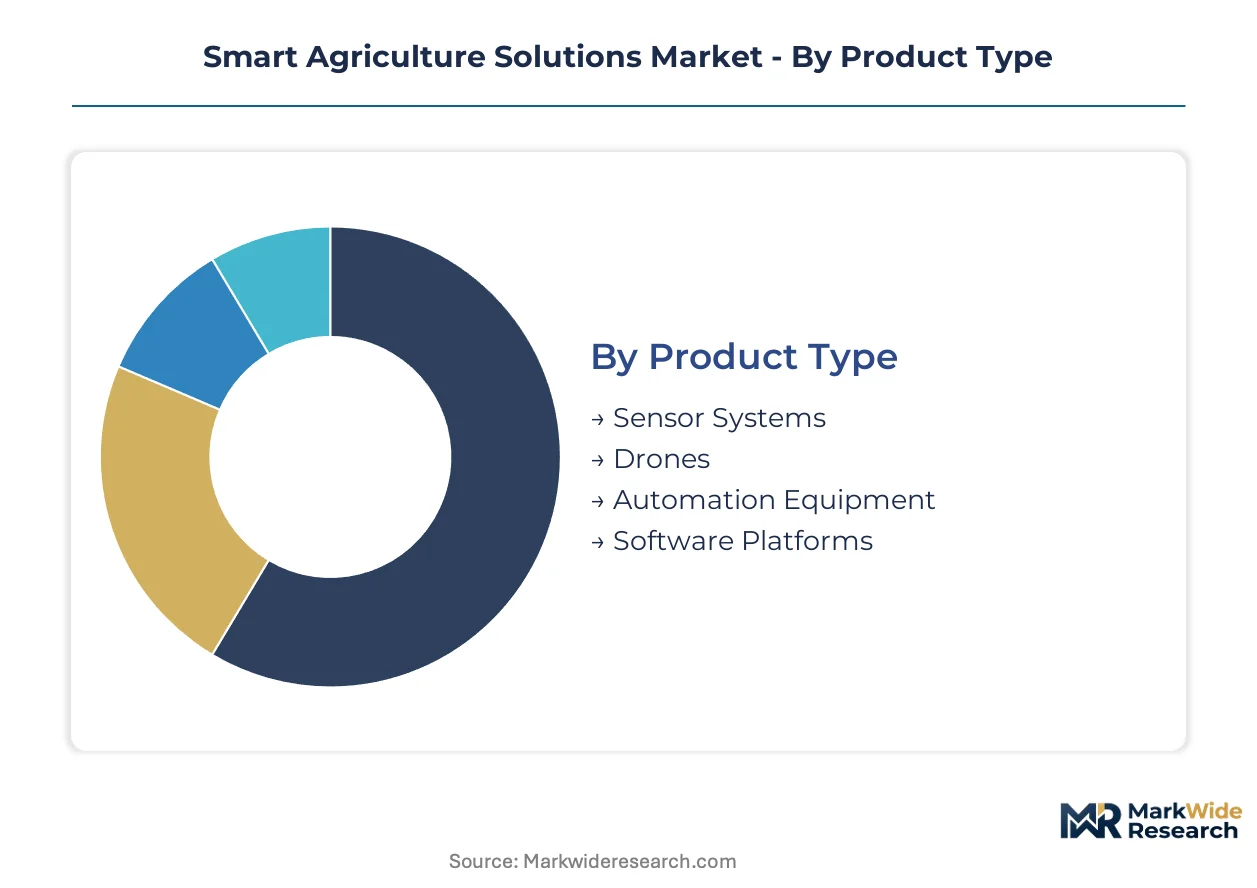
Smart agriculture solutions fragment across four intersecting dimensions that determine procurement patterns and vendor positioning. Equipment buyers prioritize integrated hardware-software stacks, while data-centric operators favor modular platforms with open APIs. Each segmentation axis carries distinct margin profiles and regulatory exposure.
Product Type:
Supply concentration in GPS modules and edge-computing chips favors vendors with captive semiconductor sourcing or long-term foundry partnerships.
- Sensor Systems:Soil moisture, weather, and crop health monitors form the data foundation for variable-rate interventions. Demand clusters in Brazil's Mato Grosso soybean belt and Iowa corn operations where cooperatives deploy dense telemetry arrays. Real-time prescription mapping cuts input waste for high-acreage producers facing carbon-reduction compliance pressure.
- Drones:Aerial platforms for spraying and multispectral imaging operate under EPA Part 107 waivers in the US and evolving EASA frameworks in Europe. German and Dutch greenhouse operators field camera-array units for targeted herbicide application, compressing equipment price points below ground-based alternatives.
- Automation Equipment:Autonomous tractors and robotic harvesters integrate GNSS correction with computer vision guidance.
- Software Platforms:Cloud-based decision support systems command recurring subscription revenue, displacing one-time hardware sales.
Today's leader: Software Platforms. Tomorrow's challenger: Sensor Systems.
Technology:
Cost tier differentiation separates premium integrated stacks from commodity point solutions, with interoperability premiums commanding 20-40% pricing spreads.
- IoT:Mesh networks of field sensors stream telemetry to cloud analytics engines, enabling sub-meter prescription accuracy. Mato Grosso cooperatives deploy LoRaWAN-enabled soil probes at scale, validating payback periods below two growing seasons for soybean operations.
- AI:Computer vision algorithms for weed identification and crop stress detection reshape spraying economics. Midwestern operations adopt camera-based spot treatment at triple the pace of multispectral alternatives, collapsing chemical input costs.
- Machine Learning:Predictive models for yield forecasting and disease outbreak detection improve with seasonal training data accumulation.
- GPS:GNSS correction networks retain the largest installed base among mature automation layers, though proprietary service fragmentation complicates mixed-fleet integration.
Volume concentrates in GPS. Margin expansion favors AI.
End User:
Customer type determines procurement modality, with cooperatives driving fleet-scale subscriptions and individual farms favoring capital purchase.
- Farmers:Owner-operators below 5,000 acres favor modular sensor deployments with low upfront commitment. India's PLI scheme for precision agriculture equipment accelerates domestic IoT adoption among smallholder clusters in Punjab and Haryana.
- Agricultural Cooperatives:Pooled equipment subscriptions displace individual ownership in high-volume production zones. Iowa and Mato Grosso grain cooperatives unbundle fleet access from capital expenditure, compressing vendor pricing leverage.
- Food Processors:FSMA Section 204 traceability mandates drive farm-level digital record integration for supply chain verification.
- Research Institutions:Field trial automation and phenotyping platforms advance breeding program throughput.
Cooperatives anchor current volume. Food processors represent the steepest expansion trajectory.
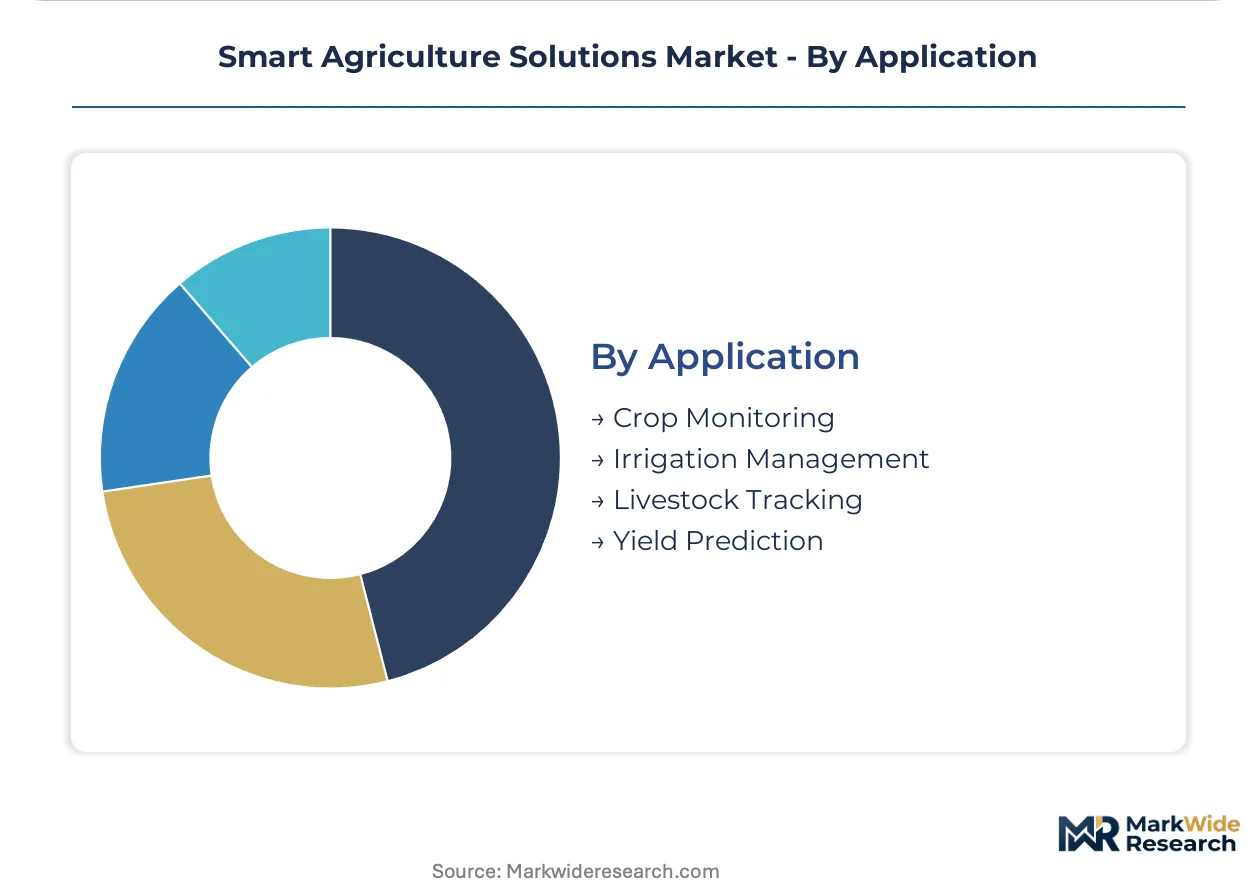
Application:
Maturity gradients separate established guidance systems from emerging analytics categories, with regulatory tailwinds accelerating specific use cases.
- Crop Monitoring:Satellite and drone-based vegetation indexing enables early stress detection across broad acreage. EU Green Deal emissions reporting requirements tighten measurement precision for German and French arable operations.
- Irrigation Management:Soil moisture telemetry integrates with variable-rate valve control, cutting water consumption in water-stressed regions. California's Central Valley and Spain's Ebro basin deploy networked probes under tightening abstraction permits.
- Livestock Tracking:RFID and GPS-enabled herd management systems improve pasture utilization and disease traceability.
- Yield Prediction:Machine learning models combine weather, soil, and historical performance data for harvest forecasting and commodity hedging.
Irrigation Management leads deployment velocity. Yield Prediction holds the highest unrealized value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomic engineering talent clusters in Germany's precision manufacturing belt, Iowa's agricultural engineering corridor, and São Paulo's agtech startup ecosystem. These concentrations anchor equipment innovation and field deployment velocity.
United States
Midwestern corn and soybean operations drive autonomous machinery demand across Iowa and Illinois. EPA Part 107 waivers for drone spraying expand aerial application channels beyond ground-based fleets. California's Central Valley deploys soil moisture telemetry under tightening water abstraction permits.
Brazil
Mato Grosso soybean cooperatives field autonomous spraying fleets at commercial scale. ANVISA regulates agrochemical application protocols for export compliance. The Cerrado biome's expanding mechanized frontier validates payback periods below two growing seasons.
Germany
Carbon-reduction mandates compel equipment retrofits across Baden-Württemberg and Lower Saxony. KBA emissions standards tighten certification timelines for farm machinery. Bavarian precision manufacturers integrate electrified drivetrains into autonomous platforms.
India
Punjab and Haryana smallholders accelerate IoT adoption through PLI scheme incentives for domestic equipment manufacturing. FSSAI traceability requirements drive digital record integration. Karnataka's agtech corridor incubates sensor array localization ventures.
France
Île-de-France and Hauts-de-France grain operations face EU Green Deal emissions reporting requirements. ANSM compliance frameworks extend to controlled-environment agriculture refrigerant choices. The Paris Basin's cooperative procurement consortia pool equipment subscriptions.
Smart Agriculture Solutions Market Competitive Environment
Capital-heavy equipment manufacturers compete with asset-light software platforms across the sector. The market structure consolidates around integrated hardware-software stacks while fragmenting among point-solution specialists. Three archetypes dominate: vertically integrated machinery conglomerates, GNSS correction network operators, and open-architecture platform vendors. M&A activity concentrates buyer power among cooperative procurement consortia, while strategic partnerships bridge interoperability gaps between proprietary correction services.
Within the integrated machinery tier, Deere & Company and CNH Industrial exemplify capital-intensive positioning through captive equipment-and-software stacks. Trimble Inc. anchors the precision technology vector through specialized GNSS and data analytics capabilities. AGCO Corporation occupies the open-architecture position, accommodating mixed-fleet environments for operators avoiding single-vendor lock-in.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| Topcon Positioning Systems |
| Raven Industries |
| CNH Industrial |
| CLAAS KGaA mbH |
| DeLaval |
| Farmers Edge Inc. |
| Others |
Value Chain & Pricing Dynamics
Semiconductor wafer costs cascade through three distinct pricing tiers for precision agriculture equipment, with sensor arrays and autonomous machinery carrying markedly different margin structures from software subscriptions.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated equipment-and-software stacks from modular point solutions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU AI Act risk classifications and ISO 27001 compliance tiers. Cost compression in mid-tier sensor hardware intensifies because camera-array sprayers displace multispectral units at 3-4x adoption velocity. Agricultural cooperatives in Mato Grosso and Iowa exhibit highest price sensitivity through pooled procurement consortia, while North American large-acreage operators show lowest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Reverse-logistics flows for autonomous machinery refurbishment concentrate in Germany's precision manufacturing belt and Iowa's agricultural engineering corridor, where OEMs remanufacture GPS modules and edge-computing units for secondary deployment. Geographic supply concentration centers on Taiwan and South Korea for semiconductor foundry capacity, with China anchoring lithium-ion cell production for autonomous robot power systems. Raw material dependencies include rare-earth elements for GNSS correction network hardware, high-purity silicon for sensor substrates, and cobalt-nickel cathode formulations. Single-source vulnerability in East Asian GPS module sourcing exposes equipment lead times to geopolitical friction. Distribution runs through cooperative procurement platforms in high-volume grain belts and direct OEM sales channels for premium integrated stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is concentrating toward premium precision-ag platforms with sub-meter accuracy specifications and documented algorithmic decision trails under tightening EU AI Act requirements.
For Market Incumbents: Anchor defensive positioning through captive semiconductor sourcing partnerships that insulate against East Asian foundry concentration risk. Deepen backward integration into GNSS correction network infrastructure to prevent disintermediation by open-architecture competitors. Priority investments should target ISO 27001 and IEC 62443 certification acceleration, as cyber-physical compliance timelines currently extend product launches by 8-14 months and create vulnerability to faster-certified entrants. For New Entrants and Emerging Players: Capture white space in India's PLI scheme for domestic precision agriculture equipment manufacturing, where smallholder clusters in Punjab and Haryana remain underpenetrated by incumbent sensor platforms. Target drone spraying service models under EPA Part 107 regulatory clarity, bypassing capital-intensive ground-based fleet competition. Go-to-market execution should emphasize blockchain-IoT convergence for FSMA Section 204 traceability compliance, as food processors face steepest digital record integration mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative procurement consortia concentrate buyer power across Mato Grosso and Iowa grain belts, compressing vendor pricing leverage and squeezing standalone point-solution margins. Long-term viability favors vertically integrated machinery conglomerates with in-house regulatory affairs capacity, particularly those positioned for EU AI Act algorithmic documentation requirements. Signal to monitor: ANVISA export compliance protocol harmonization with FDA traceability standards, which would accelerate cross-border M&A rationale for Brazilian agtech assets.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Cloud Platform Integration | Unifies telemetry streams from Mato Grosso cooperatives into prescription mapping engines with sub-meter accuracy. |
| Regulatory Affairs Capacity Buildout | Accelerates EU AI Act certification timelines for autonomous machinery operating near human workers. |
| Domestic Manufacturing Localization | Captures India's PLI scheme incentives for IoT-enabled farm equipment in Punjab and Haryana clusters. |
| Cooperative Procurement Partnership | Secures volume commitments from Iowa and Mato Grosso grain consortia through shared-service platforms. |
| Blockchain Traceability Certification | Addresses FDA FSMA Section 204 mandates for immutable farm-level digital record systems. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with equipment manufacturers, cooperative procurement managers, precision agriculture software engineers, and regulatory compliance officers at German and Dutch greenhouse operators with secondary validation. Secondary sources included SEC 10-K filings from listed machinery conglomerates, ANVISA agrochemical application protocol databases, EU Green Deal emissions reporting frameworks, and FAO agricultural mechanization statistics. Bottom-up sensor deployment counts and top-down equipment revenue estimates were triangulated to anchor market sizing.
Segment-weighting approaches distributed value across product type, technology layer, end-user archetype, and application maturity dimensions, with additional weighting for regulatory compliance tier under EU AI Act risk classifications. CAGRs were derived from equipment replacement cycle analysis, cooperative subscription penetration curves, and carbon-reduction mandate enforcement timelines across the projection horizon. Forecast inputs incorporated lithium-ion battery energy density improvement trajectories and semiconductor supply concentration risk scenarios.
Underlying measurement precision varies by segment; software platform subscription revenue carries tighter precision than emerging drone spraying service models. Forecasts reflect assumptions around EU AI Act implementation velocity and PLI scheme incentive continuity. Practitioners should monitor ANVISA-FDA regulatory harmonization signals and cooperative procurement consortia formation velocity for early inflection indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Global AI in Agriculture Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Intelligent Agricultural Drone Market