
 Intelligent Agricultural Drone Market | 2026-2036
Intelligent Agricultural Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Agricultural Drone Market Insights
A shift from outsourced spray-service contracts toward in-house multi-rotor fleets is rebalancing procurement patterns across mid-scale farms. SZ DJI Technology Co., Ltd. leverages its manufacturing scale to dominate hardware supply chains in Asia-Pacific markets. XAG Co., Ltd. anchors its position through integrated payload ecosystems spanning seeding, spraying, and crop-dusting modules. Parrot SA differentiates via spectral imaging sensors tailored for precision viticulture and orchard management.
Intelligent agricultural drones are unmanned aerial systems equipped with multispectral cameras, variable-rate applicators, and real-time telemetry for autonomous crop management, typically operating at 10-50 meter altitudes with 20-40 minute flight endurance. Their primary purpose is to convert aerial data into actionable agronomic prescriptions that reduce input waste and improve yield predictability. Multi-rotor platforms capture the dominant share of current deployment due to vertical takeoff flexibility and payload versatility across terrain types. AI Integration represents the fastest-expanding technology segment as edge-computing modules enable real-time pest identification and prescription map generation without ground-station dependency. Fixed-wing configurations retain margin strength in large-acreage row-crop monitoring where endurance and coverage efficiency outweigh maneuverability requirements.
The FAA's Part 107 framework governs commercial operator certification in the United States, while EASA's drone regulation harmonizes airspace access across European Union member states, and China's CAAC implements tiered flight permissions based on aircraft weight and operational risk categories. These regulatory architectures directly shape product design requirements, insurance obligations, and market entry pathways for manufacturers and service providers. Stakeholders must monitor evolving beyond-visual-line-of-sight waiver processes and emerging low-altitude traffic management systems as these will determine scalable deployment economics.
Market Dynamics
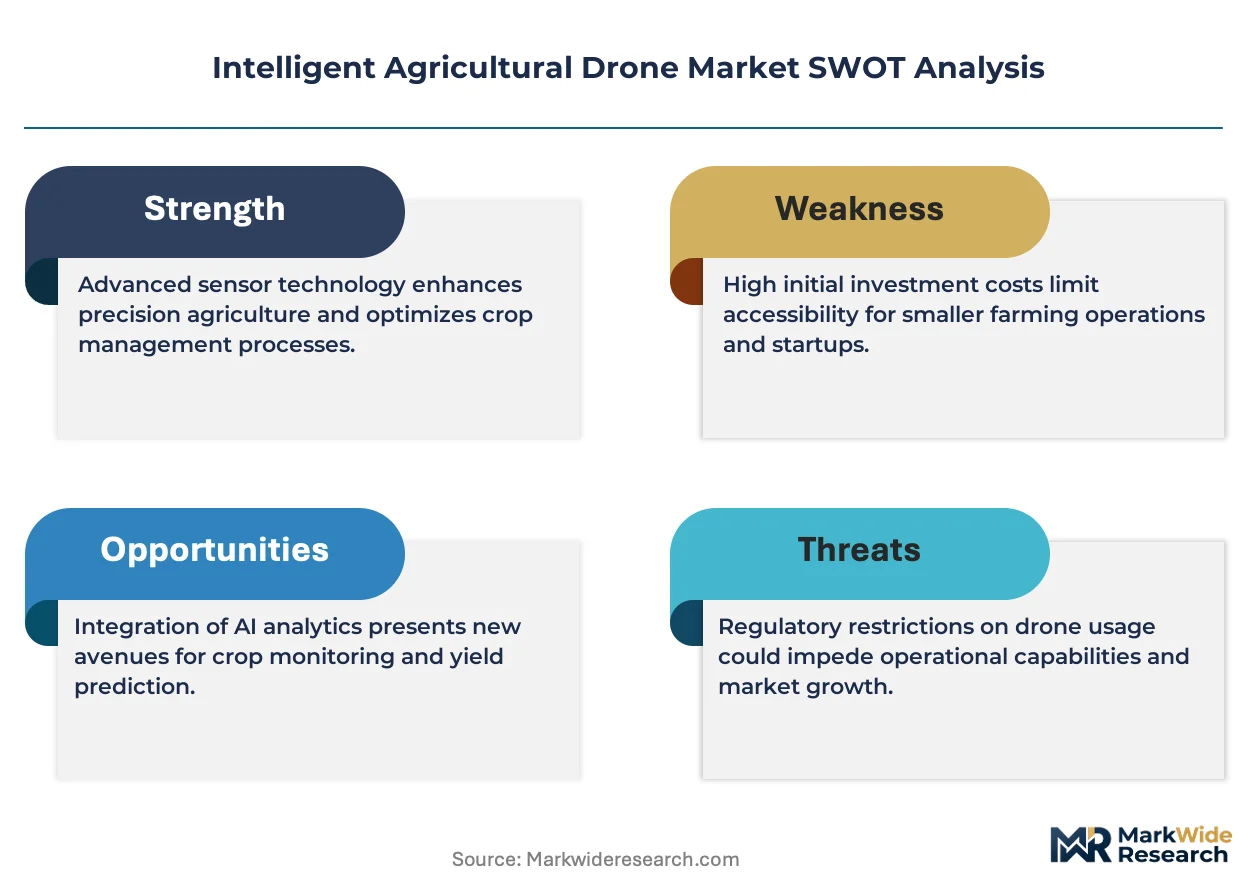
Edge-computing payloads are compressing decision cycles from aerial capture to prescription execution, eliminating ground-station bottlenecks and rewriting fleet economics for mid-scale operators.
Growth Catalysts
- Brazilian Soybean Aerial Spraying:Mato Grosso producers are scaling multi-rotor programs for fungicide application windows, converting timing precision into yield protection.
- FAA Part 107 Certification:Standardized remote pilot requirements in the United States are expanding the compliant service provider base and reducing operator liability exposure.
- Multispectral Sensor Miniaturization:Reduced payload weight is extending flight endurance while maintaining canopy-level imaging resolution for disease detection.
Market Restraints
- Lithium-Polymer Battery Cost Volatility:Cell chemistry price swings directly impact fleet replacement economics for spray-service contractors.
- Hardware Supply Concentration:Shenzhen-centered manufacturing clusters create single-point vulnerability for North American and European distributors.
- Beyond-Visual-Line-of-Sight Waiver Friction:Case-by-case FAA approvals for extended-range operations throttle scalable coverage models in large-acreage row crops.
Strategic Opportunities
- Indian Smallholder Aggregation:Custom hiring centers in Punjab and Haryana offer fleet-sharing models for sub-five-hectare plots currently excluded from drone economics.
- EU Farm-to-Fork Mandates:Pesticide reduction targets under the EU Green Deal are positioning variable-rate application as compliance infrastructure.
- AI-Edge-Lidar Convergence:Real-time canopy height mapping combined with pest identification algorithms enables autonomous spot-spraying without human-in-the-loop verification.
Industry Challenges
- Remote Pilot Skill Scarcity:Agricultural aviation expertise does not translate directly to multi-rotor telemetry management, creating recruitment friction for expanding fleets.
- Legacy Equipment Integration:Existing farm management information systems lack standardized APIs for drone-generated prescription map ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Agricultural Drone Market |
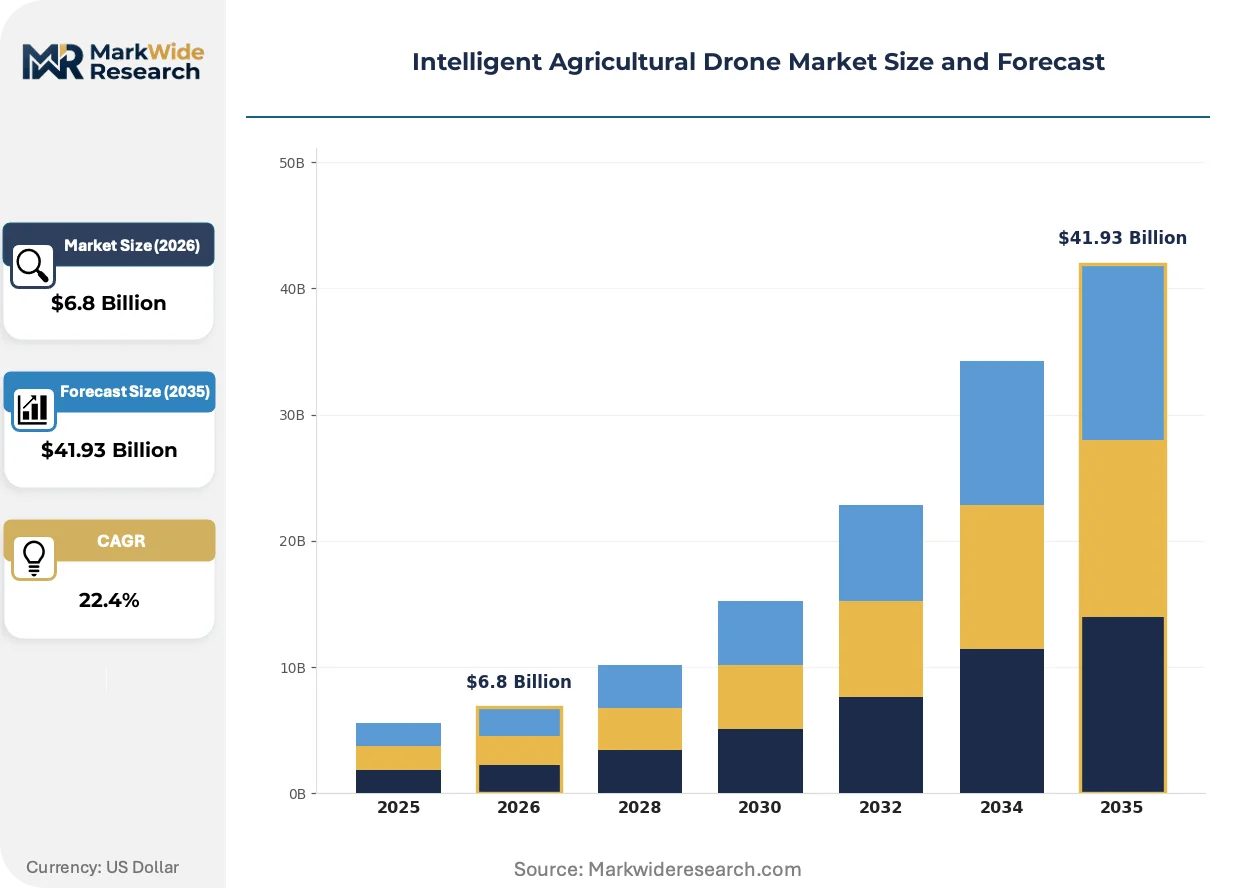
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $41.93 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
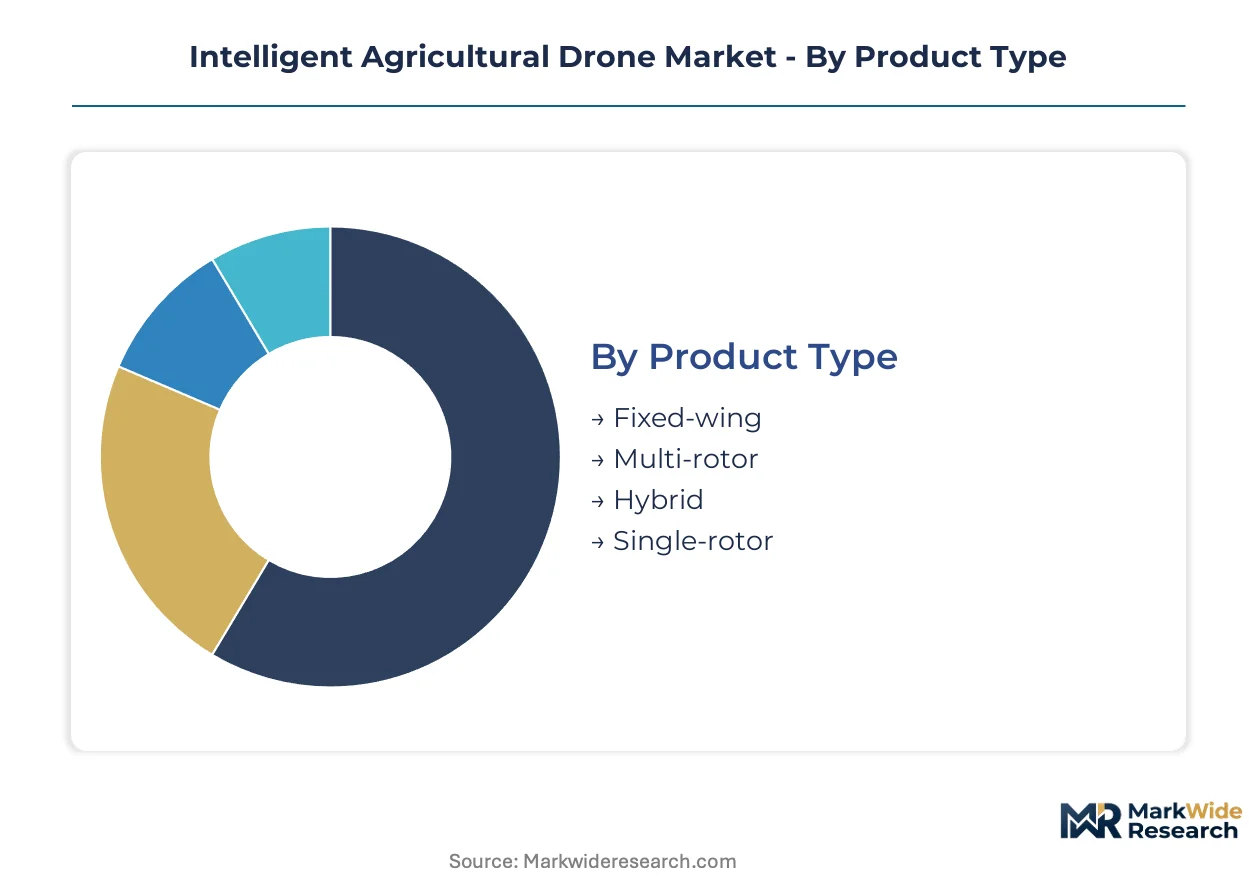
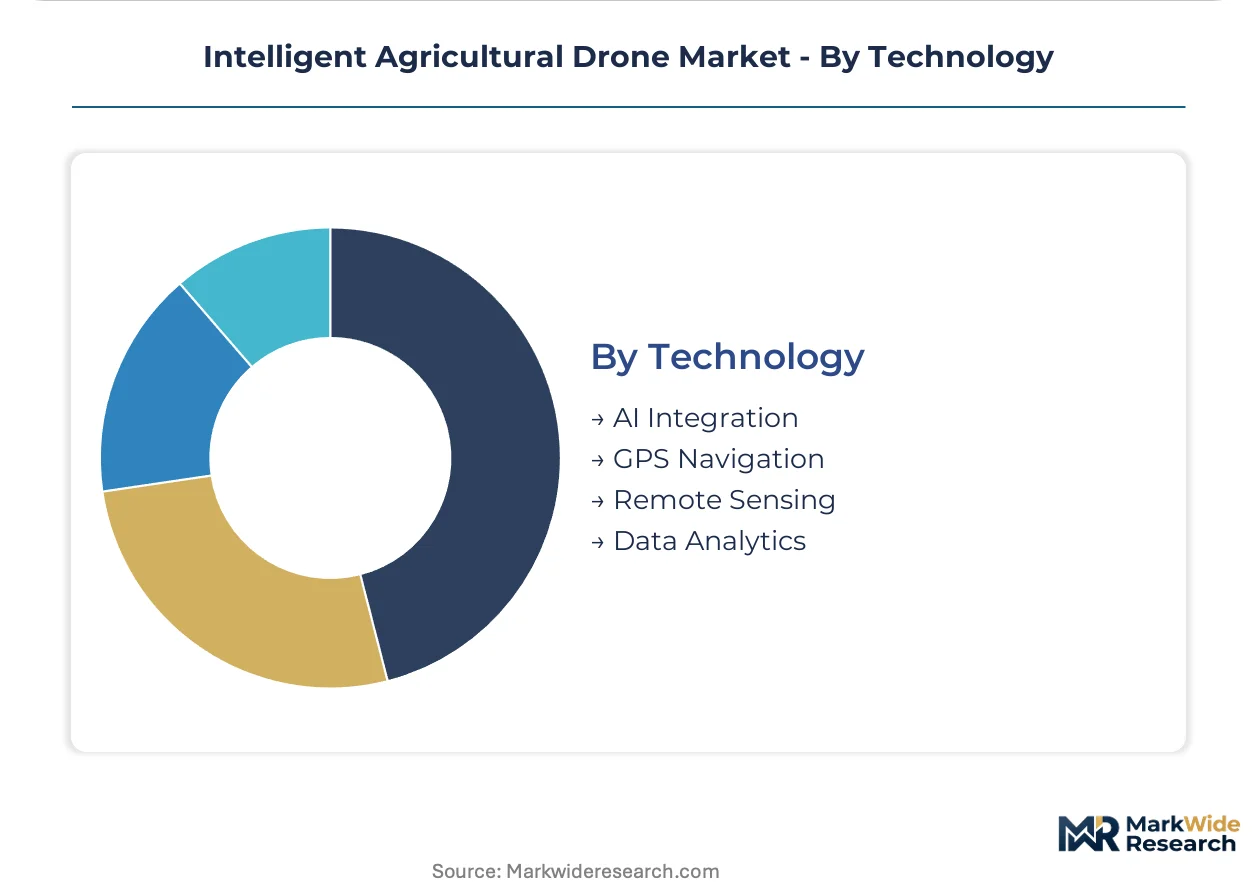
| Segmentation | Product Type: Fixed-wing, Multi-rotor, Hybrid, Single-rotor Application: Crop Monitoring, Pest Control, Irrigation Management, Soil Analysis End User: Farmers, Agricultural Cooperatives, Research Institutions, Agricultural Consultants Technology: AI Integration, GPS Navigation, Remote Sensing, Data Analytics |
| Companies Covered | SZ DJI Technology Co., Ltd., XAG Co., Ltd., Parrot SA, Yamaha Motor Co., Ltd., Trimble Inc., PrecisionHawk, AeroVironment Inc., AgEagle Aerial Systems Inc., Autel Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Agricultural Drone Market Trends and Innovations
Autonomous flight stacks and real-time agronomic AI are collapsing the latency between data capture and field intervention, shifting competitive advantage from hardware specifications to closed-loop prescription accuracy.
Swarm-coordination algorithms are electrifying fleet deployment models for large-scale operations. Brazilian sugarcane processors in São Paulo state are adopting coordinated multi-unit spraying to compress application windows during critical growth stages. This technology is electrifying the economics of outsourced spray services by reducing per-hectare labor requirements and enabling overnight operations.
EASA's harmonized drone regulation across European Union member states is standardizing airspace access and insurance frameworks. Manufacturers now design single-SKU platforms for cross-border deployment rather than jurisdiction-specific variants. French precision viticulture operations in Bordeaux and Champagne are leveraging this regulatory clarity to scale canopy management fleets without national certification fragmentation.
Service contracting is fragmenting into unbundled component purchases. Mid-scale farms in the United States are acquiring hardware directly while purchasing per-acre prescription generation from agronomic software providers. This pattern is most visible in Midwest corn-soy rotations where seasonal timing pressure previously favored full-service outsourcing.
Intelligent Agricultural Drone Market Segmentation
Segmentation in agricultural drones reveals how hardware specifications, operational missions, and user sophistication stratify procurement economics. Each dimension exposes distinct margin structures and vendor positioning strategies across deployment contexts.
Product Type:
Supply concentration in Shenzhen manufacturing clusters tilts component availability toward multi-rotor architectures, yet endurance requirements in large-acreage operations sustain diversified platform development.
- Multi-rotor:Vertical takeoff capability eliminates runway infrastructure requirements. Brazilian soybean producers in Mato Grosso deploy these for fungicide timing windows where terrain variability rules out fixed-wing alternatives. Battery-swappable designs compress turnaround cycles during critical application periods.
- Fixed-wing:Extended endurance and coverage efficiency dominate large-acreage row-crop monitoring. Operators in the United States Midwest favor these for corn-soy prescription mapping where acreage scale outweighs maneuverability tradeoffs. Wing-loading constraints limit payload flexibility.
- Hybrid:VTOL efficiency combined with forward-flight endurance addresses transitional use cases. French viticulture operations trial these for estate-scale canopy management across undulating Bordeaux terrain.
- Single-rotor:Helicopter-style platforms deliver heavy-payload spraying capacity. São Paulo sugarcane processors evaluate these for coordinated swarm applications requiring substantial liquid load.
Today's leader: Multi-rotor. Tomorrow's challenger: Hybrid.
Application:
Cost tier stratification separates diagnostic monitoring from intervention services, with variable-rate application commanding premium positioning.
- Crop Monitoring:Multispectral imaging generates normalized difference vegetation index maps for stress detection. Precision viticulture in Champagne leverages canopy-level resolution for irrigation timing decisions. Edge-computing payloads now enable real-time prescription generation without ground-station dependency.
- Pest Control:Aerial spraying converts timing precision into yield protection. Mato Grosso fungicide programs demonstrate how drone delivery compresses application windows during susceptible growth stages. Regulatory waivers for beyond-visual-line-of-sight operations throttle scalable coverage models.
- Irrigation Management:Thermal sensors identify field moisture variability for variable-rate water deployment. California almond growers integrate these datasets with drip infrastructure for deficit irrigation optimization.
- Soil Analysis:Electromagnetic induction payloads map soil texture and salinity gradients. Australian broadacre wheat operations use these outputs for variable-rate seeding prescriptions.
Diagnostic applications anchor current fleet utilization. Intervention services are climbing the fastest as spray-service economics mature.
End User:
Customer type determines procurement sophistication, from individual operator certification to enterprise fleet management infrastructure.
- Farmers:Individual proprietors drive in-house fleet acquisition among mid-scale operations. United States corn-soy rotations exhibit unbundling patterns where hardware purchases separate from per-acre prescription services.
- Agricultural Cooperatives:Aggregated demand enables shared fleet economics across member holdings. Indian custom hiring centers in Punjab and Haryana deploy this model for sub-five-hectare plots otherwise excluded from drone viability.
- Research Institutions:Methodological rigor requirements prioritize sensor calibration and data reproducibility. European viticulture research programs anchor spectral imaging validation protocols.
- Agricultural Consultants:Service-based revenue models favor flexible payload configurations across client portfolios. Brazilian agronomic advisory firms scale multi-rotor programs through seasonal outsourcing contracts.
Cooperative structures dominate emerging market penetration. Consultant channels are gaining share fastest in mature agricultural economies.
Technology:
Technology maturity curves stratify between proven navigation systems and emerging autonomous capabilities.
- AI Integration:Edge-computing modules enable real-time pest identification and autonomous spot-spraying without human-in-the-loop verification. Lidar convergence with canopy height mapping rewrites prescription accuracy benchmarks.
- GPS Navigation:Centimeter-level RTK correction underlies precision application geometry. FAA Part 107 certification requirements standardize operator proficiency in telemetry management.
- Remote Sensing:Multispectral and thermal payload miniaturization extends flight endurance while maintaining imaging resolution. Sensor weight reduction directly impacts fleet economics for spray-service contractors.
- Data Analytics:Cloud-based prescription generation platforms integrate aerial capture with farm management information systems. API standardization gaps create legacy equipment integration friction.
Navigation infrastructure anchors current deployment. Autonomous AI layers represent the steepest expansion trajectory as edge-computing costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen-centered manufacturing clusters anchor hardware supply chains while operational deployment concentrates in agricultural economies with favorable regulatory frameworks and large-scale farming structures.
United States
Midwest corn-soy rotations drive prescription mapping demand across Illinois and Iowa operations. FAA Part 107 certification standardizes remote pilot proficiency while expanding compliant service provider networks. Kansas and Nebraska operators favor fixed-wing platforms for acreage-scale coverage efficiency.
Brazil
Mato Grosso soybean producers scale multi-rotor fungicide programs during critical application windows. ANVISA pesticide registration requirements shape payload chemistry compatibility standards. São Paulo state sugarcane processors adopt coordinated swarm spraying to compress seasonal labor cycles.
China
CAAC tiered flight permissions govern commercial deployment across Heilongjiang wheat belts and Xinjiang cotton regions. Yangtze River Delta manufacturing ecosystems feed component supply to domestic and export markets. Hubei and Hunan rice operations trial edge-computing payloads for real-time pest identification.
France
Precision viticulture in Champagne and Bordeaux leverages spectral imaging for canopy management and irrigation timing. EASA harmonized drone regulation eliminates cross-border certification fragmentation. Auvergne-Rhône-Alpes orchard operations expand thermal sensor deployment for deficit irrigation optimization.
India
Punjab and Haryana custom hiring centers aggregate smallholder demand for sub-five-hectare plot viability. DGFT import duty structures influence hardware procurement economics for cooperative fleet models. Maharashtra cotton belts pilot variable-rate spraying programs through agronomic advisory channels.
Intelligent Agricultural Drone Market Competitive Landscape
Global majors compete with regional champions across hardware manufacturing and integrated service ecosystems, producing a tiered structure where scale-driven Shenzhen fabricators coexist with application-specialist developers. The vendor base stratifies between full-stack platform providers, component-centric sensor specialists, and regional service integrators. Dominant competitive moves include backward integration into payload manufacturing and geographic expansion through certification harmonization.
Within the full-stack platform tier, SZ DJI Technology Co., Ltd. and XAG Co., Ltd. exemplify manufacturing-scale positioning, while Parrot SA occupies a sensor-specialist niche. These three anchors represent divergent strategic postures: Shenzhen-based volume production, integrated payload ecosystem development, and spectral imaging differentiation respectively.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| XAG Co., Ltd. |
| Parrot SA |
| Yamaha Motor Co., Ltd. |
| Trimble Inc. |
| PrecisionHawk |
| AeroVironment Inc. |
| AgEagle Aerial Systems Inc. |
| Autel Robotics |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FAA Part 107-compliant platforms and uncertified imports manifests in pricing spreads exceeding fifty percent while concentrating procurement leverage among Shenzhen-based fabricators serving tier-one vendors. Hardware manufacturers pass through lithium-polymer cell volatility directly to spray-service contractors, compressing margins for fleet operators locked into annual replacement cycles.
Pricing Analysis
Input-cost pass-through from battery chemistry fluctuations dominates pricing dynamics for multi-rotor fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates RTK-enabled prescription platforms from basic monitoring units, with certification grade and payload integration depth as primary differentiation drivers. Pricing pressure stems from hardware supply concentration in Yangtze River Delta manufacturing clusters. Smallholder cooperatives in India exhibit highest price sensitivity, while Brazilian agro-industrial processors prioritize uptime reliability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Shenzhen-centered component fabrication for flight controllers, gimbal systems, and edge-computing modules. Geographic supply concentration spans China, South Korea, and Taiwan for semiconductor payloads, battery cells, and composite airframes. Raw material dependencies include rare-earth magnets for motor assemblies, lithium carbonate for power systems, and carbon fiber prepregs for airframe construction. Tariff exposure on Chinese-manufactured hardware creates margin risk for North American distributors. Distribution runs through authorized dealer networks and direct-to-farm e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where edge-computing integration and autonomous prescription accuracy now determine vendor viability. Demand is shifting toward premium specifications as mid-scale farms internalize fleet operations and demand closed-loop agronomic performance.
For Market Incumbents: To counter margin compression from Shenzhen manufacturing scale, anchor position through backward integration into payload manufacturing and captive supply of spectral imaging sensors. Secure FAA beyond-visual-line-of-sight waiver precedents to lock in scalable coverage models before regulatory clarity spreads. Deepen channel control via certified service center networks that capture recurring software subscription revenue. For New Entrants and Emerging Players: EASA's harmonized drone regulation across European Union member states opens a window for sensor-specialist positioning without jurisdiction-specific certification fragmentation. White-space targets include French precision viticulture operations seeking canopy-level prescription accuracy and Indian custom hiring centers requiring ruggedized hardware for sub-five-hectare plot economics. Go-to-market angle: unbundled per-acre prescription generation sold separately from hardware. For Investors and Strategic Acquirers: Asymmetric upside sits with edge-computing payload developers possessing real-time pest identification algorithms and lidar convergence capabilities. Long-term viability favors platforms integrating autonomous flight stacks with agronomic decision engines over pure hardware fabricators. Acquisition target archetype: mid-scale software-defined agriculture specialists with proven API integration into farm management information systems. Signal to watch: FAA low-altitude traffic management system deployment timelines as inflection indicator for scalable beyond-visual-line-of-sight economics.| Strategic Initiative | Industry Significance |
|---|---|
| Payload Ecosystem Integration | Combines seeding, spraying, and crop-dusting modules into unified platform architecture for Brazilian soybean operators. |
| Edge-Computing Module Development | Enables real-time prescription generation without ground-station dependency for Mato Grosso fungicide timing windows. |
| Regulatory Certification Harmonization | Eliminates jurisdiction-specific platform variants under EASA framework for French viticulture cross-border deployment. |
| Custom Hiring Center Partnership | Aggregates smallholder demand in Punjab and Haryana for sub-five-hectare plot economic viability. |
| Autonomous Swarm Coordination | Compresses seasonal labor cycles for São Paulo sugarcane processors through overnight coordinated spraying. |
Research Methodology
Direct dialogue with agricultural drone fleet managers, agronomic software developers, FAA certification consultants, and lithium-polymer battery procurement leads grounded qualitative insights in operational reality. Secondary validation drew from CAAC flight permission filings, ANVISA pesticide registration databases, EASA regulatory harmonization directives, and SEC 10-K disclosures from listed hardware manufacturers. Bottom-up fleet deployment estimates triangulated against top-down agricultural input market sizing.
Bottom-up modeling segmented volume and value across product type, application mission, end-user sophistication, and technology maturity, with additional stratification by payload integration depth. CAGRs derived from regression analysis of historical fleet penetration rates against input cost trajectories and regulatory waiver expansion timelines. Forecast inputs included battery chemistry price curves, beyond-visual-line-of-sight approval velocity, and edge-computing cost decline slopes.
Revisions become necessary when FAA low-altitude traffic management deployment stalls, lithium supply disruptions cascade through battery markets, or EASA regulatory harmonization encounters member-state implementation friction. Forecasts reflect documented assumptions about certification pathway timelines and hardware replacement cycle elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Smart Tractor Market