
 Global Agrivoltaics Market | 2026-2036
Global Agrivoltaics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agrivoltaics Market Analysis
Utility-grade agrivoltaic specifications is bifurcating the competitive landscape between premium dual-use developers and conventional ground-mount installers. Sun'Agri leverages proprietary dynamic shading algorithms to dominate French vineyard installations. BayWa r.e. anchors Central European project development through its integrated agricultural advisory services. First Solar extends its thin-film technology leadership into water-stressed agricultural regions where cadmium-telluride heat tolerance delivers measurable yield protection.
Agrivoltaics denotes the co-location of photovoltaic energy generation with active agricultural production, typically deploying elevated solar arrays between 2.5 and 5 meters to maintain mechanized farming access while reducing evapotranspiration stress on understory crops. Bifacial modules capture reflected irradiance from soil and vegetation surfaces, boosting effective capacity factors by 8-20% versus monofacial equivalents in properly configured installations. Crop production applications command the deepest project pipeline as viticulture and soft-fruit operators seek tariff diversification and hail protection. Energy storage attachments represent the fastest-expanding product category as developers add four-hour lithium-ion buffers to satisfy evening grid dispatch windows. Thin-film technology occupies a defensible niche in high-temperature, high-humidity growing environments where silicon degradation accelerates.
The EU Green Deal and F-Gas Regulation shape European deployment timelines by mandating circularity standards for module recycling and restricting fluorinated greenhouse gases in inverter cooling systems. Japan's METI feed-in tariff revisions for agricultural land use require dual-income verification before interconnection approval, filtering speculative developers from qualified operators. The USDA and EPA coordinate American soil conservation compliance for solar-ground-disturbance permits on cultivated acreage. Stakeholders must monitor evolving land-use classification disputes between energy regulators and agricultural ministries that threaten project bankability in multi-jurisdictional developments.
Market Dynamics
Bifacial module architecture is decomposing legacy monofacial deployment economics across water-stressed agricultural zones, compressing levelized cost thresholds while elevating yield protection requirements for dual-use developers.
Growth Catalysts
- EU Green Deal circularity mandates:Module recycling standards and fluorinated gas restrictions under the F-Gas Regulation accelerate certified developer qualification in France and Germany.
- Japanese agricultural land-use verification:METI feed-in tariff revisions requiring dual-income documentation filter speculative entrants and validate bankable project pipelines.
- Dynamic shading algorithms:Proprietary light-management software enables precision viticulture applications, expanding addressable acreage for specialty crop operators seeking hail protection.
Market Restraints
- Elevated structural steel costs:Mounting systems requiring 2.5-5 meter clearances consume disproportionate material tonnage versus conventional ground-mount arrays.
- Polysilicon supply concentration:Upstream ingot and wafer capacity clusters in specific manufacturing geographies expose project timelines to trade policy volatility.
- Interconnection queue congestion:Agricultural land-use reclassification disputes between energy regulators and agricultural ministries delay permitting in multi-jurisdictional developments.
Strategic Opportunities
- Four-hour lithium-ion storage attachment:Evening grid dispatch requirements create new revenue stacking for developers integrating battery buffers with solar generation.
- Soft-fruit and berry cultivation:Underpenetrated high-value horticulture segments in water-stressed regions offer premium tariff diversification potential.
- USDA soil conservation coordination:Federal compliance pathways for solar-ground-disturbance permits on cultivated acreage streamline American project development.
Industry Challenges
- Agronomic-electrical skill integration:Project teams lack unified expertise spanning crop science, electrical engineering, and land-use law simultaneously.
- Thin-film certification timelines:Cadmium-telluride heat-tolerance validation for humid growing environments extends product qualification cycles.
- Legacy inverter cooling retrofits:F-Gas Regulation restrictions on fluorinated greenhouse gases force equipment swaps in existing European installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agrivoltaics Market |
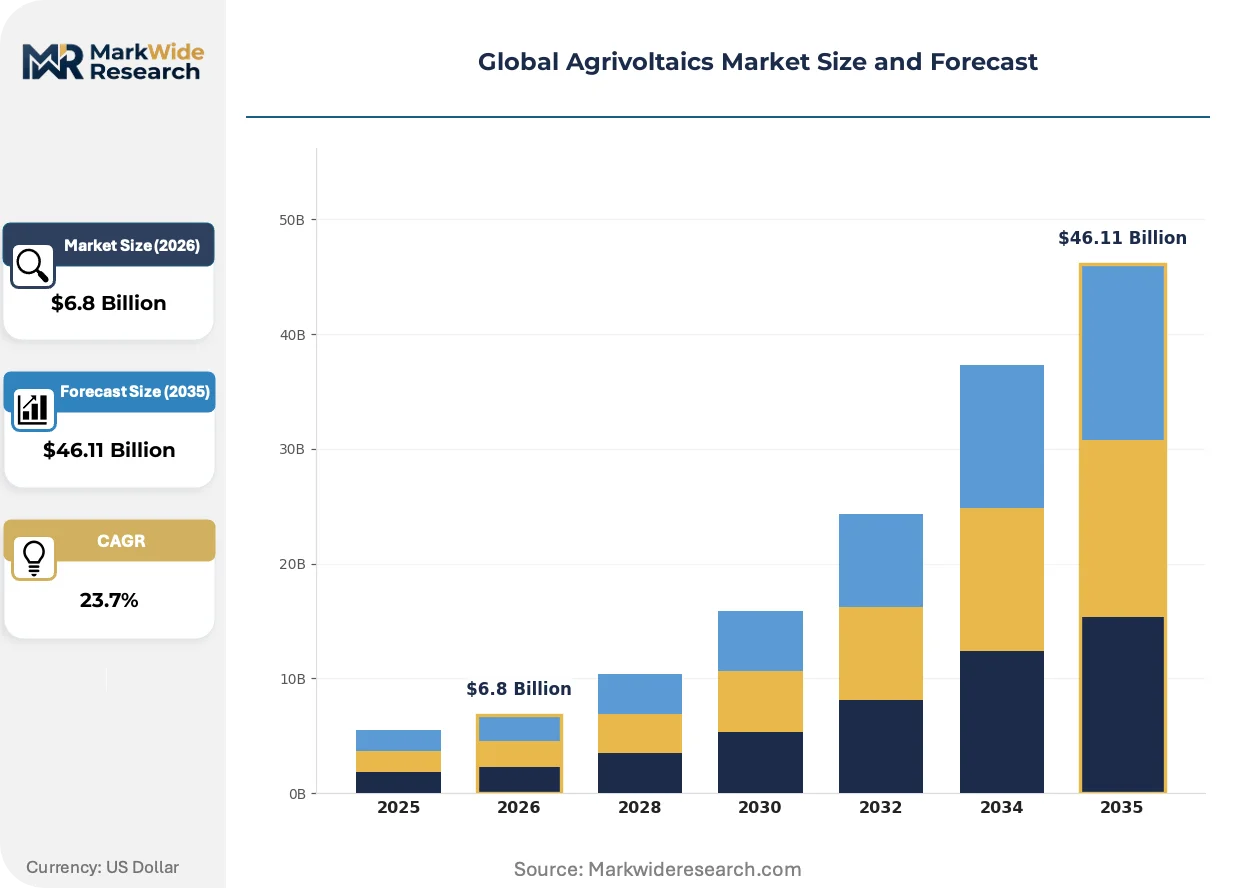
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $46.11 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
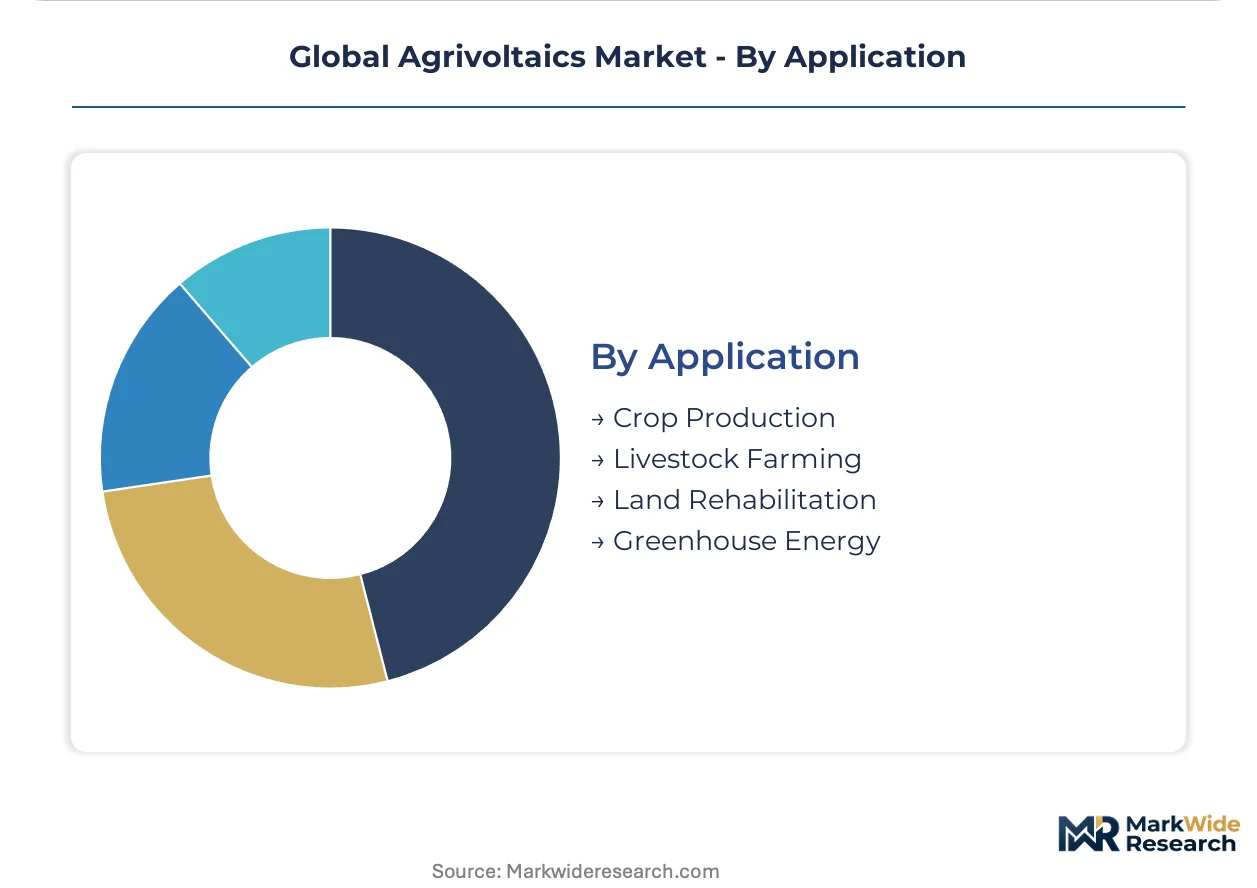
| Segmentation | Product Type: Solar Panels, Inverters, Mounting Structures, Energy Storage End User: Agricultural Producers, Energy Providers, Research Institutions, Farmers Technology: Mono-Silicon, Poly-Silicon, Thin-Film, Bifacial Modules Application: Crop Production, Livestock Farming, Land Rehabilitation, Greenhouse Energy |
| Companies Covered | Sun'Agri, BayWa r.e., Enel Green Power, Next2Sun, EDF Renewables, Akuo Energy, Insolight, First Solar, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agrivoltaics Market Emerging Trajectories
Active decomposition of conventional solar deployment models is reshaping how energy and agricultural output get priced, financed, and regulated across dual-use land applications.
Bifacial photovoltaic architecture is decomposing monofacial capacity factor assumptions by capturing reflected irradiance from soil and vegetation surfaces. Viticulture operators in France and Germany are adopting these systems fastest, driven by hail protection requirements and mechanized harvesting access needs. The technology is decomposing traditional boundaries between energy yield optimization and crop stress management, forcing developers to model trade-offs dynamically.
The EU F-Gas Regulation and circularity standards under the Green Deal are restricting fluorinated greenhouse gases in inverter cooling systems and mandating module recycling infrastructure. These rules compress deployment timelines for developers lacking certified end-of-life partnerships. French vineyard installations face the steepest compliance ramps, with ANSM and CNIL oversight extending into environmental impact assessments.
Specialty crop growers are unbundling energy and agricultural revenue streams, demanding separate metering and distinct offtake contracts for electrons versus produce. This behavior disrupts integrated developer business models predicated on consolidated project finance. The shift is most visible in Japanese pilot programs where METI verification requirements force operational transparency before interconnection approval.
Global Agrivoltaics Market Segmentation
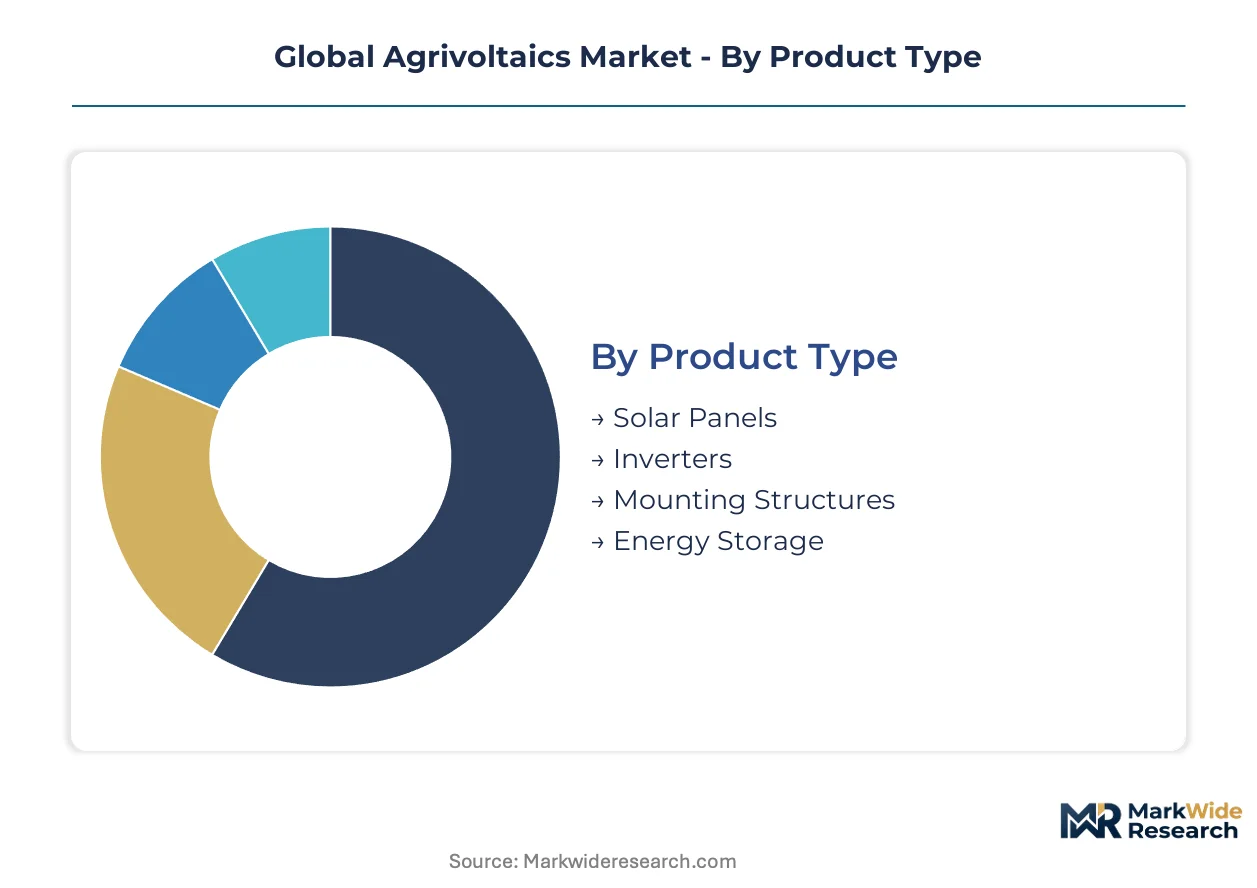
Agrivoltaic deployment economics diverge sharply across product configurations and end-use applications. Technology choices determine structural steel requirements and shading algorithms, while application types dictate regulatory compliance pathways and revenue stacking models.
Product Type:
EU F-Gas Regulation circularity mandates and Japanese METI feed-in tariff revisions differentiate certified component suppliers from uncertified entrants across module, inverter, and storage categories.
- Solar Panels:Bifacial crystalline silicon dominates French vineyard installations due to reflected irradiance capture from soil and vegetation surfaces. Elevated mounting requirements between 2.5 and 5 meters constrain module weight specifications and frame durability standards.
- Energy Storage:Four-hour lithium-ion buffers satisfy evening grid dispatch windows in Japanese agricultural pilots. METI dual-income verification requirements force separate metering architectures for electron versus produce revenue streams.
- Inverters:Fluorinated greenhouse gas restrictions under EU regulations accelerate cooling system retrofits and equipment swaps.
- Mounting Structures:Disproportionate steel tonnage consumption versus conventional ground-mount arrays elevates material cost exposure.
Established volume favors Solar Panels; emerging adoption favors Energy Storage.
End User:
Revenue model complexity separates operators with unified agricultural-electrical expertise from those dependent on external advisory services.
- Agricultural Producers:Specialty crop growers in France unbundle energy and agricultural revenue streams through distinct offtake contracts. Hail protection requirements and mechanized harvesting access needs drive premium specifications.
- Research Institutions:German and Japanese pilots validate bifacial module performance on arable land with dual-income documentation requirements. Operational transparency mandates filter speculative developers from qualified operators.
- Energy Providers:Grid interconnection queue congestion and land-use reclassification disputes delay multi-jurisdictional project permitting.
- Farmers:Soil conservation compliance under USDA and EPA coordination shapes American solar-ground-disturbance permit timelines.
Commercial maturity concentrates with Agricultural Producers; pilot scale expansion concentrates with Research Institutions.
Technology:
Heat tolerance and humidity degradation resistance determine technology selection in water-stressed growing environments.
- Bifacial Modules:Reflected irradiance capture from soil and vegetation surfaces boosts effective capacity factors. Dynamic shading algorithms enable precision viticulture applications with hail protection integration.
- Thin-Film:Cadmium-telluride chemistry occupies defensible niches in high-temperature, high-humidity environments where silicon degradation accelerates. Product qualification cycles extend due to heat-tolerance validation requirements.
- Mono-Silicon:Polysilicon supply concentration in specific manufacturing geographies exposes project timelines to trade policy volatility.
- Poly-Silicon:Upstream ingot and wafer capacity clustering creates upstream bottleneck risk.
Performance leadership belongs to Bifacial Modules; environmental resilience specialization belongs to Thin-Film.
Application:
Crop selection and land-use classification disputes between energy regulators and agricultural ministries determine project bankability.
- Crop Production:Viticulture and soft-fruit operators command the deepest project pipeline. Mechanized farming access requirements and evapotranspiration stress reduction drive elevated array specifications.
- Greenhouse Energy:Underpenetrated high-value horticulture segments in water-stressed regions offer premium tariff diversification potential with integrated climate control.
- Livestock Farming:Shade provision and water point electrification create secondary revenue streams in pastoral zones.
- Land Rehabilitation:Degraded acreage reclassification disputes complicate permitting in multi-jurisdictional developments.
Deployment scale advantages Crop Production; margin expansion advantages Greenhouse Energy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented module supply chains from China and Southeast Asia feed installation demand concentrated in European and Japanese agricultural zones, while domestic content requirements in the United States reshape procurement patterns for steel mounting structures and electrical components.
France
Specialty crop growers in Bordeaux and Provence deploy elevated arrays for hail protection and mechanized vineyard access. ANSM and CNIL oversight extends environmental impact assessments under EU Green Deal circularity mandates. The Occitanie region hosts concentrated pilot installations validating dynamic shading algorithms for precision viticulture.
Germany
Research institutions in Bavaria and Baden-Württemberg pilot bifacial systems on arable land with dual-income documentation requirements. The F-Gas Regulation restricts fluorinated greenhouse gases in inverter cooling systems, accelerating equipment retrofits. KBA certification protocols shape mounting structure safety standards for mechanized farming clearances.
Japan
METI feed-in tariff revisions require agricultural land-use verification and dual-income documentation before interconnection approval. Research clusters in Chubu and Kyushu validate elevated array performance on rice paddies and tea plantations. Operational transparency mandates filter speculative developers from qualified operators in pilot programs.
United States
USDA and EPA coordination shapes soil conservation compliance for solar-ground-disturbance permits on cultivated acreage in California and the Midwest. The Inflation Reduction Act production tax credits incentivize domestic content procurement for steel mounting structures. Water-stressed regions in the Southwest drive demand for thin-film heat tolerance in high-temperature growing environments.
China
Polysilicon and wafer manufacturing clusters in Xinjiang and Inner Mongolia supply upstream components for global agrivoltaic deployment. MIIT industrial policy guides bifacial module standardization for agricultural applications. Yangtze River Delta integrators export complete elevated mounting systems to European and Japanese project developers.
Global Agrivoltaics Market Vendor Landscape
Listed solar majors compete with private agrivoltaic specialists across technology integration and agricultural advisory capabilities. The competitive landscape fragments between premium dual-use developers with proprietary software and conventional ground-mount installers adapting elevated structural specifications. Two archetypes dominate: integrated agricultural-electrical service providers and technology-focused module suppliers. Strategic moves concentrate on vertical integration into mounting structure manufacturing and partnerships with crop science research institutions.
Within the integrated service tier, Sun'Agri and BayWa r.e. exemplify developers combining proprietary dynamic shading algorithms with agricultural advisory capabilities. First Solar anchors the thin-film technology vector for water-stressed regions. These three occupy positions spanning French vineyard deployment, Central European project development, and cadmium-telluride heat tolerance specialization respectively.
| Leading Market Players |
|---|
| Sun'Agri |
| BayWa r.e. |
| Enel Green Power |
| Next2Sun |
| EDF Renewables |
| Akuo Energy |
| Insolight |
| First Solar |
| Trina Solar |
| Others |
Supply Flow & Price Mechanics
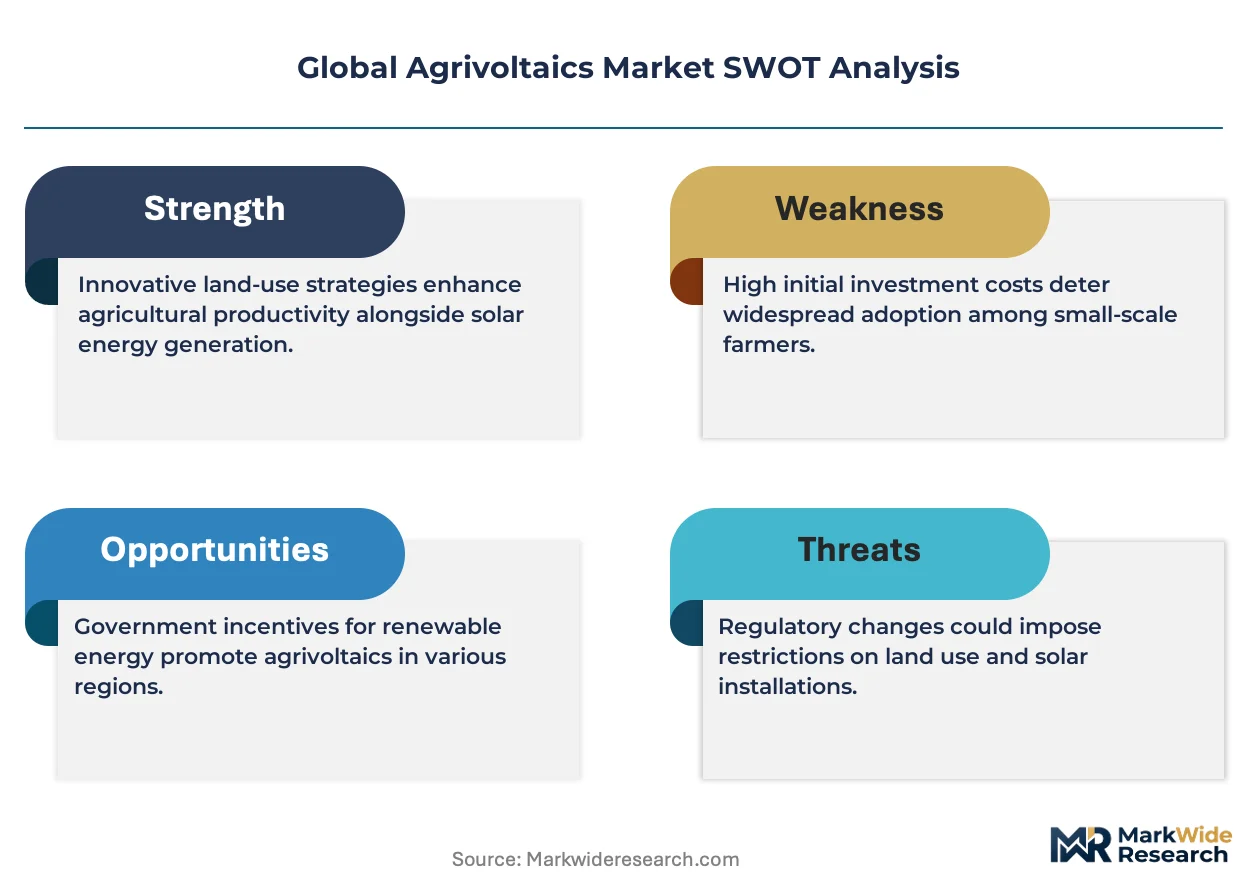
EU F-Gas Regulation certification gates both module supplier qualification and inverter pricing tiers simultaneously, compressing margins for uncertified entrants while rewarding compliant developers with premium positioning in French and German procurement channels.
Pricing Analysis
Industrial OEM buyers anchor project-based contract structures across agrivoltaic deployments. Three-tier pricing stratifies across premium certified systems, standard compliant arrays, and economy non-certified alternatives. Price differentiation rests on dual-income verification documentation and dynamic shading algorithm integration. Cost compression in economy tiers intensifies because polysilicon supply volatility forces uncertified developers into spot market exposure.
Supply Chain Analysis
China and Southeast Asia anchor polysilicon ingot and wafer manufacturing clusters feeding global module assembly. Raw material dependencies draw from Xinjiang polysilicon, Yangtze River Delta cell fabrication, and European steel mounting structure forging. Supply chain risk centers on single-source vulnerability for elevated array structural components. Distribution runs through integrated EPC contractors with captive agricultural advisory capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward agricultural producers with unified electrical-agronomic expertise, justified by consolidation among specialty crop operators demanding separate metering architectures.
For Market Incumbents: Fortify proprietary dynamic shading algorithm portfolios through backward integration into sensor hardware manufacturing. Defend against emerging thin-film specialists by securing cadmium-telluride heat-tolerance certifications for humid growing environments. Channel control over agricultural advisory services represents the critical lever. For New Entrants and Emerging Players: Agronomic-electrical skill integration gaps in incumbent service models create entry points for vertically specialized consultancies. Underpenetrated soft-fruit and berry cultivation in water-stressed American Southwest offers the most penetrable segment. Go-to-market positioning should emphasize USDA soil conservation compliance pathway navigation. For Investors and Strategic Acquirers: Japanese METI feed-in tariff revisions reshape the acquisition landscape toward dual-income verification capabilities. Long-term viability favors developers with operational transparency infrastructure spanning five-to-ten year project horizons. Acquisition targets should demonstrate proven agricultural land-use reclassification expertise. The signal to monitor is interconnection queue processing velocity in multi-jurisdictional developments.| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Shading Algorithm Patent Portfolio Expansion | Proprietary light-management software locks in French vineyard developer relationships against BayWa r.e. competition. |
| Four-Hour Lithium-Ion Storage Integration | Battery buffer attachments satisfy METI evening dispatch requirements in Japanese agricultural pilots. |
| Cadmium-Telluride Heat Tolerance Certification | Thin-film validation opens water-stressed Southwest American markets where silicon degrades rapidly. |
| USDA Soil Conservation Compliance Partnership | Federal permit streamlining accelerates Midwest project development timelines against conventional ground-mount competitors. |
| Elevated Mounting Structure Steel Forging Integration | Captive structural component supply insulates against material cost volatility in 2.5-5 meter clearance specifications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with viticulture operators, agrivoltaic EPC contractors, agricultural land-use attorneys, and METI verification officers. Secondary validation drew from EU Green Deal circularity mandate filings, F-Gas Regulation compliance databases, USDA solar-ground-disturbance permit records, and Japanese agricultural land-use reclassification decisions. Bottom-up project pipeline enumeration triangulated against top-down module shipment aggregation across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning technology type, application category, end-user archetype, and regional regulatory cluster. CAGRs were derived from installation capacity buildout trajectories validated against polysilicon supply expansion forecasts and agricultural land availability constraints. Industry-specific inputs incorporated bifacial module performance coefficients and elevated mounting structure steel tonnage requirements.
Forecasts assume regulatory continuity in EU F-Gas enforcement and Japanese METI verification protocols; material policy shifts would require re-modeling. Specific risks include land-use classification disputes between energy regulators and agricultural ministries, trade policy volatility affecting polysilicon supply, and inverter cooling system retrofit mandates. Recalibration cycles align with material shifts in module recycling standard adoption and feed-in tariff revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Smart Tractor Market