
 Smart Livestock Farming Market | 2026-2036
Smart Livestock Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Livestock Farming Market Insights
The capital-intensity divergence between automated milking specialists and sensor-software integrators is rotating competitive advantage toward full-stack platform providers. DeLaval leverages its vertical integration across robotic milking and herd management software to command premium positioning in European dairy. Nedap N.V. anchors its growth on wearable sensor networks that sustain recurring revenue through subscription analytics. GEA Farm Technologies competes through manufacturing scale in automated feeding infrastructure across German and Danish farm cooperatives.
Smart livestock farming encompasses integrated hardware-software systems that deploy IoT devices, wearable sensors, and RFID tags to monitor animal health, optimize feed conversion ratios, and automate barn climate control with precision measured to individual animal granularity. Its primary commercial purpose is to reduce veterinary intervention costs while maximizing yield per head through data-driven husbandry. IoT Devices and wearable sensors capture the strongest margin pools as hardware margins compound with recurring analytics fees, while RFID remains mature with price-commoditized tag production. Automated Feeding Systems lead capital deployment among product types, though Health Analytics Platforms are expanding fastest as veterinary labor shortages intensify across large farm end users.
EU Green Deal nitrogen regulations and F-Gas barn climate standards are tightening equipment specifications across European livestock operations, directly shaping OEM product roadmaps and farm upgrade cycles. The US FDA and USDA jointly influence antimicrobial traceability requirements that accelerate sensor-based health record adoption. Stakeholders must monitor whether EU AI Act risk classifications will subject autonomous livestock decision systems to mandatory conformity assessments, altering vendor compliance burdens and market access conditions.
Market Dynamics
EU Green Deal nitrogen emission caps are forcing Dutch and Danish dairy cooperatives into accelerated sensor deployment cycles, compressing equipment replacement timelines from seven-year cycles to four-year rotations.
Growth Catalysts
- EU F-Gas Regulation:Barn climate control equipment upgrades across German livestock operations are mandating refrigerant transitions that favor precision HVAC systems with integrated IoT monitoring.
- Veterinary labor shortages:Large farm end users in the US and Australia are automating health monitoring to offset persistent gaps in on-farm animal health professionals.
- Feed conversion optimization:Automated rationing systems that calibrate to individual metabolic markers are capturing capital allocation from traditional batch-feeding infrastructure.
Market Restraints
- Sensor hardware cost volatility:MEMS component supply concentrates in Taiwanese foundries, exposing European OEMs to input price swings and extended lead times.
- Rural broadband deficits:4G and 5G coverage gaps across Australian outback and US Great Plains regions limit real-time data transmission for cloud-dependent analytics platforms.
- Legacy barn infrastructure:Post-war concrete structures across Northern France and Belgium lack load-bearing capacity for robotic milking arm installations without structural reinforcement.
Strategic Opportunities
- Brazilian pasture-to-barn transition:Beef operations in Mato Grosso and Goiás states are consolidating into feedlot models that create first-time demand for climate control and feeding automation.
- EU AI Act compliance services:Autonomous decision systems for livestock health interventions will require conformity assessments, opening advisory and certification revenue streams for technology vendors.
- Edge computing convergence:On-farm processing units that reduce cloud dependency are enabling real-time analytics in bandwidth-constrained environments across rural Canada and Argentina.
Industry Challenges
- Data science talent scarcity:Farm management software vendors compete with fintech and e-commerce sectors for machine learning engineers capable of building predictive health models.
- Interoperability fragmentation:Proprietary data protocols from DeLaval, Nedap, and GEA prevent seamless integration across mixed-equipment barns, forcing costly middleware development.
- Cybersecurity certification timelines:IEC 62443 compliance for industrial IoT devices delays product launches by 8-14 months as penetration testing and documentation requirements expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Livestock Farming Market |
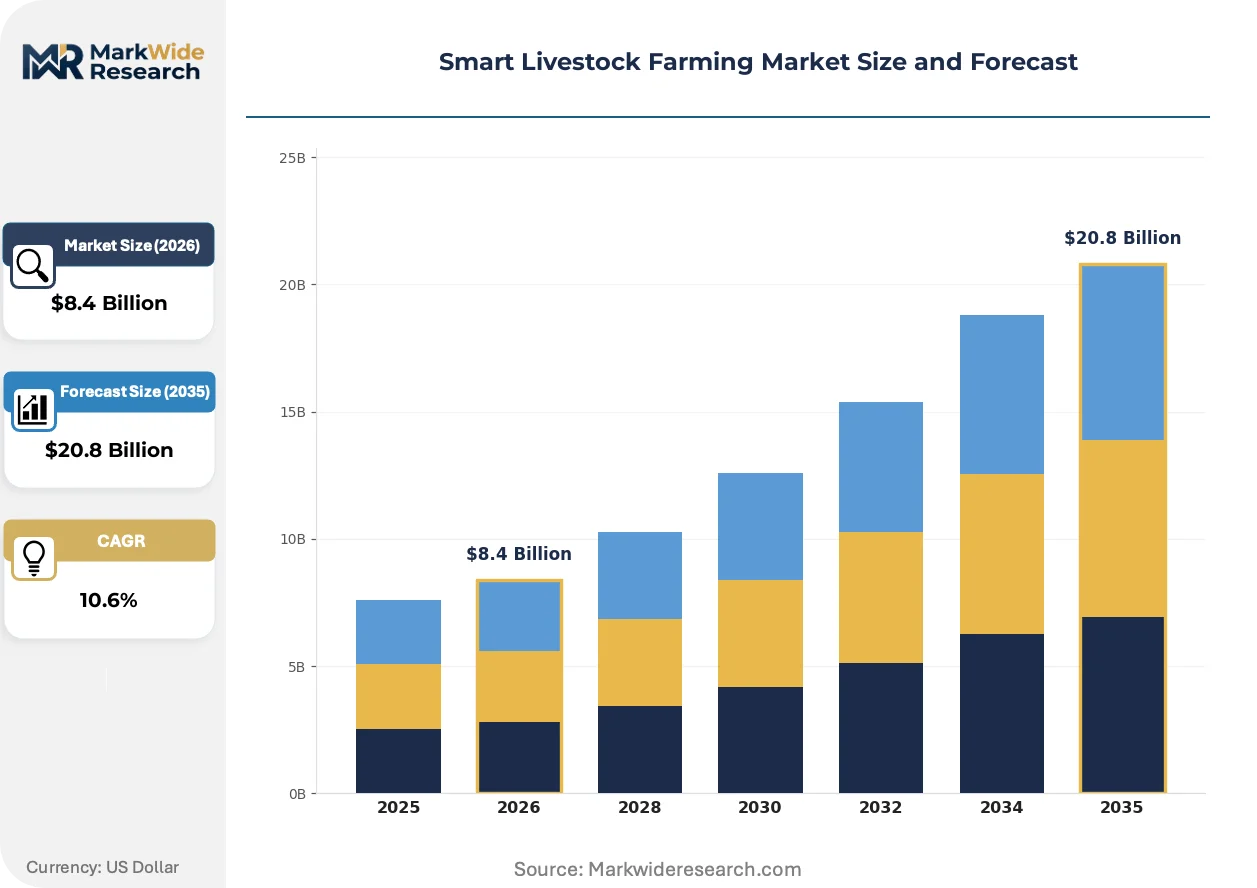
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $20.8 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, Drones, Wearable Sensors, RFID Application: Feeding Management, Health Monitoring, Breeding Optimization, Farm Management End User: Large Farms, Medium Farms, Small Farms, Cooperatives Product Type: Feed Monitoring Systems, Health Analytics Platforms, Livestock Tracking Solutions, Automated Feeding Systems |
| Companies Covered | DeLaval, GEA Farm Technologies, Afimilk Ltd, Allflex Livestock Intelligence, BouMatic, Lely International, Nedap N.V., Dairymaster, Fancom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Livestock Farming Market Trends and Innovations
Computer vision systems for lameness detection and feed intake monitoring are migrating from pilot installations to commercial scale, altering capital deployment patterns across dairy and swine operations.
Multispectral imaging cameras mounted on automated barn robots are displacing manual hoof inspection routines and subjective visual scoring methods. Large dairy cooperatives in the Netherlands and Wisconsin are deploying these systems across 500-plus head facilities. The technology is displacing veterinary technician hours while compressing early disease detection windows from days to hours.
REACH chemical registration requirements and F-Gas phase-down schedules are tightening material specifications for antimicrobial coatings and refrigerants in livestock housing equipment. German and Danish OEMs are reformulating product lines to eliminate restricted substances ahead of 2027 deadlines. Automated feeding system manufacturers face accelerated R&D cycles to maintain EU market access.
Service unbundling is separating hardware sales from analytics subscriptions, with buyers in New Zealand and Ireland demanding modular contracts that permit third-party software integration. Traditional bundled pricing is yielding to componentized procurement where farms source sensors from one vendor and cloud platforms from another. This pattern is most visible in pasture-based dairy systems where seasonal labor fluctuations drive preference for flexible, short-term software licenses.
Smart Livestock Farming Market Segmentation
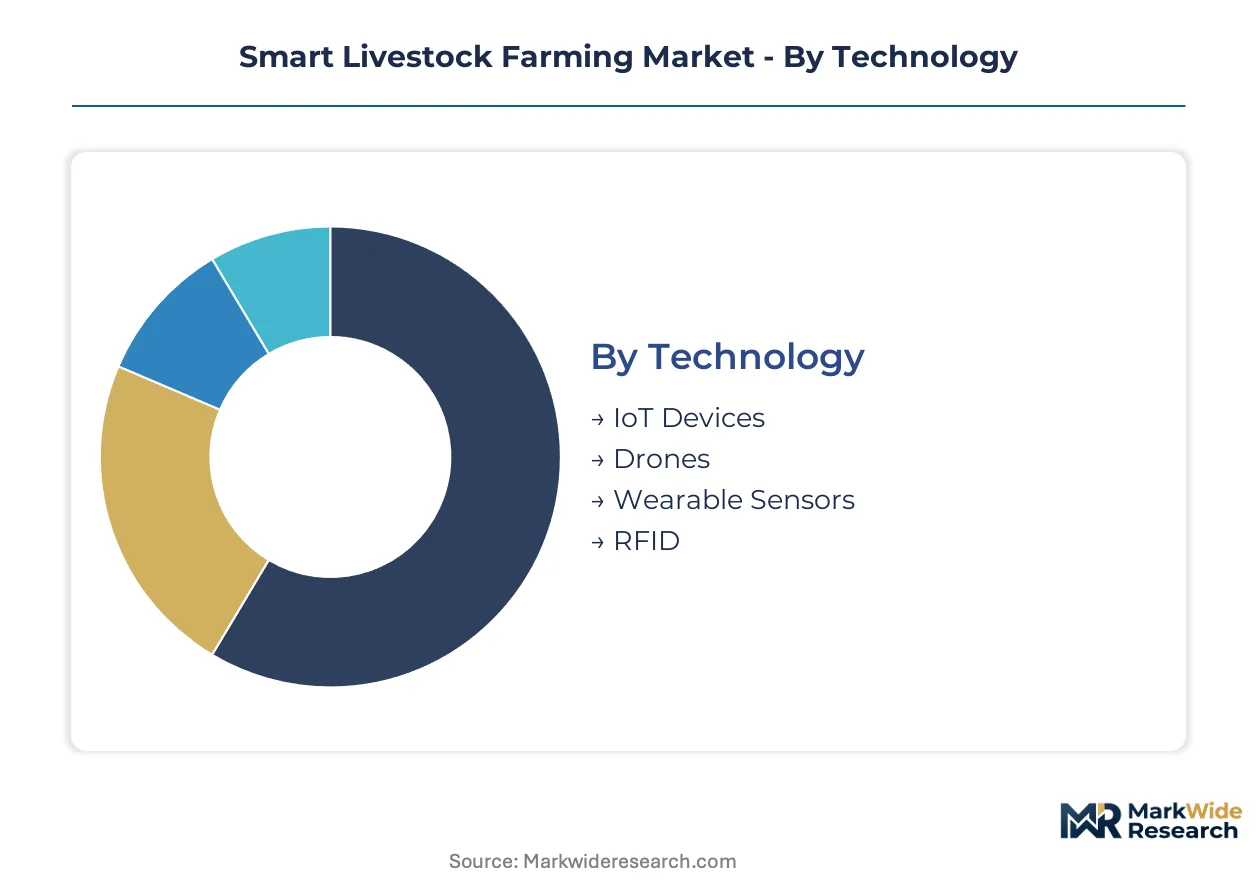
Smart livestock farming vendors design product portfolios around four distinct segmentation axes. Technology choices determine hardware margins and recurring revenue potential, while end-user scale dictates pricing architecture and service intensity across deployment models.
Technology:
EU F-Gas Regulation refrigerant phase-downs and REACH chemical compliance are fragmenting equipment specifications across sensor categories, forcing OEMs to maintain parallel product lines for European and non-European markets.
- IoT Devices:Networked environmental monitors and climate controllers that integrate barn HVAC with cloud dashboards. Demand concentrates in Dutch and Danish dairy cooperatives facing EU Green Deal nitrogen caps, where equipment replacement cycles compress from seven years to four. These deployments capture the strongest margin pools through hardware-plus-subscription models.
- Wearable Sensors:Collar-mounted accelerometers and rumination monitors that transmit individual animal biometric data. Large farm end users in the US and Australia automate health monitoring to offset veterinary labor shortages, with subscription analytics sustaining recurring revenue streams for vendors.
- Drones:Aerial platforms equipped with thermal imaging for pasture monitoring and herd location tracking. Brazilian beef operations in Mato Grosso deploy these for first-time feedlot automation as pasture-to-barn consolidation accelerates.
- RFID:Mature ear-tag and bolus identification systems with price-commoditized production. German and Danish OEMs compete on manufacturing scale rather than technology differentiation.
IoT Devices handle the majority of throughput; Wearable Sensors is the fastest mover on share.
Application:
Cost tier differentiation separates premium autonomous systems from standard monitoring tools, with pricing stratifying across certification-grade precision, mid-tier integration capability, and economy-level standalone functions.
- Feeding Management:Automated rationing systems calibrating to individual metabolic markers. Capital allocation shifts from traditional batch-feeding infrastructure toward precision delivery in Wisconsin dairy facilities exceeding 500 head.
- Health Monitoring:Predictive disease detection platforms leveraging machine learning on sensor data. Veterinary labor shortages across Australian outback and US Great Plains operations accelerate cloud-based health record adoption despite rural broadband deficits.
- Breeding Optimization:Heat detection and fertility tracking systems integrated with herd management software. Irish and New Zealand pasture-based dairies favor modular contracts permitting third-party platform integration.
- Farm Management:Centralized control systems aggregating multiple data streams across barn operations. Post-war concrete structures across Northern France and Belgium limit robotic installation without structural reinforcement, constraining addressable market.
Feeding Management commands the largest installed base; Health Monitoring is expanding most quickly as labor scarcity intensifies.
End User:
Procurement patterns diverge sharply by operational scale, with cooperatives demanding interoperability across mixed-equipment barns while large farms prioritize full-stack platform consolidation.
- Large Farms:Operations exceeding 500 head with dedicated IT infrastructure and data science capacity. These end users drive computer vision adoption for lameness detection, displacing veterinary technician hours while compressing disease detection windows from days to hours.
- Cooperatives:Member-owned dairy and beef collectives pooling capital for shared infrastructure. Dutch and Danish cooperatives lead sensor deployment velocity under EU Green Deal protocols, with pooled procurement negotiating modular contract terms.
- Medium Farms:Mid-scale operations balancing automation investment against labor retention. Edge computing convergence reduces cloud dependency in bandwidth-constrained rural Canada and Argentina.
- Small Farms:Family-owned operations under 100 head with limited capital access. Service unbundling enables componentized procurement where sensors source from one vendor and analytics from another.
Large Farms absorb the dominant share of premium system shipments; Cooperatives are climbing the fastest on procurement volume.
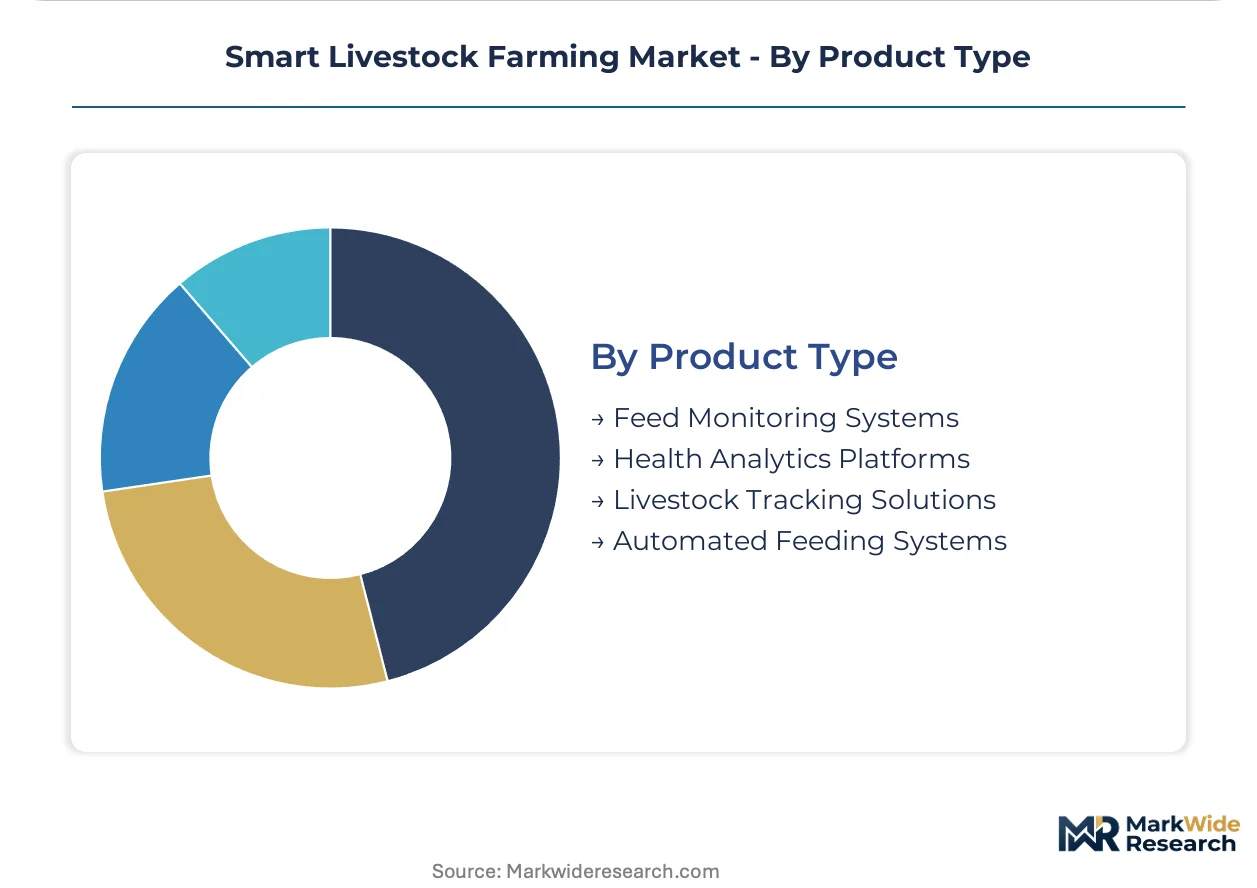
Product Type:
Supply concentration in Taiwanese MEMS foundries exposes hardware categories to input price volatility, while software platforms face talent competition from fintech and e-commerce sectors for machine learning engineers.
- Automated Feeding Systems:Robotic delivery infrastructure with integrated weight sensors and ration calibration. German livestock operations mandate refrigerant transitions favoring precision HVAC-integrated feeding lines under EU F-Gas Regulation.
- Health Analytics Platforms:Cloud-based predictive models processing wearable sensor and computer vision inputs. IEC 62443 cybersecurity certification delays product launches by 8-14 months as penetration testing requirements expand.
- Feed Monitoring Systems:Silo weight sensors and intake tracking hardware with basic dashboard visualization. Proprietary data protocols from major OEMs prevent seamless integration, forcing costly middleware development.
- Livestock Tracking Solutions:Location and movement monitoring combining RFID, GPS, and accelerometer data. Brazilian feedlot consolidation in Goiás state creates first-time demand for climate control and feeding automation integration.
Automated Feeding Systems represent the largest capital deployment category; Health Analytics Platforms are gaining share fastest as veterinary labor constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Dutch and Danish buyers absorb premium pricing for nitrogen-compliant equipment, while Brazilian and Australian operators prioritize capital efficiency in feedlot automation projects.
United States
Wisconsin dairy facilities exceeding 500 head drive computer vision adoption for lameness detection. The FDA and USDA jointly enforce antimicrobial traceability requirements that accelerate sensor-based health record adoption. Large farm operations across the Great Plains automate health monitoring to offset persistent veterinary labor gaps despite rural broadband constraints.
Netherlands
Dutch dairy cooperatives compress equipment replacement cycles from seven years to four under EU Green Deal nitrogen caps. The EU F-Gas Regulation mandates refrigerant transitions favoring precision HVAC systems with integrated IoT monitoring. Sensor deployment concentrates in Friesland and Gelderland dairy clusters where pooled procurement negotiates modular contract terms.
Germany
German livestock operations mandate refrigerant transitions under EU F-Gas Regulation that favor precision HVAC-integrated feeding lines. REACH chemical registration requirements tighten material specifications for antimicrobial coatings in livestock housing equipment. Automated feeding infrastructure manufacturing scales across Bavarian and Lower Saxon farm cooperatives.
Brazil
Beef operations in Mato Grosso and Goiás states consolidate from pasture-to-feedlot models creating first-time demand for climate control and feeding automation. The country's national agricultural regulator enforces traceability standards that favor RFID and GPS tracking integration. Drone deployment for thermal imaging and herd location tracking accelerates across Cerrado feedlot complexes.
Australia
Large farm end users across New South Wales and Victoria automate health monitoring to offset veterinary labor shortages in the outback. Edge computing convergence reduces cloud dependency in bandwidth-constrained environments across rural Queensland and South Australia. Pasture-based dairies favor modular contracts permitting third-party software integration.
Smart Livestock Farming Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in smart livestock farming equipment. The upper tier commands premium positioning through captive production of robotic milking hardware and herd management software. The specialist tier anchors growth on wearable sensor networks and subscription analytics. Competitive moves concentrate on strategic partnerships for interoperability middleware and geographic expansion into Brazilian feedlot markets.
Among Netherlands-based specialists, Nedap N.V. and Lely International occupy positions within the wearable sensor and robotic milking archetypes respectively. DeLaval exemplifies the integrated full-stack model spanning hardware manufacturing and software platforms. These three anchors represent the competitive spectrum from component specialization to vertical platform control.
| Leading Market Players |
|---|
| DeLaval |
| GEA Farm Technologies |
| Afimilk Ltd |
| Allflex Livestock Intelligence |
| BouMatic |
| Lely International |
| Nedap N.V. |
| Dairymaster |
| Fancom |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-week MEMS component lead times from Taiwanese foundries concentrate hardware cost volatility in European OEM procurement cycles, compressing margin buffers and amplifying pricing power for sensor-software integrators with captive inventory positions.
Pricing Analysis
After-sales service contracts and subscription analytics tiers drive lifetime value capture across automated milking and health monitoring deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and integration complexity, with EU F-Gas-compliant HVAC-integrated systems commanding premiums. Cost compression in economy-tier RFID tags is intensifying because Chinese manufacturing scale has commoditized ear-tag production. Small farms under 100 head exhibit acute price sensitivity, while Dutch dairy cooperatives absorb premium positioning for nitrogen-compliant equipment.
Supply Chain Analysis
Taiwan Strait transit exposure concentrates single-source vulnerability for accelerometer and rumination sensor MEMS components. Hardware manufacturing anchors in Taiwan, Germany, and Denmark, drawing from semiconductor wafers, precision motors, and antimicrobial coating chemicals. Tariff exposure on Chinese-sourced GPS modules and cloud processing chips threatens margin stability for drone and tracking solution vendors. Distribution runs through agricultural equipment dealers and direct cooperative procurement channels, with pooled buying power altering contract terms across Friesland and Gelderland dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
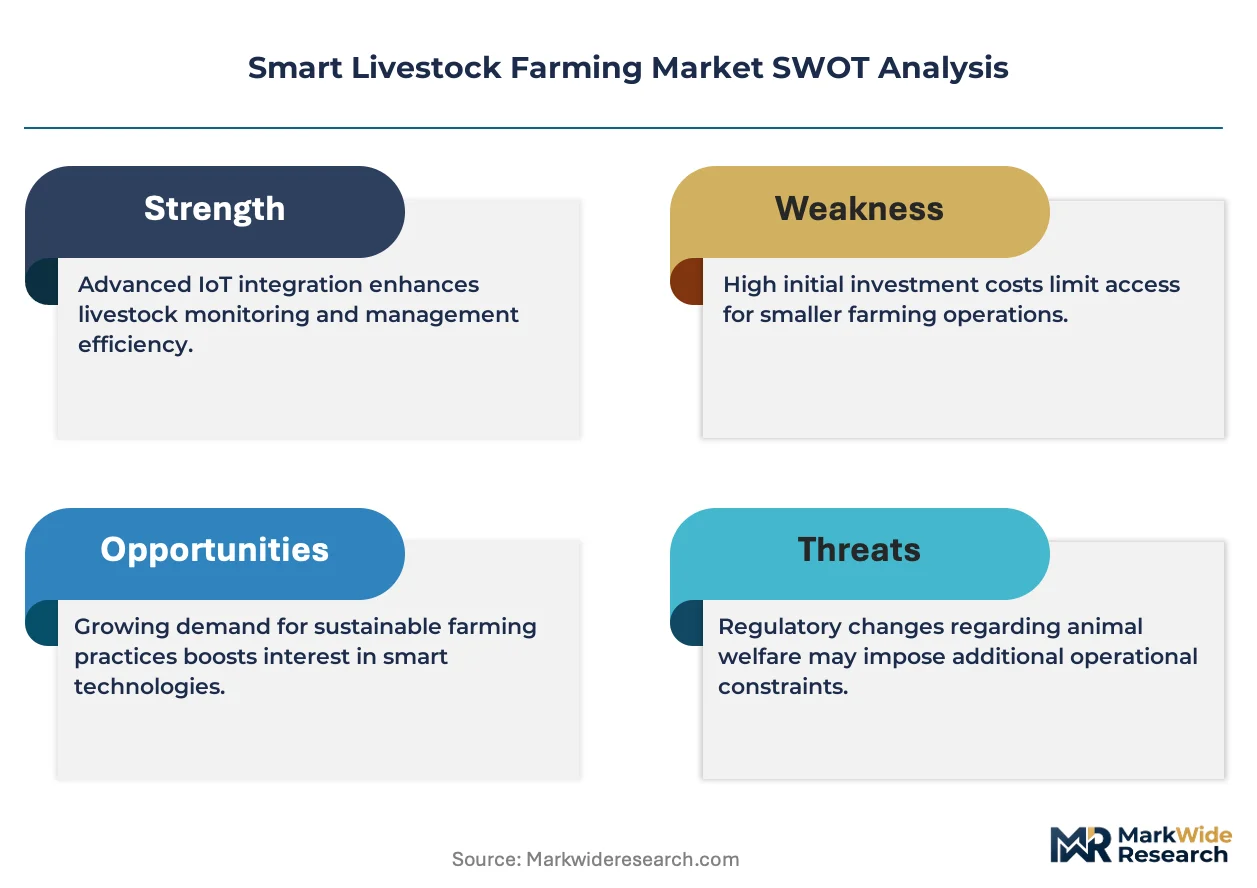
Smart livestock farming operates as a defensive-moat market where regulatory entrenchment—EU Green Deal nitrogen caps and F-Gas compliance deadlines—creates structural switching costs that lock in incumbent positions.
For Market Incumbents: Shield installed base revenue by deepening backward integration into MEMS sensor design, reducing Taiwanese foundry dependency. Accelerate IEC 62443 cybersecurity certification investment to preempt eight-to-fourteen-month product launch delays. Counter interoperability fragmentation threats by acquiring middleware specialists capable of bridging proprietary DeLaval, Nedap, and GEA data protocols.
For New Entrants and Emerging Players: Differentiate on edge computing hardware that reduces cloud dependency for bandwidth-constrained Australian outback and Argentine Pampas operations. Target Brazilian feedlot consolidation in Mato Grosso and Goiás states, where pasture-to-barn transitions create first-time automation demand absent incumbent relationships. Pursue modular software licensing approaches that unbundle hardware from analytics, matching New Zealand and Irish pasture-based dairy procurement preferences.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized livestock technology divisions lacking subscription revenue scale. Five-to-ten-year viability hinges on software platform recurring revenue ratios exceeding hardware dependency. Monitor EU AI Act conformity assessment timelines as inflection signal—mandatory certification for autonomous health intervention systems will concentrate compliance-capable vendors and eliminate marginal players.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Middleware development bridges proprietary protocols across mixed-equipment Dutch and Danish cooperatives. |
| Geographic Expansion | Brazilian feedlot automation in Mato Grosso creates first-time climate control and feeding system demand. |
| Regulatory Certification Investment | EU AI Act conformity assessments for autonomous livestock systems open advisory revenue streams. |
| Acquisition of Specialist Firm | Edge computing hardware targets bandwidth-constrained Australian outback and rural Canadian operations. |
| Strategic Partnership | Veterinary software alliances address labor shortages across US Great Plains and New South Wales farms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy cooperative procurement directors, livestock farm IT managers, OEM product strategists, and veterinary technology specialists; and secondary validation against EU regulatory filings, USDA antimicrobial traceability guidance, SEC equipment manufacturer disclosures, and agricultural trade association deployment surveys. Bottom-up equipment shipment modeling and top-down addressable farm headcount estimates were triangulated against capital expenditure patterns.
Across the analysis window, forecasts employed technology-by-application segmentation with end-user scale and regional regulatory cluster as cross-cutting dimensions. CAGRs were derived from installed base replacement cycle compression and first-time automation penetration curves. Veterinary labor shortage indices and broadband coverage gap mapping served as industry-specific demand drivers.
Material uncertainties—EU AI Act risk classification timing, MEMS foundry capacity allocation shifts, and Brazilian real exchange rate volatility—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and cooperative capital pooling sustainability. Practitioners should keep alternative scenarios live as EU Green Deal nitrogen cap implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
Smart Irrigation Controllers Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Smart Agriculture Market