
 US Smart Agriculture Market | 2026-2036
US Smart Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Agriculture Market Insights
Market Context
Midwestern equipment dealerships is rebalancing their inventory toward autonomous and precision systems as farmer capital expenditure shifts from traditional machinery to data-driven platforms. Deere & Company anchors this transition through its integrated operations center and proprietary See & Spray technology. Trimble Inc. competes via its open-platform approach, enabling interoperability across mixed-fleet environments. AGCO Corporation differentiates through its Fendt brand's autonomous tractor development and targeted livestock monitoring solutions.
Technical Definition and Structural Segments
US Smart Agriculture encompasses sensor networks, unmanned aerial systems, artificial intelligence algorithms, and connected machinery deployed to optimize input application, monitor biological systems, and automate field operations with sub-inch accuracy. The primary commercial purpose centers on maximizing yield per acre while minimizing fertilizer, water, and crop protection expenditures through real-time data feedback loops. Precision Farming applications dominate current deployment value, with Soil Monitoring representing the fastest-expanding segment as carbon credit verification protocols mature. Hardware retains the largest revenue share, though Data Analytics services command superior margins as recurring subscription models displace one-time equipment sales.
Regulatory Framework and Outlook
The USDA, EPA, and FAA collectively shape market access through emissions standards for off-road equipment, pesticide application certification requirements, and commercial drone operation waivers. The FAA's evolving Part 107 framework for beyond-visual-line-of-sight flights directly determines the operational envelope for aerial crop scouting and spraying services. Stakeholders must monitor the intersection of emerging SEC climate disclosure rules with USDA conservation program incentives, as this regulatory nexus will determine which precision agriculture investments qualify for federal cost-sharing and which data streams achieve verifiable carbon accounting status.
Market Dynamics
Farm consolidation across the Midwest Grain Belt is compressing equipment procurement cycles and concentrating technology purchasing power among fewer, larger operators who demand integrated data platforms over standalone machinery.
Growth Catalysts
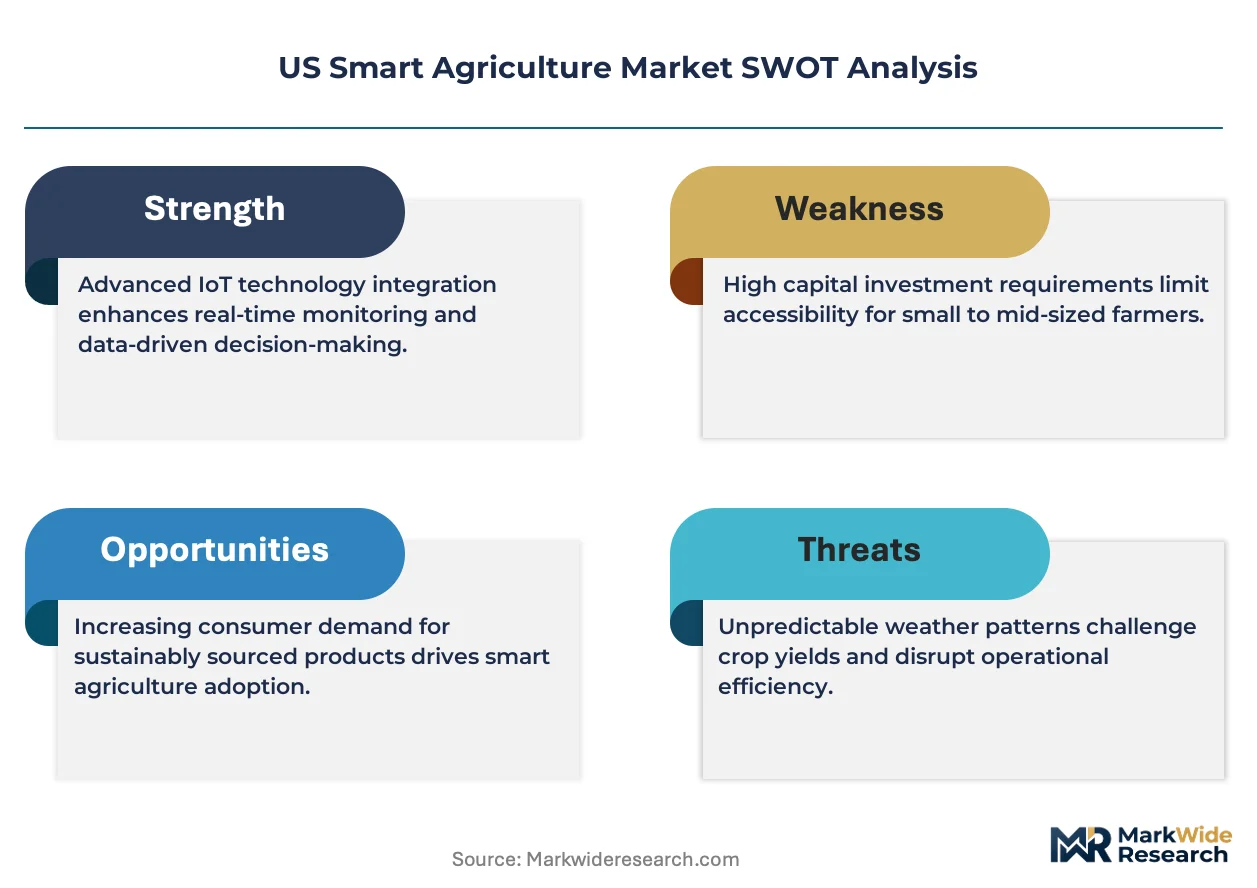
- USDA Climate-Smart Commodities Program:Federal cost-sharing accelerates adoption of soil carbon monitoring tools and precision application systems, directly lowering capital barriers for mid-sized operations.
- Variable-Rate Technology:Sub-inch accuracy in fertilizer and seed placement reduces input waste while maximizing yield per acre, creating measurable ROI that justifies equipment upgrades.
- FAA Part 107 Evolution:Expanding beyond-visual-line-of-sight waivers for commercial drones enables scalable aerial crop scouting and targeted spraying services across larger contiguous acreage.
Market Restraints
- Equipment Capital Intensity:Autonomous tractors and precision implements require substantial upfront investment that strains operators without access to federal cost-sharing or favorable credit terms.
- Connectivity Infrastructure Gaps:Rural broadband deficits in Nebraska, Kansas, and Dakotas limit real-time data transmission from field sensors to cloud-based analytics platforms.
- Technical Interoperability Friction:Proprietary data formats from major OEMs lock farmers into single-vendor ecosystems, raising switching costs and constraining mixed-fleet optimization.
Strategic Opportunities
- Carbon Credit Verification Services:Emerging SEC climate disclosure rules create demand for auditable soil carbon data streams that precision agriculture platforms are uniquely positioned to supply.
- Livestock Monitoring Expansion:Dairy and feedlot operations in Wisconsin and Texas represent underpenetrated segments for biometric sensors and automated health alerting systems.
- Data Analytics Subscriptions:Recurring revenue models for yield forecasting, pest prediction, and input optimization are displacing one-time hardware sales and improving margin profiles.
Industry Challenges
- Technical Talent Scarcity:Equipment dealerships and farm operators face acute shortages of technicians trained in mechatronics, data science, and drone piloting for commercial agricultural operations.
- Legacy System Integration:Farmers with substantial investments in conventional machinery struggle to incorporate new sensor networks and autonomous units into existing fleet management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Agriculture Market |
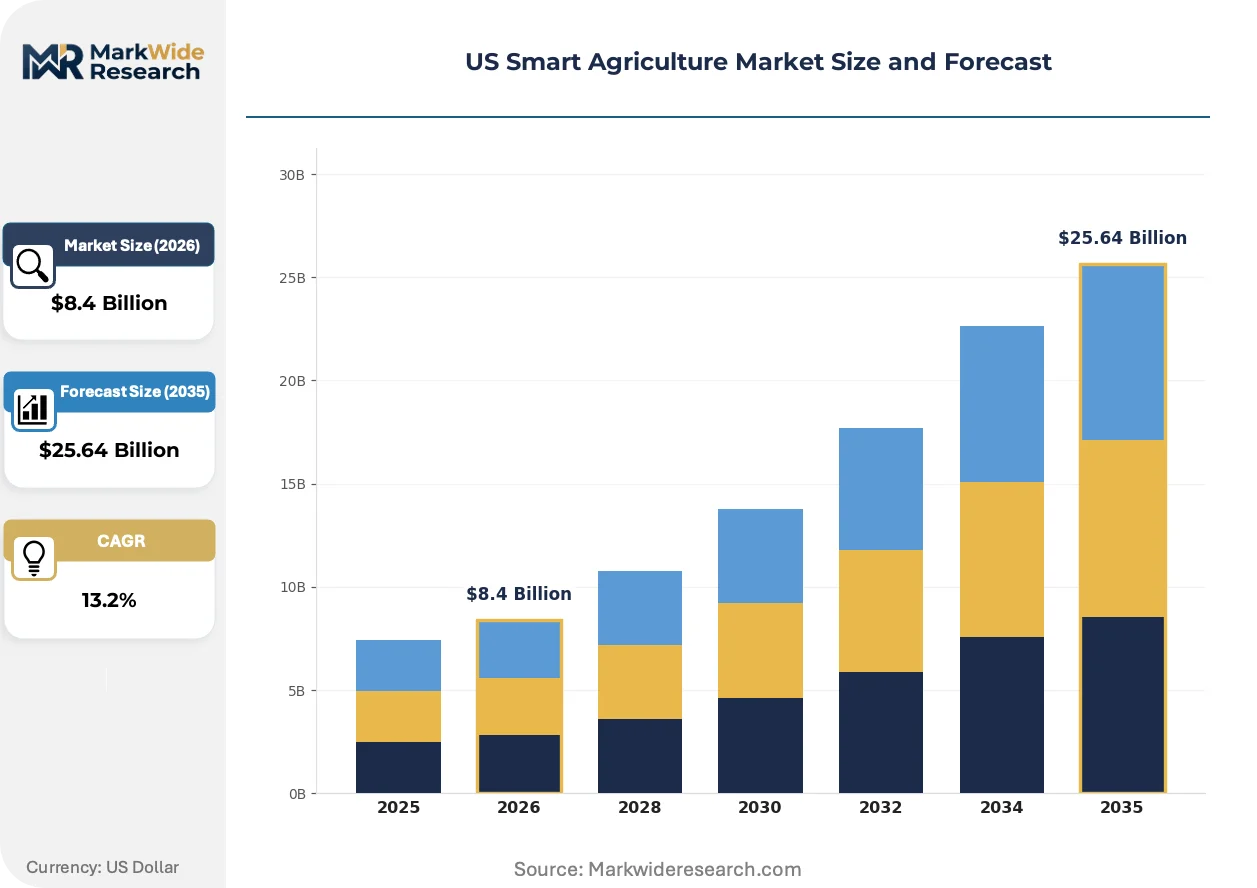
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $25.64 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Drones, Sensors, AI Application: Precision Farming, Livestock Monitoring, Crop Management, Soil Monitoring End User: Farmers, Agricultural Enterprises, Research Institutions, Cooperatives Product Type: Hardware, Software, Services, Data Analytics |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, Topcon Positioning Systems, CNH Industrial, Raven Industries, Monarch Tractor, Carbon Robotics, Farmers Edge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Agriculture Market Trends and Innovations
Artificial intelligence algorithms are rewiring how agricultural decisions are made, shifting authority from field experience to predictive models trained on multi-season datasets across diverse soil and weather conditions.
Computer vision systems for weed identification and targeted herbicide application are expanding into row-crop operations throughout Iowa and Illinois. Large-scale corn and soybean producers are retrofitting existing sprayers with camera arrays and machine-learning inference engines at accelerating pace. This technology is expanding into mid-tier equipment lines previously reserved for premium autonomous platforms, compressing the price-performance frontier for precision weed control.
The SEC's emerging climate disclosure framework intersects with USDA conservation incentives to create new compliance obligations for agricultural data. Publicly traded food processors and grain handlers now face pressure to verify upstream emissions and soil carbon sequestration claims. Midwestern grain cooperatives and input suppliers are responding by investing in blockchain-traceable data infrastructure that links field-level measurements to corporate sustainability reporting.
Equipment purchasing committees at consolidated farm operations are unbundling after-sales service from original equipment procurement. These buyers now negotiate separate contracts for maintenance, software updates, and technical support, often selecting third-party providers over manufacturer-affiliated dealer networks. This pattern is most visible across the Corn Belt, where multi-thousand-acre operators leverage scale to drive service pricing transparency and performance-based contracting terms.
US Smart Agriculture Market Segmentation
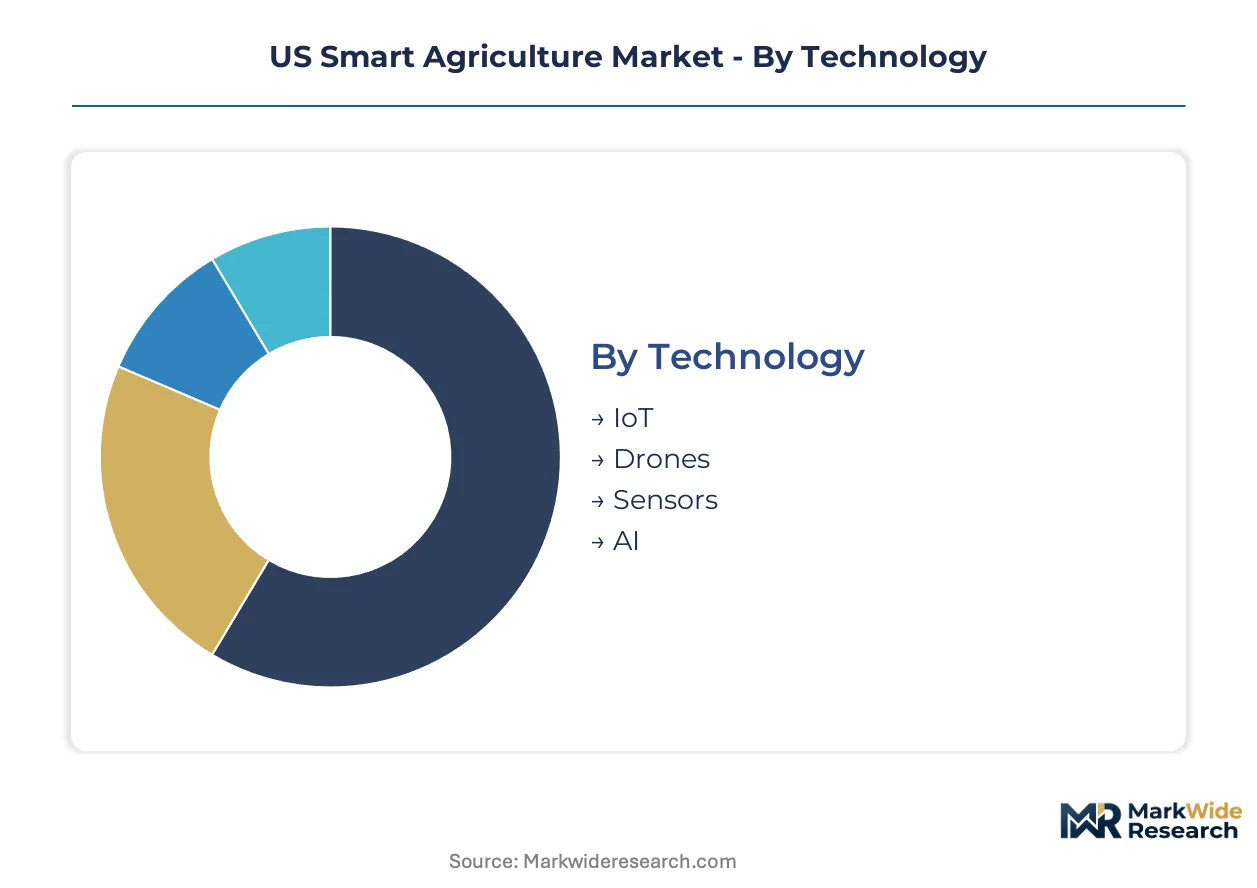
Technology deployment patterns across the US Smart Agriculture Market diverge sharply by operational scale, connectivity infrastructure, and compliance obligations. Understanding these segment boundaries enables suppliers to align R&D investment with where purchasing power is concentrating.
Technology:
Capital intensity and technical sophistication separate early adopters from mainstream buyers in this dimension.
- IoT:Mesh networks of soil moisture probes, weather stations, and equipment telematics dominate current field deployment across the Corn Belt. Iowa and Illinois operators prioritize IoT bundles that integrate with existing farm management information systems rather than standalone sensor purchases.
- AI:Machine learning inference engines for yield prediction, pest pressure modeling, and autonomous machinery navigation command premium pricing but deliver measurable input cost reductions. Large-scale operations in Nebraska and Kansas are expanding AI procurement fastest as they consolidate acreage and centralize decision-making.
- Drones:Aerial platforms for crop scouting and variable-rate spraying face operational constraints from FAA Part 107 waiver availability.
- Sensors:Ground-based monitoring devices for soil carbon, nutrient levels, and plant health metrics generate the raw data streams feeding upstream analytics platforms.
IoT leads volumes today; AI is gaining share fastest.
Application:
Return-on-investment timelines vary dramatically by biological system complexity and input cost exposure.
- Precision Farming:Variable-rate application of seeds, fertilizers, and crop protection chemicals anchored in GPS guidance and prescription mapping commands the largest current revenue pool. Midwestern corn and soybean operations treat precision farming as baseline infrastructure rather than discretionary upgrade.
- Soil Monitoring:Carbon quantification protocols, nutrient tracking, and moisture profiling generate accelerating demand as USDA cost-sharing programs and emerging SEC disclosure rules create compliance-driven purchasing. The Dakotas and Kansas show steepest adoption curves where soil heterogeneity rewards granular measurement.
- Livestock Monitoring:Biometric sensors and automated health alerting for dairy and feedlot operations remain underpenetrated relative to row-crop potential.
- Crop Management:Integrated pest management platforms and irrigation optimization systems serve specialty crop producers in California and Florida with higher per-acre technology budgets.
Precision Farming anchors current spending; Soil Monitoring is expanding most quickly.
End User:
Procurement authority concentrates with scale, though federal programs are democratizing access for smaller operators.
- Farmers:Owner-operators below five hundred acres depend heavily on USDA Partnerships for Climate-Smart Commodities grants to finance precision equipment transitions. Their technology choices prioritize interoperability with mixed-brand machinery fleets.
- Agricultural Enterprises:Corporate farming operations and integrated food companies with direct land control deploy capital fastest, negotiating enterprise software licenses and autonomous machinery fleets at scale. Their procurement teams unbundle hardware from service contracts.
- Cooperatives:Member-owned grain and input cooperatives aggregate purchasing power and shared equipment pools for mid-sized producers.
- Research Institutions:University extension services and USDA research stations drive technology validation and farmer demonstration programs.
Agricultural Enterprises dominate absolute spending; Farmers represent the deepest addressable pool.
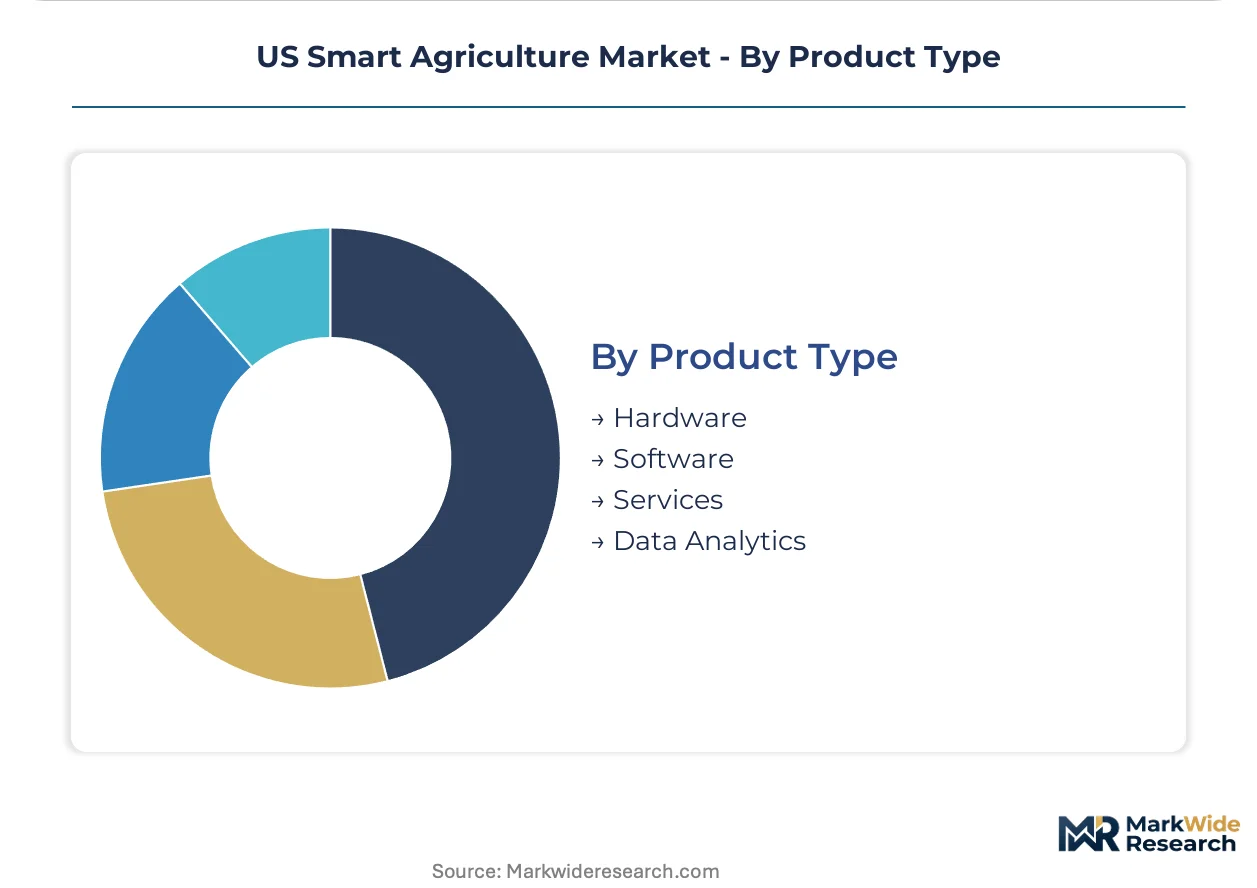
Product Type:
Margin structure inverts between capital equipment and recurring service relationships.
- Hardware:Autonomous tractors, sensor arrays, and drone platforms require substantial upfront capital and generate one-time revenue recognition. Equipment financing availability directly determines adoption velocity among credit-constrained operators.
- Data Analytics:Subscription-based yield forecasting, pest prediction, and input optimization services command superior gross margins and customer lifetime value. Platform providers are shifting business models toward recurring revenue.
- Software:Farm management information systems and prescription mapping tools serve as integration layers connecting hardware to analytics.
- Services:Technical support, equipment maintenance, and carbon credit verification consulting complete the value chain.
Hardware retains the largest revenue share; Data Analytics shows the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision farming equipment exports exceed France's domestic smart agriculture deployment by a factor of three, yet both markets operate under harmonized EU subsidy frameworks that shape technology adoption curves differently.
Midwest Grain Belt
Iowa and Illinois corn-soybean operations drive autonomous machinery demand through consolidated acreage and capital access. The USDA Partnerships for Climate-Smart Commodities program subsidizes soil carbon monitoring adoption across Minnesota and Nebraska. Equipment dealerships in Des Moines and Omaha are rebalancing inventory toward variable-rate application systems and telemetry-integrated tractors.
California Central Valley
Specialty crop producers in Fresno and Kern counties deploy sensor networks for irrigation optimization and labor cost reduction. The state's Sustainable Groundwater Management Act mandates water-use efficiency reporting that accelerates precision agriculture procurement. Technology clusters around Salinas and Watsonville focus on computer vision systems for harvest automation and quality grading.
Southeastern Coastal Plains
Peanut and cotton operations in Georgia and North Carolina adopt drone-based crop scouting as FAA Part 107 waivers expand beyond-visual-line-of-sight permissions. The USDA Natural Resources Conservation Service cost-shares precision nutrient management in the Chesapeake Bay watershed. Research partnerships between Raleigh-Durham agtech startups and land-grant extension services validate autonomous spraying protocols.
Northern Great Plains
Wheat and pulse growers in Montana and the Dakotas face connectivity infrastructure gaps that limit real-time data transmission from remote fields. The FCC's Rural Digital Opportunity Fund targets broadband expansion across North Dakota's Red River Valley. Cooperatives in Grand Forks and Fargo aggregate purchasing power for shared precision equipment pools serving mid-sized operators.
Pacific Northwest
Tree fruit and vineyard operations in Washington's Yakima Valley and Oregon's Willamette Valley prioritize labor-saving automation amid seasonal worker shortages. State-level carbon offset programs in Washington create demand for auditable soil carbon data streams. Equipment manufacturers near Seattle and Portland develop specialized platforms for perennial crop monitoring and automated pruning systems.
US Smart Agriculture Market Competitive Landscape
Midwestern equipment manufacturers anchor the integrated systems tier; Silicon Valley agtech specialists hold the software and analytics vector. Market structure consolidates around three dominant OEMs controlling proprietary data ecosystems, while venture-backed entrants fragment the autonomous machinery and computer vision segments. Two strategic archetypes prevail: vertically integrated full-stack providers and modular platform specialists enabling mixed-fleet interoperability. Competitive intensity centers on M&A activity targeting AI and sensor capabilities, plus strategic partnerships between equipment makers and carbon credit verification services.
Within the legacy equipment tier, Deere & Company and AGCO Corporation occupy positions exemplifying integrated hardware-software bundling, while Trimble Inc. represents the open-platform interoperability archetype. These three companies collectively illustrate the market's central tension between proprietary data lock-in and farmer demand for cross-brand compatibility.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| Topcon Positioning Systems |
| CNH Industrial |
| Raven Industries |
| Monarch Tractor |
| Carbon Robotics |
| Farmers Edge |
| Others |
Pricing and Supply Chain Analysis
Semiconductor chip costs cascade through precision agriculture equipment manufacturing, compressing margins on autonomous tractors and sensor arrays before reaching Midwestern farm operations through tiered dealer markups.
Pricing Analysis
Distributor margin layers in the Corn Belt equipment channel absorb 12-18 points before reaching farm gates. Three-tier pricing structure across premium, standard, and economy levels separates Deere's integrated See & Spray bundles from Trimble's open-platform modules and third-party retrofit kits. Pricing pressure stems from farmer capital constraints and USDA cost-sharing program delays. Smallholder operators below 500 acres exhibit acute price sensitivity, while consolidated agricultural enterprises negotiate enterprise licenses with minimal per-unit friction.
Supply Chain Analysis
Freight costs from Taiwan, South Korea, and Germany for LiDAR units and GPS modules amplify landed costs for domestic assembly plants. Precision agriculture hardware draws from Chinese rare earth processing, Mexican sensor fabrication, and domestic software development. Single-source vulnerability concentrates in advanced imaging chipsets from TSMC foundries. Distribution runs through John Deere and AGCO captive dealer networks alongside independent precision agriculture specialists serving mixed-fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Smart Agriculture Market functions as a regulatory compounder where USDA Partnerships for Climate-Smart Commodities and emerging SEC climate disclosure rules create mandatory technology procurement obligations.
For Market Incumbents: Extend proprietary data ecosystem lock-in through deeper See & Spray retrofit penetration and carbon credit verification service bundling. Defend against Trimble's open-platform threat by accelerating interoperability friction in next-generation telemetry protocols. Prioritize vertical integration into LiDAR and edge-computing chipsets to offset semiconductor supply vulnerability.
For New Entrants and Emerging Players: Capture livestock monitoring whitespace in Wisconsin dairy and Texas feedlot operations where incumbent presence remains thin. Penetrate the Northern Great Plains through cooperative equipment pools serving connectivity-constrained wheat growers. Lead with drone-based crop scouting services requiring minimal upfront farmer capital versus autonomous machinery sales.
For Investors and Strategic Acquirers: Consolidation pressure builds where carbon credit verification platforms lack auditable field-data infrastructure. Position for 5-10 year viability around AI-enabled input optimization rather than hardware-dependent models. Target acquisition archetypes combine computer vision IP with existing FAA Part 107 waiver portfolios. Monitor USDA cost-sharing program renewal cycles as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Credit Verification Platform Development | Positions precision agriculture data for SEC climate disclosure compliance and USDA conservation incentive stacking. |
| FAA Part 107 Waiver Portfolio Expansion | Enables scalable beyond-visual-line-of-sight drone operations across contiguous Midwestern acreage. |
| LiDAR and Edge Computing Backward Integration | Reduces semiconductor supply vulnerability and accelerates autonomous navigation cost curves. |
| Livestock Monitoring Biometric Sensor Launch | Penetrates underexploited dairy and feedlot segments in Wisconsin and Texas with recurring subscription models. |
| Open-Platform Interoperability Partnership | Captures mixed-fleet operators frustrated by Deere's proprietary data lock-in through Trimble-compatible middleware. |
Research Methodology
Multiple input streams — equipment dealership interviews, farm operator procurement surveys, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged precision agriculture sales directors at Iowa and Illinois dealerships, USDA program administrators, and autonomous machinery engineering leads. Secondary validation drew from FAA Part 107 waiver databases, USDA Partnerships for Climate-Smart Commodities award records, and SEC climate disclosure rulemaking dockets. Bottom-up equipment shipment tallies and top-down agricultural enterprise technology budgets were triangulated for cross-verification.
Historical adoption curves were cross-referenced against expert panel assessments of farmer capital access and connectivity infrastructure buildout across the analysis window. Segmentation modeling incorporated technology tier, application type, operational scale, and regional regulatory intensity dimensions. CAGRs were derived from slope-consistent extrapolation of equipment replacement cycles and subscription service attach rates. Forecast inputs included USDA cost-sharing program appropriation trajectories and FCC Rural Digital Opportunity Fund disbursement schedules.
Underlying measurement precision varies by segment; precision farming hardware carries tighter precision than nascent carbon credit verification services. Forecasts reflect documented assumptions regarding farm consolidation velocity and FAA regulatory evolution. Stakeholders should weight assumptions against their own operating context and regional subsidy availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Smart Tractor Market