
 India Microirrigation System Market | 2026-2036
India Microirrigation System Market Size, Share, and Industry Trends Forecast 2026-2036
India Microirrigation System Market Insights
Polyethylene tubing is broadening its displacement of rigid PVC laterals across India's microirrigation channels, cutting per-hectare installation costs and improving terrain adaptability. Jain Irrigation Systems Ltd leverages backward integration into polymer compounding to protect margin pools across drip emitter production. Netafim anchors its position through Israeli-origin drip technology adapted for Indian soil salinity conditions. Mahindra & Mahindra Ltd competes via farm equipment dealer networks that bundle microirrigation with tractor financing.
Microirrigation systems encompass low-pressure water delivery networks comprising emitters, lateral tubing, filtration units, and control valves engineered to apply water directly to crop root zones at flow rates typically below 100 liters per hour per emitter. These systems serve commercial agriculture by minimizing evaporative losses and enabling fertigation in water-stressed growing regions. Drip irrigation occupies the dominant revenue position due to established subsidy eligibility and proven payback periods in horticulture. Smart irrigation represents the fastest-expanding technology segment as cellular-connected soil moisture sensors gain traction among export-oriented grape and banana growers. Sprinkler irrigation retains volume leadership in cereal and fodder crops where overhead application matches crop architecture.
BIS certification requirements for emitter discharge uniformity and the CEA's agricultural power tariff structures shape product design priorities and farmer payback calculations across Indian states. The PLI scheme for specialty steel and polymer processing indirectly supports domestic component sourcing for system manufacturers. State-level nodal agencies under the National Mission on Micro Irrigation enforce quality benchmarks that filter substandard imports from Chinese and Southeast Asian suppliers. Stakeholders must track groundwater extraction caps proposed by the central water commission and their cascading impact on acreage eligibility for subsidized drip installations.
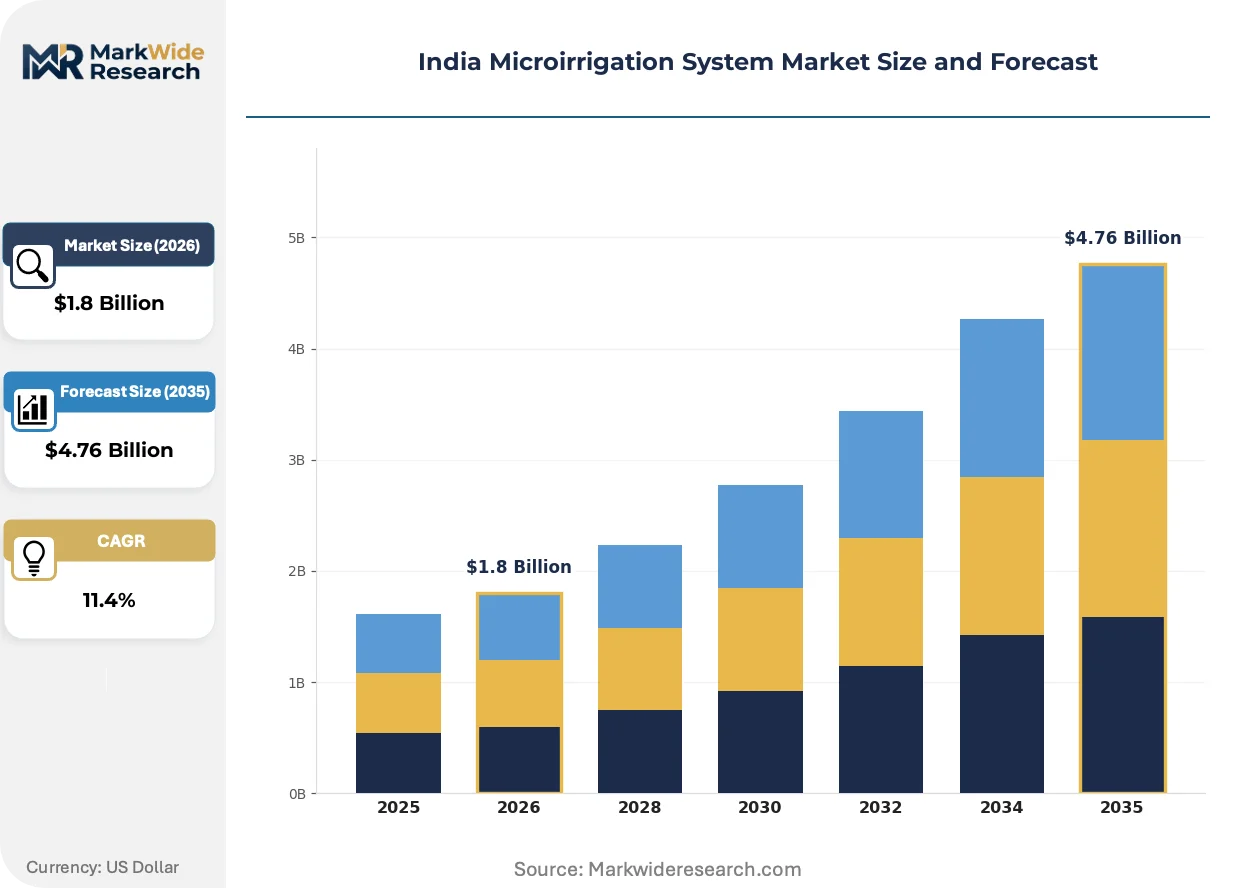
Market Dynamics
PM-KUSUM scheme disbursements and state-level precision agriculture subsidies are compressing farmer payback periods from flood irrigation conversion, while groundwater extraction caps proposed by the central water commission threaten to restrict acreage eligibility for subsidized drip installations across western Maharashtra and Gujarat.
Growth Catalysts
- PM-KUSUM Scheme:Central government capital subsidies for solar-powered microirrigation pumps reduce diesel dependency and accelerate adoption in sugarcane belts where grid power is unreliable.
- Horticulture Expansion:Grape and pomegranate orchard operators in Maharashtra and Karnataka are converting flood-irrigated acreage to drip systems to meet export quality standards and reduce water stress penalties.
- Polymer Compounding Integration:Domestic backward integration into polyethylene resin processing is lowering per-hectare lateral tubing costs and shortening procurement lead times for system integrators.
Market Restraints
- Groundwater Depletion Regulation:Central Water Commission extraction caps in overexploited blocks of Gujarat and Rajasthan threaten to disqualify marginal farmers from subsidized equipment eligibility.
- Import Dependency for Emitters:Precision-molded drip emitters and pressure-compensating valves concentrate sourcing from Israeli and Chinese suppliers, exposing margins to currency volatility and shipping disruptions.
- Capital Intensity for Smallholders:Subsidized drip systems still require 30-40% farmer co-payment, which remains prohibitive for holdings below two hectares in Bihar and eastern Uttar Pradesh.
Strategic Opportunities
- Smart Irrigation Convergence:Cellular-connected soil moisture sensors and valve automation are creating premium service tiers among export-oriented banana and grape growers in Nashik and Sangli districts.
- State Nodal Agency Channel Expansion:Direct procurement partnerships with Gujarat Green Revolution Company and Maharashtra Micro Irrigation Corporation are bypassing traditional dealer networks in high-volume districts.
- Fertigation Bundling:Water-soluble fertilizer integration with drip infrastructure is opening recurring revenue streams in vegetable-growing clusters of Madhya Pradesh and Karnataka.
Industry Challenges
- BIS Certification Timelines:Emitter discharge uniformity testing and BIS mark acquisition create 8-12 month product launch delays for new drip lateral designs.
- Installation Workforce Scarcity:Trained technicians for hydraulic design and field layout are concentrated in western India, limiting deployment speed in emerging eastern markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Microirrigation System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Irrigation, Micro Sprinklers, Subsurface Drip End User: Agriculture, Horticulture, Landscape, Greenhouse Technology: Automated Systems, Sensor-Based, Manual Systems, Smart Irrigation Installation: On-Farm, Off-Farm, Commercial, Residential |
| Companies Covered | Jain Irrigation Systems Ltd, Netafim (Orbia Advance Corporation), Mahindra & Mahindra Ltd, Rivulis (Temasek), Kothari Group, Finolex Plasson, Rain Bird Corporation, The Toro Company, Supreme Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Microirrigation System Market Trends and Innovations
Polyethylene tubing formulations and precision emitter manufacturing are compressing installed costs while cellular telemetry and automated valve control create new premium tiers in export-oriented horticulture clusters.
Linear low-density polyethylene (LLDPE) laterals with UV stabilizers are consolidating field deployment across undulating terrain in the Western Ghats and Deccan Plateau. Grape growers in Nashik district are specifying flexible tubing over rigid PVC to reduce trenching labor and accommodate slope gradients. This material shift is consolidating supplier margins around polymer compounding capabilities rather than extrusion equipment alone.
CEA agricultural power tariff restructuring is forcing demand response integration into microirrigation control systems. Time-of-day electricity pricing in Maharashtra and Gujarat is prompting farmers to specify automated valve scheduling that synchronizes irrigation with off-peak tariff windows. Drip system manufacturers are responding by bundling programmable controllers with subsidized pump sets.
Dealer financing unbundling is accelerating direct manufacturer-to-farmer engagement in high-volume districts. State nodal agencies under the National Mission on Micro Irrigation are consolidating procurement into annual tenders that bypass traditional equipment dealers. Jain Irrigation and Netafim are deploying dedicated project teams to interface directly with Gujarat Green Revolution Company and Maharashtra's horticulture department.
India Microirrigation System Market Segmentation
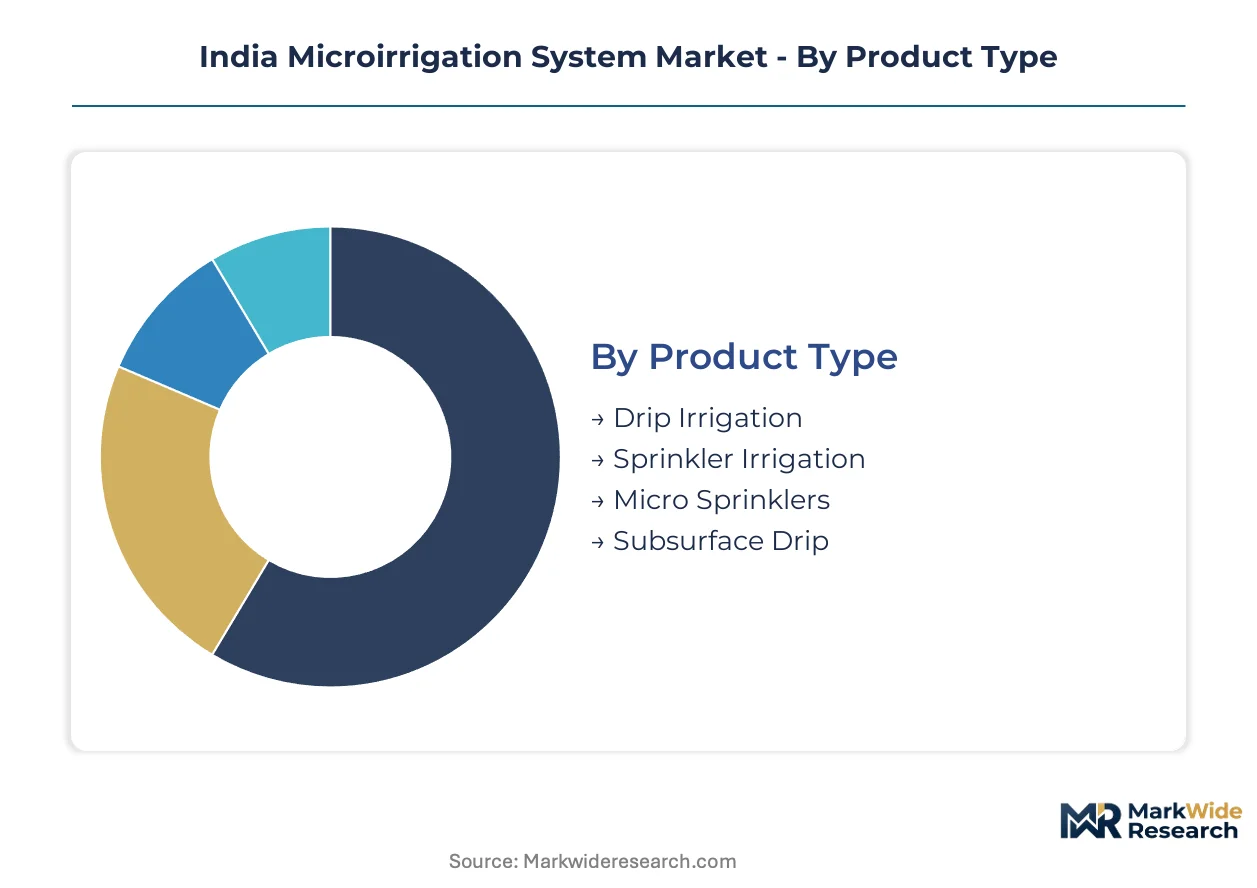
India's microirrigation market fragments across four dimensions that each carry distinct regulatory footprints and subsidy eligibility criteria. BIS certification requirements, PM-KUSUM scheme disbursement rules, and state nodal agency procurement protocols create divergent compliance burdens across product categories and end-use applications.
Product Type:
BIS certification mandates for emitter discharge uniformity apply differentially across product types, with drip irrigation facing the most stringent testing protocols while subsurface systems navigate emerging standards.
- Drip Irrigation:Surface and subsurface emitter networks with flow rates below 100 liters per hour dominate Maharashtra's sugarcane belts and Gujarat's vegetable districts. BIS mark acquisition for discharge uniformity testing creates 8-12 month launch delays for new lateral designs, consolidating advantage among established compounders with captive testing facilities.
- Sprinkler Irrigation:Overhead application systems retain volume leadership in cereal and fodder crops where crop architecture tolerates broadcast wetting. Fixed and portable configurations face lighter certification burdens than precision emitters, accelerating product refresh cycles in Rajasthan's fodder blocks.
- Micro Sprinklers:Low-angle rotary and static emitters bridge drip and conventional sprinkler performance for orchard crops with wide root zones.
- Subsurface Drip:Buried lateral networks with root-intrusion resistant emitters target high-value perennial crops in Karnataka's coffee and Maharashtra's grape belts.
Leading the category by volume: Sprinkler Irrigation. Growing fastest: Subsurface Drip.
End User:
Subsidy co-payment structures and minimum holding size thresholds segment farmer eligibility, with horticulture operators capturing disproportionate scheme benefits relative to cereal growers.
- Agriculture:Broadacre cereal and oilseed producers in Punjab and Haryana deploy sprinkler systems for wheat and mustard under PM-KUSUM pump subsidies. 30-40% farmer co-payment requirements exclude marginal holders below two hectares in Bihar and eastern Uttar Pradesh from drip conversion.
- Horticulture:Export-oriented grape and pomegranate operators in Nashik and Sangli districts specify precision drip with fertigation integration to meet European residue standards. Cellular-connected soil moisture monitoring penetrates fastest among banana contract growers supplying organized retail chains.
- Landscape:Golf course and highway median irrigation in peri-urban corridors around Bengaluru and Hyderabad.
- Greenhouse:Controlled-environment vegetable and flower producers in Pune and Nashik districts.
Horticulture commands premium pricing. Agriculture supplies raw volume.
Technology:
Capital intensity and digital infrastructure requirements stratify adoption, with automated and smart systems concentrating where grid power reliability and cellular coverage converge.
- Automated Systems:Programmable valve controllers synchronized with CEA agricultural tariff windows enable demand response irrigation in Maharashtra and Gujarat. Time-of-day electricity pricing forces pump scheduling automation that bundles with subsidized equipment tenders.
- Sensor-Based:Tensiometers and capacitance probes penetrate export-oriented clusters where water stress penalties threaten contract cancellations. Nashik grape growers deploy soil moisture telemetry to document sustainable irrigation practices for European importers.
- Manual Systems:Basic filtration and valve assemblies dominate smallholder adoption where technical workforce scarcity limits hydraulic design capacity.
- Smart Irrigation:Cloud-connected platforms with predictive analytics remain nascent outside corporate farming estates and contract grower collectives.
Manual systems anchor installed base. Sensor-based configurations climbing fastest.
Installation:
Procurement channel structure bifurcates between state nodal agency direct tenders and dealer-mediated distribution, with installation type determining channel access.
- On-Farm:Field-assembled lateral networks for individual holdings constitute the dominant installation mode. Gujarat Green Revolution Company and Maharashtra Micro Irrigation Corporation tenders consolidate procurement into annual cycles that bypass traditional dealer networks.
- Off-Farm:Community drip and sprinkler systems for water user associations in Gujarat's Narmada command areas.
- Commercial:Turnkey project execution for plantation estates and corporate farming ventures with dedicated maintenance contracts.
- Residential:Terrace and kitchen garden micro-kits in urban peripheries with limited subsidy eligibility.
On-farm installations supply overwhelming volume. Commercial segment expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in western and southern states where horticulture export clusters and sugarcane processing infrastructure overlap with groundwater stress zones. State nodal agencies channel PM-KUSUM subsidies toward districts with documented water table decline.
Maharashtra
Nashik and Sangli grape belts drive drip conversion for European export compliance. Maharashtra Micro Irrigation Corporation tenders bypass dealer networks for direct manufacturer procurement. Pune's precision agriculture equipment cluster supplies automated valve controllers for CEA tariff synchronization.
Gujarat
Vegetable-growing districts around Vadodara and Anand deploy subsidized drip for potato and cumin cultivation. Gujarat Green Revolution Company consolidates annual procurement cycles for water user associations. Narmada command areas test community sprinkler systems for fodder blocks.
Karnataka
Pomegranate orchards in Bijapur and Bagalkot convert flood irrigation to meet Middle Eastern phytosanitary standards. BIS certification delays filter substandard emitters from Tamil Nadu suppliers. Bengaluru's polymer compounding units feed lateral tubing demand for coffee estates in Coorg.
Telangana
Chili and turmeric belts in Warangal and Khammam adopt drip for fertigation integration. State agriculture department subsidies target holdings above two hectares. Hyderabad's smart agriculture startups pilot cellular soil moisture sensors for contract banana growers.
Tamil Nadu
Cauvery delta coconut and banana growers face groundwater extraction caps that threaten subsidy eligibility. Coimbatore's precision molding industry supplies drip emitters to Kerala and Karnataka markets. Erode's turmeric processing cooperatives bundle drip installation with water-soluble fertilizer procurement.
India Microirrigation System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated compounders capturing margin pools that extrusion-only fabricators cannot access. The structure concentrates around three archetypes: polymer-integrated system designers, irrigation technology licensors, and farm equipment bundlers. Capacity expansion and direct state agency engagement represent the dominant competitive vectors as dealer networks lose procurement share.
Among polymer-integrated specialists, Jain Irrigation Systems Ltd anchors the backward-compounded tubing segment, while Netafim occupies a position tied to Israeli-origin emitter technology adapted for salinity conditions. Mahindra & Mahindra Ltd exemplifies the equipment-bundling archetype through tractor financing channels that cross-sell microirrigation systems. These three represent distinct strategic postures rather than overlapping capability sets.
| Leading Market Players |
|---|
| Jain Irrigation Systems Ltd |
| Netafim (Orbia Advance Corporation) |
| Mahindra & Mahindra Ltd |
| Rivulis (Temasek) |
| Kothari Group |
| Finolex Plasson |
| Rain Bird Corporation |
| The Toro Company |
| Supreme Industries Limited |
| Others |
Pricing and Supply Chain Analysis
State nodal agency procurement concentration in Gujarat and Maharashtra enforces tender-based pricing that compresses dealer margins while rewarding manufacturers with captive polymer compounding capabilities. PM-KUSUM subsidy disbursement schedules create payment lags that force working capital financing costs into quoted system prices.
Pricing Analysis
Volume leadership in sprinkler systems trades at thinner margins than precision drip configurations serving export-oriented horticulture. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified emitters with fertigation bundling from basic lateral assemblies. Cost compression in economy-tier polyethylene tubing is intensifying because domestic resin processors are expanding compounding capacity. Marginal farmers below two hectares exhibit acute price sensitivity, while corporate plantation operators prioritize discharge uniformity certification over unit cost.
Supply Chain Analysis
Emitter refurbishment and lateral recycling programs in Maharashtra and Gujarat are recovering UV-degraded tubing for recompounding into non-irrigation polymer applications. Precision-molded drip emitters draw from Israeli and Chinese manufacturing clusters, while polyethylene resin supplies rest on Saudi Arabian and Indian petrochemical feedstocks. Single-source vulnerability in pressure-compensating valve technology exposes margins to shipping disruptions. Distribution runs through state nodal agency tender platforms that bypass traditional equipment dealer networks in high-volume districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer compounding capacity scarcity props pricing power for integrated manufacturers while constraining margin expansion for extrusion-only fabricators. This supply-constrained structure favors backward-integrated players with captive resin processing.
For Market Incumbents: Extend polymer compounding capacity in western India to defend margin pools against emerging contract manufacturers from Tamil Nadu. Deepen direct engagement with Gujarat Green Revolution Company and Maharashtra Micro Irrigation Corporation tenders to offset dealer network displacement. Prioritize BIS certification investment for next-generation emitter designs before groundwater extraction caps restrict eligible acreage. For New Entrants and Emerging Players: Begin with sensor-based smart irrigation configurations targeting Nashik and Sangli grape exporters seeking European compliance documentation. White-space exists in cellular telemetry bundling for contract banana growers supplying organized retail chains. Pursue project-based commissioning partnerships with agritech startups in Hyderabad and Bengaluru rather than equipment-only sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor polymer-integrated system designers with established state agency relationships in water-stressed districts of western Maharashtra. Long-term viability hinges on regulatory capture of PM-KUSUM subsidy flows and groundwater cap navigation. Monitor Central Water Commission extraction threshold announcements as the critical inflection signal for acreage eligibility compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive LLDPE resin processing protects margin pools from petrochemical price volatility. |
| Direct State Agency Tender Engagement | Bypassing dealer networks secures volume commitments from Gujarat Green Revolution Company. |
| Smart Irrigation Platform Development | Cellular-connected soil moisture telemetry creates recurring service revenue from export growers. |
| Fertigation Bundling Expansion | Water-soluble fertilizer integration opens recurring revenue streams in vegetable-growing clusters. |
| BIS Certification Fast-Track Investment | Accelerated discharge uniformity testing reduces product launch delays for emitter innovations. |
Research Methodology
Multi-period observation of PM-KUSUM disbursement rates, state nodal agency tender awards, and groundwater extraction cap announcements anchored the trend analysis, supplemented by interviews with Maharashtra Micro Irrigation Corporation procurement officers, Jain Irrigation Systems Ltd product managers, Netafim territory sales heads, and Gujarat-based drip installation contractors. Secondary validation drew from CEA agricultural tariff orders, BIS certification registries, Ministry of Agriculture scheme guidelines, and PLI scheme polymer processing disclosures. Bottom-up farmer adoption modeling and top-down equipment shipment aggregation were cross-referenced for triangulation.
Segment-weighting across product type, end user, technology tier, and installation channel shaped the analytical framework across the analysis window. CAGRs were derived from installed base growth trajectories, replacement cycle assumptions, and subsidy eligibility expansion scenarios. Industry-specific forecast inputs incorporated groundwater table decline rates from Central Water Commission monitoring and horticulture export volume projections from APEDA trade data.
Subsidy disbursement delays, groundwater extraction cap enforcement timing, and polymer resin price volatility are the dominant revision risks to modeled adoption trajectories. Forecasts reflect assumptions about state-level co-payment continuity and BIS certification timeline stability. Practitioners should monitor Central Water Commission block-level extraction designations and PM-KUSUM fund release schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Qatar Agriculture Market