
 Colombia Floriculture Market | 2026-2036
Colombia Floriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Floriculture Market Outlook
Event planning is repositioning as a dominant demand vertical for Colombian growers, shifting volume away from traditional retail bouquet channels. Sunshine Bouquet Company leverages direct farm-to-retailer relationships across North American grocery chains. Elite Flower SAS CI anchors its competitiveness through specialized rose genetics and post-harvest cold-chain infrastructure. Jardines de los Andes SAS differentiates via sustainable certification programs that command premium positioning in European procurement.
Colombia floriculture encompasses the commercial cultivation, harvesting, post-harvest treatment, and export-oriented distribution of ornamental plant material including cut flowers, foliage, seeds, and bulbs, with cold-chain maintenance between 1°C and 3°C preserving vase life during transoceanic transit. Cut flowers dominate export value, while foliage plants capture expanding margin pools from interior landscaping contracts in hospitality. E-commerce channels represent the fastest-growing distribution vector, though wholesale auctions still control price discovery for standardized rose grades.
ICA, Colombia's national agricultural institute, enforces phytosanitary certification that determines market access eligibility for United States and European Union destinations. The Ministry of Environment and Sustainable Development coordinates water-use licensing that constrains expansion in the Bogotá savanna aquifer zone. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their documentation burdens on smallholder cooperative suppliers.
Market Dynamics
ICA's phytosanitary certification overhaul is compressing export timelines for Colombian growers while simultaneously raising compliance barriers for smaller cooperatives. This regulatory tightening concentrates volume among operators with dedicated cold-chain documentation systems.
Growth Catalysts
- Destination wedding procurement:Event planners in North America and Europe are sourcing premium cut roses directly from Bogotá savanna farms, bypassing traditional wholesale auction layers.
- EU deforestation-free regulations:Early compliance with emerging supply chain documentation requirements is securing market access advantages for certified Colombian exporters ahead of enforcement deadlines.
- Equatorial light-cycle production:Year-round harvest capability in the Bogotá savanna corridor eliminates seasonal supply gaps that constrain competitors in temperate growing regions.
Market Restraints
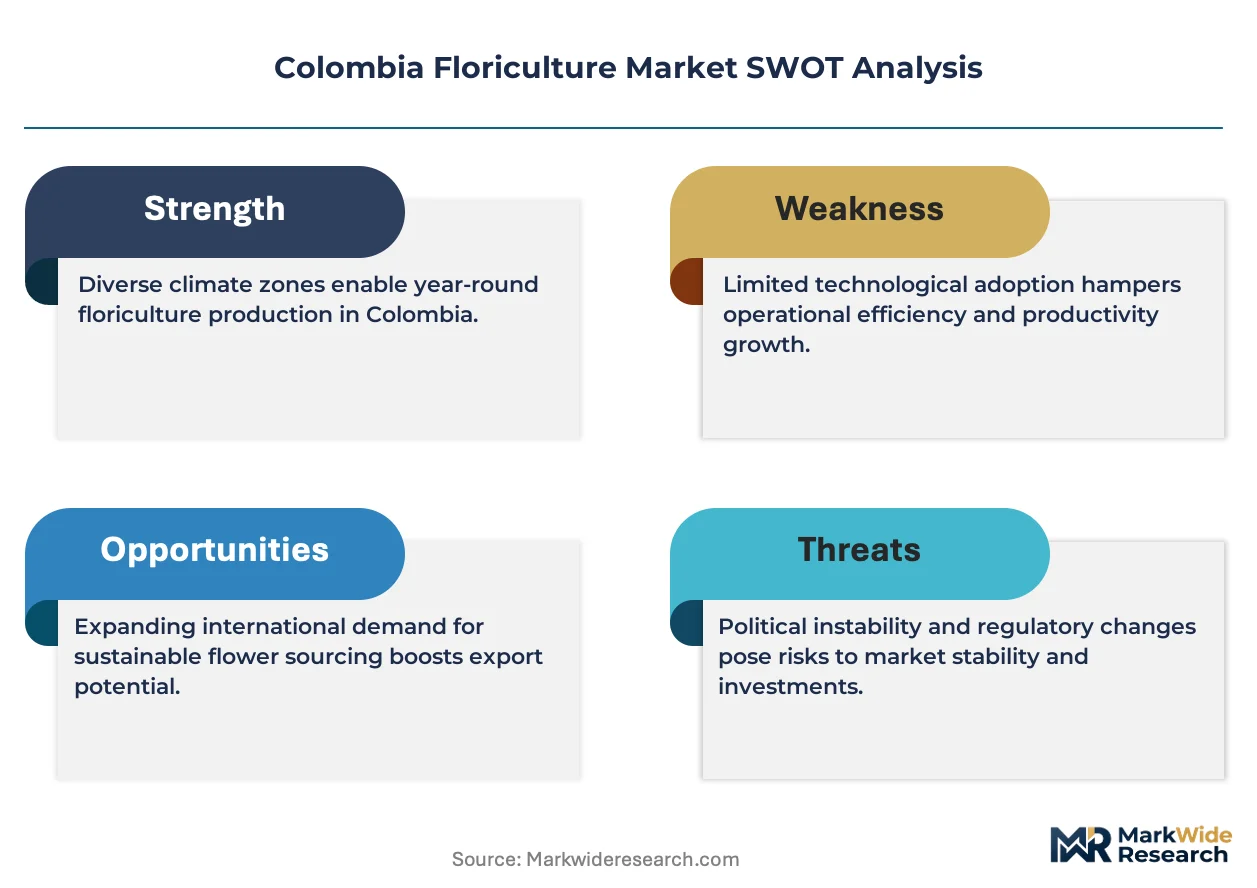
- Aquifer licensing constraints:Ministry of Environment water-use permits in the Bogotá savanna zone restrict farm expansion regardless of export demand signals.
- Fuel-linked freight volatility:Transoceanic air cargo rates for temperature-controlled shipments fluctuate with aviation fuel benchmarks, compressing margin predictability.
- Single-corridor production risk:Altitude-dependent cultivation concentrates 70-plus percent of export volume within a 100-kilometer radius, exposing supply continuity to localized climate events.
Strategic Opportunities
- E-commerce direct-to-consumer channels:Subscription flower services in the United States are accepting shorter-stem, non-auction grades previously rejected by grocery retail buyers.
- Hospitality interior landscaping:Foliage plant contracts for hotel chains in Miami and Dubai generate recurring revenue streams with lower perishability risk than cut flower exports.
- Carbon footprint certification:ICA-coordinated carbon accounting protocols are creating premium positioning for Bogotá savanna producers in sustainability-scored European procurement tenders.
Industry Challenges
- Post-harvest cold-chain technician scarcity:Specialized expertise in 1°C to 3°C temperature protocol management during peak harvest windows commands wage premiums that smaller farms cannot absorb.
- Phytosanitary documentation backlog:ICA certification processing delays during high-volume export seasons force air freight bookings without confirmed clearance, triggering detention penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Floriculture Market |
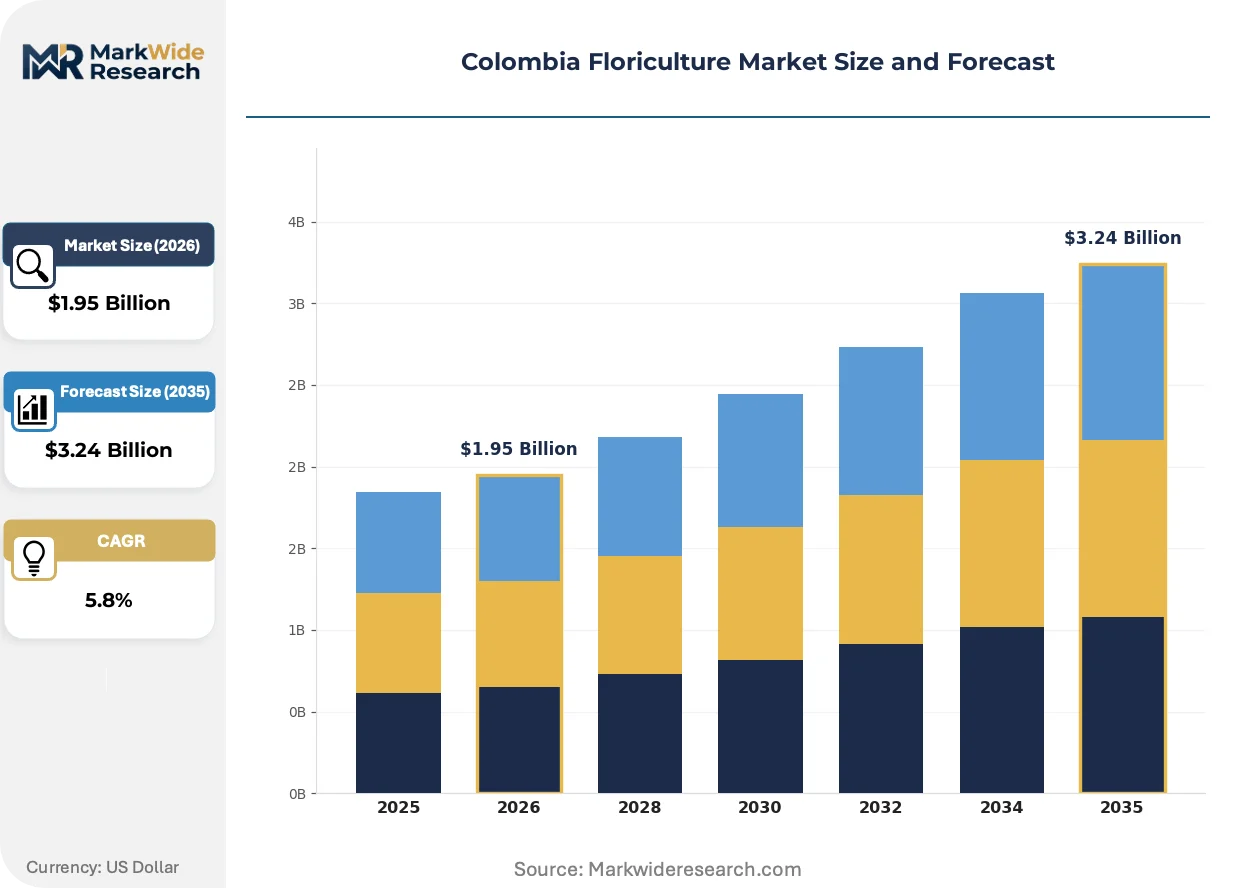
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cut Flowers, Foliage Plants, Flower Seeds, Bulbs Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales End User: Florists, Event Planners, Retail Stores, Exporters Packaging Type: Boxes, Bags, Bunches, Wraps |
| Companies Covered | Flores Funza, Elite Flower SAS CI, Sunshine Bouquet Company, Jardines de los Andes SAS, Agroindustria del Riofrio SAS, Flores El Trigal SAS, Florval SAS, Falcon Farms, Inc., Alexandra Farms SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Floriculture Market Strategic Shifts
Genetic breeding programs and digital traceability systems are converging to reshape how Colombian growers differentiate rose varieties and document provenance for premium buyers. These shifts are compressing the traditional auction-based price discovery model.
LED supplemental lighting is modularizing greenhouse climate control across the Bogotá savanna corridor. Mid-scale farms are adopting tunable spectrum arrays to extend photoperiods during Andean cloud cover weeks. This technology is modularizing the historical dependence on natural light cycles, enabling harvest scheduling that aligns with cargo capacity rather than solar availability.
EU deforestation-free supply chain regulations are mandating geolocation-tagged farm documentation for all ornamental plant imports. Colombian exporters must now integrate GPS boundary verification into ICA certification workflows. Smallholder cooperative suppliers face the steepest adaptation burden, driving consolidation toward vertically documented estate farms.
Buyer concentration among North American grocery chains is compressing stem-length specification tolerance and delivery window flexibility. Procurement teams at major retailers now require farm-direct relationships with documented cold-chain handoff protocols. This behavioral shift is most visible in Miami and Los Angeles distribution hubs, where consolidated import volumes enable just-in-time replenishment models previously impossible through auction intermediation.
Colombia Floriculture Market Segmentation
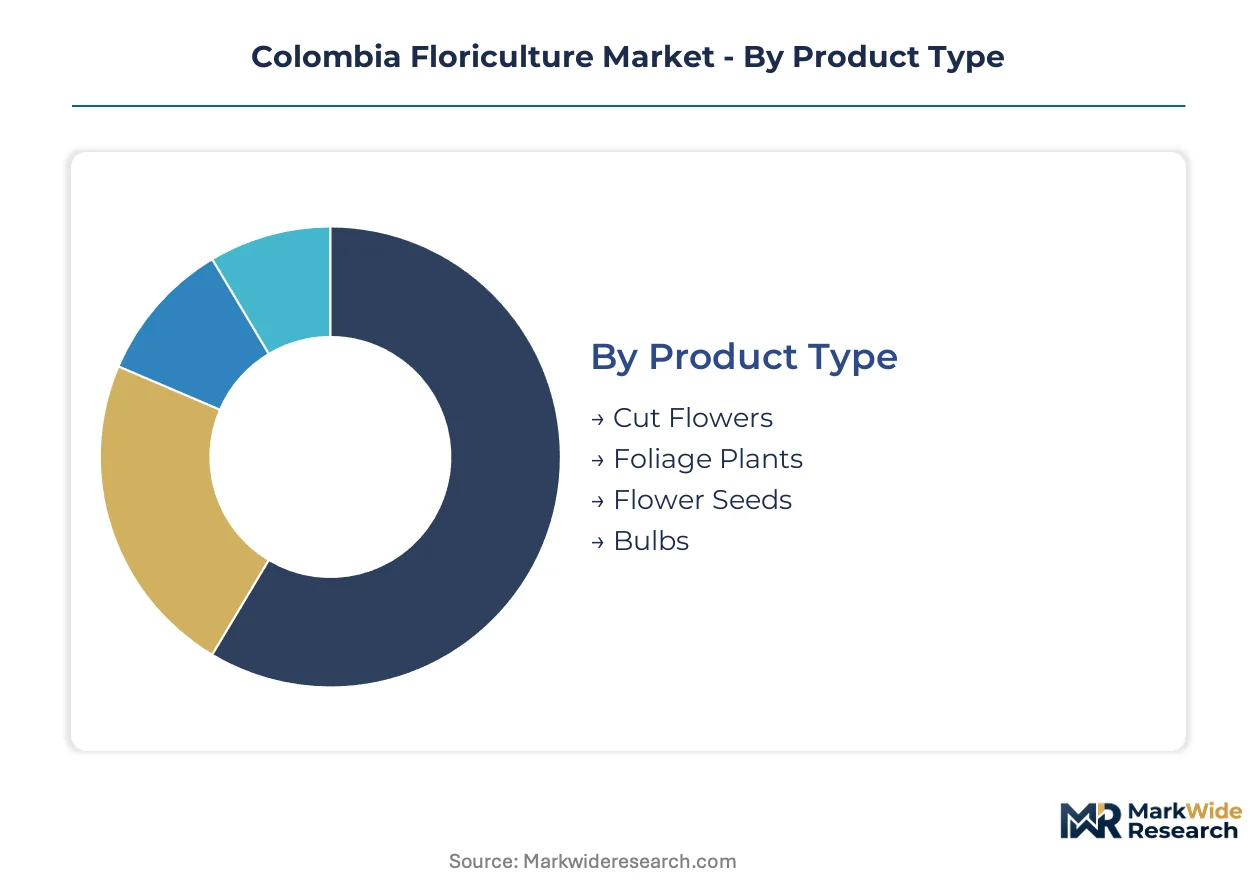
Colombia's floriculture segmentation reveals how altitude-dependent cultivation in the Bogotá savanna corridor shapes product mix and channel economics. Buyer sophistication varies sharply across end-user categories, driving divergent packaging and cold-chain requirements.
Product Type:
Buyers in this category differentiate by perishability tolerance and margin capture potential, with cut flowers commanding premium positioning against longer-cycle alternatives.
- Cut Flowers:Roses, carnations, and chrysanthemums harvested at bud stage for transoceanic air freight. Event planners in Miami and Los Angeles source premium stem lengths directly from savanna farms, bypassing auction intermediaries. ICA phytosanitary certification mandates 1°C to 3°C cold-chain documentation for US and EU market access.
- Foliage Plants:Ornamental leaves and tropical greens for interior landscaping contracts. Hospitality chains in Dubai and Miami generate recurring revenue with lower perishability risk than cut flower exports, though volume scales more slowly.
- Flower Seeds:Genetic stock for propagation programs in temperate growing regions.
- Bulbs:Dormant planting material for seasonal European and North American markets.
Volume sits with Cut Flowers; growth tilts toward Foliage Plants.
Distribution Channel:
Channel selection determines price discovery mechanics and working capital intensity, with direct relationships compressing margin leakage.
- Wholesale:Auction-based price discovery at Miami and Aalsmeer hubs for standardized rose grades. Colombian growers face compressed stem-length tolerance as buyer concentration among grocery chains erodes flexibility.
- E-commerce:Subscription flower services accepting shorter-stem, non-auction grades previously rejected by retail buyers. Direct-to-consumer channels in the United States are expanding most quickly among all distribution vectors.
- Retail:Farm-direct relationships with documented cold-chain handoff protocols at major grocery chains.
- Direct Sales:Estate farm relationships with event planners for destination wedding procurement.
Wholesale still captures the majority of volume; E-commerce is climbing the fastest.
End User:
End-user sophistication drives specification tolerance, with professional procurement teams demanding traceability that informal buyers overlook.
- Event Planners:North American and European destination wedding specialists sourcing premium cut roses directly from Bogotá savanna farms. These buyers prioritize color consistency and harvest-to-delivery timelines over per-stem cost minimization.
- Exporters:Consolidators managing ICA certification workflows and transoceanic air freight bookings. EU deforestation-free regulations now mandate geolocation-tagged farm documentation, concentrating volume among vertically documented estate farms.
- Florists:Small-scale retail operators with mixed-grade tolerance and spot purchasing patterns.
- Retail Stores:Grocery chains with just-in-time replenishment models requiring farm-direct cold-chain protocols.
Volume concentrates with Exporters; margin expansion favors Event Planners.
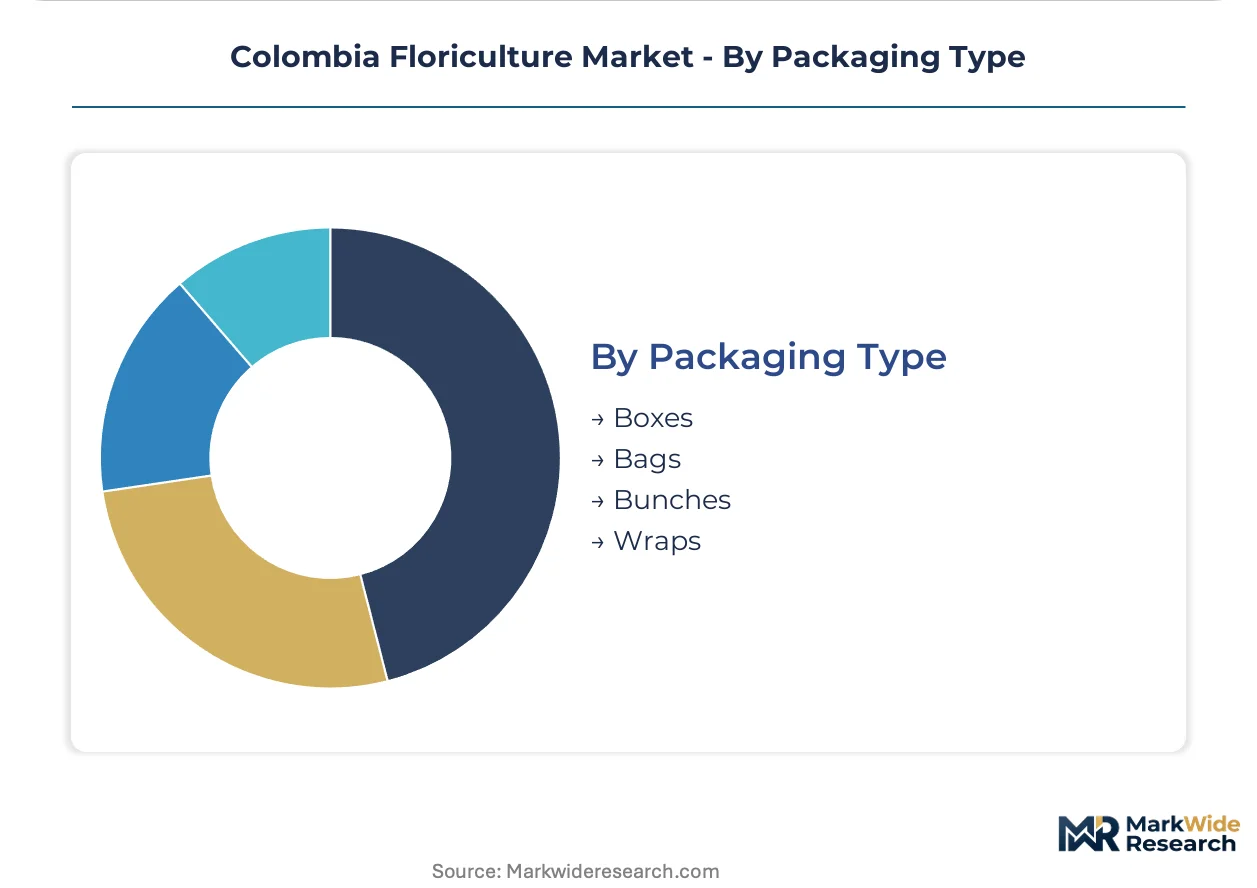
Packaging Type:
Packaging economics hinge on freight density and temperature maintenance duration, with air cargo constraints favoring standardized formats.
- Boxes:Corrugated containers with gel-pack cooling for transoceanic shipments. ICA mandates stricter cold-chain documentation for export clearance, driving adoption of temperature-logging integrated packaging among Bogotá savanna operators.
- Bunches:Stem-bound units for auction-grade roses moving through Miami distribution hubs. Fuel-linked air cargo volatility compresses margin predictability for weight-sensitive formats.
- Bags:Lightweight formats for foliage plant contracts with lower perishability risk.
- Wraps:Protective sleeves for retail-ready bouquet presentation.
Boxes dominate export volume; Bunches gain share fastest in direct retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Bogotá and Cundinamarca concentrate floriculture operations through tax exemptions on imported inputs and export logistics infrastructure. These designated areas anchor 70-plus percent of national export volume within a 100-kilometer radius of the capital.
Bogotá Savanna Corridor
Event planners in Miami and Los Angeles source premium cut roses directly from savanna farms, bypassing traditional auction intermediaries. ICA phytosanitary certification mandates stricter cold-chain documentation for United States and European Union market access. The Funza and Madrid municipalities host the densest greenhouse clusters, where altitude and equatorial light cycles enable year-round production.
Antioquia Department
Medellín-based exporters manage consolidated air freight bookings to Miami distribution hubs. The Ministry of Environment coordinates water-use licensing that constrains expansion in high-altitude aquifer zones. Rionegro and La Ceja municipalities develop specialized carnation genetics programs for European grocery retail contracts.
Cundinamarca Highlands
Sustainable certification programs command premium positioning in European procurement tenders from this sub-region. ICA-coordinated carbon accounting protocols create competitive differentiation for Bogotá-adjacent producers. Zipaquirá and Cajicá greenhouse complexes integrate LED supplemental lighting to extend photoperiods during Andean cloud cover weeks.
Quindío Department
Smaller-scale farms in Armenia and Calarcá supply non-auction grades to United States subscription flower services. The central bank's trade finance facilities support working capital for air cargo bookings during peak Valentine's and Mother's Day export windows. This coffee-belt sub-region diversifies into foliage plants for Dubai and Miami hospitality interior landscaping contracts.
Colombia Floriculture Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with estate farms capturing direct retail relationships while cooperatives serve auction channels. The vendor base concentrates among Bogotá savanna operators with dedicated cold-chain documentation systems, compressing volume among compliant mid-scale and large-scale growers. Three strategic archetypes dominate: vertically integrated estate farms with genetic breeding programs, export consolidators managing ICA certification workflows, and sustainability-certified specialists commanding European premium tenders. Competitive moves center on backward integration into rose genetics and farm-direct bypass of Miami auction intermediaries.
Among Colombia-based cultivators, Elite Flower SAS CI, Sunshine Bouquet Company, and Jardines de los Andes SAS exemplify divergent positioning archetypes. Elite Flower SAS CI occupies the genetics-specialist tier with proprietary rose varieties and post-harvest infrastructure. Sunshine Bouquet Company anchors the farm-to-retail consolidator position through North American grocery chain relationships. Jardines de los Andes SAS sits within the sustainability-certified segment, leveraging environmental credentials for European procurement access. These three represent how Bogotá savanna operators translate altitude advantage into distinct competitive moats.
| Leading Market Players |
|---|
| Flores Funza |
| Elite Flower SAS CI |
| Sunshine Bouquet Company |
| Jardines de los Andes SAS |
| Agroindustria del Riofrio SAS |
| Flores El Trigal SAS |
| Florval SAS |
| Falcon Farms, Inc. |
| Alexandra Farms SAS |
| Others |
Value Chain & Pricing Dynamics
Captive cold-chain infrastructure anchors both supply position and pricing power across the Bogotá savanna corridor. Estate farms with in-house post-harvest systems command premium positioning against cooperative suppliers dependent on third-party logistics, compressing margin capture toward vertically documented operators.
Pricing Analysis
Premium harvest-to-delivery timelines command price escalation against spot auction purchases. Three-tier pricing structure across estate-direct, wholesale auction, and subscription-grade tiers separates stem-length specifications and cold-chain documentation rigor. Cost compression in auction-grade roses intensifies as grocery chain procurement teams consolidate volume and narrow tolerance bands. Event planners demonstrate least price sensitivity; subscription services accepting non-auction grades exhibit highest elasticity.
Supply Chain Analysis
Reverse logistics for perished inventory and temperature-excursion returns flows through Miami cold-storage consolidation points before disposal or composting feedstock recovery. Production concentrates in Colombia, with distribution nodes in the United States and the Netherlands. Supply chain risk centers on single-corridor geographic concentration within the Bogotá savanna aquifer zone. Distribution runs through farm-direct relationships, wholesale auction intermediation, and emerging e-commerce fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED supplemental lighting and GPS-tagged geolocation documentation are displacing legacy solar-dependent scheduling and paper-based ICA certification workflows. This technology transition compresses competitive advantage toward early adopters with capital deployment capacity.
For Market Incumbents: Cement farm-direct relationships with North American grocery chains through documented cold-chain handoff protocols. Expand LED supplemental lighting deployment across Funza and Madrid greenhouse clusters to decouple harvest scheduling from Andean cloud cover patterns. ICA phytosanitary documentation backlog threatens detention penalties; dedicated certification staff buffers this exposure.
For New Entrants and Emerging Players: E-commerce subscription channels offer lowest barrier to volume entry, accepting shorter-stem grades rejected by retail procurement. Target United States direct-to-consumer floral services with non-auction inventory from Quindío Department smallholders. Carbon footprint certification protocols create differentiation wedge in European sustainability-scored tenders.
For Investors and Strategic Acquirers: Exit pathways concentrate in estate-farm consolidation to export consolidators with ICA workflow mastery. Long-term viability favors operators with captive genetics programs and cold-chain infrastructure over cooperative-dependent models. Monitor EU deforestation-free enforcement deadlines as inflection signal for documentation-capable asset premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | ICA mandates stricter documentation, concentrating volume toward compliant operators. |
| Genetic Breeding Program Expansion | Proprietary rose varieties command premium positioning in direct retail channels. |
| E-Commerce Channel Development | Subscription services absorb non-auction grades, expanding addressable volume pools. |
| Sustainability Certification Acquisition | Carbon accounting protocols unlock European procurement tender access. |
| LED Lighting System Deployment | Tunable spectrum arrays enable harvest scheduling aligned with cargo capacity. |
Study Parameters
Document review covered ICA regulatory filings, Ministry of Environment water-use licensing records, and EU deforestation-free regulation drafts, complemented by interviews with greenhouse operations managers, export logistics coordinators, Miami distribution hub procurement leads, and European grocery chain category buyers. Secondary validation drew from customs export data, aviation cargo rate indices, and cold-chain equipment supplier disclosures. Bottom-up farm-level volume estimates triangulated against top-down export value benchmarks.
Cross-reference between historical export trajectory patterns and expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user category, and packaging format alongside altitude-dependent cultivation zone. CAGRs derived from trend extrapolation calibrated against infrastructure capacity constraints and regulatory enforcement timelines. Forecast inputs incorporated LED adoption curves and ICA certification processing capacity.
The model holds under stable EU market access conditions and contained aviation fuel volatility; deviation in aquifer licensing restrictions or transoceanic freight rate spikes would shift volume and value trajectories. Practitioners should monitor ICA certification backlog duration and EU geolocation documentation enforcement rigor for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market