
 Smart Harvest Market | 2026-2036
Smart Harvest Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Harvest Market Outlook
The EU Green Deal is shifting procurement criteria across European fresh produce supply chains, forcing packers and retailers to source from operations with verified labor and environmental compliance. Deere & Company leverages its integrated precision agriculture stack to dominate North American large-farm deployments. Panasonic Corporation anchors Asian greenhouse automation through sensor-to-actuator systems. Harvest CROO Robotics LLC specializes in strawberry-specific robotic pickers for US fresh-market growers.
Smart harvest denotes the integration of autonomous machinery, machine vision, and connected sensor networks to execute or support crop harvesting decisions with minimal human intervention. Systems typically incorporate spectral cameras operating at 400-1000 nm, robotic end-effectors with force-feedback grippers, and edge-computing nodes processing sub-second latency for real-time fruit localization and maturity classification. Robotics commands the highest capital allocation among technology segments as labor substitution economics improve for delicate crops. Automated harvesters within product type generate the steepest replacement cycles, while precision sprayers occupy a more mature upgrade path focused on input-cost reduction.
The EPA governs pesticide application thresholds that smart sprayers must document, while the FDA's Produce Safety Rule mandates harvest-condition traceability that IoT sensor networks directly support. OSHA standards for agricultural machinery operator safety shape robotic system guarding and emergency-stop requirements. Stakeholders must weigh capital deployment timing against evolving regulatory data-submission obligations and the pace of varietal breeding optimized for mechanical harvesting compatibility.
Market Dynamics
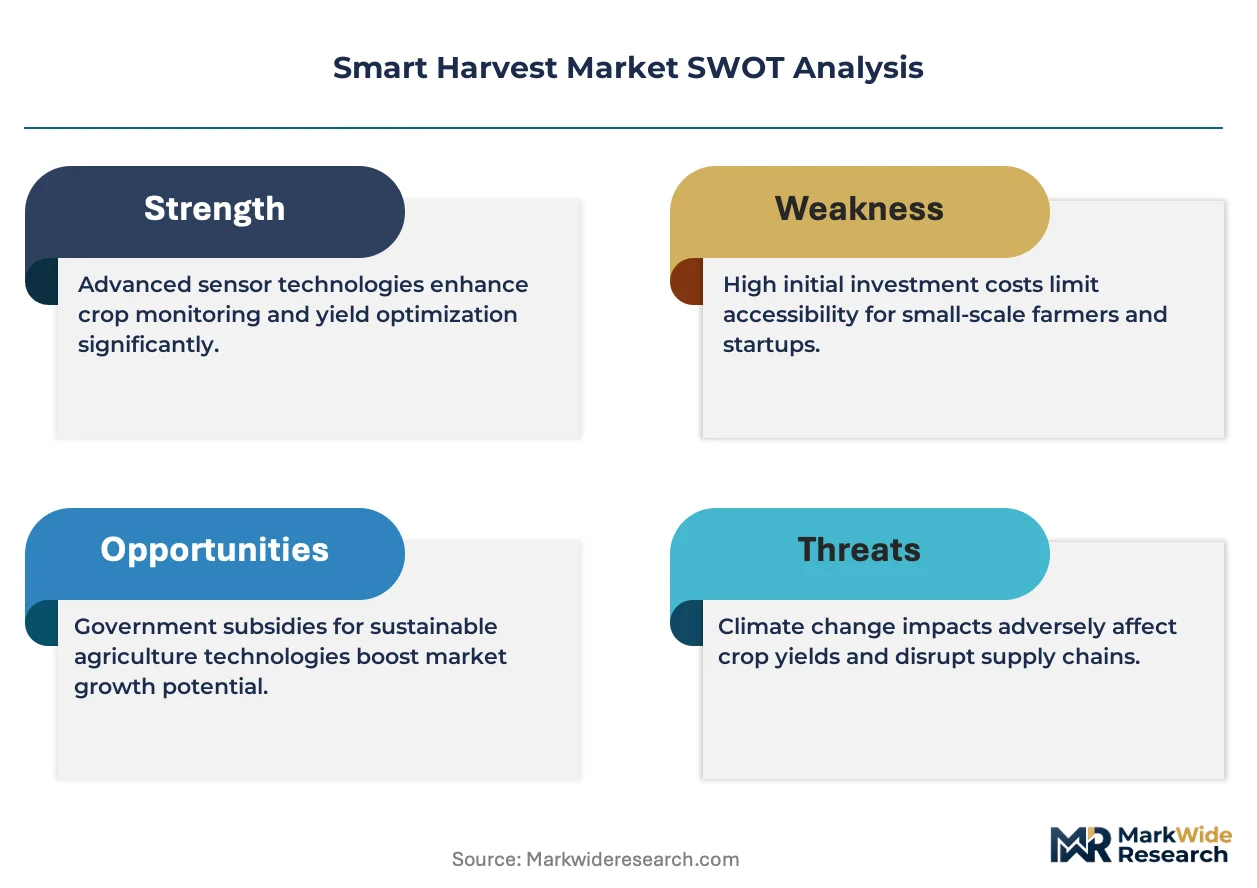
Labor substitution economics for delicate crops is concentrating capital deployment toward robotic harvesting systems, as tightening farm labor regulations in California and Spain force fresh produce growers toward autonomous machinery fleets.
Growth Catalysts
- EU Green Deal procurement mandates:European packers and retailers must now source from operations with verified labor and environmental compliance, redirecting supply chain investment toward automated harvesting infrastructure.
- Machine vision spectral imaging:Cameras operating at 400-1000 nm enable real-time fruit localization and maturity classification, reducing per-unit harvesting labor hours for greenhouse operators.
- California agricultural labor law tightening:Fresh produce growers face escalating compliance costs and worker availability constraints, accelerating payback calculations for robotic strawberry pickers and automated harvesters.
Market Restraints
- High upfront capital intensity:Robotic end-effectors with force-feedback grippers and edge-computing nodes require substantial initial investment, limiting adoption to large-scale operations with balance sheet capacity.
- Varietal breeding lag:Crop genetics optimized for mechanical harvesting compatibility remain underdeveloped for many delicate fruits, constraining system effectiveness across diverse cultivars.
- OSHA machinery safety compliance:Agricultural robotic systems must incorporate extensive guarding and emergency-stop architectures, adding engineering complexity and certification timelines to deployment schedules.
Strategic Opportunities
- Netherlands greenhouse scale optimization:AI-powered crop analytics platforms concentrate demand among Dutch operators pursuing yield maximization, creating anchor customers for integrated sensor-to-actuator systems.
- FDA Produce Safety Rule traceability:IoT sensor networks directly support harvest-condition documentation mandates, opening recurring revenue streams for connected data infrastructure providers.
- Edge-computing and 5G convergence:Sub-second latency processing requirements for real-time fruit classification are driving hybrid architectures that reduce cloud dependency while maintaining decision accuracy.
Industry Challenges
- Mechatronics engineering talent scarcity:Force-feedback gripper design and spectral camera calibration require specialized cross-disciplinary expertise that agricultural regions struggle to attract and retain.
- Legacy equipment integration friction:Greenhouse operators with existing climate control and irrigation automation face complex interoperability challenges when layering robotic harvesting onto heterogeneous technology stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Harvest Market |
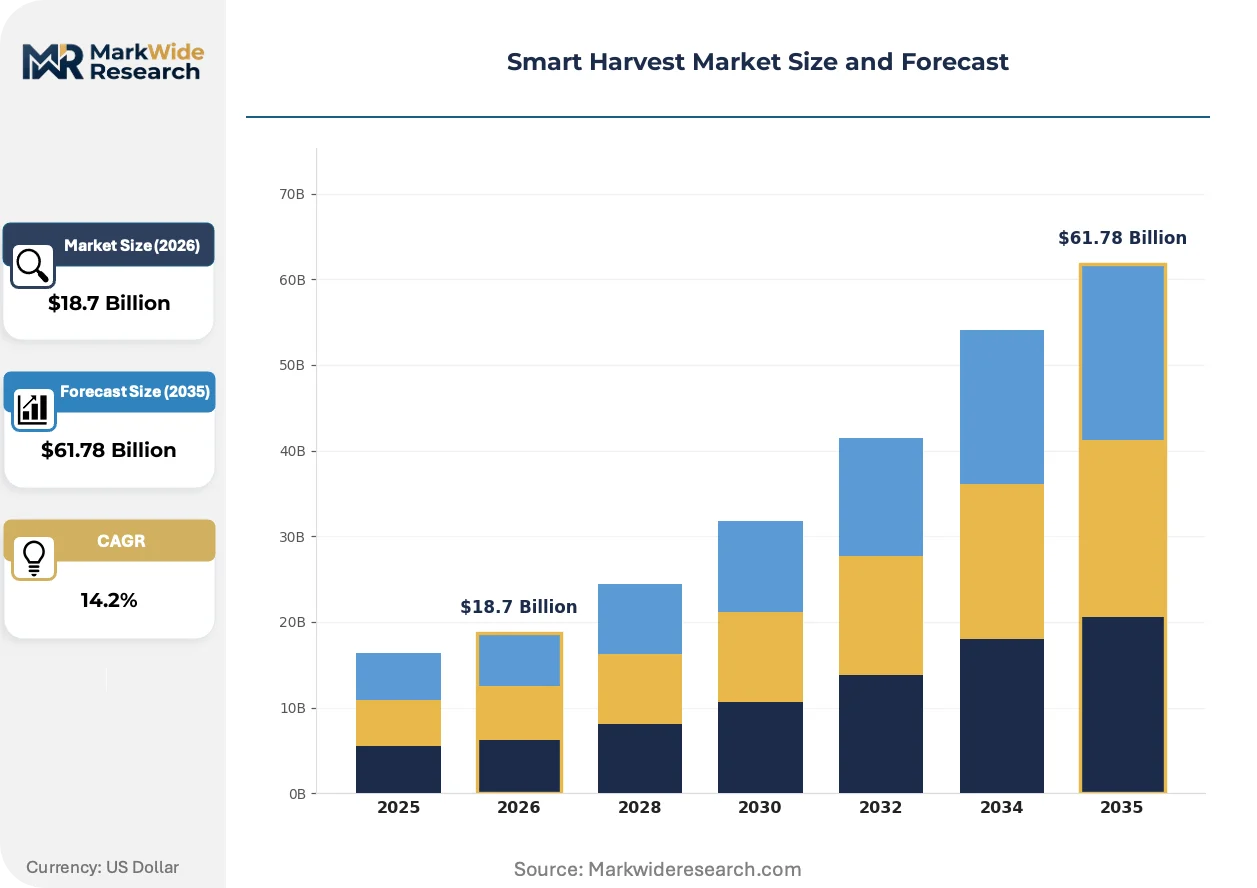
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Drone Technology, IoT Sensors, AI Analytics, Robotics Product Type: Automated Harvesters, Precision Sprayers, Soil Sensors, Crop Monitors End User: Farmers, Agricultural Cooperatives, Agri-Tech Startups, Research Institutions Application: Crop Management, Yield Optimization, Pest Control, Soil Health Monitoring |
| Companies Covered | Deere & Company, Trimble Inc., Robert Bosch GmbH, Agrobot, Harvest CROO Robotics LLC, CNH Industrial, Panasonic Corporation, Vision Robotics Corp., Abundant Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Harvest Market Strategic Shifts
Autonomous machinery architectures are fragmenting traditional harvesting workflows into distributed decision nodes, compressing the gap between sensing and actuation while reshaping how operators deploy capital across growing seasons.
Edge-computing nodes processing fruit localization and maturity classification at sub-second latency is decentralizing harvest decision authority away from centralized cloud platforms. Large-farm operators in North America are deploying these systems at accelerating pace, replacing batch-processed analytics with real-time field-level autonomy. This shift is compressing equipment replacement cycles as growers prioritize low-latency architectures over legacy centralized control systems.
The EPA's pesticide application documentation thresholds are tightening data-capture requirements for smart sprayer operators, mandating granular record-keeping that IoT sensor networks must directly support. Agricultural equipment manufacturers are re-engineering spray systems to embed continuous monitoring and automated logging capabilities. Precision sprayer segments face the steepest compliance adaptation costs, while robotic harvester vendors absorb documentation requirements through existing machine vision infrastructure.
Fresh produce retailers are consolidating supplier qualification criteria around verified automation and labor compliance, displacing traditional procurement relationships based primarily on volume and price. This behavioral shift concentrates contract awards toward greenhouse operators and large farms with capitalized robotic fleets. The Netherlands and Spain exhibit the most pronounced concentration, as EU Green Deal alignment becomes a gatekeeping criterion for shelf access.
Smart Harvest Market Segmentation
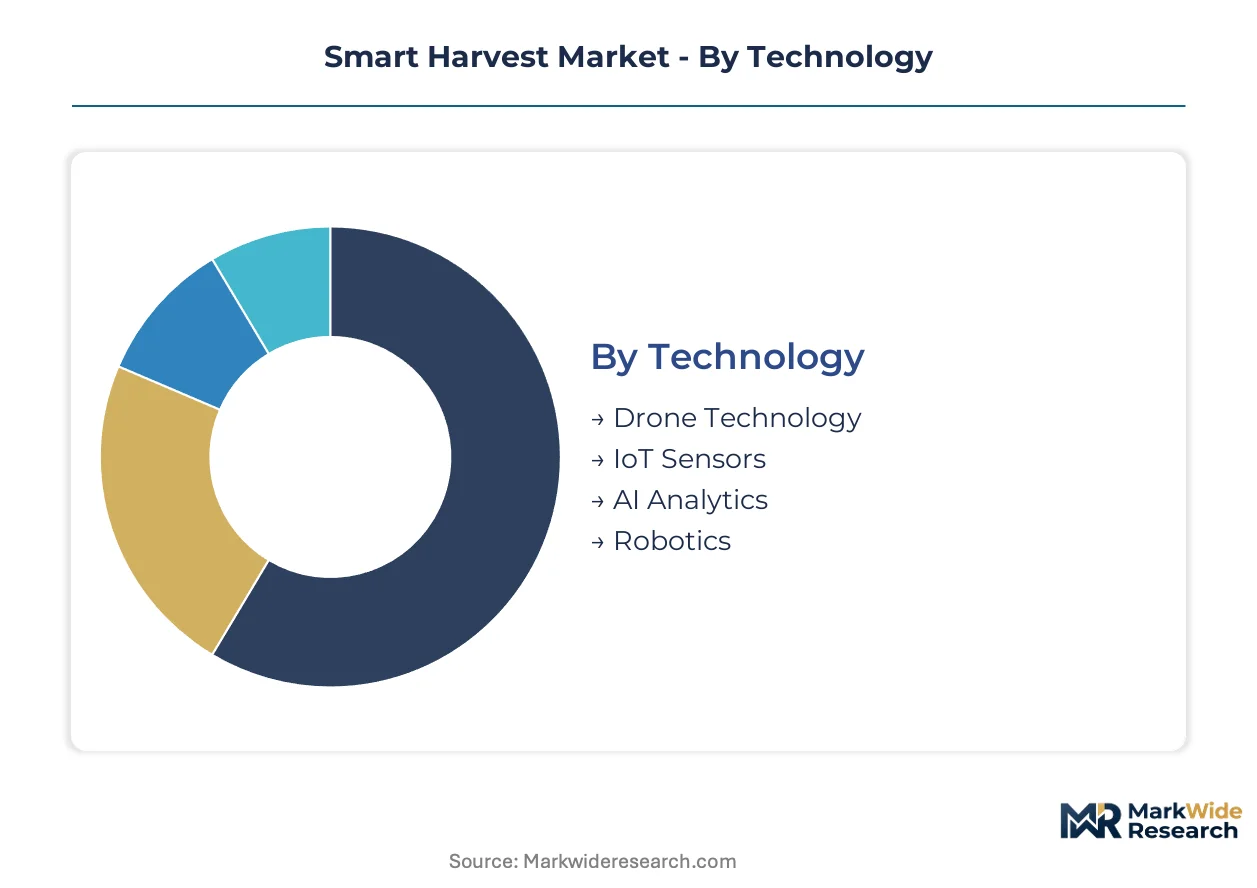
Smart harvest systems fragment across integration architectures that determine capital deployment patterns and replacement cycles. Technology choices cascade into product configurations, end-user economics, and application priorities that reshape competitive positioning across agricultural value chains.
Technology:
Integration depth varies sharply: drone platforms and IoT sensors deploy as standalone point solutions, while AI analytics and robotics demand embedded system architectures with sensor-to-actuator闭环.
- Robotics:Robotic end-effectors with force-feedback grippers and edge-computing nodes execute physical harvesting tasks with minimal human intervention. California strawberry growers and Dutch greenhouse operators concentrate capital deployment here as labor substitution economics improve for delicate crops.
- AI Analytics:Machine learning models process spectral imaging data and sensor feeds to localize fruit and classify maturity in real time. Netherlands greenhouse operators anchor demand for yield optimization platforms that compress decision latency from cloud to edge.
- Drone Technology:Aerial platforms equipped with multispectral cameras enable field-scale crop monitoring without ground infrastructure. Large-farm operators deploy these for rapid acreage coverage where terrain permits.
- IoT Sensors:Distributed soil moisture, temperature, and nutrient monitors feed data streams to centralized or edge platforms. These function as infrastructure layers beneath higher-order analytics and automation systems.
Volume placements concentrate in IoT Sensors; the faster expansion belongs to Robotics.
Product Type:
Cost tier stratification separates capital-intensive automated harvesters from precision sprayers occupying mature upgrade paths focused on input-cost reduction.
- Automated Harvesters:Self-propelled or tractor-mounted systems integrate machine vision, robotic arms, and conveyance mechanisms for selective fruit picking. Fresh produce growers in Spain and California drive replacement cycles as tightening farm labor regulations force fleet expansion.
- Precision Sprayers:Variable-rate application systems with GPS guidance and real-time canopy sensing optimize chemical inputs. These generate steadier upgrade demand from operators targeting EPA documentation compliance and input cost reduction rather than labor substitution.
- Soil Sensors:In-ground or portable probes measuring moisture, pH, and nutrient profiles. These support irrigation and fertilization decisions across farm sizes with lower capital barriers than robotic systems.
- Crop Monitors:Stationary or mobile imaging systems tracking plant health indicators through growth cycles. Greenhouse operators deploy these as precursors or complements to full robotic harvesting infrastructure.
Revenue concentration sits with Automated Harvesters; Precision Sprayers maintain the most predictable replacement cadence.
End User:
Customer type determines procurement scale and integration complexity, from individual farm investments to cooperative pooling and venture-backed startup deployments.
- Agricultural Cooperatives:Member-owned organizations aggregate capital for shared robotic harvesting fleets and sensor networks. These structures dominate procurement in European fresh produce regions where EU Green Deal compliance requirements concentrate investment.
- Farmers:Individual owner-operators deploy point solutions—typically IoT sensors and precision sprayers—within constrained balance sheet capacity. Adoption concentrates among specialty crop producers facing acute labor availability constraints.
- Agri-Tech Startups:Venture-funded enterprises pilot integrated technology stacks on leased or partner acreage. These actors drive early validation of AI analytics and robotics combinations before commercial scale.
- Research Institutions:Universities and government agricultural stations test varietal breeding for mechanical harvesting compatibility and sensor calibration protocols. Their procurement supports technology maturation rather than production economics.
Procurement volume clusters with Farmers; Agricultural Cooperatives are expanding most quickly as compliance costs rise.
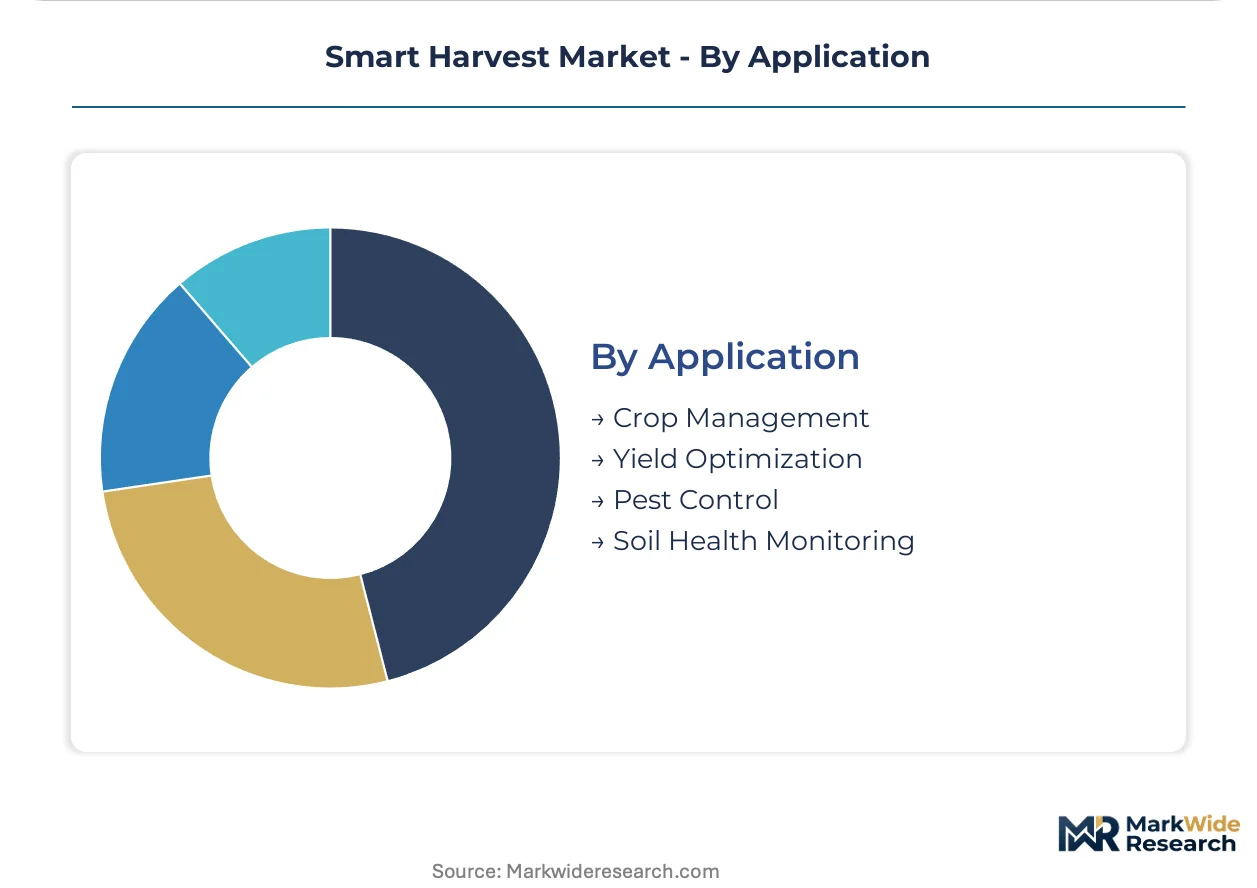
Application:
Application priority reflects operational pain points: labor-driven harvesting automation versus input-cost-driven precision management versus risk-driven pest and soil interventions.
- Crop Management:Integrated monitoring and intervention systems spanning planting through harvest. Greenhouse operators in the Netherlands concentrate demand here as scale optimization becomes competitive necessity.
- Yield Optimization:Data-driven strategies to maximize output per hectare through precise timing of inputs and harvest. AI analytics platforms anchor this application with real-time decision support.
- Pest Control:Targeted chemical and biological intervention guided by sensor detection and predictive models. Precision sprayers dominate this segment with EPA documentation requirements shaping system design.
- Soil Health Monitoring:Continuous assessment of physical, chemical, and biological soil conditions to guide amendment strategies. This application draws on IoT sensor networks with longer payback horizons than harvest automation.
Current deployment favors Crop Management; steepest expansion trajectory belongs to Yield Optimization as analytics platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of smart harvest systems concentrates in industrialized agricultural economies, while consumption spreads across labor-constrained growing regions. Equipment fabrication clusters in Germany, Japan, and the United States. Deployment tilts toward Spain, the Netherlands, and California where regulatory pressure and labor economics accelerate adoption.
United States
California strawberry growers and large-farm operators in the Pacific Northwest drive robotic harvesting procurement. The EPA's pesticide documentation thresholds and OSHA agricultural machinery safety standards shape system design requirements. Salinas Valley and Central Coast clusters anchor precision agriculture deployment, with venture-backed startups piloting integrated sensor-to-actuator stacks on partner acreage.
Netherlands
Greenhouse operators in Westland and North Brabant pursue yield optimization through AI-powered crop analytics platforms. EU Green Deal procurement mandates redirect supply chain investment toward verified automation compliance. Wageningen University and Research anchors varietal breeding programs for mechanical harvesting compatibility, feeding technology validation pipelines.
Spain
Fresh produce growers in Almería and Murcia expand robotic harvesting fleets to comply with tightening EU labor regulations and seasonal worker availability constraints. The country's national agricultural regulator enforces documentation standards that IoT sensor networks must support. Andalusian greenhouse clusters concentrate capital deployment toward automated harvesters as payback calculations improve.
Japan
Panasonic Corporation anchors domestic greenhouse automation through sensor-to-actuator systems, while METI funding programs accelerate precision agriculture R&D. Chubu and Kanto regions concentrate deployment of robotic end-effectors for delicate crop handling. Aging agricultural workforce demographics intensify labor substitution economics across the archipelago's protected cultivation sector.
Germany
Robert Bosch GmbH and precision engineering specialists supply machine vision and force-feedback components to global harvester manufacturers. Bavaria and Baden-Württemberg host mechatronics engineering clusters addressing gripper design and spectral camera calibration. REACH chemical compliance and CE marking requirements shape export-oriented equipment specifications for European and Asian markets.
Smart Harvest Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with precision agriculture portfolios, though specialized robotics ventures occupy critical technology niches. Tier-one players leverage integrated hardware-software stacks to dominate large-farm deployments, while mid-scale specialists concentrate on crop-specific harvesting solutions. Strategic moves center on sensor-to-actuator technology licensing partnerships and varietal breeding collaborations that improve mechanical harvesting compatibility.
Within the diversified industrial tier, Deere & Company exemplifies the integrated precision agriculture archetype through its dominance of North American large-farm deployments. Panasonic Corporation anchors Asian greenhouse automation, representing the sensor-to-actuator systems specialist model. Harvest CROO Robotics LLC occupies the crop-specific robotics niche, exemplifying ventures that concentrate capital deployment on single-commodity harvesting solutions for US fresh-market growers.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| Robert Bosch GmbH |
| Agrobot |
| Harvest CROO Robotics LLC |
| CNH Industrial |
| Panasonic Corporation |
| Vision Robotics Corp. |
| Abundant Robotics |
| Others |
Value Chain & Pricing Dynamics
Steel price volatility on the London Metal Exchange cascades through robotic harvester fabrication costs, compressing margins for mid-tier automated harvester manufacturers while concentrating pricing power among integrated precision agriculture conglomerates with captive component production.
Pricing Analysis
Outcome-based pricing tied to per-hectare yield improvement anchors premium tiers for AI-powered crop analytics platforms. Three-tier pricing structure across premium, standard, and economy levels separates Deere's integrated precision agriculture stack from Panasonic's sensor-to-actuator bundles and point-solution IoT vendors. Cost compression in economy-tier soil sensors is intensifying because Chinese component suppliers are flooding distribution channels. Agricultural cooperatives exhibit highest price sensitivity due to pooled capital constraints; venture-backed agri-tech startups show least sensitivity given risk-tolerant funding structures.
Supply Chain Analysis
Spectral camera sensor supply rests on German precision optics manufacturers and Japanese semiconductor fabricators. Robotic end-effector assemblies draw from Taiwanese mechatronics specialists and Bavarian force-feedback component engineers. Lithium-ion battery cells for autonomous harvester propulsion hinge on South Korean and Chinese suppliers. Single-source vulnerability in 400-1000 nm CMOS image sensors creates procurement risk for machine vision subsystem vendors. Distribution runs through Deere's captive dealer network in North America and Panasonic's industrial equipment channels across Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into force-feedback gripper manufacturing and spectral camera calibration capabilities is accelerating as labor substitution economics improve and component lead times extend.
For Market Incumbents: Extend precision agriculture platform stickiness by embedding FDA Produce Safety Rule compliance documentation into existing IoT sensor networks. Consolidate position through backward integration into edge-computing node production, neutralizing emerging entrant cost advantages in sub-second latency architectures. California agricultural labor law tightening threatens non-integrated harvester vendors with margin compression. For New Entrants and Emerging Players: Capture white-space in strawberry-specific robotic picker retrofits for existing greenhouse infrastructure in Spain's Almería region. Penetrate mid-scale Dutch greenhouse operators bypassed by Deere's large-farm focus. Pursue technology licensing partnerships with Wageningen University varietal breeding programs as primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor crop-specific robotics ventures with validated machine vision pipelines in California's Salinas Valley. Long-term viability hinges on mechanical harvesting compatibility advances across soft-fruit cultivars. Watch EPA pesticide documentation threshold tightening as inflection indicator for precision sprayer consolidation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Actuator Technology Licensing | Panasonic's greenhouse automation stack accelerates third-party robotic harvester integration timelines. |
| Varietal Breeding Collaboration | Wageningen University programs reduce mechanical harvesting compatibility gaps for delicate crops. |
| Edge-Computing Node Manufacturing Scale-Up | In-house production of sub-second latency processors insulates against semiconductor supply shocks. |
| EU Green Deal Compliance Certification | Verified automation documentation unlocks procurement contracts with European fresh produce retailers. |
| 5G-Enabled Real-Time Harvest Analytics | Hybrid architectures reduce cloud dependency while maintaining decision accuracy for Dutch operators. |
Study Parameters
Multi-period observation of robotic harvester deployment rates and greenhouse automation capital expenditure anchored the trend analysis, supplemented by interviews with precision agriculture platform executives, greenhouse operations managers, agricultural cooperative procurement leads, and mechatronics engineering specialists. Secondary validation drew from EPA pesticide application filings, FDA Produce Safety Rule guidance documents, EU Green Deal implementation reports, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up equipment shipment tracking and top-down agricultural labor cost modeling were triangulated.
Input-output matrices connected technology adoption curves to farm labor regulation enforcement intensity across segmentation dimensions including integration architecture depth, crop type mechanization readiness, end-user capital structure, and regional compliance framework. CAGRs were derived from installed base growth rates and replacement cycle compression observed across the projection horizon. Forecast inputs incorporated spectral camera cost decline trajectories and varietal breeding program timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to OSHA machinery safety standard revisions and EU seasonal worker visa policy shifts. Forecasts reflect assumptions about mechanical harvesting compatibility advances and edge-computing cost curves. A small set of triggers—California agricultural labor law ballot initiatives, REACH chemical restriction expansions, and METI precision agriculture subsidy modifications—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Global AI in Agriculture Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
Smart Tap Timer Market