
 Smart Tractor Market | 2026-2036
Smart Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Tractor Market Insights
Subscription-based precision agriculture software is pivoting how tractor OEMs monetize equipment lifecycles. John Deere leverages its integrated Operations Center platform to lock in recurring revenue from yield-mapping and variable-rate application services. CNH Industrial anchors its competitive stance through extensive dealer networks that bundle telemetry subscriptions with hardware sales. AGCO Corporation differentiates via its Fuse open-architecture approach, allowing third-party agronomy tools to integrate with its smart tractor fleet.
A smart tractor integrates GPS guidance, IoT sensors, and automated control systems into a self-propelled agricultural vehicle capable of executing tillage, planting, and harvesting tasks with minimal operator intervention, typically operating within sub-inch accuracy via RTK correction signals. Its primary commercial purpose is to optimize input application rates, reduce fuel consumption, and enable 24-hour field operations during narrow weather windows. Autonomous models and precision agriculture tools represent the fastest-expanding demand pools, as labor scarcity and input cost volatility push commercial farms toward unmanned night operations and sub-field-level input management. Electric tractors occupy an emerging niche where short-duty-cycle vineyards and municipal maintenance fleets prioritize zero-emission compliance over all-day endurance.
The EPA enforces Tier 4 Final and emerging Stage V-aligned emissions standards that compel engine redesigns and after-treatment hardware integration, directly inflating smart tractor development costs and OEM compliance timelines. EU F-Gas Regulation and REACH chemical restrictions further constrain hydraulic fluid formulations and refrigerant choices for cab climate systems, creating technical barriers for non-European manufacturers seeking CE-marked market access. Stakeholders must monitor how rapidly evolving autonomous vehicle liability frameworks and data sovereignty rules reshape software licensing terms and cross-border fleet management architectures.
Market Dynamics
Labor scarcity across commercial row-crop operations is compressing adoption timelines for autonomous tractor platforms, forcing OEMs to accelerate RTK-GPS integration and telematics bundling before full self-driving certification.
Growth Catalysts
- EPA Tier 4 Final mandates:Emissions compliance deadlines are compelling fleet operators in the United States to retire legacy diesel tractors ahead of depreciation schedules, creating replacement demand for cleaner smart tractor models with integrated after-treatment systems.
- RTK correction networks:Sub-inch accuracy guidance systems are expanding coverage across the Corn Belt and Great Plains, enabling night operations and reducing overlap waste during planting and fertilizer application windows.
- Contract farming consolidation:Large-scale agricultural service providers in India are aggregating fragmented landholdings and deploying shared smart tractor fleets to optimize equipment utilization across multiple smallholder clients.
Market Restraints
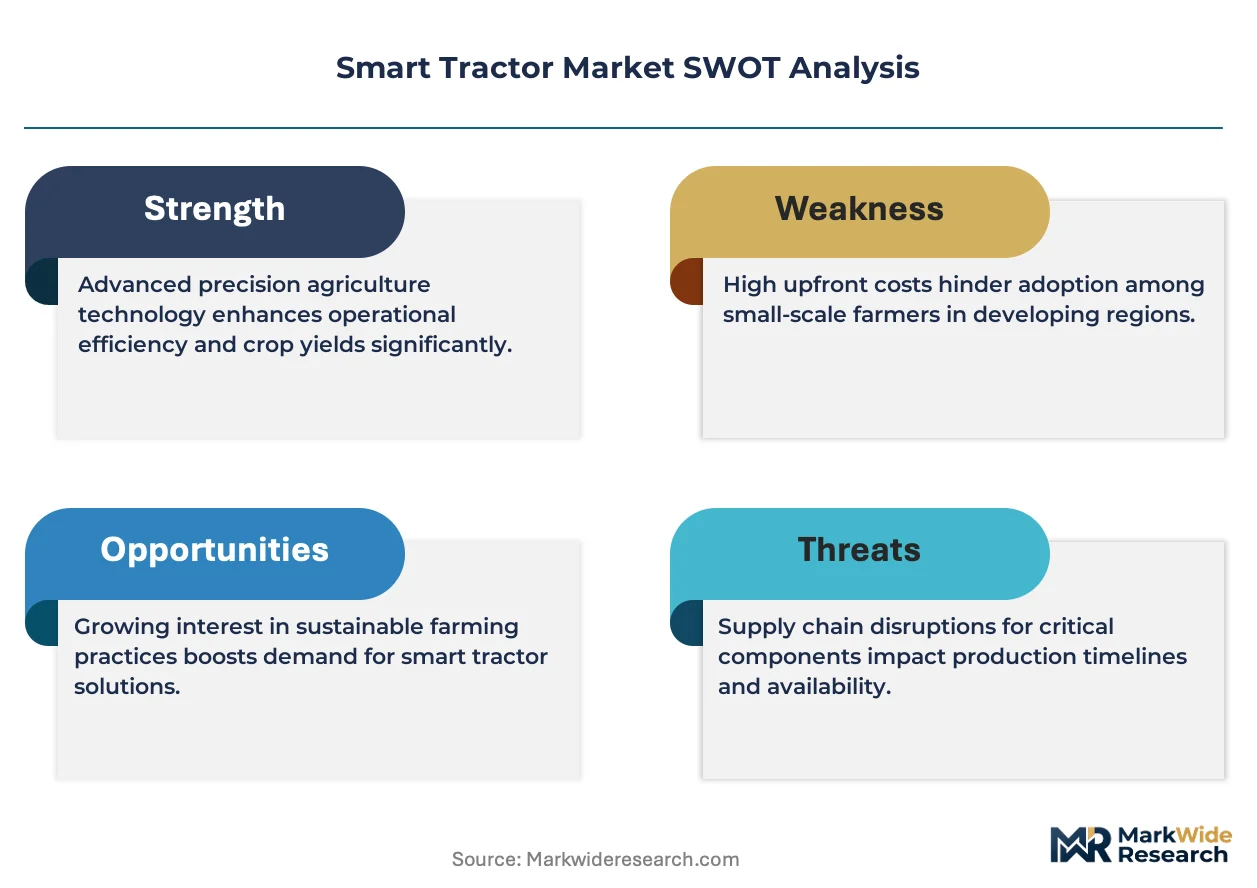
- High-sulfur diesel price volatility:Fuel cost spikes disproportionately impact smart tractor operating economics, as precision features increase weight and baseline fuel consumption compared to stripped-down conventional alternatives.
- Lithium-ion cell supply concentration:Battery pack sourcing for electric tractor prototypes depends on cylindrical cell suppliers concentrated in East Asia, exposing OEMs to export control and shipping disruption risks.
- Autonomous liability framework gaps:Unclear fault allocation between equipment manufacturers, software providers, and operators during unmanned incidents is delaying insurance product development and fleet deployment at scale.
Strategic Opportunities
- Vineyard and orchard electrification:Short-duty-cycle specialty crop operations in France and Italy present immediate addressable demand for battery-electric compact tractors where diesel particulate emissions face municipal restrictions.
- Telematics-to-finance convergence:Usage-based equipment financing models are emerging, allowing lenders to underwrite tractor loans against verified field-hours data streamed from OEM cloud platforms rather than credit scores alone.
- EU F-Gas Regulation phase-down:Refrigerant restrictions on cab climate systems create technical white space for heat-pump-based thermal management suppliers to displace conventional HVAC architectures in next-generation smart cabs.
Industry Challenges
- Embedded software talent scarcity:Agricultural OEMs compete with automotive and aerospace sectors for control systems engineers capable of developing safety-critical autonomous navigation algorithms meeting ISO 26262 standards.
- Legacy fleet interoperability:Proprietary CAN bus protocols and closed telematics architectures prevent mixed-brand smart tractor fleets from sharing implement control data, fragmenting precision agriculture software ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Tractor Market |
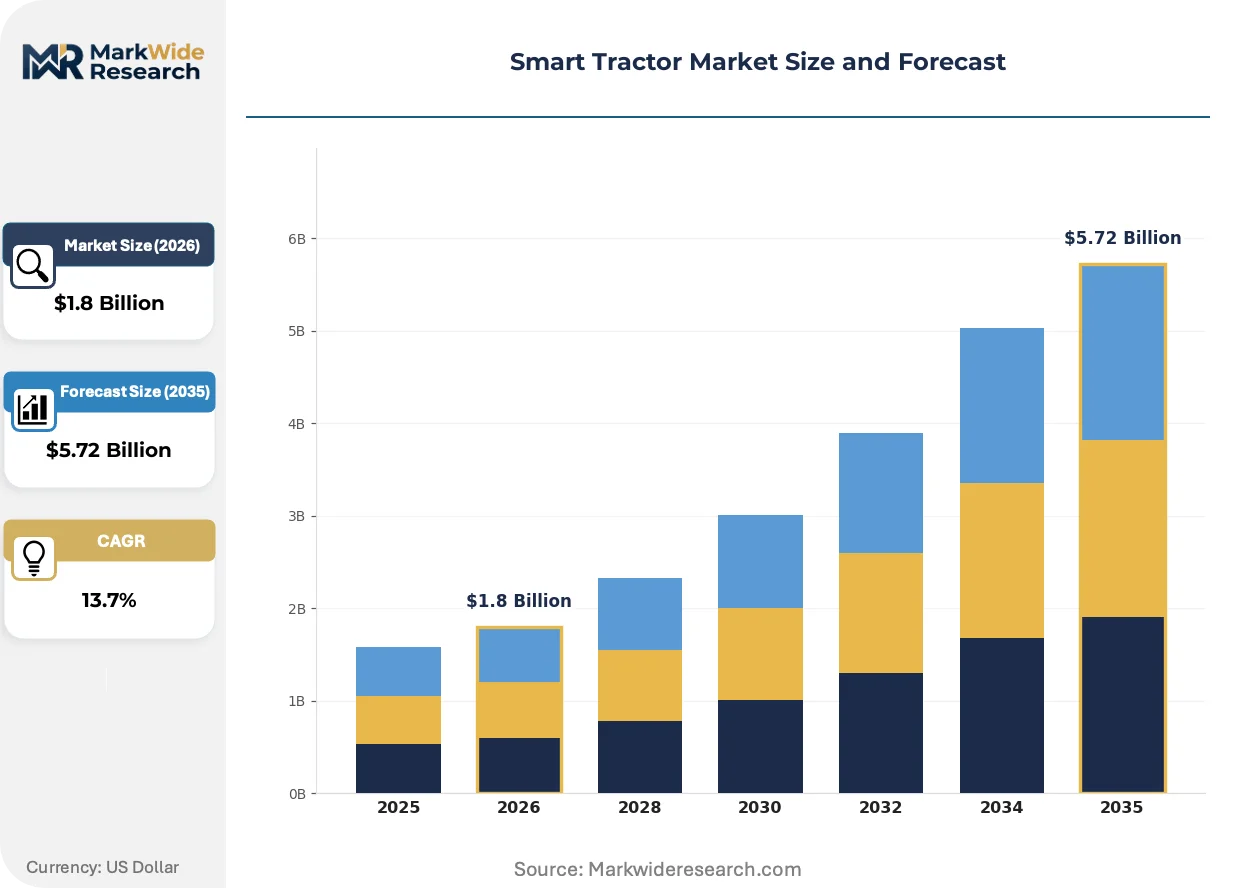
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tractors, Autonomous Models, Hybrid Tractors, Fuel-Cell Tractors Technology: GPS Guidance, IoT Integration, Precision Agriculture Tools, Data Analytics End User: Agricultural Cooperatives, Large Scale Farmers, Small Holders, Government Agencies Application: Crop Cultivation, Land Preparation, Harvesting, Soil Management |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra Ltd, Yanmar Co. Ltd, SDF Group, Trimble, Raven Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Tractor Market Trends and Innovations
Sensor fusion and edge computing architectures are compressing the latency between field data capture and actuator response, enabling real-time agronomic adjustments during single-pass operations.
Machine vision systems paired with convolutional neural networks are absorbing weed identification and selective herbicide spraying tasks previously requiring manual spot treatment. Large grain operations in the United States and Brazil are deploying these platforms at commercial scale during the 2024-2025 growing seasons. The technology is absorbing variable-rate application workflows into single autonomous passes, reducing tractor hours per acre and compressing seasonal equipment demand curves.
REACH chemical restrictions and EU F-Gas Regulation amendments are constraining hydraulic fluid formulations and refrigerant selections for cab climate systems. OEMs serving European markets must reformulate seals and hoses to accommodate bio-based hydraulic fluids with different thermal degradation profiles. Smart tractor lines destined for CE marking now require separate HVAC engineering streams, fragmenting global platform architectures.
Fleet managers are consolidating procurement authority at the holding-company level, displacing decentralized dealer relationships with direct OEM negotiations for multi-year telemetry and precision agriculture software subscriptions. This concentration is most visible across corporate farming operations in the United States and Black Sea grain regions, where procurement teams now bundle hardware, software, and agronomic advisory services into single vendor contracts with penalty clauses for uptime guarantees.
Smart Tractor Market Segmentation
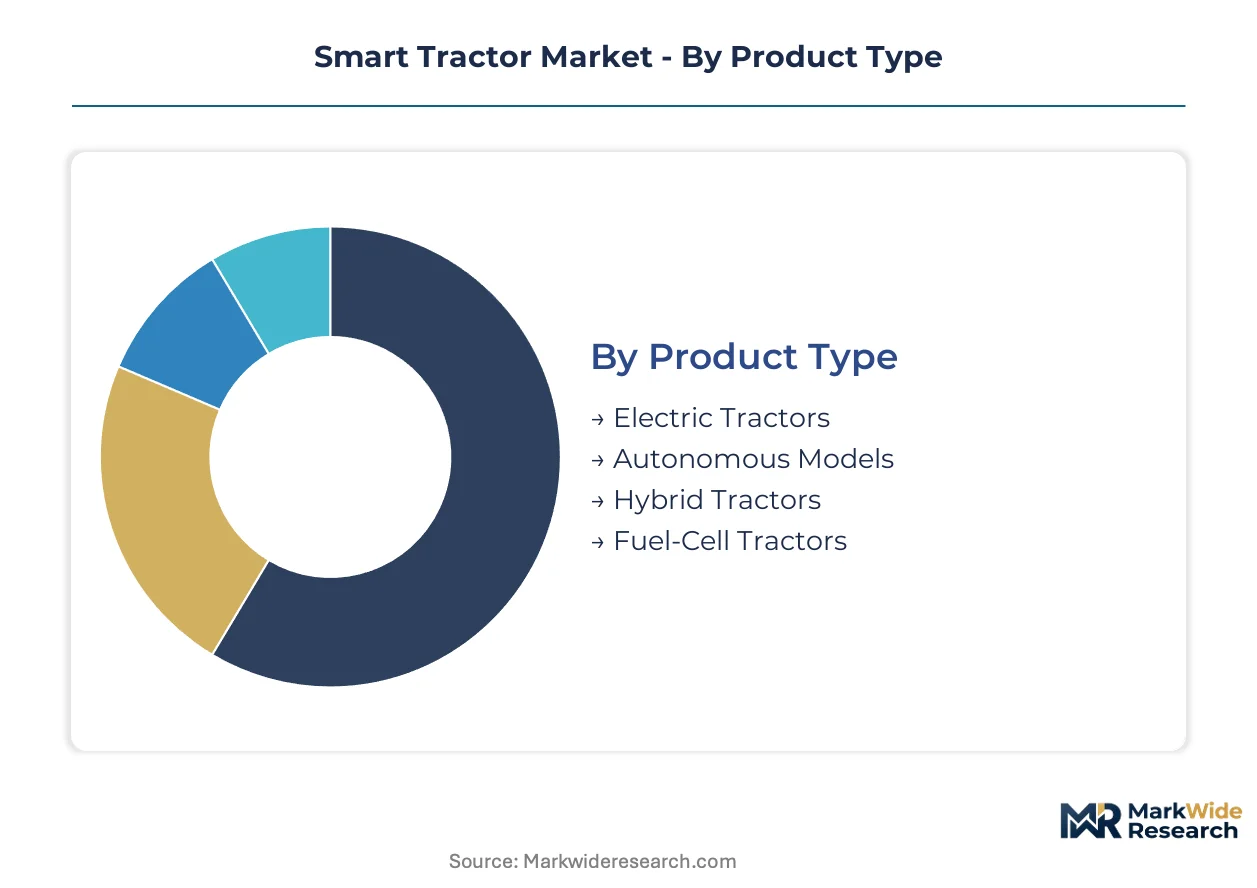
Smart tractor procurement decisions pivot on duty-cycle requirements, infrastructure availability, and labor economics. Segment boundaries are blurring as electrification and autonomy converge on shared platforms, forcing OEMs to engineer modular architectures that span multiple product categories.
Product Type:
Capital intensity varies sharply across powertrain architectures, with fuel-cell prototypes demanding the heaviest upfront R&D investment while electric compact models leverage existing automotive battery supply chains.
- Electric Tractors:Battery-electric drivetrains integrate lithium-ion packs sized for 4-8 hour vineyard and orchard duty cycles. Municipal maintenance fleets in France and Italy are procuring these units to comply with urban emissions restrictions, though range limitations exclude them from large-scale grain operations.
- Autonomous Models:Self-propelled platforms fuse RTK-GPS, LiDAR, and machine vision for unmanned field operations. Large-scale farming operations across the United States are deploying these systems to compress planting windows during labor shortages, despite insurance framework gaps delaying full fleet conversion.
- Hybrid Tractors:Diesel-electric architectures balance torque density with fuel efficiency through regenerative braking and electric PTO assist.
- Fuel-Cell Tractors:Proton-exchange-membrane hydrogen systems target all-day endurance without battery weight penalties, constrained by hydrogen refueling infrastructure scarcity.
Most installed capacity flows through Autonomous Models. Expansion is steepest in Electric Tractors.
Technology:
Technology stack selection determines recurring revenue potential for OEMs, with cloud-connected platforms generating subscription income long after hardware delivery.
- GPS Guidance:RTK correction networks deliver sub-inch positional accuracy for controlled-traffic farming and reduced overlap waste. The Corn Belt and Great Plains regions are seeing dense network buildouts that enable night operations and 24-hour field utilization during narrow weather windows.
- IoT Integration:CAN bus-connected sensors stream engine telemetry, implement status, and fuel levels to OEM cloud platforms. Telematics-to-finance convergence is emerging as lenders underwrite equipment loans against verified field-hours data rather than traditional credit scoring.
- Precision Agriculture Tools:Variable-rate application controllers adjust seeding density and fertilizer flow in real-time based on yield maps and soil sensors.
- Data Analytics:Agronomic decision-support platforms process multi-season field data to optimize input allocation and crop rotation planning.
Deployment density concentrates in GPS Guidance. Subscription revenue growth is climbing fastest in Data Analytics.
End User:
Customer scale dictates procurement authority, with consolidated operators negotiating enterprise software bundles while fragmented smallholders access equipment through shared-service models.
- Large Scale Farmers:Corporate farming operations in the United States and Black Sea grain regions are consolidating procurement authority at holding-company level. These entities negotiate multi-year telemetry and precision agriculture subscriptions with uptime guarantee clauses, displacing decentralized dealer relationships.
- Agricultural Cooperatives:Member-owned entities aggregate equipment purchasing power across hundreds of individual farms. Shared smart tractor fleets in India are optimizing utilization rates across fragmented landholdings through contract farming consolidation.
- Small Holders:Sub-50 hectare operators access precision technology through equipment rental networks and contractor services rather than direct ownership.
- Government Agencies:Municipal and state entities procure compact electric units for roadside maintenance and park management.
Volume leadership sits with Large Scale Farmers. Cooperative fleet aggregation is gaining share fastest in emerging mechanization markets.
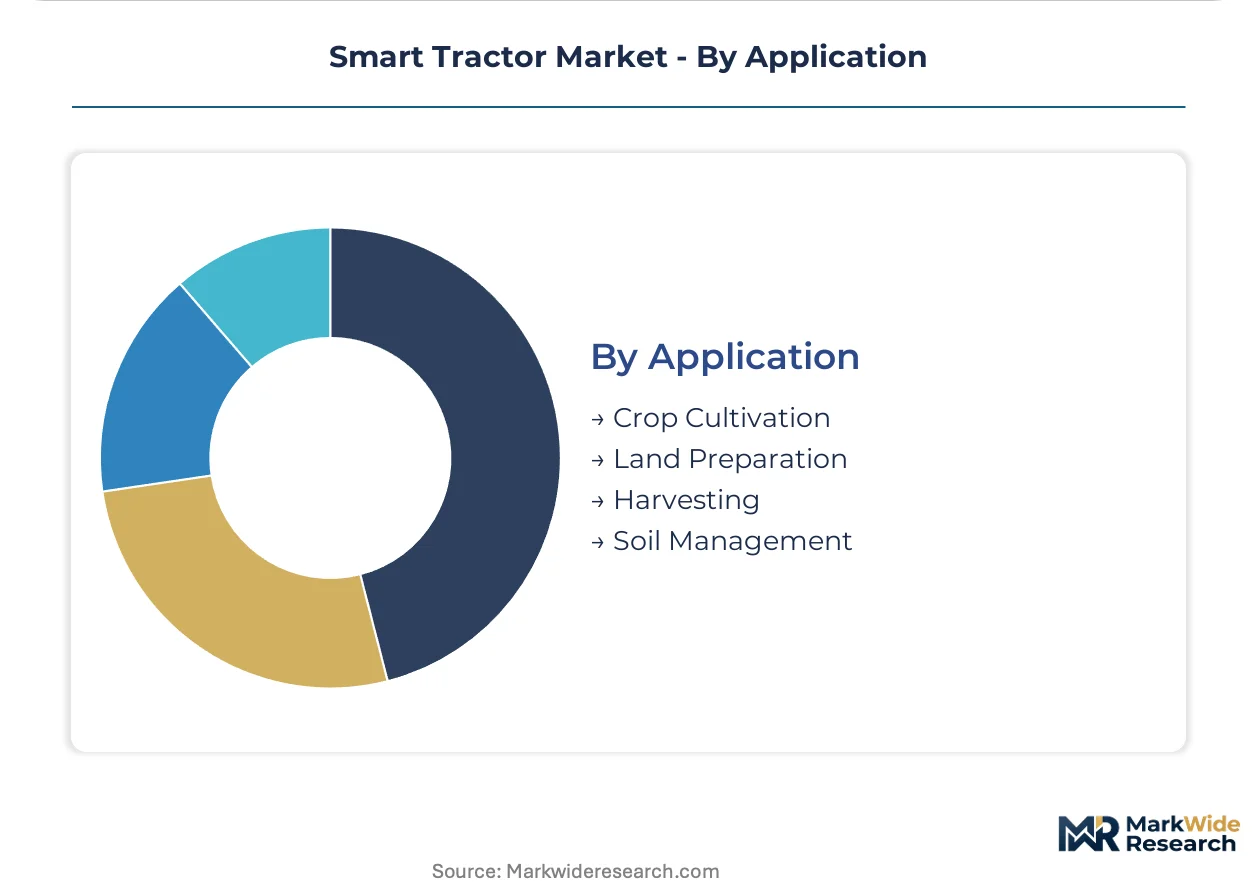
Application:
Task-specific implement requirements drive tractor specification, with high-draft tillage operations demanding maximum engine displacement and harvesting windows requiring maximum PTO power.
- Crop Cultivation:Planting and seeding operations demand precise depth control and row-spacing accuracy enabled by RTK guidance. Machine vision systems paired with convolutional neural networks are absorbing weed identification and selective herbicide spraying into single autonomous passes.
- Harvesting:Grain and forage collection requires high-horsepower PTO output and hydraulic flow capacity for header and thresher drives. Large grain operations in the United States and Brazil are deploying sensor-fusion platforms at commercial scale during current growing seasons.
- Land Preparation:Primary and secondary tillage operations impose the highest draft loads on tractor powertrains.
- Soil Management:Subsoiling, drainage installation, and conservation tillage practices require specialized implement integration.
Equipment hours accumulate heaviest in Crop Cultivation. Technology integration is advancing most rapidly in Harvesting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping smart tractor manufacturing geography as OEMs migrate assembly to jurisdictions with lower compliance burdens while maintaining Tier 4 Final and Stage V certification through modular after-treatment systems. Production cost gaps between emission-standard jurisdictions exceed 12% for equivalent powertrain specifications.
United States
Large-scale farming operations across the Corn Belt and Great Plains are accelerating procurement of GPS-guided autonomous tractor fleets to compress planting windows during labor shortages. EPA Tier 4 Final mandates are compelling fleet operators to retire legacy diesel tractors ahead of depreciation schedules, creating replacement demand for cleaner models. Iowa and Illinois clusters concentrate precision agriculture software development and RTK correction network infrastructure.
Germany
Engineering-intensive OEMs are leveraging advanced manufacturing capabilities to integrate fuel-cell prototypes and heat-pump-based cab climate systems. EU F-Gas Regulation and REACH chemical restrictions constrain hydraulic fluid formulations and refrigerant selections, fragmenting global platform architectures for CE-marked equipment. Stuttgart and Munich metropolitan areas anchor precision agriculture R&D centers and autonomous navigation algorithm development.
India
Contract farming consolidation is aggregating fragmented landholdings and deploying shared smart tractor fleets to optimize equipment utilization across multiple smallholder clients. The PLI scheme for agricultural machinery incentivizes domestic manufacturing of precision agriculture components. Punjab and Haryana states concentrate high-horsepower tractor demand and telematics subscription growth among agricultural cooperatives.
Brazil
Large grain operations are deploying sensor-fusion platforms with machine vision systems for weed identification and selective herbicide spraying at commercial scale during current growing seasons. ANVISA and environmental licensing requirements for agricultural chemicals drive demand for precision application technologies that reduce input volumes. Mato Grosso and Rio Grande do Sul clusters concentrate autonomous harvesting platform deployment and variable-rate controller adoption.
France
Vineyard and orchard electrification presents immediate addressable demand for battery-electric compact tractors where diesel particulate emissions face municipal restrictions in Burgundy and Bordeaux regions. EU F-Gas Regulation phase-down creates technical white space for heat-pump-based thermal management suppliers to displace conventional HVAC architectures. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur concentrate specialty crop equipment procurement and short-duty-cycle electric tractor trials.
Smart Tractor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line OEMs dominating autonomous platform development while component suppliers capture recurring telemetry revenue. The vendor base concentrates around three strategic archetypes: integrated equipment-software platforms bundling hardware with subscription services, precision agriculture specialists supplying guidance and control systems to multiple OEMs, and regional manufacturers serving price-sensitive emerging markets with GPS-enabled but non-autonomous configurations. M&A activity targets telemetry data platforms and machine vision software assets, while strategic partnerships between tractor OEMs and battery cell suppliers address lithium-ion sourcing concentration risks.
Among integrated equipment-software platforms, John Deere and CNH Industrial exemplify the recurring-revenue archetype through bundled precision agriculture subscriptions, while AGCO Corporation occupies a position emphasizing open-architecture interoperability with third-party agronomy tools. These three anchors represent contrasting approaches to customer lock-in versus ecosystem flexibility.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra Ltd |
| Yanmar Co. Ltd |
| SDF Group |
| Trimble |
| Raven Industries |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between Tier 4 Final-compliant autonomous platforms and GPS-enabled conventional tractors manifests in both hardware premiums and supply chain sourcing strategies. EPA emissions mandates in the United States and EU F-Gas Regulation in Europe force parallel engineering streams for CE-marked equipment, fragmenting global platform architectures and compressing margins on non-compliant configurations.
Pricing Analysis
Distributor margins on precision agriculture subscriptions now exceed hardware markups in mature markets. Three-tier pricing structure across premium autonomous fleets, standard GPS-guided models, and economy telemetry-enabled units stratifies procurement authority at holding-company level. Cost compression in mid-range hybrid architectures intensifies as lithium-ion cell volatility feeds into battery pack pricing. Large-scale farming operations in the United States demonstrate lowest price sensitivity due to uptime guarantee clauses, while Indian agricultural cooperatives prioritize per-hour rental economics over capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with cylindrical lithium-ion cell suppliers concentrated in South Korea and Japan. Smart tractor manufacturing draws from German precision hydraulics, Chinese telematics hardware, and Indian steel forgings. Tariff exposure on battery components and semiconductor shortages in edge-computing modules present structural risks. Distribution runs through OEM captive dealer networks in North America and Europe, shifting toward shared-service aggregators in emerging mechanization markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart tractor demand compounds through regulatory ratcheting, with EPA Tier 4 Final and EU Stage V alignment deadlines forcing accelerated fleet replacement ahead of depreciation schedules.
For Market Incumbents: Cement recurring revenue lock-in through telemetry subscription bundling that displaces decentralized dealer relationships. Deepen backward integration into RTK correction network infrastructure to control precision agriculture data flows. Defend against open-architecture challengers by accelerating ISO 26262 certification timelines for autonomous navigation algorithms. For New Entrants and Emerging Players: Machine vision software for selective herbicide spraying presents a technology-first wedge into the harvesting application segment. Vineyard electrification in France and Italy offers immediate addressable demand with shorter duty cycles and municipal emissions restrictions. Pursue telematics-to-finance convergence partnerships that underwrite equipment loans against verified field-hours data. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded software talent scarcity intersects with proprietary CAN bus protocol fragmentation. Long-term viability favors platforms demonstrating cross-brand interoperability or captive data aggregation at fleet scale. Signal to monitor: autonomous liability framework clarity from NHTSA and EU regulatory bodies as inflection indicator for insurance product development and unmanned deployment at scale.| Strategic Initiative | Industry Significance |
|---|---|
| RTK Correction Network Buildout | Sub-inch accuracy coverage expansion enables night operations and 24-hour field utilization during narrow weather windows. |
| Heat-Pump HVAC Architecture Transition | EU F-Gas Regulation phase-down creates technical displacement opportunity for refrigerant-free cab climate systems. |
| Telematics-to-Finance Convergence | Usage-based equipment financing models allow lenders to underwrite against verified field-hours data rather than credit scores. |
| Open-Architecture Platform Development | Third-party agronomy tool integration addresses mixed-brand fleet interoperability barriers fragmenting precision agriculture ecosystems. |
| Fuel-Cell Prototype Commercialization | Proton-exchange-membrane hydrogen systems target all-day endurance without battery weight penalties in large-scale grain operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from precision agriculture software directors, OEM platform engineers, agricultural cooperative procurement heads, and aftermarket service network managers. Secondary validation drew from EPA emissions compliance filings, EU ECHA REACH substance registrations, USDA farm equipment surveys, and customs trade data on agricultural machinery imports. Bottom-up equipment shipment modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting approaches distributed forecast mass across powertrain architecture, guidance technology tier, end-user scale, and regional regulatory cluster. Powertrain splits modeled electric, hybrid, autonomous, and fuel-cell configurations. Technology segmentation tracked GPS guidance, IoT integration, precision agriculture tools, and data analytics subscription penetration. CAGR derivation applied logistic diffusion curves for autonomous adoption and linear extrapolation for mature guidance markets. Labor scarcity indices and diesel price volatility scenarios fed sensitivity testing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to autonomous liability framework evolution, lithium-ion supply concentration disruptions, and REACH chemical restriction amendments affecting hydraulic fluid formulations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Fertigation Monitoring Market