
 Smart Farming Technology Market | 2026-2036
Smart Farming Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Farming Technology Market Insights
Precision-grade automation is rotating the Smart Farming Technology market toward higher-accuracy equipment tiers that command premium positioning. Deere & Company leverages its integrated autonomy stack to dominate North American row-crop automation. Trimble Inc. specializes in GNSS-guided steering and variable-rate application systems for mixed-fleet operations. AGCO Corporation competes through its open-platform FendtONE architecture, which extends third-party developer access across its equipment lines.
Smart farming technology encompasses sensor networks, autonomous machinery, aerial imaging platforms, and cloud-based decision-support systems that optimize input application, livestock health, and harvest logistics through real-time data fusion. These systems typically operate at sub-inch GPS accuracy with latency below 100 milliseconds for autonomous steering and variable-rate control. The technology dimension shows IoT connectivity and machine learning analytics capturing the fastest expansion as farm operators prioritize predictive yield modeling and automated irrigation triggers over standalone hardware. Within applications, crop monitoring retains the largest installed base while livestock management generates higher per-unit software margins due to recurring health-analytics subscriptions.
The EPA regulates agricultural drone operations and chemical application thresholds under FIFRA and Part 107 waivers, while the EU Green Deal and F-Gas Regulation constrain machinery emissions and refrigerant choices across European equipment fleets. USDA conservation programs and NRCS technical standards further shape adoption incentives through cost-share structures for precision nutrient management. Stakeholders must weigh compliance trajectory against platform interoperability investments as regulatory fragmentation between jurisdictions intensifies.
Market Dynamics
The Smart Farming Technology market rotates around precision-grade automation as commercial growers face tightening EU Green Deal emissions mandates and water-use standards that demand sub-inch accuracy in input application.
Growth Catalysts
- Variable-rate application technology:Large-scale row-crop operators in the US Corn Belt deploy GNSS-guided steering to reduce fertilizer overlap and comply with USDA NRCS nutrient management cost-share thresholds.
- EU F-Gas Regulation:Machinery emissions constraints across European fleets accelerate replacement cycles for diesel-powered equipment with electric and hybrid autonomous platforms.
- California Central Valley concentration:Water scarcity in this agricultural cluster drives adoption of soil moisture sensor networks and automated irrigation triggers tied to cloud-based analytics.
Market Restraints
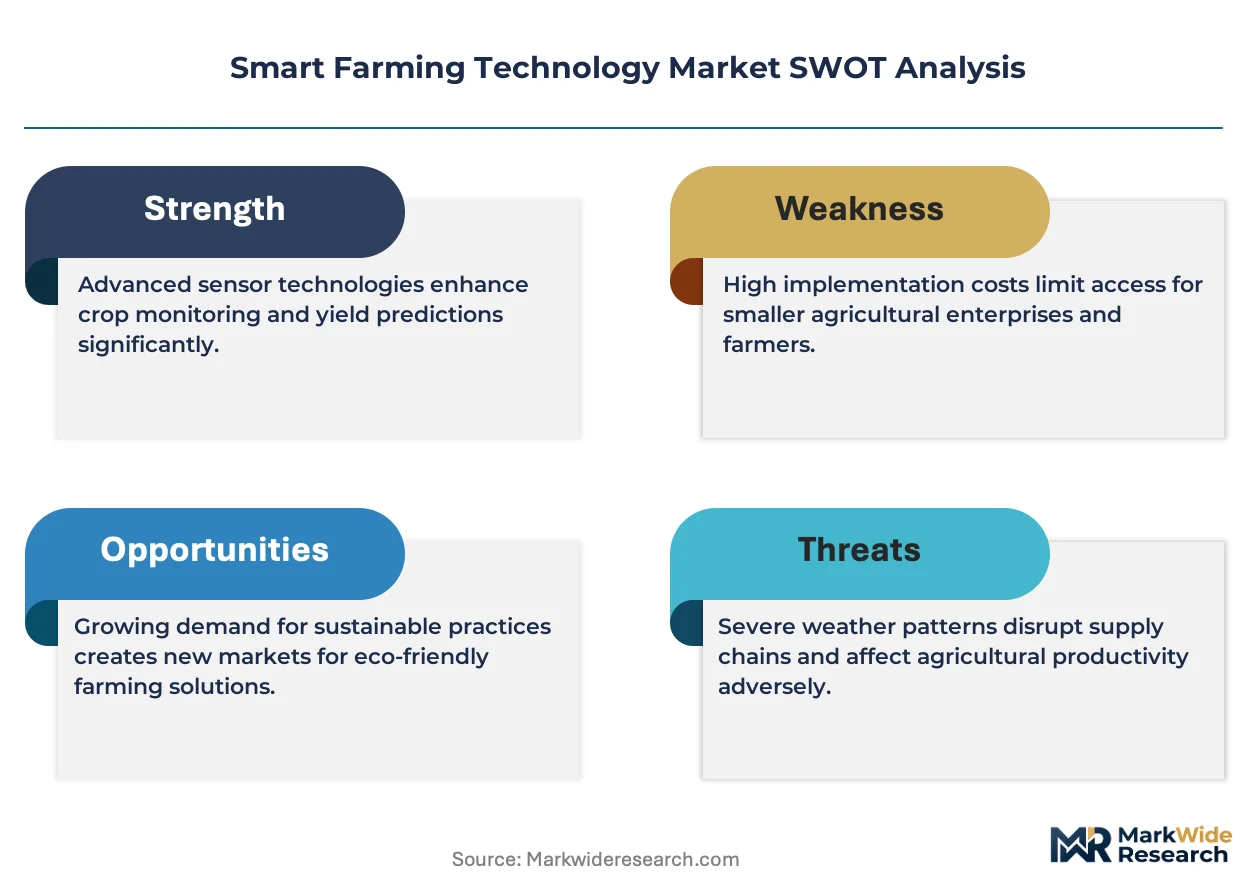
- Silicon supply concentration:Semiconductor fabrication for edge-computing modules concentrates in East Asian foundries, exposing equipment manufacturers to geopolitical disruption in chip availability.
- Legacy fleet incompatibility:Proprietary CAN bus protocols from incumbent OEMs block retrofit of third-party autonomy stacks onto existing tractors and harvesters.
- Cellular connectivity gaps:Rural broadband deserts in agricultural regions delay real-time data transmission for autonomous steering systems requiring sub-100-millisecond latency.
Strategic Opportunities
- Livestock health analytics:Dairy and feedlot operations in the Netherlands and Denmark present underpenetrated demand for recurring subscription software monitoring animal biometric data.
- India PLI scheme:Production-linked incentives for precision agriculture equipment manufacturing create localized assembly opportunities for sensor-integrated machinery serving South Asian smallholder cooperatives.
- Drone-swarm imaging convergence:Multi-rotor aerial platforms fused with hyperspectral cameras enable pest detection at plant-level resolution, opening vineyard and orchard segments previously served by manual scouting.
Industry Challenges
- Mechatronics talent scarcity:Rural equipment dealerships lack technicians trained in hydraulic-electronic integration for autonomous steering retrofit installations.
- EPA Part 107 waiver delays:Agricultural drone operators face extended approval timelines for beyond-visual-line-of-sight chemical application, compressing seasonal deployment windows.
- Interoperability certification backlog:ISO 11783 compliance testing for mixed-fleet telemetry creates bottlenecks as third-party developers seek FendtONE and comparable open-platform integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Farming Technology Market |
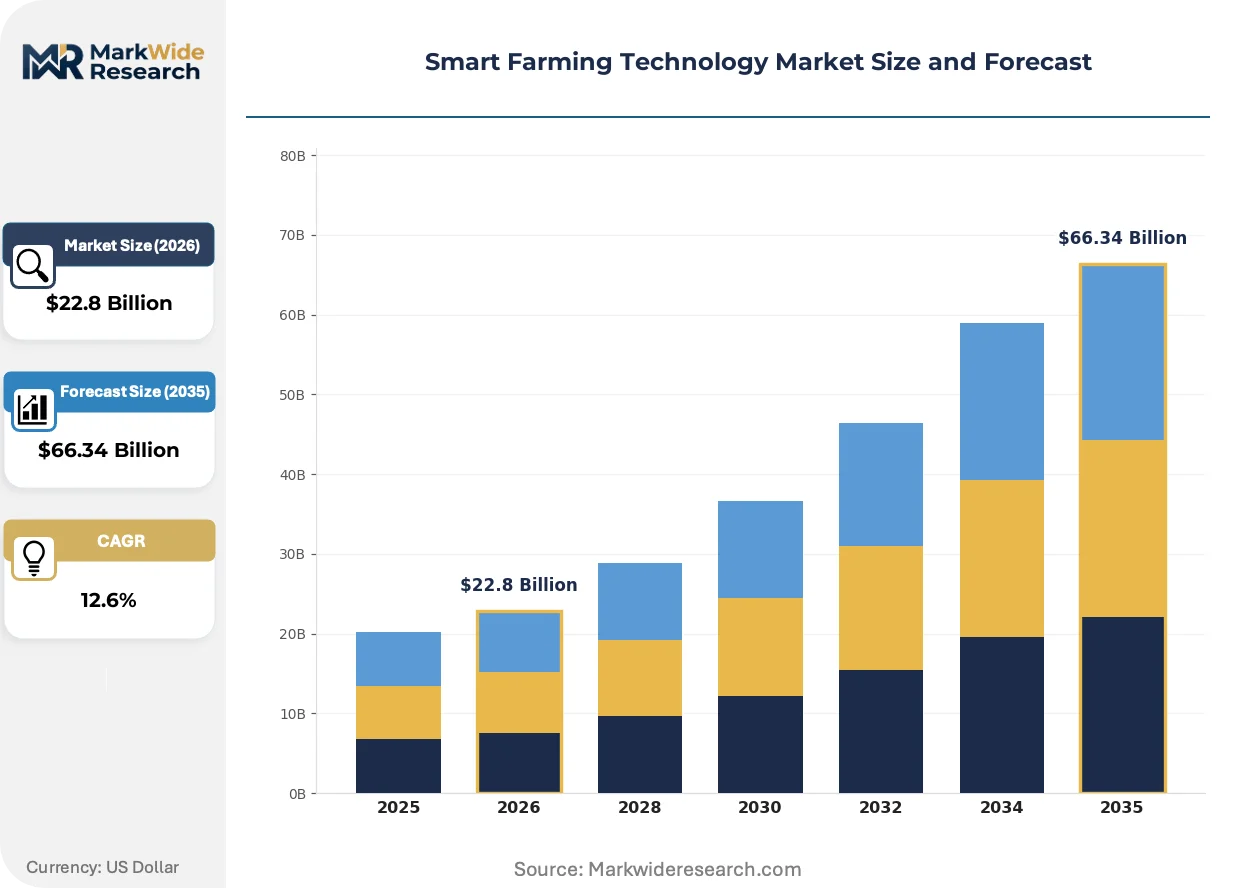
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $66.34 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Drones, Irrigation Systems, Software Technology: IoT, Artificial Intelligence, Big Data Analytics, Machine Learning Application: Crop Monitoring, Livestock Management, Soil Management, Weather Forecasting End User: Farmers, Agricultural Cooperatives, Government Agencies, Research Institutions |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, Topcon Corporation, CNH Industrial N.V., Raven Industries, Kubota Corporation, DeLaval, DJI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Farming Technology Market Trends and Innovations
Sensor fusion architectures and edge-computing deployment are compressing decision latency from field to cloud, while regulatory pressure on emissions and chemical application reshapes equipment specifications and operator certification requirements.
Multispectral imaging sensors mounted on unmanned aerial vehicles is miniaturizing from kilogram-scale payloads to gram-level modules that integrate directly onto crop-spraying drones. Vineyard managers in France's Bordeaux region adopt these platforms for mildew detection at per-vine resolution. The form-factor reduction is compressing hardware margins while expanding addressable acreage for precision viticulture beyond estate-scale operations.
The EU AI Act's risk classification framework for autonomous machinery imposes conformity assessment obligations on self-driving tractors operating in public road segments between fields. German equipment manufacturers now embed explainability logging in steering algorithms to satisfy notified body audit trails. This regulatory layer adds six-to-twelve-month certification cycles that delay North American product launches for European-developed autonomy stacks.
California's Central Valley growers now unbundle equipment purchases from annual service contracts, preferring subscription access to yield-forecasting algorithms over capital expenditure on owned sensor hardware. Dealer networks respond with usage-based pricing for telemetry dashboards. This preference shift concentrates software revenue with cloud platform operators while compressing margins on tractor and harvester unit sales in the United States' highest-value vegetable-producing region.
Smart Farming Technology Market Segmentation
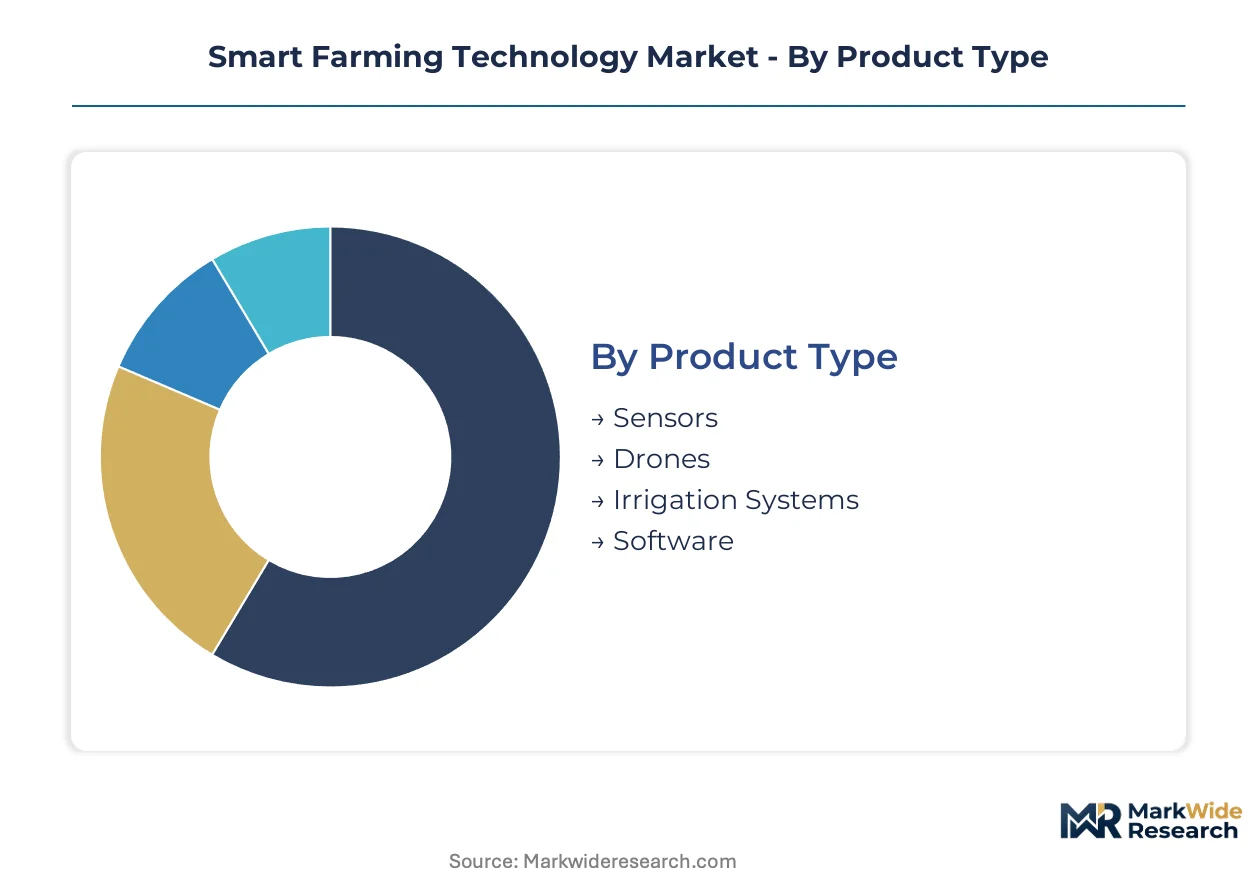
Segmentation in smart farming technology reveals how precision agriculture investments concentrate across hardware, software, and service layers. Equipment manufacturers and platform operators use these divisions to align R&D spend with regulatory compliance requirements and farm operator purchasing patterns.
Product Type:
Sensor networks face substitution pressure from integrated drone-mounted systems that combine multiple detection modalities in single platforms.
- Sensors:Soil moisture probes, weather stations, and canopy sensors deploy at sub-acre density across California Central Valley vegetable operations. USDA NRCS cost-share programs reimburse up to 75% of installation costs for nutrient monitoring arrays in the Corn Belt.
- Drones:Fixed-wing and multi-rotor aerial platforms carry hyperspectral cameras for plant-level pest detection. EPA Part 107 waiver delays constrain beyond-visual-line-of-sight chemical application in US row-crop regions.
- Irrigation Systems:Automated drip and pivot systems integrate valve controllers with cloud-based moisture triggers.
- Software:Yield-forecasting algorithms and telemetry dashboards operate on subscription pricing models.
Sensors anchor the volume base while drones gain share at the steepest rate.
Technology:
Cost tier differentiation separates capital-intensive edge-computing deployments from lightweight cloud-dependent implementations.
- IoT:Low-power wide-area networks connect field sensors to cellular gateways with latency below 100 milliseconds for real-time irrigation triggers. Rural broadband gaps in agricultural regions delay deployment in Nebraska and Kansas wheat belts.
- Artificial Intelligence:Computer vision models process aerial imagery for weed identification and crop stress classification. EU AI Act conformity assessments add six-to-twelve-month certification cycles for autonomous steering algorithms in German-developed equipment.
- Big Data Analytics:Cloud platforms aggregate multi-season yield records with soil composition maps.
- Machine Learning:Predictive models forecast harvest logistics and input requirements.
IoT infrastructure commands the largest installed base while artificial intelligence expands most quickly.
Application:
Volume concentration in mature segments contrasts with margin expansion in specialized monitoring categories.
- Crop Monitoring:Multispectral imaging and NDVI analysis cover broadacre grains and specialty crops. Vineyard managers in France's Bordeaux region deploy gram-level sensor modules for per-vine mildew detection.
- Livestock Management:Biometric ear tags and automated feeding systems generate recurring software subscriptions. Dairy operations in the Netherlands and Denmark present underpenetrated demand for animal health analytics.
- Soil Management:Variable-rate lime and fertilizer application relies on grid-sampled nutrient maps.
- Weather Forecasting:Hyperlocal precipitation models inform planting and spraying windows.
Crop monitoring retains the largest footprint while livestock management climbs the fastest.
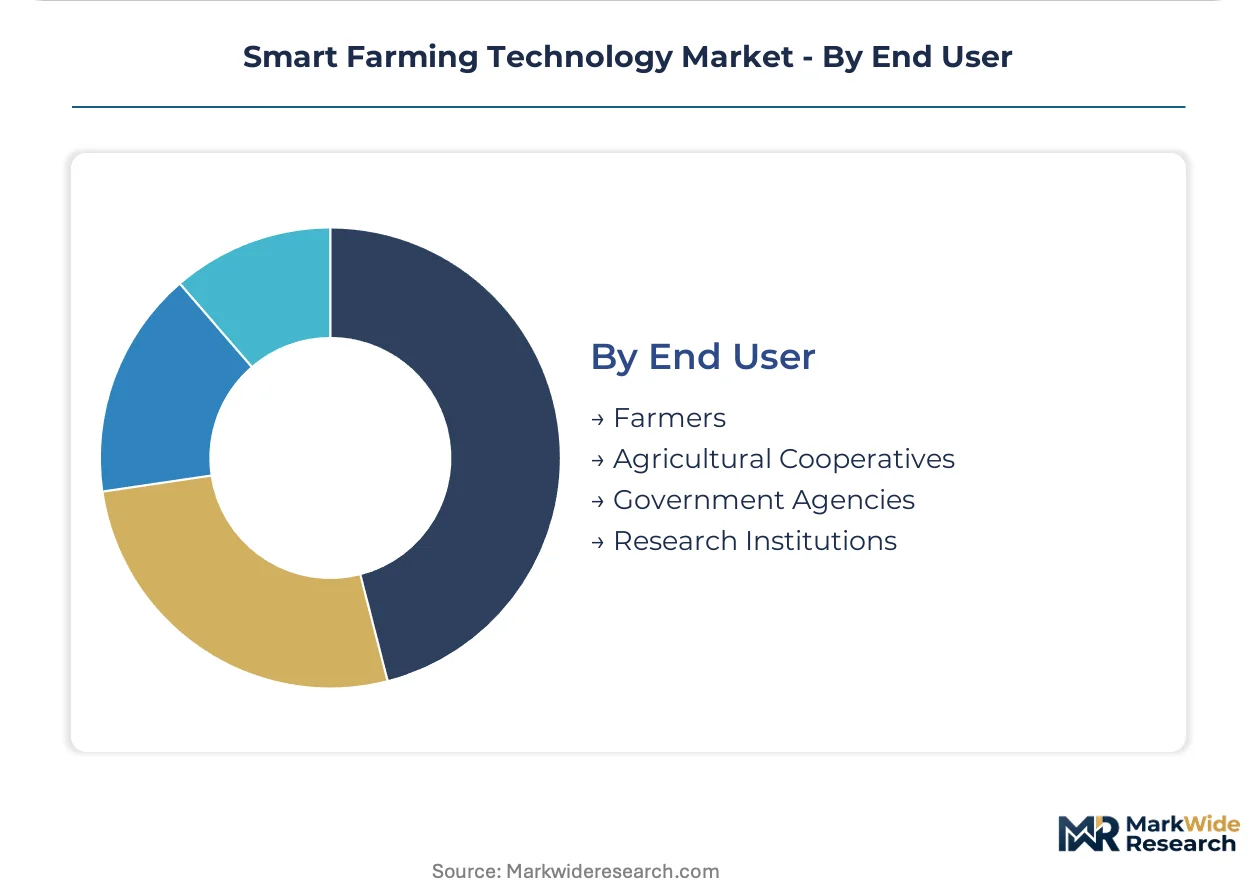
End User:
Customer type determines procurement complexity, with consolidated buyers extracting volume discounts unavailable to fragmented purchasers.
- Farmers:Individual operators in the US Corn Belt prioritize GNSS-guided steering to reduce fertilizer overlap. Capital constraints delay adoption among smallholders outside subsidized equipment programs.
- Agricultural Cooperatives:Consolidated buying power across member farms enables shared telemetry infrastructure. India's PLI scheme for precision agriculture equipment targets cooperative procurement structures.
- Government Agencies:Extension services deploy demonstration fleets to accelerate technology transfer.
- Research Institutions:University field stations validate algorithm performance across diverse agronomic conditions.
Farmers represent the dominant demand source while agricultural cooperatives show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for precision agriculture equipment tilt toward net importing in emerging agricultural economies while established manufacturing bases in Germany and the United States supply high-tier autonomy stacks to overseas markets. Trade flows concentrate around integrated steering systems and sensor modules rather than commodity machinery.
United States
US Corn Belt operators deploy GNSS-guided variable-rate applicators to meet USDA NRCS nutrient management cost-share thresholds. EPA Part 107 waivers constrain beyond-visual-line-of-sight drone spraying, compressing seasonal deployment windows for aerial platforms. California's Central Valley anchors demand for soil moisture sensor networks as water scarcity intensifies automated irrigation adoption.
Germany
German equipment manufacturers embed explainability logging in autonomous steering algorithms to satisfy EU AI Act conformity assessments for public road operation. F-Gas Regulation emissions constraints accelerate replacement cycles for diesel-powered fleets with electric platforms. Bavaria's agricultural machinery cluster faces six-to-twelve-month certification delays that postpone North American product launches.
Netherlands
Dutch dairy operations generate underpenetrated demand for recurring livestock health analytics subscriptions. EU Green Deal sustainability mandates tighten nitrogen emission standards for intensive livestock facilities. Wageningen University's research corridor validates algorithm performance across diverse agronomic conditions for export-oriented precision agriculture systems.
India
India's PLI scheme for precision agriculture equipment creates localized assembly opportunities for sensor-integrated machinery serving smallholder cooperatives. The country's national agricultural regulator shapes import certification requirements for foreign autonomous platforms. Maharashtra and Gujarat's cooperative procurement structures concentrate shared telemetry infrastructure investments among consolidated buyers.
Brazil
Brazilian large-scale soybean and sugarcane operators import North American and European autonomy stacks for retrofit onto existing fleet equipment. ANVISA regulates agricultural drone chemical application thresholds alongside national aviation authority waivers. São Paulo state's mechanized farming belt drives replacement demand for precision planting systems amid currency-driven import cost volatility.
Smart Farming Technology Market Competitive Landscape
Concentration sits with diversified agricultural machinery conglomerates that control proprietary CAN bus protocols and integrated autonomy stacks. The vendor base spans three distinct tiers: full-line OEMs with captive software platforms, specialized GNSS and guidance technology providers, and emerging drone-centric imaging specialists. Strategic moves center on open-platform architecture licensing to third-party developers and backward integration into edge-computing semiconductor sourcing.
Within the full-line OEM tier, Deere & Company and AGCO Corporation exemplify divergent platform strategies. Deere's integrated autonomy stack represents closed-system dominance in North American row-crop automation. AGCO's FendtONE architecture occupies a position as the primary open-platform alternative, extending third-party developer access across equipment lines. Trimble Inc. anchors the specialized guidance tier, supplying GNSS-directed steering systems for mixed-fleet operations where proprietary OEM protocols create retrofit barriers.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| Topcon Corporation |
| CNH Industrial N.V. |
| Raven Industries |
| Kubota Corporation |
| DeLaval |
| DJI |
| Others |
Pricing and Supply Chain Analysis
EU AI Act conformity assessments gate both supplier qualification timelines and price differentiation across autonomous steering tiers. Certification cycles compress margins on European-developed platforms while extending premium positioning for compliant architectures in North American markets.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in precision agriculture equipment. Price differentiation rests on ISO 11783 compliance certification and GNSS accuracy grade, with sub-inch systems commanding substantial premiums over decimeter-tier alternatives. Cost compression in economy-tier sensor modules intensifies as Taiwanese foundry output expands. Smallholder cooperatives in South Asia exhibit highest price sensitivity, while California Central Valley vegetable operations prioritize performance over unit cost.
Supply Chain Analysis
Port congestion on transpacific lanes elevates inbound logistics costs for semiconductor modules bound from East Asian foundries. Geographic supply concentration centers on Taiwan, South Korea, and China for edge-computing chips, with Germany and the United States contributing precision GNSS components. Raw material dependencies include silicon wafers, rare-earth magnets for drone motors, and lithium cells for autonomous platform power systems. Single-source vulnerability in advanced node fabrication creates supply chain risk. Distribution runs through agricultural equipment dealer networks with captive service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart farming technology market enters a cyclical recovery phase as EU Green Deal replacement cycles for diesel-powered fleets accelerate equipment refresh demand.
For Market Incumbents: Compound platform stickiness through backward integration into edge-computing semiconductor sourcing. Expand FendtONE-style open-architecture licensing to neutralize proprietary CAN bus protocol threats from closed-system rivals. Prioritize ISO 11783 certification investment to accelerate third-party developer onboarding. For New Entrants and Emerging Players: Anchor in livestock health analytics subscriptions for Dutch and Danish dairy operations, the most penetrable white-space segment. Target India's PLI scheme localized assembly opportunities for sensor-integrated machinery serving Maharashtra and Gujarat cooperatives. Pursue usage-based pricing go-to-market angles that unbundle hardware from algorithm access. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward explainability-logging capabilities in autonomous steering. Five-to-ten-year viability favors targets with hybrid-electric platform portfolios aligned with F-Gas Regulation trajectories. Watch EPA Part 107 waiver processing velocity as inflection indicator for aerial platform deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Platform Architecture Licensing | FendtONE-style third-party access expands addressable mixed-fleet retrofit market. |
| Backward Integration into Edge Silicon | Captive semiconductor sourcing insulates against Taiwan foundry concentration risk. |
| Livestock Health Analytics Subscription Launch | Recurring software margins exceed crop monitoring hardware economics in Netherlands. |
| EU AI Act Conformity Pre-Certification | Explainability logging investment accelerates North American product launch timelines. |
| PLI Scheme Localized Assembly Partnership | India cooperative procurement structures enable smallholder market penetration. |
Research Methodology
Cross-validation between equipment manufacturer technical documentation and regulatory filing databases anchors the qualitative findings. Primary interviews with precision agriculture R&D directors, agricultural cooperative procurement managers, dealer network service heads, and USDA extension specialists combine with secondary validation through EPA Part 107 waiver records, EU notified body conformity assessments, SEC equipment manufacturer filings, and customs trade data for sensor module imports. Bottom-up installed base estimates triangulate against top-down addressable acreage projections.
Sensitivity analysis frameworks stress-test projections across the analysis window against variable-rate technology adoption curves and livestock subscription renewal assumptions. Segmentation dimensions modeled include product type tier, technology deployment cost structure, application crop versus livestock split, and end-user consolidation level. CAGRs derive from equipment replacement cycle analysis and software subscription expansion trajectories. Forecast inputs incorporate EU F-Gas Regulation phase-out schedules and California Central Valley water scarcity policy intensity.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable transpacific logistics capacity; material deviation would warrant model refresh. Forecasts reflect assumptions around GNSS accuracy standardization and cellular latency improvement in rural broadband deployment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Smart Irrigation Controllers Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
US Smart Agriculture Market