
 Qatar Agriculture Market | 2026-2036
Qatar Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Agriculture Market Outlook
Hotel and restaurant procurement is broadening as Qatar's hospitality sector rebuilds capacity ahead of major sporting and cultural events. Baladna leverages its integrated dairy and fresh produce operations to supply institutional buyers directly. Hassad Food anchors strategic grain reserves and livestock import channels that buffer domestic supply volatility. AGRICO Agriculture Development Co. specializes in greenhouse vegetable production using Dutch hydroponic systems.
Qatar agriculture encompasses crop cultivation, animal husbandry, and aquaculture within an arid climate where average annual rainfall falls below 80 millimetres and summer temperatures exceed 45 degrees Celsius, requiring intensive irrigation, climate-controlled greenhouses, and desalinated water infrastructure to achieve commercial yields. The sector serves domestic food security priorities, hospitality procurement, and limited premium export to Gulf neighbours. Vegetables lead volume output from hydroponic facilities, while precision agriculture represents the fastest-growing technology segment as sensor networks and automated nutrient dosing reduce water consumption per kilogram of yield. Livestock retains margin concentration in dairy and poultry, where cold-chain infrastructure and shelf-stable distribution create defensive profit pools.
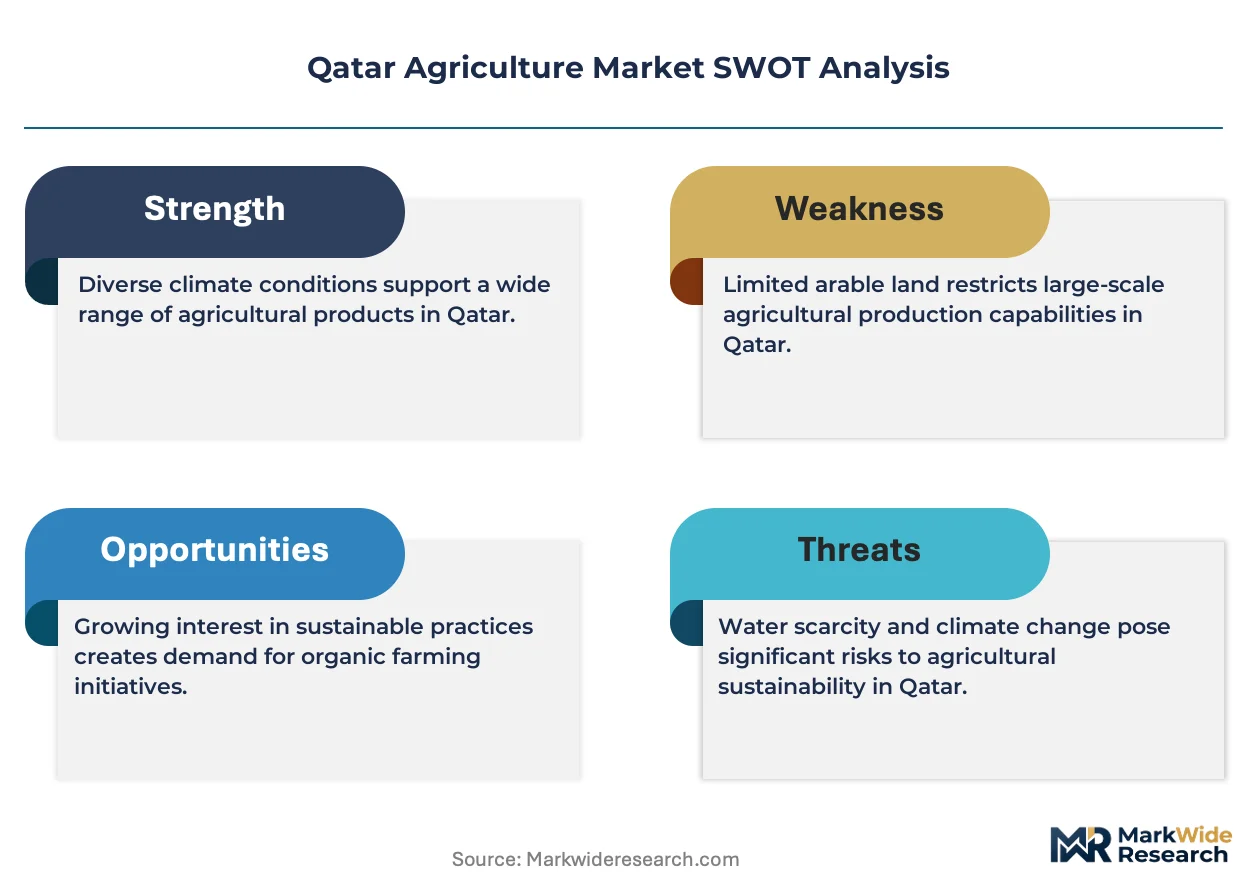
The Ministry of Municipality and Environment enforces land-use allocations and water tariffs that determine farm gate economics, while the Qatar General Organization for Standard and Metrology (QS) certifies organic and halal product claims for retail access. The Qatar National Food Security Programme channels capital subsidies toward hydroponic and aeroponic expansion, reshaping where producers locate and which technologies achieve scale. Stakeholders must monitor desalination energy costs and groundwater withdrawal limits as these variables determine which production models sustain profitability through the forecast horizon.
Market Dynamics
Desalinated water tariffs and controlled-environment technology subsidies are compressing farm gate economics while concentrating production in peri-urban greenhouse corridors around Doha. The Qatar National Food Security Programme redirects capital toward hydroponic and aeroponic systems, fundamentally restructuring where commercial agriculture achieves viability.
Growth Catalysts
- Controlled-environment agriculture subsidies:The Qatar National Food Security Programme channels capital toward hydroponic and aeroponic expansion, lowering entry barriers for commercial greenhouse operators.
- Hospitality procurement mandates:Hotels and catering services are expanding direct sourcing from domestic producers ahead of major sporting and cultural events.
- Baladna:The integrated dairy and fresh produce operator supplies institutional buyers directly, demonstrating viable backward integration into primary production.
Market Restraints
- Desalination energy costs:Thermal and reverse osmosis desalination consumes 13-15% of Qatar's electricity generation, exposing growers to tariff volatility that erodes margins.
- Groundwater depletion:The Ministry of Municipality and Environment enforces withdrawal limits that cap traditional irrigation-dependent farming.
- Import dependency for feed grains:Hassad Food anchors strategic reserves, but livestock producers remain exposed to global grain price shocks and shipping disruptions.
Strategic Opportunities
- Precision agriculture convergence:Sensor networks and automated nutrient dosing are reducing water consumption per kilogram of yield, opening margin expansion for early adopters.
- Halal certification premium channels:The Qatar General Organization for Standard and Metrology certifies organic and halal claims, unlocking retail access with pricing power.
- Peri-urban greenhouse corridors:Doha's surrounding districts offer logistics proximity to institutional buyers while land-use allocations favor agricultural zoning.
Industry Challenges
- Hydroponic system integration:Dutch hydroponic technology deployment at AGRICO Agriculture Development Co. requires specialized agronomy expertise that remains scarce in domestic labor markets.
- Cold-chain capex intensity:Dairy and poultry margin defense demands continuous investment in refrigerated transport and shelf-stable distribution infrastructure.
- Organic certification timelines:QS organic verification processes extend product launch schedules, compressing first-mover advantage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Agriculture Market |
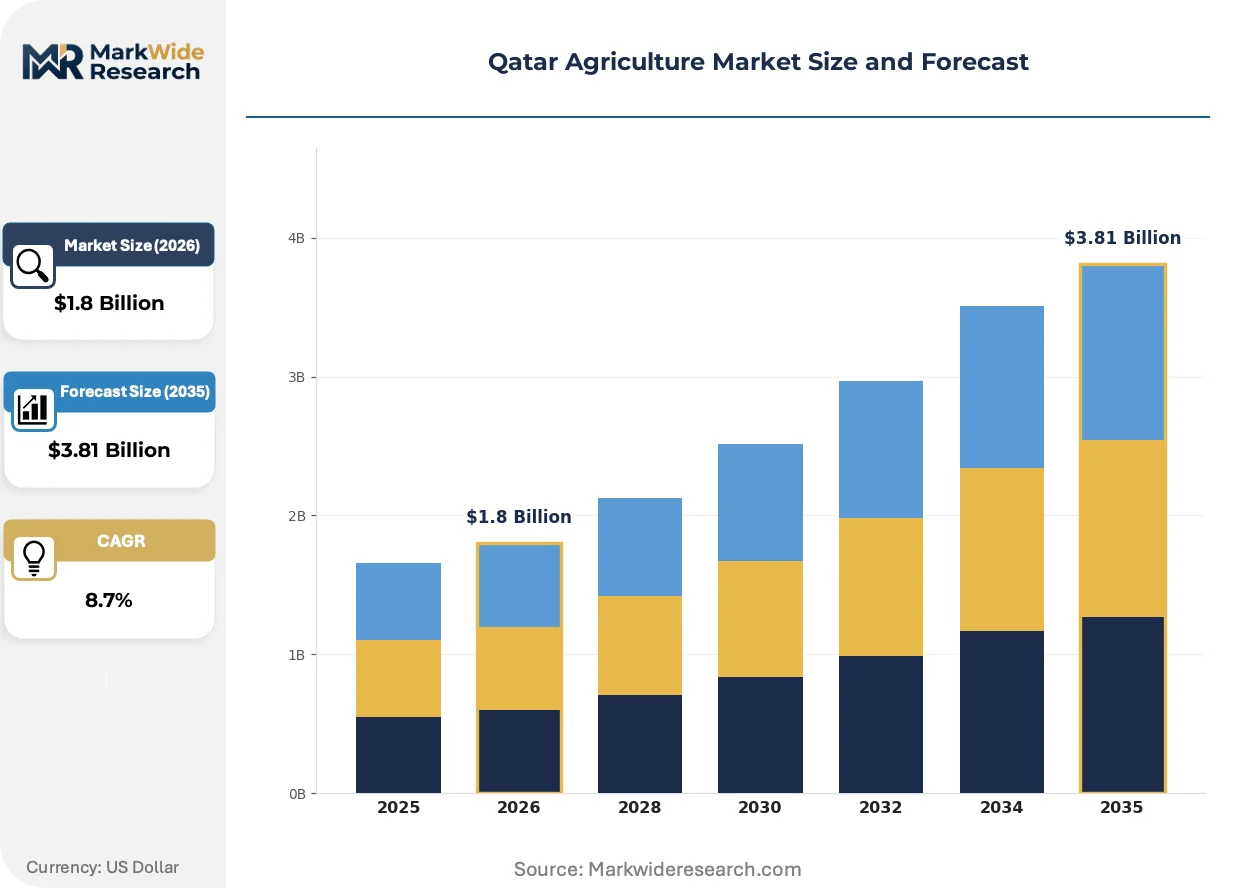
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Livestock End Use Industry: Food Processing, Retail, Export, Restaurants Technology: Hydroponics, Aeroponics, Organic Farming, Precision Agriculture Distribution Channel: Direct Sales, Wholesale, Online, Supermarkets |
| Companies Covered | AGRICO Agriculture Development Co., Al Dahra Holding Company, Baladna, Almarai Company, Agthia Group, Hassad Food, QADCO - Qatar Agricultural Development Company, National Agricultural Development Company (NADEC), Mazzraty W.L.L., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Agriculture Market Strategic Shifts
Automation and climate control technologies are compressing operational cost structures while regulatory pressure on water consumption accelerates technology substitution. The sector is pivoting from volume expansion toward yield efficiency and quality differentiation.
Automated nutrient dosing systems are consolidating control over greenhouse operations by replacing manual irrigation management with sensor-driven precision. Commercial vegetable producers are adopting these systems at accelerating pace to meet Ministry of Municipality and Environment water tariff structures. The technology is consolidating smaller, labor-intensive operations into technology-intensive facilities that achieve compliance at scale.
The Qatar National Food Security Programme channels capital subsidies toward hydroponic and aeroponic expansion, reshaping producer location decisions and technology adoption thresholds. Commercial operators must now demonstrate water efficiency metrics to access preferential land-use allocations. Vegetable producers in Doha's peri-urban corridors are responding by retrofitting existing greenhouse infrastructure with closed-loop irrigation systems.
Direct contracting between growers and hospitality groups is displacing traditional wholesale distribution channels for premium produce categories. Hotel procurement teams are establishing multi-year supply agreements with greenhouse operators, bypassing central markets. This pattern concentrates in Doha's luxury hospitality cluster, where traceability requirements and event-driven volume spikes favor captive supply relationships.
Qatar Agriculture Market Segmentation
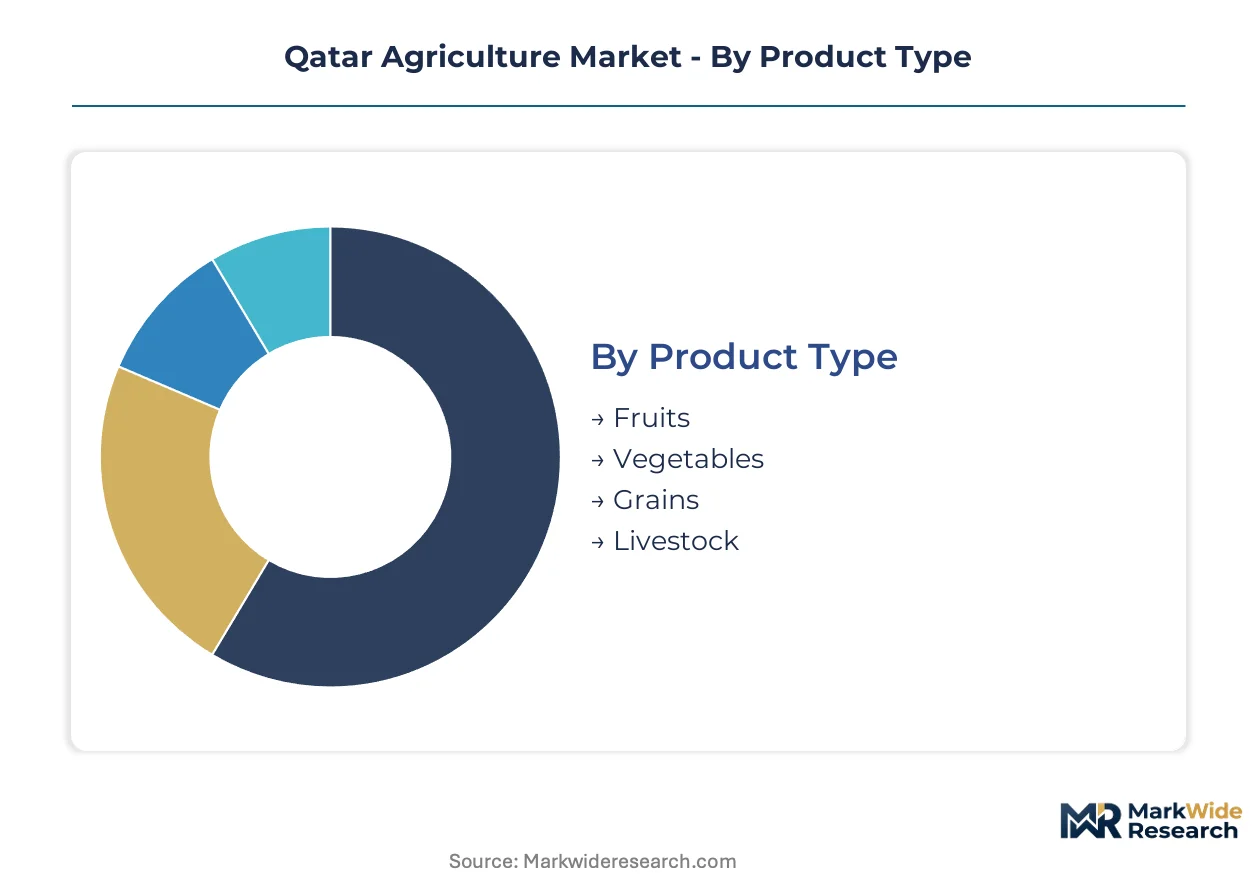
Qatar's agriculture market segments reflect competing imperatives between water efficiency mandates and hospitality-driven quality premiums. The Ministry of Municipality and Environment's tariff structures and the Qatar National Food Security Programme's subsidy channels reshape which product categories and technologies achieve commercial scale.
Product Type:
Vegetables dominate volume throughput from hydroponic facilities, while livestock commands premium pricing through cold-chain infrastructure investment.
- Vegetables:Tomatoes, cucumbers, and leafy greens constitute the primary output from Dutch-designed hydroponic systems deployed across Doha's peri-urban greenhouse corridors. Hotel procurement teams source these directly for traceability compliance ahead of major events, bypassing wholesale markets entirely.
- Livestock:Dairy and poultry operations concentrate margin defense through Baladna's integrated model, where captive cold-chain distribution locks in institutional contracts. Desalinated water costs and imported feed grain exposure compress returns for smaller operators outside this structure.
- Fruits:Date palms and limited citrus cultivation serve domestic consumption and premium Gulf export channels.
- Grains:Barley and fodder crops occupy marginal acreage; Hassad Food anchors strategic import reserves rather than domestic cultivation.
Mature deployment sits with vegetables. Newer deployment is concentrated in livestock integration models.
End Use Industry:
Procurement concentration tracks Qatar's hospitality rebuild and food security sovereignty targets.
- Restaurants:Direct contracting from Doha's luxury hotel cluster drives volume for traceable, halal-certified produce. Procurement mandates ahead of sporting events accelerate this channel's expansion.
- Retail:Supermarkets and organic specialty stores access QS-certified products through consolidated distribution networks.
- Food Processing:Limited domestic processing capacity concentrates on dairy pasteurization and poultry slaughtering.
- Export:Premium dates and select vegetables reach Saudi Arabia and UAE markets through established Gulf trade corridors.
Volume concentrates in restaurant procurement. Margin expansion is accelerating fastest in retail certification premiums.
Technology:
Water efficiency metrics determine subsidy access and land-use allocation under Ministry of Municipality and Environment frameworks.
- Hydroponics:Closed-loop irrigation systems dominate commercial vegetable production, achieving compliance with water tariff structures that penalize open-field cultivation. AGRICO Agriculture Development Co. deploys Dutch system architecture requiring specialized agronomy expertise.
- Precision Agriculture:Sensor networks and automated nutrient dosing reduce consumption per kilogram of yield, opening margin expansion for technology-intensive operators. The Qatar National Food Security Programme channels capital subsidies toward these deployments.
- Aeroponics:Experimental deployments target leafy green categories with extreme water efficiency requirements.
- Organic Farming:QS certification timelines extend product launch schedules, compressing first-mover windows for certified operators.
Subsidized deployment concentrates in hydroponics. Steepest expansion trajectory belongs to precision agriculture sensor integration.
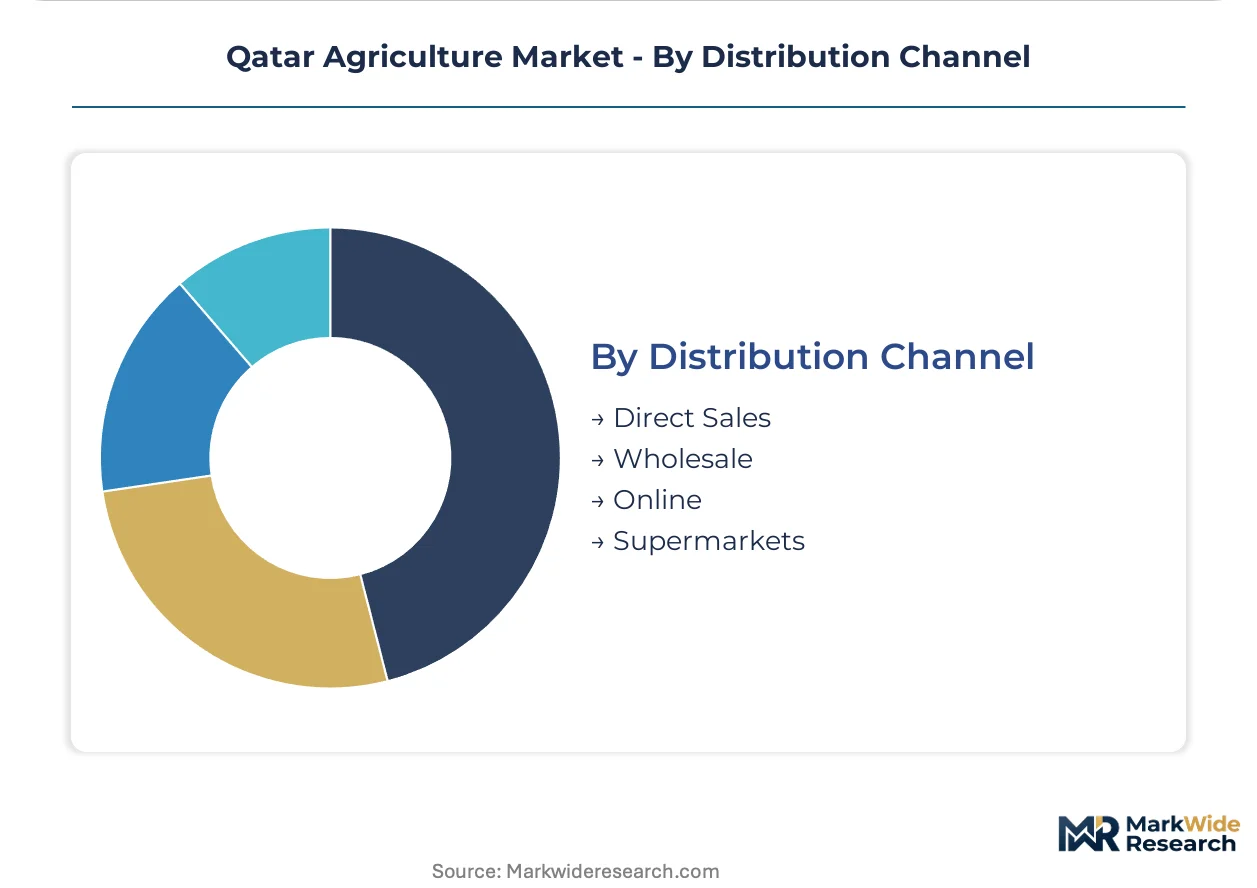
Distribution Channel:
Channel structure bifurcates between institutional direct sourcing and fragmented retail access.
- Direct Sales:Multi-year supply agreements between greenhouse operators and hotel procurement teams displace traditional wholesale relationships. Traceability requirements and event-driven volume spikes favor captive supply structures.
- Wholesale:Central markets serve smaller retail and restaurant accounts outside luxury hospitality clusters.
- Supermarkets:Consolidated retail chains access QS-certified organic and halal products through regulated distribution networks.
- Online:Emerging platforms target household consumers with subscription produce boxes and direct farm-to-door logistics.
Established volume flows through wholesale. Channel investment is concentrating in direct sales institutional contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ras Bufontas Economic Zone and Logistics Park concentrates greenhouse infrastructure investment through land-use allocations and subsidized utility tariffs. Qatar National Food Security Programme capital subsidies flow disproportionately to peri-urban districts within this zone. Doha's surrounding municipalities anchor commercial production clusters.
Al Rayyan Municipality
Baladna operates integrated dairy and fresh produce facilities serving institutional procurement channels. The Ministry of Municipality and Environment enforces water tariff structures that favor closed-loop hydroponic systems over open-field cultivation. Umm Salal Mohammed hosts the largest concentration of Dutch-designed greenhouse complexes supplying hotel and restaurant buyers directly.
Al Khor and Al Thakhira
Hassad Food anchors strategic grain reserves and livestock import channels buffering domestic supply volatility. The Qatar National Food Security Programme channels capital toward hydroponic expansion in this northern corridor. Al Thakhira's coastal location supports aquaculture development targeting hospitality procurement mandates.
Al Wakrah
AGRICO Agriculture Development Co. deploys precision agriculture infrastructure across peri-urban greenhouse facilities. The Ministry of Municipality and Environment's land-use allocations prioritize agricultural zoning in districts adjacent to Hamad International Airport logistics corridors. Mesaieed's industrial zone proximity enables cold-chain integration for poultry and dairy distribution.
Umm Salal
QADCO operates diversified crop cultivation targeting retail certification premiums through QS organic and halal verification. Groundwater withdrawal limits enforced by the Ministry of Municipality and Environment cap traditional irrigation-dependent farming. Umm Salal Ali concentrates experimental aeroponic deployments for leafy green categories with extreme water efficiency requirements.
Al Daayen
Al Dahra Holding Company leverages import logistics infrastructure for feed grain distribution to livestock operators. The Qatar General Organization for Standard and Metrology certifies product claims determining retail access eligibility. Lusail's planned city development incorporates designated agricultural zones for urban farming pilot programs.
Qatar Agriculture Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated operators capturing institutional procurement relationships while technology licensors supply equipment and agronomy expertise. The market exhibits tiered concentration: Baladna and Hassad Food anchor capital-intensive livestock and grain reserve operations, AGRICO and QADCO represent greenhouse technology specialists, and Al Dahra occupies import-logistics intermediation. Strategic moves concentrate on backward integration into primary production and direct contracting with hospitality buyers displacing wholesale channels.
Within the integrated livestock tier, Baladna and Hassad Food exemplify capital deployment models that combine captive production with cold-chain distribution infrastructure. AGRICO Agriculture Development Co. occupies the precision agriculture specialist position, representing technology-intensive greenhouse operations that reduce water consumption per kilogram of yield through sensor networks and automated systems. These three entities anchor distinct competitive vectors: Baladna demonstrates viable backward integration into dairy and fresh produce, Hassad Food secures supply chain resilience through strategic reserves, and AGRICO channels Dutch hydroponic expertise into commercial vegetable production.
| Leading Market Players |
|---|
| AGRICO Agriculture Development Co. |
| Al Dahra Holding Company |
| Baladna |
| Almarai Company |
| Agthia Group |
| Hassad Food |
| QADCO - Qatar Agricultural Development Company |
| National Agricultural Development Company (NADEC) |
| Mazzraty W.L.L. |
| Others |
Value Chain & Pricing Dynamics
Dutch hydroponic system specialists concentrated in Doha's peri-urban corridors command wage premiums that compress pricing spreads between technology-intensive greenhouse tiers and labor-dependent open-field operations. The Ministry of Municipality and Environment's water tariff structures amplify these differentials, pushing procurement decisions toward certified hydroponic suppliers despite higher base rates.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as hotel procurement teams pay above-spot rates for harvest-to-delivery cycles under 48 hours. Three-tier pricing structure across premium, standard, and economy levels separates QS-certified organic produce from conventional hydroponic output and import-reliant wholesale categories. Pricing pressure stems from desalination energy cost volatility that erodes margins for operators without solar co-generation. Food processing buyers exhibit highest price sensitivity due to thin conversion margins, while luxury hospitality segments absorb premiums for traceability compliance.
Supply Chain Analysis
Refrigerated freight costs from Doha's peri-urban greenhouse corridors to Hamad International Airport logistics hubs anchor distribution economics for export-bound produce. Supply concentration rests on the Netherlands for hydroponic system components, Saudi Arabia for feed grain transshipment, and Oman for live cattle imports. Single-source vulnerability runs through Dutch equipment licensors whose agronomy expertise remains scarce in domestic labor markets. Distribution runs through direct sales agreements with institutional buyers that displace traditional wholesale channels for premium categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar agriculture functions as a vertical-integration race where captive cold-chain infrastructure determines who captures hospitality procurement mandates. Players are pursuing backward integration into desalinated water co-generation to lock in energy cost predictability.
For Market Incumbents: Lock in multi-year supply agreements with Doha's luxury hotel cluster before event-driven volume spikes concentrate buyer power. Invest in QS halal certification infrastructure to defend margin position against emerging greenhouse operators importing Dutch technical expertise. Priority defensive moves center on securing peri-urban land-use allocations under Ministry of Municipality and Environment frameworks that cap competitor expansion.
For New Entrants and Emerging Players: Begin with precision agriculture sensor integration targeting water efficiency metrics that unlock Qatar National Food Security Programme capital subsidies. White-space opportunity concentrates in aeroponic leafy green production for retail certification premiums where QS organic verification timelines have stalled incumbent product launches. Go-to-market angle should emphasize direct online subscription channels bypassing consolidated supermarket distribution.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated livestock operators given captive cold-chain infrastructure scarcity and Baladna's demonstrated backward integration model. Long-term viability favors entities controlling both primary production and institutional distribution relationships. Signal to watch is Ministry of Municipality and Environment groundwater withdrawal limit enforcement that could accelerate technology substitution and consolidate share toward capital-intensive operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Desalinated Water Co-generation | Solar-powered desalination assets hedge against Ministry of Municipality and Environment tariff volatility eroding greenhouse margins. |
| QS Halal Certification Investment | Qatar General Organization for Standard and Metrology verification unlocks retail access with pricing power in consolidated supermarket channels. |
| Direct Hospitality Procurement Contracts | Multi-year agreements with Doha's luxury hotel cluster displace wholesale intermediation and capture event-driven volume spikes. |
| Precision Agriculture Sensor Deployment | Automated nutrient dosing systems reduce water consumption per kilogram of yield to meet Qatar National Food Security Programme efficiency thresholds. |
| Peri-Urban Land-Use Allocation Securement | Ministry of Municipality and Environment agricultural zoning approvals in Ras Bufontas Economic Zone concentrate logistics proximity to institutional buyers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with greenhouse operations managers, hotel procurement directors, Ministry of Municipality and Environment land-use officials, and Qatar General Organization for Standard and Metrology certification auditors combined with secondary validation from Qatar National Food Security Programme subsidy disclosures, desalination utility tariff schedules, and Hassad Food strategic reserve reports. Bottom-up facility capacity modeling and top-down agricultural output triangulation reconciled volume estimates.
Production volume, technology adoption rates, and end-use procurement patterns were reconciled across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, technology platform, and distribution channel structure. CAGRs were derived from facility-level capacity buildout schedules and subsidy disbursement trajectories. Forecast inputs incorporated desalination energy cost scenarios and groundwater withdrawal limit enforcement timelines.
Underlying measurement precision varies by segment; hydroponic vegetable output carries tighter precision than experimental aeroponic deployments given established reporting frameworks. Forecasts reflect assumptions regarding Qatar National Food Security Programme capital allocation continuity and Ministry of Municipality and Environment regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Farming Market