
 Smart Cattle Market | 2026-2036
Smart Cattle Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Cattle Market Analytics
Commercial dairy operations is consolidating its share of total smart cattle technology procurement as margins tighten and scale advantages intensify. DeLaval leverages its integrated milking and herd management ecosystem to anchor premium positioning across Northern European and North American installations. GEA Farm Technologies sustains competitive pressure through specialized automation engineering for rotary parlors and feeding systems. Nedap N.V. differentiates via precision livestock monitoring hardware that controls cow identification and estrus detection workflows.
Smart cattle systems encompass networked hardware and software platforms that capture biometric, behavioral, and environmental data from individual animals or herds, typically transmitting via low-power wireless protocols to centralized analytics dashboards for real-time decision support. IoT Devices and Wearable Technology dominate current installation volumes, though Drones are recording the fastest uptake trajectory as ranching operations adopt aerial thermal imaging for calving detection and pasture assessment. Software Platforms and Data Analytics capture disproportionate margin pools relative to hardware, reflecting recurring subscription economics and integration complexity that Farm Management Systems vendors exploit. Health Monitoring leads application penetration due to veterinary cost pressures, while Breeding Optimization offers the steepest growth curve as genomic data layers onto sensor-derived fertility signals.
USDA traceability rules and FDA veterinary feed directive frameworks shape product design requirements, compelling vendors to build audit-ready data architectures and prescription-aligned dosing controls into platform roadmaps. EPA nutrient management standards for concentrated animal feeding operations further mandate environmental sensor networks that integrate with manure handling infrastructure. Stakeholders must weigh regulatory compliance depth against modular interoperability as jurisdictions layer additional data sovereignty and animal welfare transparency obligations onto system specifications.
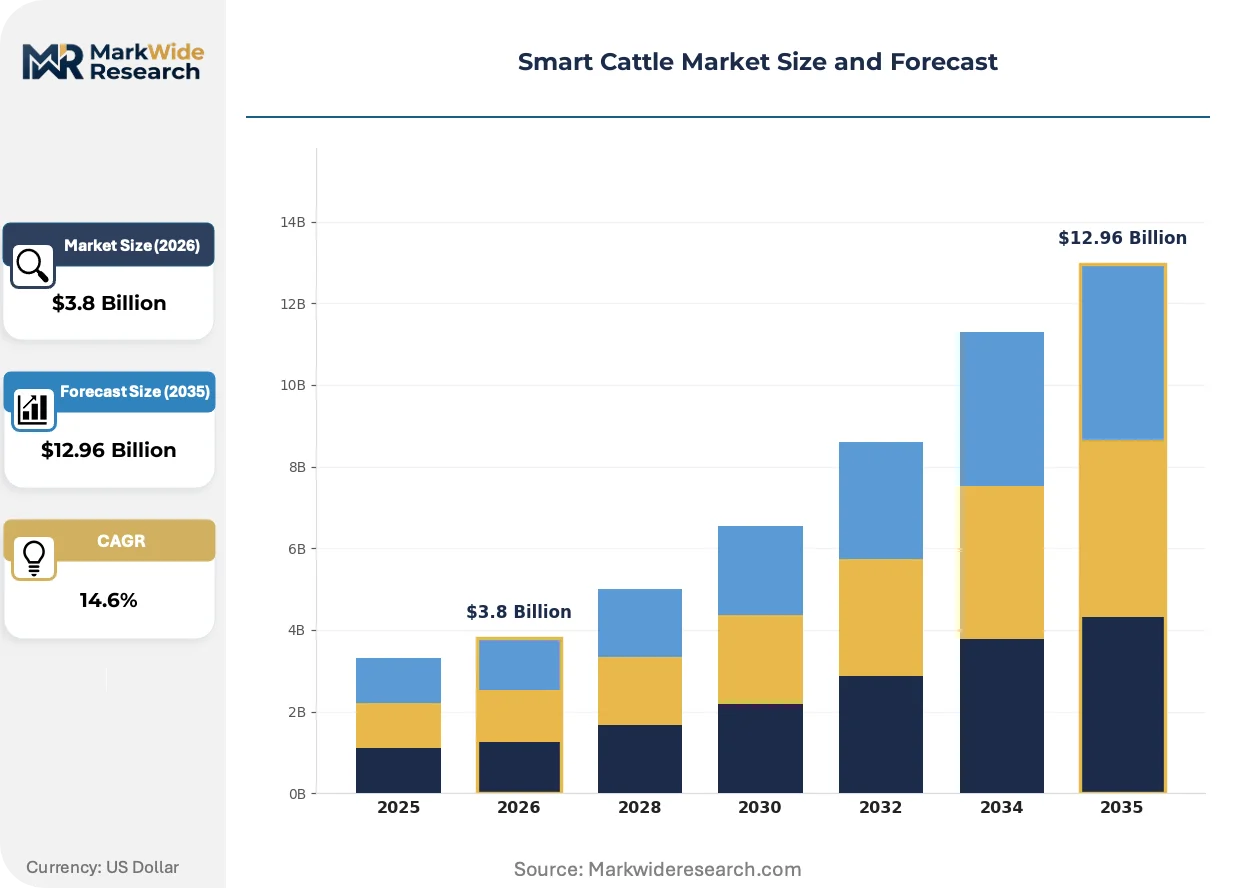
Market Dynamics
Large-scale feedlot operators and dairy cooperatives in the United States are consolidating procurement around integrated herd management platforms, compressing vendor margins while accelerating platform standardization across North American livestock operations.
Growth Catalysts
- USDA Animal Health Traceability Mandates:Federal requirements for electronic identification and movement tracking are compelling feedlot operators to deploy sensor networks that capture real-time location and health data for compliance reporting.
- EPA Manure Management Regulations:Concentrated animal feeding operations face nutrient discharge limits that require environmental sensor integration with manure handling infrastructure, driving automated monitoring system sales.
- Genomic Data Layering:Dairy cooperatives are combining sensor-derived fertility signals with genomic databases to optimize breeding decisions, creating demand for analytics platforms that merge biological and behavioral data streams.
Market Restraints
- Silicon Supply Concentration:Semiconductor fabrication for livestock wearables depends on concentrated Asian foundry capacity, exposing hardware vendors to input cost volatility and extended lead times for microcontrollers and wireless chipsets.
- Veterinary Prescription Alignment:FDA veterinary feed directive frameworks create compliance friction by requiring prescription-aligned dosing controls in automated feeding systems, adding software validation costs that slow deployment timelines.
- Low-Power Wireless Limitations:Bluetooth Low Energy and LoRaWAN protocols face range and interference constraints in dense feedlot environments, limiting real-time data transmission reliability for remote pasture monitoring applications.
Strategic Opportunities
- Brazilian Ranching Digitization:Underpenetrated pasture operations in Mato Grosso and Goiás states present white-space demand for drone-based thermal imaging systems that detect calving events and assess forage conditions across extensive grazing lands.
- Subscription Analytics Convergence:Farm management software vendors can capture recurring revenue by integrating predictive health algorithms with estrus detection hardware, shifting customer relationships from equipment sales to outcome-based service tiers.
- EU Green Deal Alignment:Methane emissions monitoring requirements under the EU's Farm to Fork Strategy create regulatory tailwinds for environmental sensor networks that quantify enteric fermentation and manure management impacts.
Industry Challenges
- Veterinary Data Science Talent Gap:Livestock operations lack personnel capable of interpreting sensor-derived biometric patterns and integrating them with clinical decision workflows, slowing technology adoption despite hardware availability.
- Legacy Herd Management Integration:Proprietary data formats from incumbent milking equipment manufacturers create interoperability friction, forcing new platform vendors to build expensive translation layers for customer retention.
- Wireless Certification Timelines:FCC and CE marking processes for novel wearable form factors extend product launch cycles by 8-14 months, compressing first-mover advantage windows in fast-evolving application categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Cattle Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, Sensors, Drones, Wearable Technology Application: Health Monitoring, Feeding Management, Breeding Optimization, Behavior Analysis End User: Dairy Farmers, Beef Producers, Livestock Traders, Research Institutions Solution: Software Platforms, Data Analytics, Farm Management Systems, Automation Tools |
| Companies Covered | DeLaval, GEA Farm Technologies, BouMatic, Lely, Afimilk Ltd., Merck & Co., Inc. (Allflex), SCR Dairy Ltd., Nedap N.V., Fullwood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Cattle Market Evolving Landscape
Sensor miniaturization and edge computing architectures are compressing the latency between data capture and actionable insight, enabling real-time intervention workflows that were previously constrained by cloud-dependent processing pipelines.
Machine learning inference at the edge is absorbing the computational burden previously routed to centralized servers, enabling collar-mounted devices to classify rumination patterns and detect lameness without continuous cellular connectivity. Dairy cooperatives in Wisconsin and California are deploying these systems at scale, reducing veterinary response times from days to hours. The shift is absorbing margin from traditional cloud analytics providers while creating captive hardware-software bundles that lock in multi-year service contracts.
REACH chemical restrictions and RoHS substance limitations are forcing hardware redesigns for European deployments, compelling wearable manufacturers to eliminate lead-based solders and restricted phthalates from housing materials. Industrial consequence includes accelerated obsolescence of existing inventory and supplier qualification costs for compliant component sourcing. Northern European dairy technology vendors are responding by vertically integrating injection molding capacity to control material certification documentation.
Large feedlot operators are unbundling after-sales service from equipment procurement, negotiating direct maintenance contracts with regional veterinary technology specialists rather than original manufacturers. This channel disintermediation is most visible in Texas and Kansas, where independent service providers capture 30-40% of installation and calibration revenue previously retained by DeLaval and GEA. Equipment vendors are responding by encrypting diagnostic protocols to preserve proprietary service access.
Smart Cattle Market Segmentation
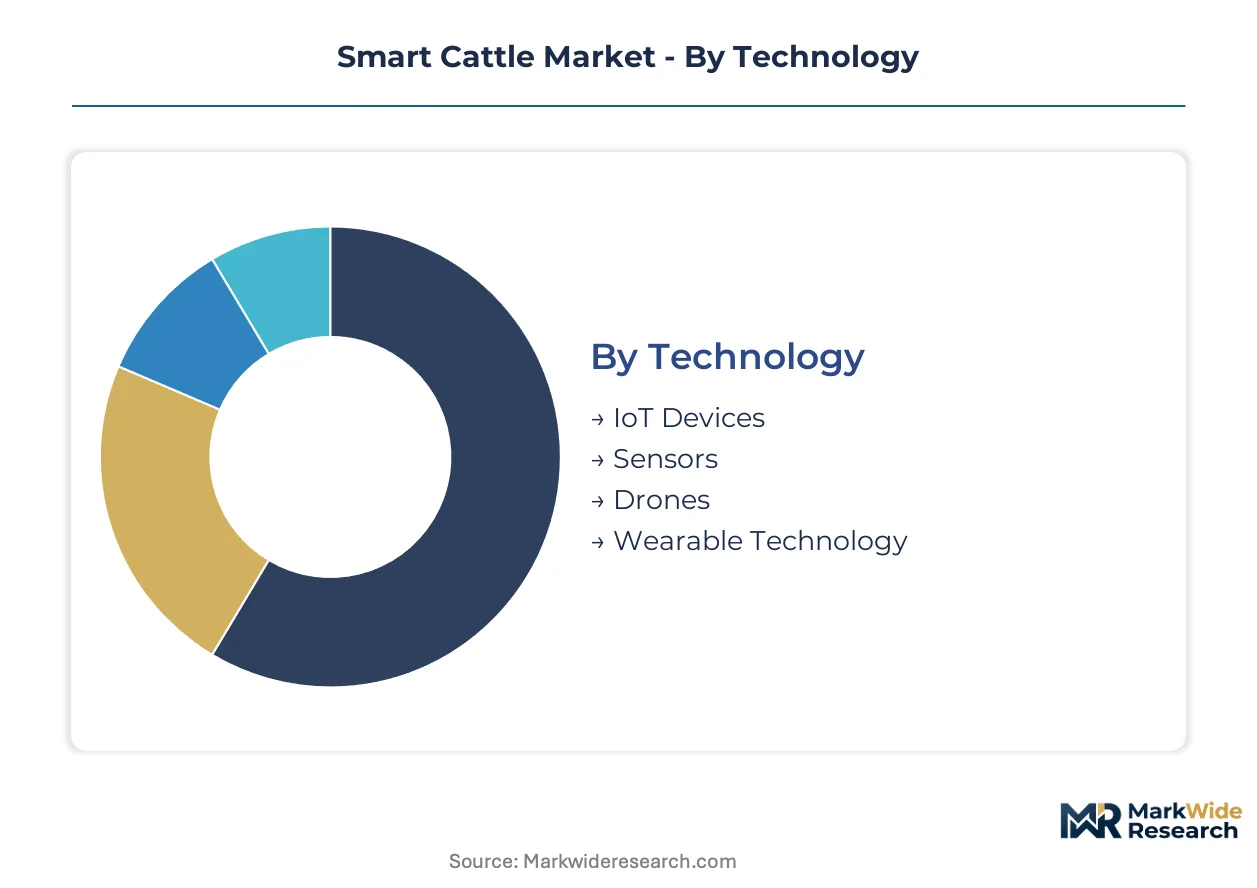
Technology procurement patterns in smart cattle operations diverge sharply by operational scale and regulatory exposure. Large feedlot operators prioritize integrated platforms that satisfy USDA traceability mandates, while pasture-based ranchers favor modular hardware with minimal infrastructure requirements.
Technology:
Capital intensity and connectivity infrastructure separate buyers in this dimension.
- IoT Devices:Networked environmental sensors capture temperature, humidity, and air quality metrics in barn and feedlot settings. Dairy cooperatives in the United States deploy these most densely to satisfy EPA nutrient management monitoring requirements for concentrated animal feeding operations.
- Wearable Technology:Collar-mounted and ear-tag form factors transmit biometric and behavioral data via low-power wireless protocols. Beef producers across Texas and Kansas favor these for estrus detection and calving alerts where labor scarcity drives automation urgency.
- Sensors:Fixed-position hardware monitors rumination, lameness, and feed intake at individual stall or bunk levels. Research institutions leverage high-fidelity sensor arrays for longitudinal studies on metabolic efficiency.
- Drones:Aerial platforms equipped with thermal imaging enable calving detection and pasture condition assessment across extensive grazing operations. Brazilian ranchers in Mato Grosso represent the steepest adoption trajectory as they digitize underpenetrated pasture management.
Volume sits with IoT Devices; growth tilts toward Drones.
Application:
Return-on-investment horizons and labor substitution potential shape deployment priorities.
- Health Monitoring:Continuous biometric tracking enables early disease detection and reduced veterinary intervention costs. Dairy farmers concentrate procurement here as mastitis and metabolic disorder prevention delivers immediate margin protection.
- Breeding Optimization:Sensor-derived fertility signals combined with genomic databases accelerate genetic gain and reproductive efficiency. Large-scale beef producers invest most aggressively where artificial insemination programs already dominate breeding strategy.
- Feeding Management:Automated ration delivery and intake monitoring optimize feed conversion ratios. Feedlot operators deploy these systems to align with FDA veterinary feed directive prescription controls.
- Behavior Analysis:Machine learning classifiers identify lameness, heat stress, and social hierarchy disruptions from movement patterns. Research institutions drive specialized demand for ethological study applications.
Revenue concentrates in Health Monitoring; Breeding Optimization climbs the fastest.
End User:
Procurement sophistication and platform integration requirements distinguish customer tiers.
- Dairy Farmers:Operations with 500+ head deploy integrated milking and herd management ecosystems. Northern European and North American installations lead in platform standardization.
- Beef Producers:Feedlot and cow-calf operations prioritize ruggedized hardware for harsh environmental conditions. Large-scale operators in the United States consolidate procurement around multi-year service contracts.
- Livestock Traders:Buyers focus on traceability and certification data to satisfy destination market requirements. Export-oriented operations invest most heavily in compliance-aligned sensor networks.
- Research Institutions:Universities and government agricultural stations demand open data architectures and publication-grade measurement precision. These users drive early adoption of experimental sensing modalities.
Volume aggregates with Dairy Farmers; expansion tilts toward Beef Producers.
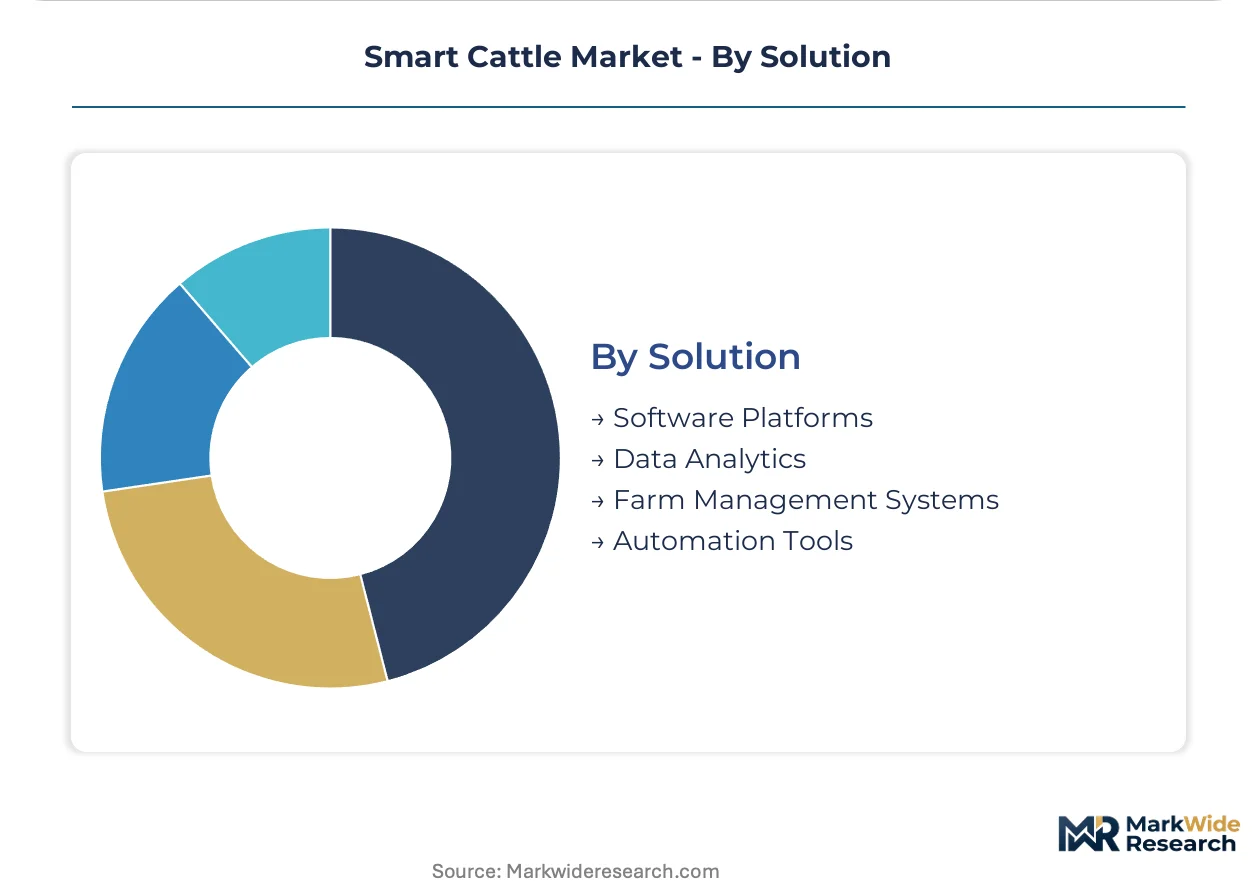
Solution:
Margin capture and customer lock-in dynamics separate software from hardware value pools.
- Software Platforms:Cloud-based dashboards aggregate multi-source data streams and enable remote management workflows. Recurring subscription economics attract venture investment and vendor consolidation activity.
- Data Analytics:Predictive algorithms for health, fertility, and productivity outcomes command premium pricing. Dairy cooperatives pay most for genomic integration layers that merge biological and sensor-derived signals.
- Farm Management Systems:Comprehensive platforms combine milking automation, feeding control, and herd records in unified architectures. Incumbent equipment manufacturers defend position through proprietary data formats.
- Automation Tools:Robotic milking, automated feeding, and sorting gate hardware reduce labor dependence. Capital constraints limit penetration among mid-scale operations despite demonstrated payback periods.
Revenue pools deepest in Software Platforms; Data Analytics gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of smart cattle technology concentrates in Northern Europe and North America, while consumption tilts toward large-scale dairy and beef operations in the United States, Brazil, and Australia. Manufacturing ecosystems in Sweden and the Netherlands supply integrated milking and monitoring hardware to export markets. Regulatory mandates in multiple jurisdictions are accelerating sensor deployment timelines.
United States
Large feedlot operators in Texas and Kansas consolidate procurement around multi-year service contracts for integrated herd management platforms. USDA animal health traceability mandates compel electronic identification and movement tracking infrastructure across concentrated animal feeding operations. Dairy cooperatives in Wisconsin deploy edge-computing collar systems to reduce veterinary response times for mastitis detection.
Brazil
Ranchers in Mato Grosso and Goiás states drive the steepest adoption trajectory for drone-based thermal imaging systems that detect calving events across extensive grazing lands. ANVISA regulatory frameworks for veterinary product traceability create compliance-aligned demand for sensor networks. Beef export operations invest heavily in certification data infrastructure to satisfy European Union destination market requirements.
Germany
Baden-Württemberg and Bavaria host precision engineering clusters that supply rotary parlor automation and feeding system hardware to global dairy markets. ECHA REACH chemical restrictions and RoHS substance limitations force hardware redesigns for compliant component sourcing. Equipment manufacturers in Lower Saxony respond by establishing in-house injection molding capacity to control material certification documentation.
Australia
Pastoral operations in Queensland and New South Wales favor modular hardware with minimal infrastructure requirements for remote cattle monitoring. The country's national agricultural regulator enforces livestock identification and traceability standards that drive ear-tag and collar deployments. Research institutions in Victoria deploy high-fidelity sensor arrays for longitudinal studies on metabolic efficiency in grazing systems.
Netherlands
Dairy technology vendors in the Eindhoven region anchor premium positioning through integrated milking and herd management ecosystems. EU Green Deal methane emissions monitoring requirements under the Farm to Fork Strategy create regulatory tailwinds for environmental sensor networks. Precision livestock monitoring specialists control cow identification and estrus detection workflows for Northern European installations.
Smart Cattle Market Competitive Landscape
Top-tier vendors anchor integrated platform ecosystems, while mid-tier specialists compete on modular hardware and regional service density. The vendor base separates into three distinct tiers: full-system integrators with captive software-hardware bundles, component specialists focused on sensor miniaturization, and regional service providers capturing aftermarket maintenance revenue. Two dominant competitive moves are reshaping positioning: incumbent equipment manufacturers encrypt diagnostic protocols to preserve proprietary service access, and farm management software vendors shift customer relationships from equipment sales to subscription-based outcome tiers.
Among Northern European integrated system providers, DeLaval and GEA Farm Technologies occupy positions that exemplify full-ecosystem anchoring, while Nedap N.V. sits within the precision monitoring hardware specialist tier. These three entities represent distinct strategic archetypes: the milking equipment incumbent defending through proprietary data formats, the automation engineering specialist sustaining pressure through rotary parlor expertise, and the precision hardware vendor differentiating via fertility signal detection workflows. Their collective positioning illustrates how competitive advantage in this market derives from either captive integration depth or specialized workflow control.
| Leading Market Players |
|---|
| DeLaval |
| GEA Farm Technologies |
| BouMatic |
| Lely |
| Afimilk Ltd. |
| Merck & Co., Inc. (Allflex) |
| SCR Dairy Ltd. |
| Nedap N.V. |
| Fullwood |
| Others |
Value Network & Pricing Analysis
Premium-mid-economy pricing differentiation across hardware tiers manifests simultaneously in subscription bundling strategies and semiconductor sourcing footprints. USDA traceability mandates compress margins on baseline sensor hardware while amplifying pricing power for integrated platforms that bundle compliance-ready data architectures with veterinary workflow tools.
Pricing Analysis
Short lead-time premiums command substantial markups as feedlot operators face compressed deployment windows tied to USDA electronic identification deadlines. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors from modular hardware suppliers and spot-market component distributors. Price differentiation hinges on FDA veterinary feed directive alignment and EPA nutrient management certification depth. Pricing pressure stems from silicon supply volatility in Asian foundries, with mid-scale dairy cooperatives exhibiting highest price sensitivity due to capital constraints.
Supply Chain Analysis
Semiconductor fabrication for livestock wearables rests on concentrated Taiwanese and South Korean foundry capacity, with microcontroller and wireless chipset supply anchored in mainland Chinese packaging facilities. Raw material dependencies span rare earth elements for magnetometers, lithium-polymer cells for collar power systems, and RoHS-compliant housing polymers. Single-source vulnerability concentrates in BLE chipset suppliers serving dense feedlot environments. Distribution runs through original equipment manufacturer direct sales for large feedlots and agricultural equipment dealers serving mid-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
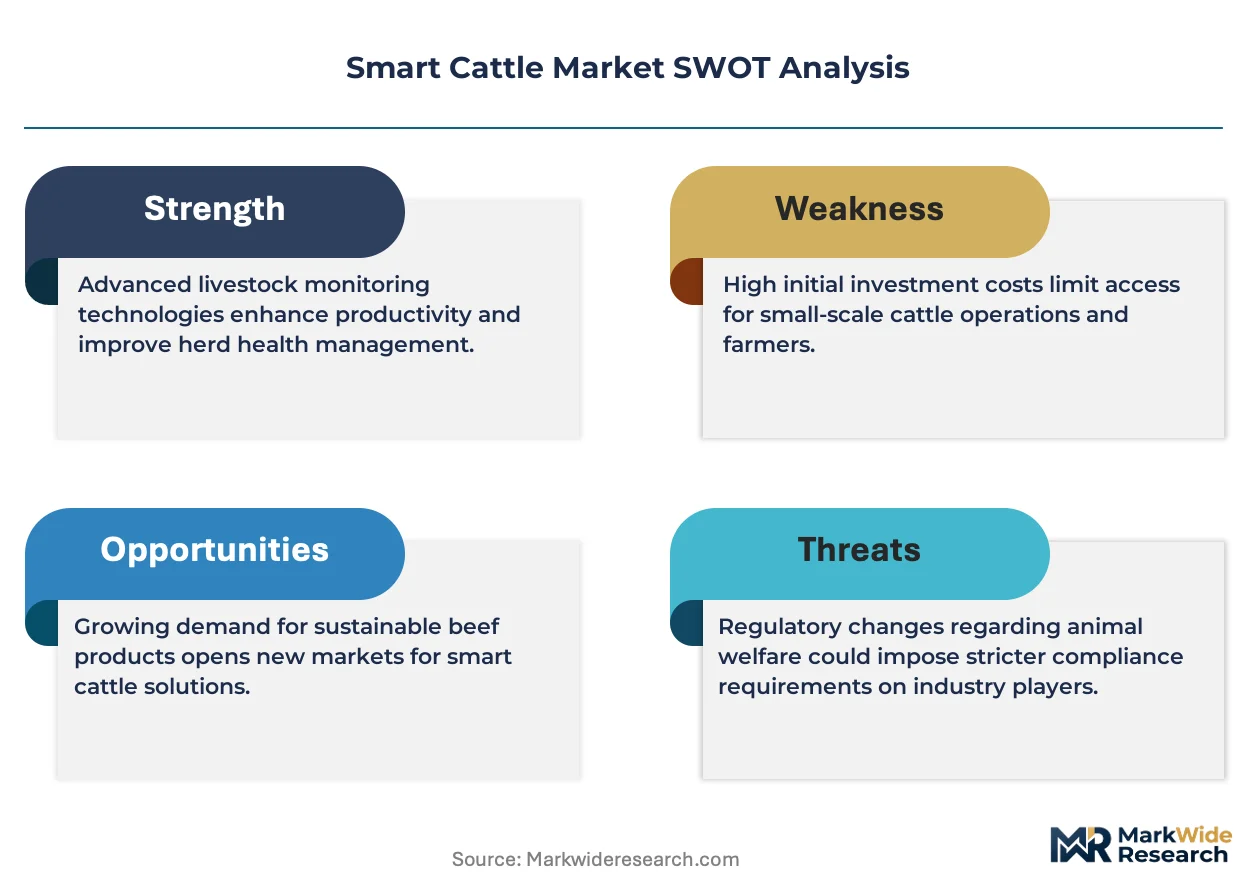
This market reads as a cost-of-compliance story where USDA animal health traceability mandates erect barrier-to-entry moats favoring vendors with pre-built audit-ready data architectures.
For Market Incumbents: Anchor platform positioning through encrypted diagnostic protocols that preserve proprietary service access against regional veterinary technology specialists. Deepen backward integration into injection molding capacity to control REACH and RoHS material certification documentation. Threat vectors include independent service providers capturing 30-40% of installation revenue in Texas and Kansas feedlot corridors. For New Entrants and Emerging Players: Regional veterinary technology specialists represent the most penetrable channel archetype for wedge strategies. White-space demand concentrates in Brazilian Mato Grosso pasture operations and Australian Queensland pastoral stations where drone-based thermal imaging remains underdeployed. Go-to-market traction requires outcome-based service tier pricing that shifts customer relationships from equipment sales to recurring subscription economics. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by incumbent milking equipment manufacturers seeking precision livestock monitoring capabilities. Long-term viability favors precision hardware specialists with captive fertility signal detection workflows and genomic data integration layers. Watch for FCC and CE marking timeline compression as inflection indicator for first-mover advantage windows in novel wearable form factors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified milking and herd management ecosystems lock in multi-year service contracts across Wisconsin dairy cooperatives. |
| Backward Integration | In-house injection molding capacity controls REACH-compliant material certification for Northern European deployments. |
| Geographic Expansion | Drone-based thermal imaging penetration in Brazilian Mato Grosso addresses underpenetrated extensive grazing management. |
| Regulatory Alignment | Audit-ready data architectures satisfy USDA traceability mandates and EPA nutrient management monitoring requirements. |
| Acquisition of Specialist Firm | Precision livestock monitoring hardware vendors add estrus detection and cow identification workflow control. |
Research Methodology
Document review covered regulatory filings from USDA, EPA, and FDA, complemented by interviews with feedlot operations managers, dairy cooperative technology directors, veterinary equipment procurement leads, and precision livestock monitoring specialists. Secondary validation drew from agricultural trade association reports, SEC filings from publicly traded equipment manufacturers, customs data on semiconductor imports, and veterinary feed directive compliance databases. Bottom-up unit economics triangulated against top-down market sizing across technology, application, end user, and solution dimensions.
Cross-referencing historical installation data against expert panel inputs anchored the analytical framework across the projection horizon. Segmentation modeling captured technology type, operational scale, regulatory exposure tier, and geographic adoption pattern. CAGRs derived from curve-fitting approaches calibrated to disclosed vendor revenue trajectories and cooperative procurement cycle timing. Industry-specific forecast inputs incorporated genomic database integration velocity and edge computing hardware replacement cycles.
Caveats apply where FCC certification timeline extensions, REACH chemical restriction amendments, or Brazilian ANVISA traceability rule changes could materially shift the outlook. Forecasts reflect assumptions about silicon supply normalization and veterinary data science talent pipeline development. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Smart Farming Market