
 Artificial Intelligence (AI) in Agriculture Market | 2026-2036
Artificial Intelligence (AI) in Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Agriculture Market Insights
Precision livestock farming is rebalancing demand away from traditional row-crop automation as dairy and poultry operators adopt computer vision for animal health monitoring. Deere & Company anchors the machinery-integrated AI segment through its See & Spray technology platform. Microsoft Corporation extends cloud infrastructure dominance by powering predictive analytics workloads for agricultural enterprises. IBM Corporation differentiates via weather-modeling AI that insurers and cooperatives deploy for yield risk assessment.
Artificial Intelligence in Agriculture encompasses machine learning algorithms, computer vision systems, and IoT sensor networks deployed to optimize planting schedules, input application, and harvest logistics. These systems process spectral imagery, soil moisture telemetry, and historical yield databases to generate field-specific recommendations that reduce waste and improve output consistency. Crop Management Software captures the largest current revenue pool as farmers prioritize subscription-based decision support over capital-intensive hardware. Machine Learning leads technology adoption for yield prediction models, while Computer Vision accelerates fastest through drone and satellite imagery analysis. Robotics remains nascent in open-field settings but commands premium pricing in controlled-environment horticulture.
The EPA governs pesticide application rates that AI-guided sprayers must respect, creating compliance-layer requirements for computer vision targeting systems. The EU Green Deal and F-Gas Regulation shape equipment standards for automated irrigation and greenhouse climate control across European markets. The USDA's precision agriculture initiatives and NRCS conservation programs influence adoption incentives for soil analysis platforms. Stakeholders must weigh regulatory fragmentation between jurisdictions against the standardization benefits of cloud-based model deployment.
Market Dynamics
Precision livestock farming is rebalancing capital allocation across the agricultural AI sector as dairy and poultry operators redirect automation budgets from row-crop machinery toward animal health monitoring systems. This demand rotation is compressing hardware sales cycles while accelerating subscription-based software adoption.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory sustainability reporting requirements are forcing European growers to adopt AI-enabled crop monitoring tools for compliance documentation and input optimization.
- Computer vision for animal welfare:Dairy cooperatives in the Netherlands and Denmark are deploying real-time lameness detection systems to reduce veterinary costs and improve herd productivity metrics.
- Cloud infrastructure scale economics:Hyperscale providers have reduced predictive analytics storage costs below on-premise alternatives, removing the primary barrier for mid-size farm adoption.
Market Restraints
- Sensor hardware cost volatility:Semiconductor supply concentration in East Asian foundries creates input price instability for IoT soil moisture and spectral imaging equipment.
- EPA pesticide application compliance:Computer vision targeting systems must integrate real-time regulatory databases, adding software complexity and certification delays for sprayer manufacturers.
- Limited substitutability for agronomist judgment:Edge-case weather events and novel pest pressures still require human intervention, capping full automation penetration in risk-sensitive cropping systems.
Strategic Opportunities
- Controlled-environment horticulture robotics:Greenhouse operators in Spain and Italy are piloting autonomous pollination and harvesting systems for high-value tomato and pepper production.
- USDA NRCS conservation program incentives:Soil carbon quantification platforms qualify for federal cost-share payments, creating a subsidized entry point for precision agriculture adoption.
- Convergence of satellite imagery and edge AI:On-drone processing chips from NVIDIA and Qualcomm are enabling real-time weed identification without cloud latency, opening bandwidth-constrained rural markets.
Industry Challenges
- Data science talent scarcity:Agricultural technology vendors compete with fintech and healthcare for machine learning engineers, inflating compensation costs and extending product development timelines.
- Legacy equipment integration complexity:Proprietary CAN bus protocols from Deere, CNH, and AGCO block seamless AI retrofitting of installed tractor and combine fleets.
- Model validation timelines:Crop-specific AI training requires multi-season field trials across diverse soil types, delaying commercialization for new geographic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Agriculture Market |
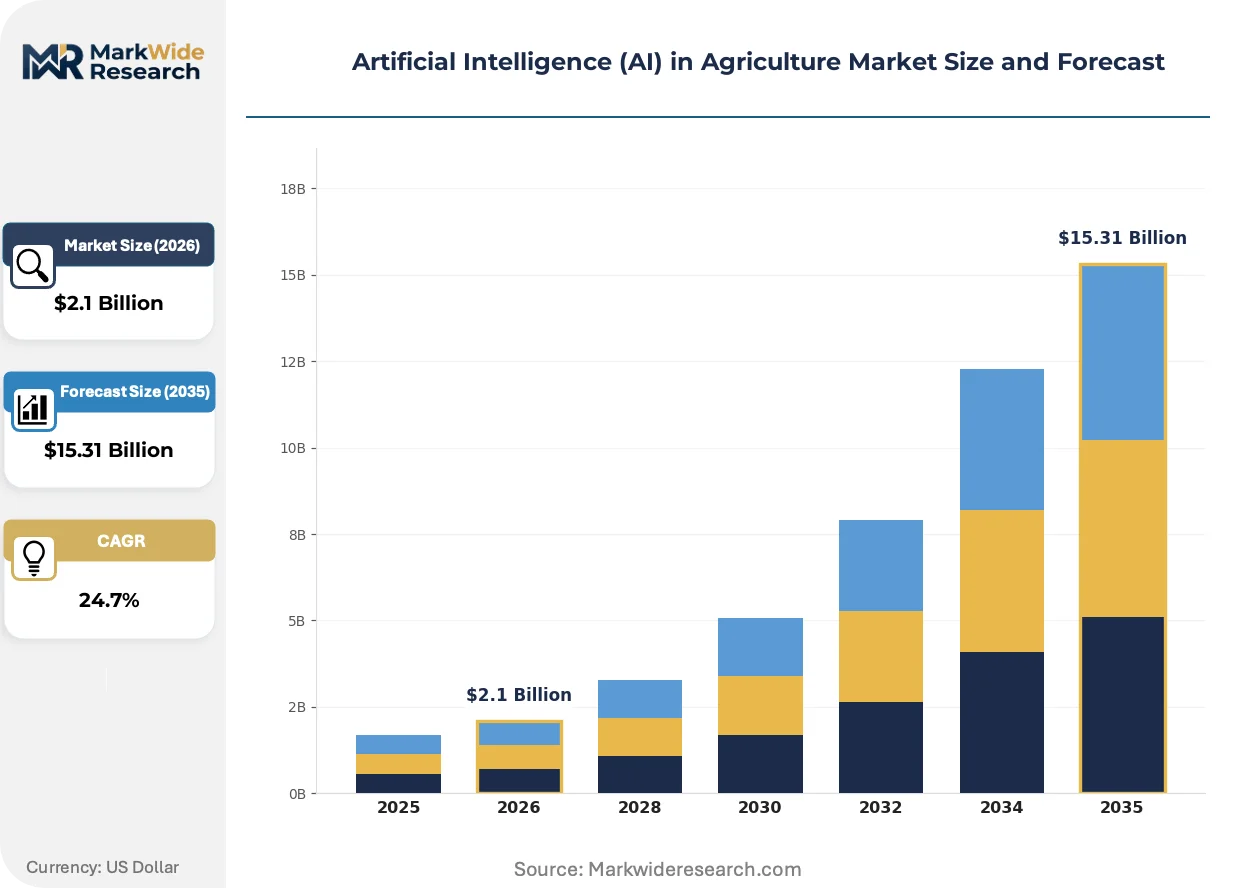
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $15.31 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Management Software, Precision Farming Tools, Predictive Analytics Platforms, Automated Irrigation Systems Technology: Machine Learning, Computer Vision, IoT Sensors, Robotics End User: Farmers, Agricultural Enterprises, Research Institutions, Government Agencies Application: Yield Prediction, Soil Analysis, Pest Control, Crop Monitoring |
| Companies Covered | Deere & Company, Microsoft Corporation, IBM Corporation, Trimble Inc., Bayer AG, Syngenta AG, AGCO Corporation, Ecorobotix SA, Farmers Edge Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Agriculture Market Trends and Innovations
Generative AI is infiltrating agricultural decision support as large language models translate complex yield forecasts into natural language recommendations accessible to non-technical farm managers. This interface simplification is expanding addressable market beyond early-adopter technologists.
Transformer-based neural networks for pest and disease identification are overtaking convolutional architectures in commercial drone analytics platforms. Major agritech service providers in Brazil and Australia are retraining their image classification stacks on vision-language models that accept text queries about field conditions. The structural compression of model development costs is enabling regional specialists to compete with centralized AI labs.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on automated irrigation systems that make autonomous water allocation decisions. Equipment manufacturers must now document algorithmic transparency and human oversight protocols to achieve CE marking for smart valve controllers. German and Dutch greenhouse technology suppliers are restructuring product architectures to isolate high-risk decision modules from standard automation functions.
Cooperative purchasing agreements are consolidating input procurement for AI-enabled farm management software across Midwestern grain belts. Groups of fifty to two hundred growers now negotiate enterprise licensing terms that individual operations could not secure, compressing vendor margins while accelerating platform standardization within county-level geographies. This collective bargaining dynamic is most pronounced in Iowa and Illinois corn-soy rotations where shared agronomic conditions justify unified system selection.
Artificial Intelligence (AI) in Agriculture Market Segmentation
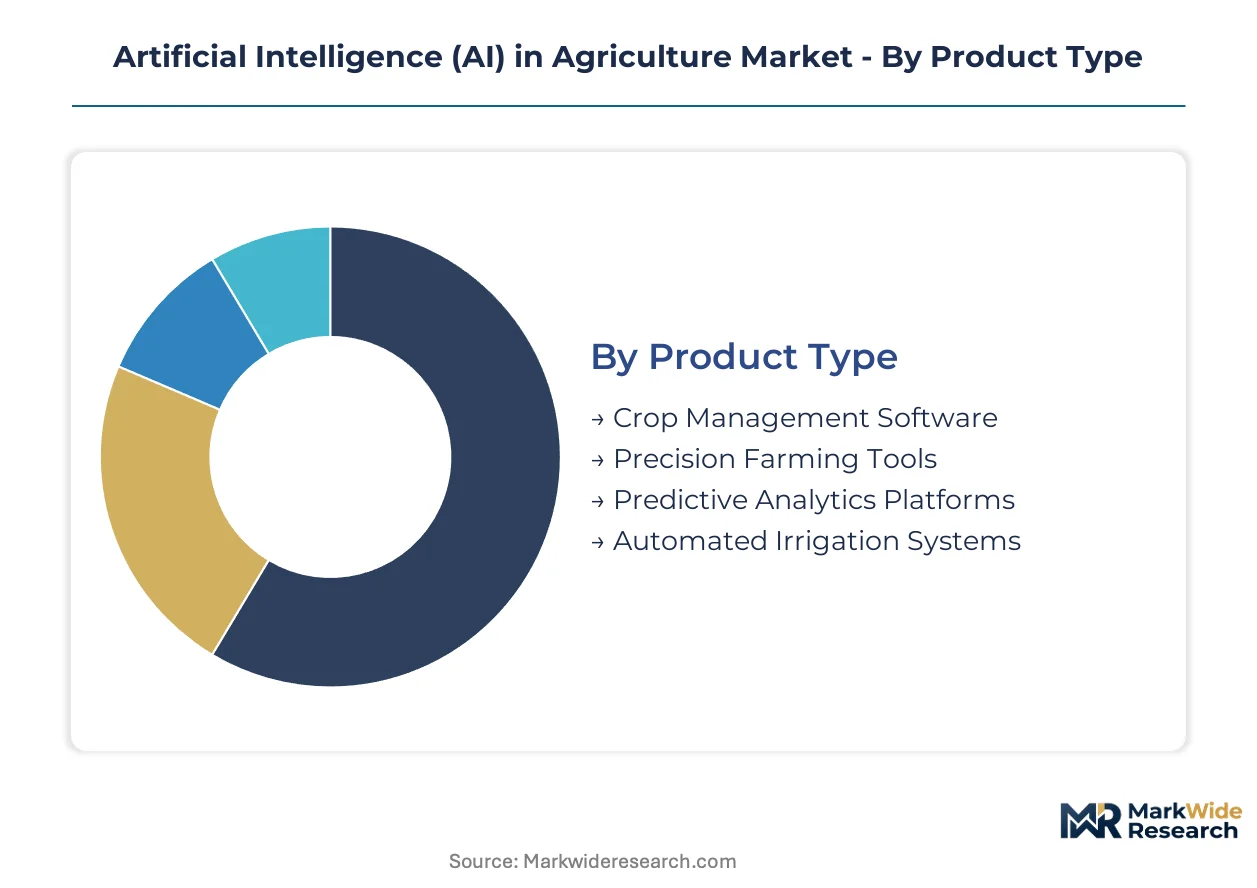
Segmentation in agricultural AI reveals divergent adoption economics between capital-intensive hardware and recurring software revenue models. Understanding where precision technology concentrates versus where it scales determines vendor positioning and partnership strategy across farming operations.
Product Type:
Volume deployment favors subscription models with minimal upfront capital, while premium pricing attaches to integrated hardware-software bundles requiring field installation.
- Crop Management Software:Cloud-based decision support platforms aggregate satellite imagery, weather data, and soil telemetry into field-specific recommendations. Demand concentrates among mid-size United States grain operations seeking to reduce input waste without tractor replacement. The USDA NRCS conservation program eligibility accelerates procurement through cost-share subsidies.
- Precision Farming Tools:Variable-rate application controllers and GPS-guided implements retrofit existing machinery with AI-enabled targeting capabilities. European adoption leads under EU Green Deal compliance requirements for input reduction documentation. Hardware-software integration complexity limits vendor proliferation.
- Predictive Analytics Platforms:Enterprise-grade yield forecasting systems serving agricultural cooperatives and commodity traders.
- Automated Irrigation Systems:Smart valve networks with soil moisture feedback loops, expanding fastest in water-stressed Spain and Italy.
Mature deployment sits with Crop Management Software. Newer deployment is concentrated in Automated Irrigation Systems.
Technology:
Adoption maturity separates proven algorithms from emerging modalities still requiring field validation and regulatory clearance.
- Machine Learning:Supervised learning models trained on multi-season yield databases generate planting date and seed density recommendations. United States corn-soy belt adoption is deepest where historical data density supports model confidence. Cloud infrastructure cost reductions from hyperscale providers removed the primary barrier for mid-size farm access.
- Computer Vision:Convolutional and transformer neural networks process drone and satellite imagery for weed detection, disease identification, and growth stage assessment. Netherlands dairy cooperatives deploy real-time lameness detection, compressing veterinary response timelines. Edge processing chips from NVIDIA and Qualcomm enable bandwidth-constrained rural deployment without cloud dependency.
- IoT Sensors:Soil moisture, temperature, and nutrient probes transmitting telemetry to centralized platforms.
- Robotics:Autonomous pollination and harvesting systems piloting in Spanish and Italian controlled-environment horticulture.
Established implementation centers on Machine Learning. Steepest expansion trajectory belongs to Computer Vision.
End User:
Procurement authority and technical sophistication divide the addressable market between individual operators and institutional buyers with dedicated IT infrastructure.
- Farmers:Individual owner-operators purchasing subscription software or financing equipment through dealer networks. United States Midwest grain producers drive volume through cooperative purchasing agreements consolidating fifty to two hundred operations into enterprise licensing negotiations. Shared agronomic conditions within county-level geographies justify unified platform selection.
- Agricultural Enterprises:Large integrated operations and cooperatives with in-house agronomy teams and captive data science capabilities. These buyers demand API access and custom model training for proprietary field portfolios.
- Research Institutions:Universities and government agricultural extension services validating algorithms across diverse soil types.
- Government Agencies:National ministries deploying AI for food security monitoring and subsidy compliance verification.
Revenue concentration rests with Farmers. Capability investment is accelerating fastest among Agricultural Enterprises.
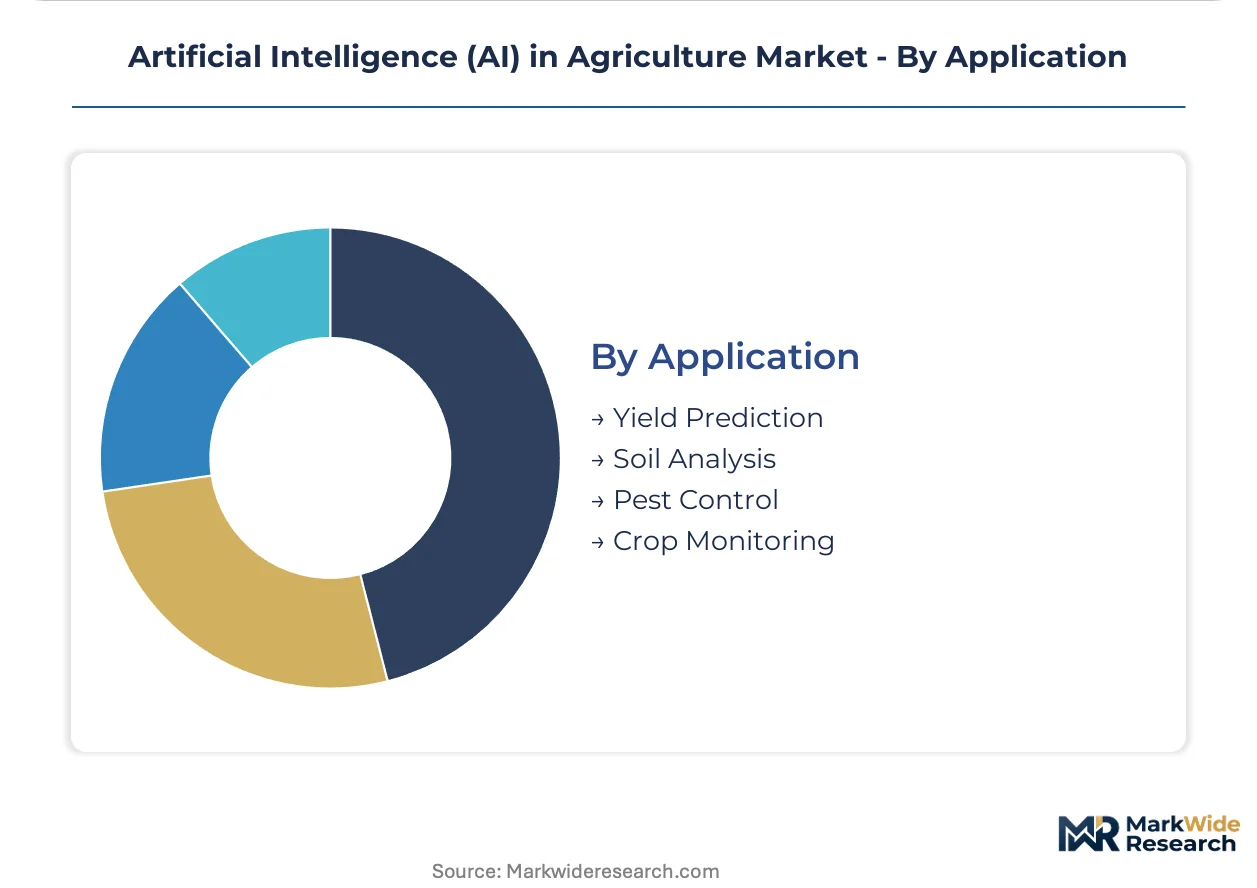
Application:
Use case maturity correlates with data availability and outcome measurability within single growing seasons.
- Yield Prediction:Regression models integrating weather forecasts, soil maps, and management practices to forecast output tonnage. Commodity traders and crop insurers in Brazil and Australia deploy these systems for contract pricing and risk assessment. Transformer architectures are overtaking earlier statistical methods in commercial platforms.
- Soil Analysis:Spectral imaging and sensor fusion quantifying organic matter, moisture, and nutrient profiles. United States adoption is subsidized through USDA precision agriculture initiatives and NRCS conservation program incentives for carbon quantification.
- Pest Control:Computer vision targeting for precision pesticide application respecting EPA application rate regulations.
- Crop Monitoring:Continuous growth stage tracking and anomaly detection via satellite and drone imagery.
Commercial maturity clusters around Yield Prediction. Emerging deployment concentrates in Pest Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Research Triangle Park in North Carolina and Silicon Valley in California concentrate venture capital flows into autonomous tractor and drone analytics startups, anchoring North American AI agriculture development.
United States
Midwestern grain cooperatives in Iowa and Illinois negotiate enterprise software licenses covering fifty to two hundred growers simultaneously, compressing vendor margins while accelerating platform standardization. The USDA's precision agriculture initiatives and NRCS conservation programs subsidize soil carbon quantification adoption through cost-share payments. Autonomous tractor development clusters in California's Central Valley, where computer vision sprayers undergo EPA pesticide compliance certification.
Germany
Greenhouse operators in Bavaria pilot autonomous pollination systems for high-value tomato and pepper production, commanding premium robotics pricing. The EU AI Act's risk classification framework imposes conformity assessment requirements on automated irrigation controllers, forcing algorithmic transparency documentation. German greenhouse technology suppliers in Lower Saxony restructure product architectures to isolate high-risk decision modules from standard automation functions.
Netherlands
Dairy cooperatives deploy real-time lameness detection systems using computer vision, reducing veterinary response timelines and improving herd productivity metrics. The EU Green Deal's Farm to Fork strategy mandates sustainability reporting that forces growers to adopt AI-enabled crop monitoring for compliance documentation. Wageningen University anchors agritech research partnerships validating multi-season AI training across diverse soil types.
Brazil
Commodity traders and crop insurers deploy transformer-based yield forecasting systems for contract pricing and risk assessment, overtaking earlier statistical methods. Vision-language models accepting text queries about field conditions retrain commercial drone analytics stacks. São Paulo-based agritech service providers compress model development costs to compete with centralized AI labs.
China
Yangtze River Delta greenhouse operators integrate smart valve networks with soil moisture feedback loops, expanding fastest in water-stressed agricultural zones. The country's national agricultural regulator encloses data localization requirements for satellite imagery processing platforms. Shenzhen hardware manufacturers supply edge processing chips enabling real-time weed identification without cloud dependency.
Artificial Intelligence (AI) in Agriculture Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with machinery-integrated AI consolidating around established agricultural equipment makers while pure-software vendors fragment across crop management niches. The competitive terrain organizes into three strategic archetypes: hyperscale cloud infrastructure providers, legacy machinery OEMs with retrofit AI platforms, and specialized computer vision startups targeting livestock monitoring. Dominant competitive moves include strategic partnerships between equipment manufacturers and cloud providers, plus geographic expansion through cooperative purchasing agreements that aggregate mid-size farm demand.
Within the legacy machinery tier, Deere & Company anchors integrated AI deployment through field-installed See & Spray systems, while AGCO Corporation represents European-rooted equipment automation. Microsoft Corporation exemplifies hyperscale cloud infrastructure dominance powering predictive analytics workloads. IBM Corporation occupies a position in weather-modeling AI serving insurers and agricultural cooperatives for yield risk assessment.
| Leading Market Players |
|---|
| Deere & Company |
| Microsoft Corporation |
| IBM Corporation |
| Trimble Inc. |
| Bayer AG |
| Syngenta AG |
| AGCO Corporation |
| Ecorobotix SA |
| Farmers Edge Inc. |
| Others |
Pricing and Supply Chain Analysis
Cooperative purchasing agreements among fifty to two hundred Midwestern grain operations are compressing vendor margins and forcing suppliers to restructure pricing architectures around enterprise licensing terms rather than individual farm subscriptions.
Pricing Analysis
Short lead times for cloud-deployed crop management software command premium subscription rates, while extended implementation timelines for precision farming hardware attract spot discounts. Three-tier pricing structure across premium, standard, and economy levels segments buyers by data integration depth and API access tiers. Price differentiation hinges on certification grade for EPA-compliant computer vision sprayers and geographic delivery cost for edge processing hardware. Pricing pressure stems from hyperscale cloud providers reducing predictive analytics storage costs below on-premise alternatives. Mid-size United States grain operations exhibit highest price sensitivity, while agricultural enterprises with captive data science capabilities demonstrate lowest.
Supply Chain Analysis
CE marking and EPA certification requirements for automated irrigation controllers and computer vision targeting systems gate supplier participation and extend procurement timelines for non-compliant manufacturers. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, creating geographic supply concentration for edge processing chips from NVIDIA and Qualcomm. IoT soil moisture sensors and spectral imaging equipment draw from East Asian foundries and German precision optics manufacturers. Single-source vulnerability in semiconductor supply creates exposure to trade restriction disruptions. Distribution runs through agricultural equipment dealer networks and direct-to-farm SaaS platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as cooperative purchasing agreements aggregate mid-size farm demand and squeeze standalone software vendors unable to achieve enterprise scale.
For Market Incumbents: Extend platform integration depth through API ecosystems that lock agricultural enterprises into proprietary data architectures. Incumbent machinery OEMs should deepen backward integration into edge processing chip supply chains to reduce exposure to Taiwan and South Korea foundry concentration. Deere & Company and AGCO Corporation must defend against pure-software entrants by bundling computer vision sprayers with subscription analytics under unified financing terms. For New Entrants and Emerging Players: The price-point gap between premium enterprise AI platforms and economy-tier basic crop monitoring software creates white-space opportunity for mid-market challengers. Target controlled-environment horticulture robotics in Spain and Italy where premium pricing tolerates nascent technology margins. Deploy vision-language models accepting text queries to differentiate drone analytics stacks against incumbent convolutional architectures. Pursue USDA NRCS conservation program eligibility as subsidized entry mechanism for soil carbon quantification platforms. For Investors and Strategic Acquirers: Re-rating potential sits with specialized computer vision startups targeting livestock monitoring given precision livestock farming's demand rotation away from row-crop automation. Long-term viability favors vendors with multi-season field trial databases validating crop-specific AI training across diverse soil types. Acquisition target archetype: regional agritech service providers in Brazil and Australia with compressed model development costs competing against centralized AI labs. Watch for inflection in cooperative purchasing agreement penetration across Iowa and Illinois corn-soy belts as signal of platform standardization maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified API ecosystems lock agricultural enterprises into proprietary data architectures against fragmented competitors. |
| Backward Integration | In-house edge processing chip sourcing reduces Taiwan and South Korea foundry dependency for machinery OEMs. |
| Certification Investment | EPA pesticide compliance and EU AI Act conformity assessment unlock regulated market access for irrigation controllers. |
| Geographic Expansion | Controlled-environment horticulture robotics pilots in Spain and Italy command premium pricing for pollination systems. |
| Strategic Partnership | Cooperative purchasing agreements aggregate fifty to two hundred Midwestern growers into enterprise licensing negotiations. |
Research Methodology
Independent corroboration across primary interviews with precision agriculture software executives, agricultural cooperative procurement directors, EPA regulatory affairs specialists, and greenhouse technology suppliers underwrites the qualitative findings. Secondary validation draws from USDA precision agriculture initiative disclosures, EU Green Deal Farm to Fork strategy documentation, SEC filings from hyperscale cloud providers, and venture capital flow databases tracking autonomous tractor startups. Bottom-up farm-level adoption modeling triangulates against top-down market sizing from equipment shipment data and SaaS subscription metrics.
Rate-of-change decomposition separates volume expansion from value capture across the projection horizon. Segmentation dimensions modeled include product type, technology modality, end-user procurement authority, and application use case maturity. CAGRs derive from multi-season field trial validation timelines, regulatory clearance pathways, and cooperative purchasing agreement penetration curves. Industry-specific forecast inputs incorporate semiconductor supply concentration indices and EPA pesticide application compliance certification backlogs.
Inputs from agricultural cooperative procurement directors and greenhouse technology suppliers were available through the study window; gaps in real-time farm management software usage telemetry introduce uncertainty bands around mid-size farm adoption velocity. Forecasts reflect assumptions regarding EU AI Act implementation timelines and USDA NRCS conservation program funding continuity. A model refresh is warranted upon material change in semiconductor supply chain concentration or EPA regulatory database integration requirements for computer vision targeting systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Smart Irrigation Software Market