
 Micro Computed Tomography Market | 2026-2036
Micro Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Computed Tomography Market Intelligence
Radiological technologist specialization is rotating toward micro-CT operators as universities and contract labs expand imaging cores. Bruker Corporation leverages its magnetic resonance heritage to cross-sell into preclinical micro-CT suites. SCANCO Medical AG dominates orthopedic and bone morphometry applications through decades of protocol refinement. TESCAN competes in materials science by extending electron microscopy relationships into complementary X-ray tomography workflows.
Micro computed tomography captures three-dimensional internal structures of objects at micron-scale resolution using X-ray attenuation and computed reconstruction algorithms, typically achieving voxel sizes below one micrometer for materials characterization and biological specimen analysis. The technique serves non-destructive testing, quantitative morphometry, and additive manufacturing defect detection where destructive sectioning would destroy specimen integrity. Desktop systems anchor routine quality control in industrial settings where throughput and footprint constraints override peak resolution requirements. Biomedical research applications represent the fastest-expanding demand pool as preclinical imaging protocols integrate micro-CT with histopathological endpoints. Machine learning technology is displacing conventional threshold-based segmentation, compressing analysis timelines from hours to minutes for high-throughput phenotyping studies.
FDA medical device regulations and ISO 13485 quality management standards govern instrument validation for clinical and pharmaceutical applications, while EPA radiation safety frameworks limit X-ray source deployment in unshielded laboratory environments. The EU Medical Device Regulation and CE marking requirements impose conformity assessment burdens on manufacturers seeking European healthcare and research access. Stakeholders must monitor evolving AI-enabled diagnostic claims that could trigger stricter FDA software-as-medical-device oversight and reshape competitive positioning for algorithm-integrated platforms.
Market Dynamics
Machine learning segmentation algorithms are compressing analysis timelines from hours to minutes, fundamentally altering throughput economics for high-throughput phenotyping studies and reshaping instrument procurement criteria across biomedical and industrial verticals.
Growth Catalysts
- FDA 21 CFR Part 11 compliance mandates:Pharmaceutical manufacturers face intensified validation requirements for electronic records, driving replacement cycles for non-compliant legacy micro-CT systems in quality control laboratories.
- Additive manufacturing defect detection:Aerospace and medical implant producers deploy desktop micro-CT systems for layer-wise porosity analysis, embedding tomography into production workflows previously reliant on destructive metallography.
- German precision manufacturing clusters:Concentrated demand from automotive and metrology institutes in Baden-Württemberg and Bavaria sustains premium instrument procurement despite broader capital equipment softness.
Market Restraints
- X-ray source supply concentration:Specialized microfocus tube production concentrates among three European and Japanese suppliers, creating vulnerability to lead-time volatility for system integrators.
- EPA radiation safety framework constraints:Unshielded laboratory deployment requires costly lead-lined enclosures or facility modifications, elevating total cost of ownership for academic users with limited infrastructure budgets.
- Destructive sectioning persistence:Conventional histopathology maintains cost advantages for terminal studies, limiting micro-CT penetration in price-sensitive contract research segments.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO-aligned quality control modernization creates demand for validated micro-CT systems in active pharmaceutical ingredient and finished dosage form inspection.
- AI-enabled diagnostic claims pathway:FDA software-as-medical-device oversight evolution may create first-mover advantages for algorithm-integrated platforms in clinical bone mineral density assessment.
- Battery electrode microstructure analysis:Lithium-ion and solid-state cell manufacturers adopt micro-CT for void and binder distribution mapping, extending addressable market beyond traditional biomedical and materials science verticals.
Industry Challenges
- Radiological technologist specialization gaps:Universities and imaging cores struggle to recruit operators with combined expertise in X-ray physics, computed reconstruction, and specimen preparation protocols.
- ISO 13485 certification timelines:Medical device manufacturers face 12-18 month conformity assessment periods for instrument validation, compressing competitive windows for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Computed Tomography Market |
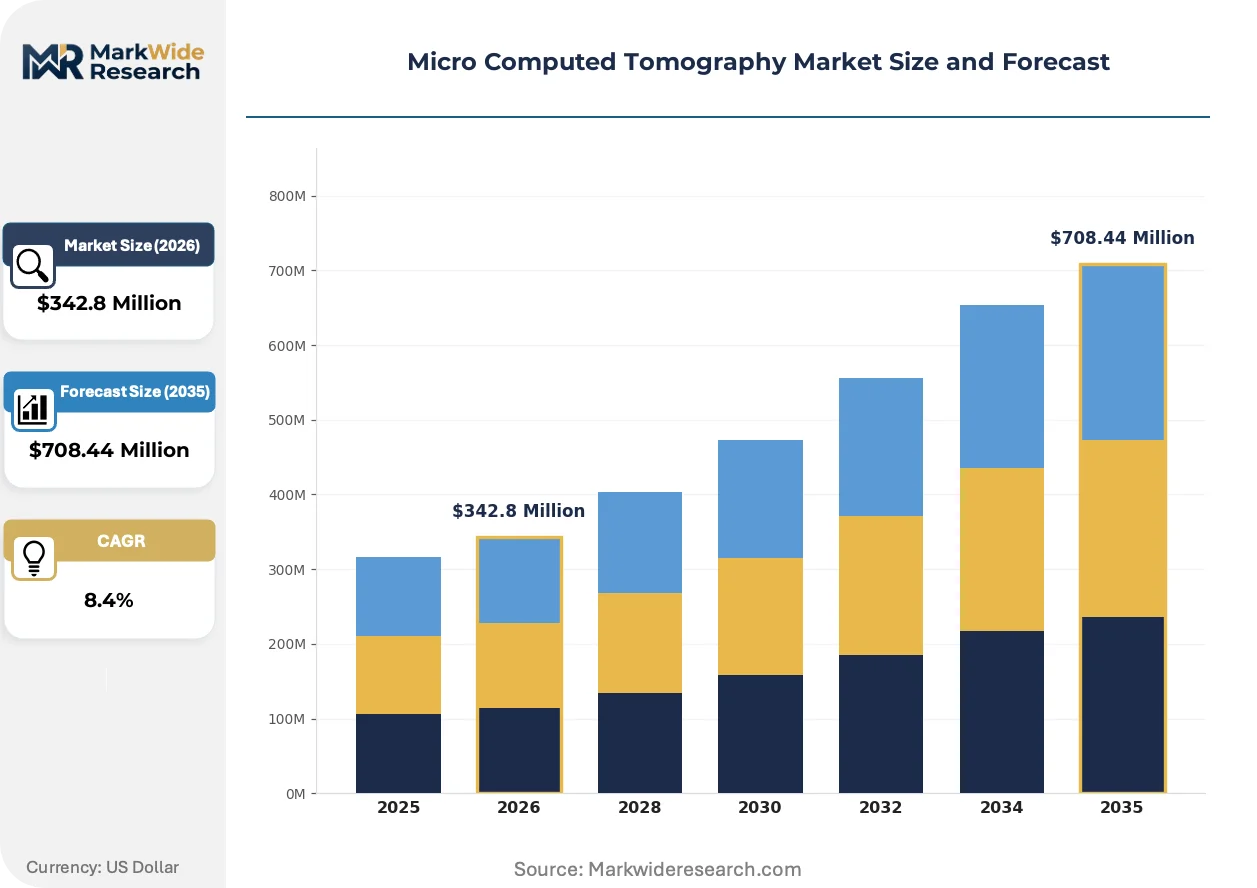
| Market Size in 2026 | $342.8 Million |
| Market Size in 2035 | $708.44 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Systems, Portable Systems, High-Resolution Systems, Custom Systems End User: Research Institutions, Pharmaceutical Companies, Academic Institutions, Healthcare Providers Application: Material Science, Biomedical Research, Quality Control, Non-Destructive Testing Technology: 3D Imaging, Image Reconstruction, Data Analysis, Machine Learning |
| Companies Covered | ZEISS, North Star Imaging Inc, Bruker Corporation, Sanying Precision Instruments Co., Ltd, TESCAN, PerkinElmer Inc., SCANCO Medical AG, Rigaku Corporation, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Computed Tomography Market Strategic Shifts & Innovations
Computational acceleration and detector evolution are converging to democratize micron-scale resolution, extending micro-CT from specialized research cores into distributed quality control environments and point-of-need inspection workflows.
Photon-counting detector technology is replacing energy-integrating sensors in premium micro-CT configurations, enabling spectral differentiation and improved contrast-to-noise ratios for low-density biological specimens. Preclinical imaging facilities at US National Institutes of Health-funded institutions are adopting these systems for longitudinal osteoporosis studies. The technology is miniaturizing into compact benchtop formats, collapsing the footprint and capital threshold for entry-level deployment.
EU Medical Device Regulation (MDR) conformity assessment requirements are extending to micro-CT systems with clinical diagnostic claims, imposing notified body involvement and clinical evidence standards previously reserved for therapeutic devices. Manufacturers seeking CE marking for European healthcare access must restructure quality management systems and technical documentation. Bone morphometry applications in orthopedic research face the steepest compliance burden, driving consolidation among vendors with established regulatory affairs capabilities.
Service unbundling is separating hardware procurement from analysis software subscriptions and maintenance contracts, enabling academic cores to match cost structures to grant funding cycles. Contract research organizations in Japan and Germany now procure instruments with minimal initial software licensing, deferring advanced segmentation modules to project-specific activation. This flexibility is most visible in multi-instrument imaging cores where utilization patterns vary across funding periods and collaborative agreements.
Micro Computed Tomography Market Segmentation
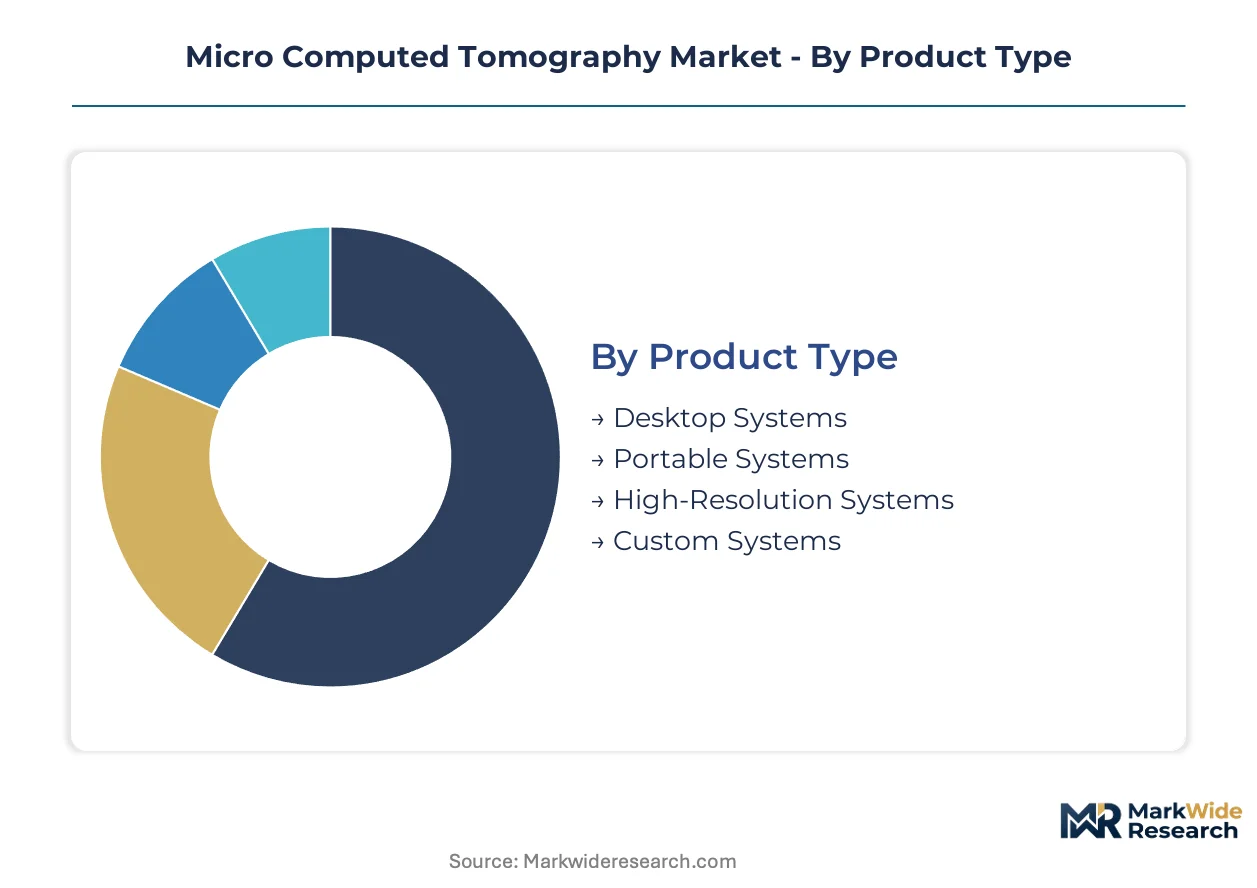
Segmentation in micro-CT reveals how substitute technologies and alternative inspection methods pressure different product tiers. Desktop systems face displacement from optical coherence tomography in surface-only applications, while high-resolution configurations defend against electron microscopy in subsurface analysis.
Product Type:
Desktop systems confront the strongest substitution threat from lower-cost optical and ultrasound methods for routine quality control, while custom configurations resist displacement through application-specific optimization.
- Desktop Systems:Compact footprint instruments with sealed X-ray tubes and fixed magnification geometries serve routine quality control in manufacturing environments. Demand concentrates in German automotive supply chains where Baden-Württemberg precision manufacturers embed tomography into production lines, constrained by EPA radiation safety requirements for unshielded deployment.
- High-Resolution Systems:Sub-micron voxel instruments with rotating anode sources and large-format detectors target preclinical imaging and materials research. NIH-funded biomedical cores in the United States drive procurement for longitudinal osteoporosis studies, though X-ray source supply concentration among European and Japanese vendors creates lead-time vulnerability.
- Portable Systems:Battery-powered or cart-mounted configurations for field inspection and museum conservation applications.
- Custom Systems:Application-engineered platforms with modified sample stages, environmental chambers, or specialized detectors for unique research protocols.
Desktop systems anchor the volume base while high-resolution configurations gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive pharmaceutical validation from grant-dependent academic procurement, reshaping vendor pricing architectures.
- Pharmaceutical Companies:FDA 21 CFR Part 11 compliance mandates drive replacement cycles for electronic records validation in quality control laboratories. United States-based manufacturers face intensified inspection protocols, accelerating instrument turnover despite broader capital equipment softness.
- Research Institutions:Multi-instrument imaging cores with variable utilization patterns favor service-unbundled procurement models. German Helmholtz Association centers and Japan's RIKEN institute network sustain premium demand through centralized federal funding mechanisms.
- Academic Institutions:Individual laboratory budgets constrain total cost of ownership, elevating importance of deferred software licensing and shared core facility access models.
- Healthcare Providers:Clinical diagnostic claims trigger EU Medical Device Regulation conformity assessment burdens, limiting penetration to established regulatory affairs capabilities.
Pharmaceutical companies anchor the volume base while research institutions gain share at the steepest rate.
Application:
Volume concentration in materials characterization creates margin pressure, while biomedical expansion offers differentiation through regulatory certification.
- Biomedical Research:Preclinical imaging protocols integrating micro-CT with histopathological endpoints represent the fastest-expanding demand pool. Machine learning segmentation compresses analysis timelines from hours to minutes for high-throughput phenotyping at US National Institutes of Health-funded institutions.
- Material Science:Additive manufacturing defect detection for aerospace and medical implant layer-wise porosity analysis embeds tomography into production workflows. German metrology institutes and Japanese automotive suppliers sustain procurement despite destructive sectioning cost advantages in price-sensitive segments.
- Quality Control:Routine inspection for porosity, cracks, and dimensional accuracy in precision manufacturing environments.
- Non-Destructive Testing:Conservation science and failure analysis applications where specimen integrity preservation is paramount.
Material science anchors the volume base while biomedical research gains share at the steepest rate.
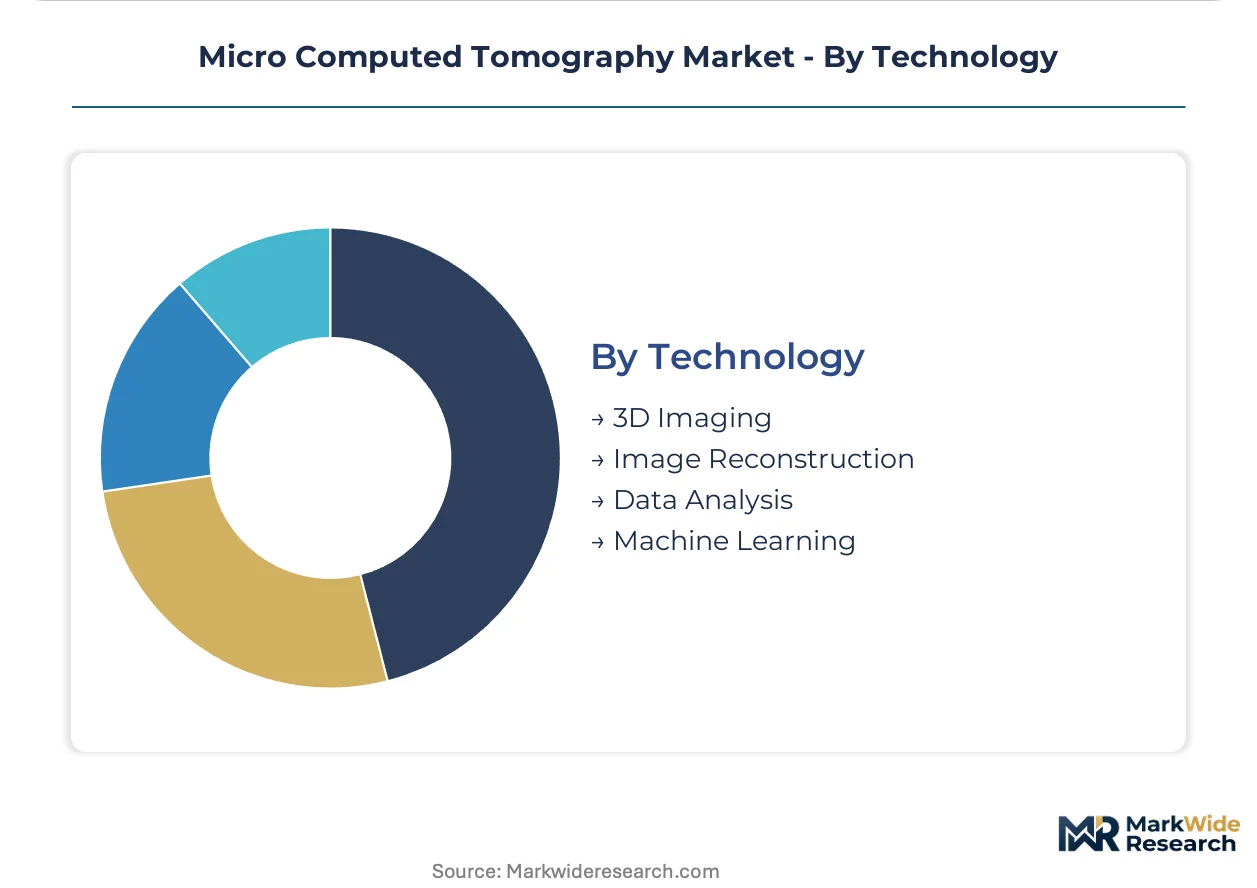
Technology:
Supply concentration in detector manufacturing favors integrated platform vendors over component specialists, consolidating competitive architecture.
- Machine Learning:Algorithm-driven segmentation and quantitative morphometry displace conventional threshold-based methods. FDA software-as-medical-device oversight evolution may create first-mover advantages for integrated platforms in clinical bone mineral density assessment.
- 3D Imaging:Volumetric reconstruction from multi-angle projection data forms the core technical capability across all product tiers. Photon-counting detector adoption at NIH-funded preclinical facilities improves contrast-to-noise ratios for low-density biological specimens.
- Image Reconstruction:Filtered back-projection and iterative algorithms for computed tomography data processing.
- Data Analysis:Quantitative morphometry, porosity calculation, and dimensional measurement software modules.
3D imaging anchors the volume base while machine learning gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German precision manufacturers deploy desktop systems for inline quality control, while United States biomedical cores prioritize high-resolution configurations for longitudinal studies. Japanese automotive suppliers balance both applications through centralized metrology institutes.
United States
NIH-funded preclinical imaging facilities drive demand for photon-counting detector systems. FDA 21 CFR Part 11 compliance mandates accelerate replacement cycles in pharmaceutical quality control laboratories. Greater Boston and Research Triangle Park sustain concentrated procurement through federal research funding mechanisms.
Germany
Automotive supply chains in Baden-Württemberg embed micro-CT into production workflows for additive manufacturing defect detection. EU Medical Device Regulation conformity assessment requirements reshape vendor selection criteria for clinical diagnostic applications. Bavarian metrology institutes and precision manufacturers anchor premium instrument demand despite broader capital equipment softness.
Japan
RIKEN institute network and university imaging cores sustain demand for high-throughput phenotyping configurations. METI industrial standards frameworks govern instrument validation for manufacturing quality control deployment. Nagoya automotive cluster and Osaka biomedical corridor concentrate procurement through centralized federal funding.
China
Battery electrode microstructure analysis for lithium-ion manufacturers creates emerging demand outside traditional verticals. NMPA medical device registration requirements impose conformity assessment burdens on clinical diagnostic platforms. Yangtze River Delta precision manufacturing bases adopt desktop systems for routine porosity inspection.
India
CDSCO-aligned quality control modernization drives validated system procurement in pharmaceutical manufacturing. Active pharmaceutical ingredient and finished dosage form inspection applications expand addressable market beyond research institutions. Maharashtra and Gujarat pharmaceutical clusters lead adoption through contract manufacturing organization expansion.
Micro Computed Tomography Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with cross-technology platform vendors leveraging existing customer relationships to enter adjacent imaging workflows. The structure consolidates around three archetypes: diversified analytical instrument conglomerates, focused preclinical imaging specialists, and precision optics heritage players. Competitive moves concentrate on algorithm-integrated platform development and service unbundling to match academic procurement cycles.
Among diversified analytical instrument conglomerates, Thermo Fisher Scientific and PerkinElmer Inc. occupy positions spanning life sciences and industrial applications. ZEISS exemplifies the precision optics heritage archetype. Bruker Corporation represents cross-technology platform vendors leveraging magnetic resonance customer bases. SCANCO Medical AG anchors the focused preclinical imaging specialist tier.
| Leading Market Players |
|---|
| ZEISS |
| North Star Imaging Inc |
| Bruker Corporation |
| Sanying Precision Instruments Co., Ltd |
| TESCAN |
| PerkinElmer Inc. |
| SCANCO Medical AG |
| Rigaku Corporation |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
FDA 21 CFR Part 11 compliance mandates gate both supplier qualification and price differentiation simultaneously, as pharmaceutical manufacturers demand validated electronic records systems that only established vendors can provision. This regulatory threshold stratifies procurement between premium validated platforms and lower-tier research-grade instruments, concentrating pricing power among ISO 13485-certified manufacturers while academic buyers face compressed budgets.
Pricing Analysis
Long-term service contracts dominate procurement, with pharmaceutical manufacturers locking in multi-year maintenance and software subscription bundles to satisfy FDA validation requirements. Price differentiation rests on certification tier and after-sales service intensity, with ISO 13485-validated systems commanding substantial premiums over research-grade alternatives. Cost compression in the academic tier intensifies as shared core facility models spread fixed costs across multiple principal investigators. Contract research organizations exhibit the sharpest price sensitivity, while NIH-funded biomedical cores demonstrate relatively inelastic demand for photon-counting configurations.
Supply Chain Analysis
Extended lead times for specialized microfocus X-ray tubes constrain system integrator output planning, with inventory buffers rarely exceeding eight weeks. Component sourcing concentrates in Germany, Japan, and the United States, where Hamamatsu Photonics and Oxford Instruments anchor detector and tube supply. Single-source vulnerability around rotating anode tube manufacturing creates exposure to export control fluctuations. Distribution runs through direct sales forces for pharmaceutical accounts and specialized distributors for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among federally funded imaging cores and consolidated pharmaceutical quality control departments, fragmenting the vendor-customer relationship and intensifying price negotiation leverage.
For Market Incumbents: Secure algorithm-integrated platform development to defend against machine learning specialist entrants disrupting segmentation workflows. Deepen backward integration into photon-counting detector manufacturing to reduce exposure to Hamamatsu supply constraints. Prioritize EU MDR regulatory affairs capacity as notified body involvement extends to bone morphometry applications. For New Entrants and Emerging Players: Deferred software licensing models represent a service-layer gap where incumbents under-serve grant-dependent academic cores with inflexible bundled pricing. Target Indian pharmaceutical manufacturing clusters where CDSCO-aligned quality control modernization outpaces established vendor presence. Pursue battery electrode microstructure analysis as a go-to-market angle, leveraging lithium-ion manufacturer demand outside traditional biomedical verticals. For Investors and Strategic Acquirers: FDA software-as-medical-device oversight evolution reshapes the acquisition landscape toward algorithm-integrated platforms with clinical diagnostic pathways. Five-to-ten year viability favors vendors with established regulatory affairs capabilities across FDA, EU MDR, and NMPA frameworks. Monitor AI-enabled diagnostic claim submissions as an inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Integration | NIH-funded preclinical facilities adopt spectral differentiation for longitudinal osteoporosis studies. |
| Service Unbundling | German Helmholtz Association centers defer advanced segmentation modules to project-specific activation. |
| Regulatory Affairs Capacity Expansion | EU MDR conformity assessment burdens bone morphometry vendors with 12-18 month certification timelines. |
| Battery Electrode Analysis Platform | Lithium-ion manufacturers adopt void mapping for solid-state cell microstructure characterization. |
| Machine Learning Segmentation Development | Algorithm-driven analysis compresses phenotyping timelines from hours to minutes at US biomedical cores. |
Research Approach
Initial hypotheses were tested against primary input from preclinical imaging core directors, pharmaceutical quality control managers, regulatory affairs specialists, and X-ray detector manufacturing engineers and refined through secondary validation. Primary interviews combined with FDA 510(k) filings, NIH RePORTER grant databases, EU MDR notified body documentation, and customs trade data for precision instrument imports. Bottom-up instrument shipment analysis triangulated against top-down research funding allocation patterns.
Variance decomposition across product type, end user, application, and technology segmentation dimensions anchored the analytical framework. CAGRs were derived from installed base growth rates and replacement cycle compression in validated environments. Forecast inputs incorporated NIH budget appropriation trajectories, German automotive capital expenditure surveys, and lithium-ion manufacturing capacity expansion announcements.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EU MDR, and CDSCO quality control frameworks; material policy shifts would require re-modeling. Model outputs reflect assumptions around X-ray source supply stability and federal research funding levels. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
PET Imaging Systems Market
Imaging
Hybrid Imaging Systems Market
Imaging
High-Speed Camera Market
Imaging
Global AI in Computer Vision Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Machine Vision Camera Market
Imaging
Frame Grabber Market
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Thermal Imaging Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
IR Camera Market
Imaging
Compact Camera Module Market
Imaging
Industrial Computed Tomography Market
Imaging
Machine Vision System and Services Market
Imaging
Image Intensifier Market
Imaging
2D and 3D Machine Vision Systems Market