
 Compact Camera Module Market | 2026-2036
Compact Camera Module Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Camera Module Market Intelligence
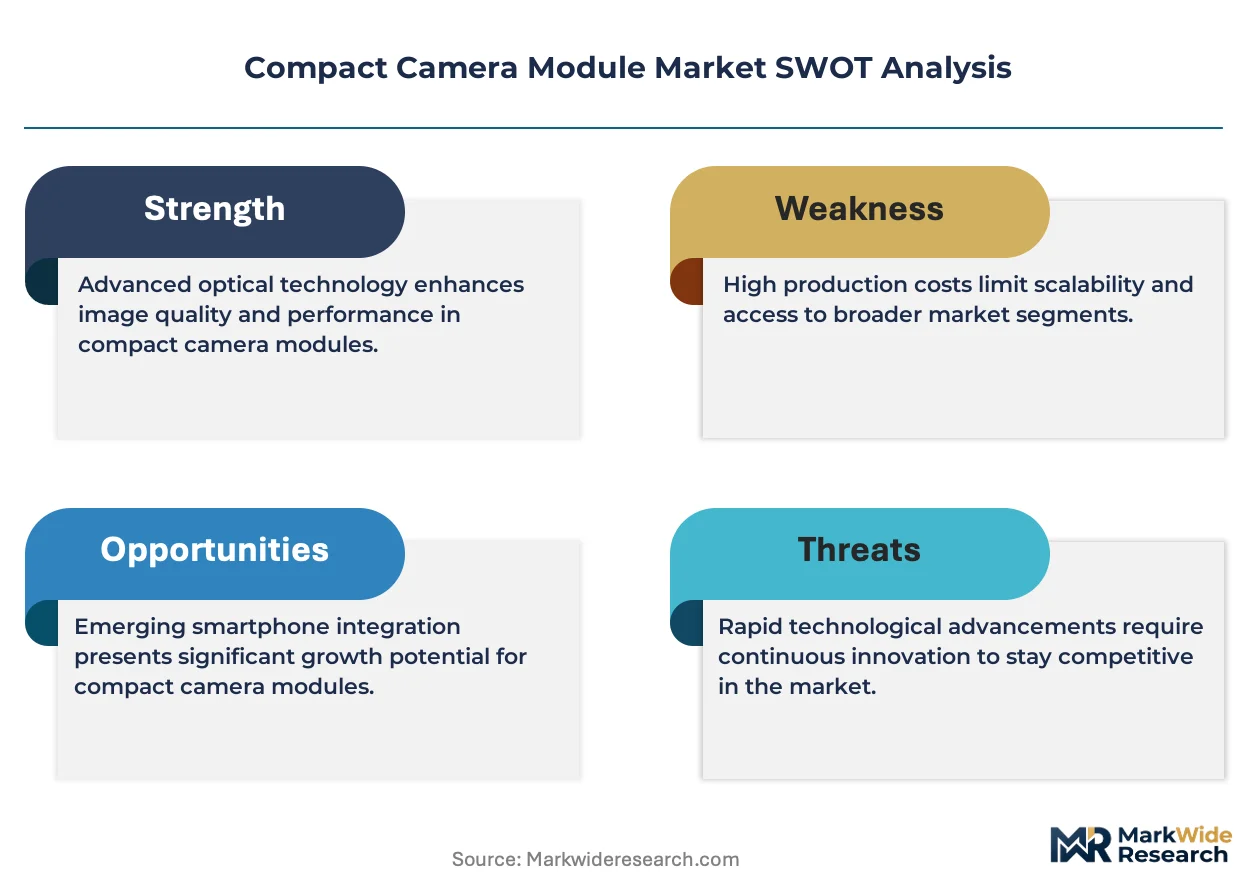
Differentiation between high-performance and standard modules is shifting toward advanced features like optical image stabilization and higher resolution sensors. Sony Corporation leverages its leadership in CMOS sensor technology to dominate the premium segment. LG Innotek competes on manufacturing scale and its established relationships with major mobile device manufacturers. Meanwhile, OFilm Group specializes in modules for the high-volume, mid-range smartphone market in Asia.
A compact camera module is a self-contained unit integrating a lens, image sensor, and processing electronics into a single package. These modules often feature pixel sizes measured in micrometers and are designed for embedded vision applications. High resolution modules and autofocus modules represent the core of the market's value, driven by smartphone applications. The industrial inspection segment, while smaller, offers higher margins for specialized infrared modules.
Product standards are influenced by directives like the EU's RoHS, which restricts hazardous substances in electronics. In the US, components for security systems may need to comply with standards referenced by the FCC for telecommunications equipment. Component suppliers must navigate increasingly complex supply chain verification requirements demanded by downstream automotive and consumer electronics customers.
Market Dynamics
The market's structure is defined by the smartphone industry's relentless demand for multi-camera systems for enhanced imaging. This demand concentrates production, innovation, and supply chain logistics within China's advanced electronics manufacturing ecosystem, influencing cost and availability globally.
Growth Catalysts
- Stacked Sensor Technology:The industry-wide transition to stacked CMOS image sensors allows smaller module footprints and higher processing speeds, enabling more complex imaging features within constrained device spaces.
- Automotive ADAS Integration:The integration of multiple camera modules into Advanced Driver-Assistance Systems for functions like lane departure warnings and surround-view monitoring creates a high-value, long-term demand stream.
- Telehealth Expansion:Government support and private investment in telehealth services, particularly in North America and Europe, drive demand for high-resolution camera modules in medical diagnostic devices and remote patient monitoring.
Market Restraints
- CMOS Sensor Supply Bottlenecks:The market's heavy reliance on a few CMOS image sensor suppliers, primarily in Japan and South Korea, creates vulnerability to supply disruptions and price volatility.
- Thermal Management Complexity:Increasing pixel density and on-board processing within smaller modules generate significant heat, a technical challenge that can degrade image quality and module lifespan without advanced thermal solutions.
- Volatile Rare Earth Inputs:Lenses and actuators within autofocus and optical image stabilization systems depend on rare earth elements, whose prices are subject to geopolitical tensions and concentrated supply chains.
Strategic Opportunities
- AR/VR Headsets:The nascent but expanding market for augmented and virtual reality devices requires multiple, low-latency camera modules for head and eye tracking, creating a new growth vector beyond smartphones.
- Industrial Automation in India:India's push for manufacturing self-reliance through initiatives like the PLI scheme presents an opportunity for specialized modules in industrial inspection, robotics, and quality control systems.
- AI on the Edge:Integrating dedicated AI processing units directly into the camera module allows for on-device image analysis, opening applications in smart home security, retail analytics, and autonomous drones.
Industry Challenges
- Supply Chain Verification Demands:Meeting complex verification requirements from automotive and consumer electronics customers, which trace materials and labor practices, adds significant administrative overhead and compliance risk for module assemblers.
- Autofocus and OIS Patents:Navigating the dense patent landscape for voice coil motor actuators used in autofocus and optical image stabilization systems requires significant legal resources and can lead to costly licensing disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Camera Module Market |
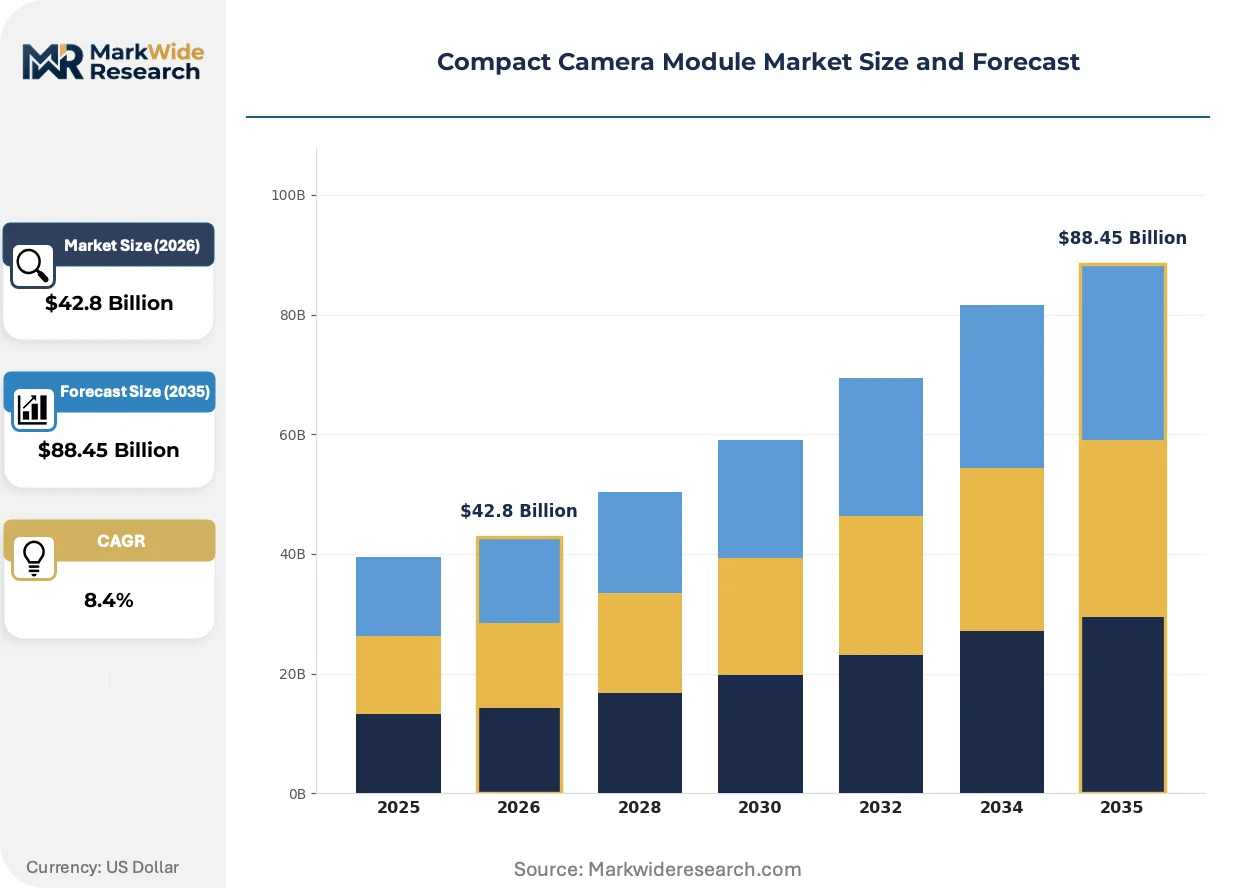
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Camera Module, Autofocus Module, Wide Angle Module, High Resolution Module, Infrared Module Technology: CMOS, CCD, BSI, FSI, Stacked Sensor Application: Smartphones, Drones, Wearables, Security Systems, Industrial Inspection End User: Mobile Device Manufacturers, Drone OEMs, Consumer Electronics Producers, Surveillance Providers, Automation Specialists |
| Companies Covered | Sony Corporation, Sharp Corporation, LG Innotek, OmniVision Technologies, Chicony Electronics, Samsung Electro-Mechanics, OFilm Group, Cowell E Holdings, Sunny Optical Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Camera Module Market Strategic Shifts & Innovations
Miniaturization continues to define the product roadmap, but the new competitive frontier is embedding advanced computational capabilities directly within the module. This shift transforms modules from simple imagers into intelligent vision sensors for a new class of applications.
Per-pixel microlens and advanced pixel-binning techniques are technologies that enhance light sensitivity in low-light conditions. Smartphone manufacturers in the premium segment are rapidly adopting these features to differentiate imaging performance. This capability is rewriting the performance expectations for standard camera modules across all price tiers.
The European Union's updated RoHS directive continues to tighten restrictions on hazardous substances like lead and cadmium used in solders and electronic components. This is forcing manufacturers to re-qualify materials and redesign production processes. The industrial and medical segments are most affected due to longer product lifecycles and stringent validation requirements.
A notable demand-side shift involves the unbundling of software and hardware in procurement for industrial vision systems. Instead of buying fully integrated systems from a single vendor, customers now often source camera modules directly and partner with specialized software firms for analytics. This trend is most visible in North American and European markets for factory automation, where flexibility and customization are paramount.
Compact Camera Module Market Segmentation
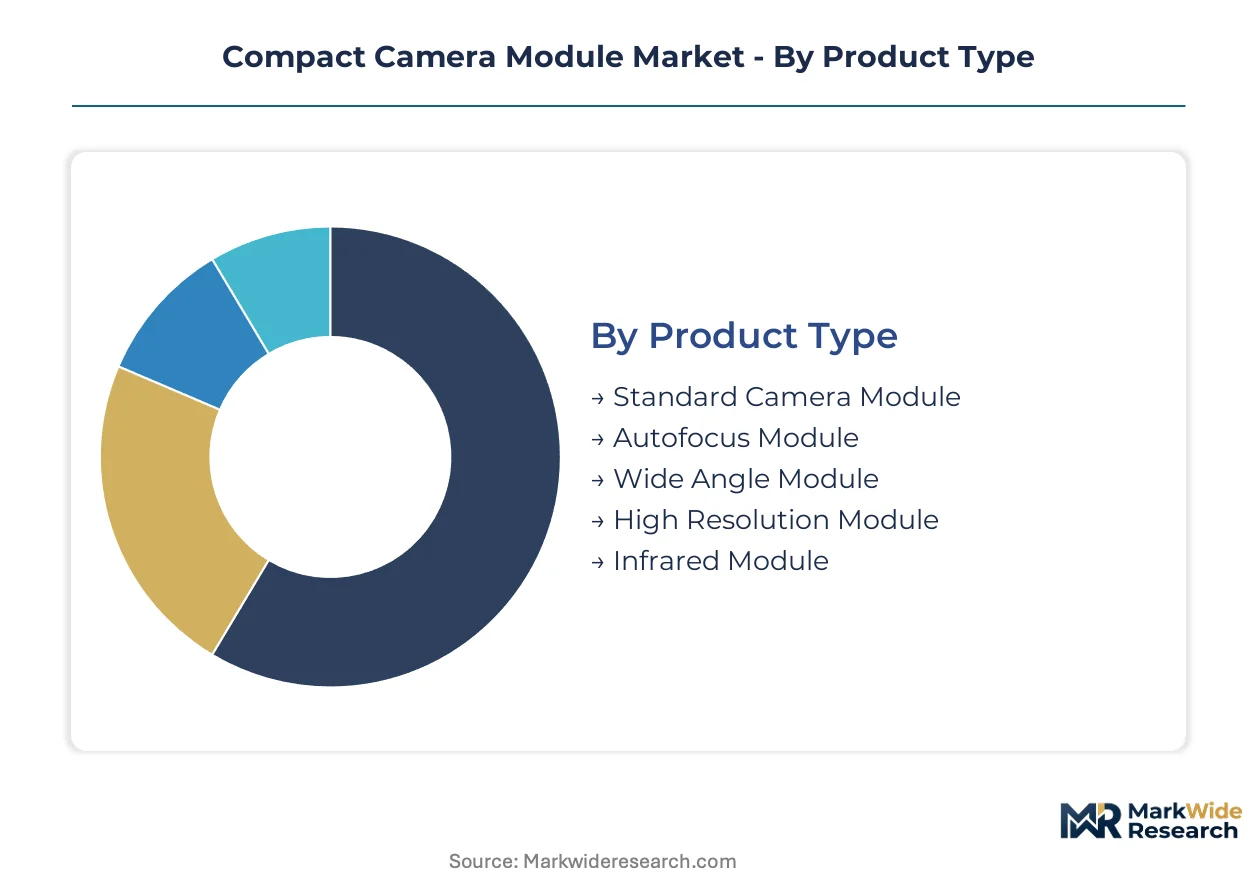
The compact camera module market segments reflect the diverse requirements of embedded vision systems, ranging from high-volume consumer electronics to specialized industrial applications. Each segment possesses distinct technical specifications and demand drivers, influencing manufacturing processes and supply chain dynamics.
Product Type:
Product type segmentation differentiates modules based on their core functionality and integration depth, from basic imaging to advanced optical capabilities within a device.
- High Resolution Module:These modules incorporate image sensors with high pixel counts, typically exceeding 20 megapixels, designed for capturing detailed imagery. Demand concentrates in premium smartphones and advanced digital photography, driven by consumer expectations for superior image quality.
- Autofocus Module:Integrating voice coil motor actuators or other mechanisms, these modules dynamically adjust lens focus for sharp images at varying distances. Smartphone applications represent the primary demand, where rapid and accurate focusing enhances user experience.
- Standard Camera Module:These modules provide basic imaging capabilities without advanced features like optical stabilization or high-resolution sensors.
- Wide Angle Module:Featuring lenses with a broad field of view, these modules are used for panoramic shots or capturing more context within a single frame.
- Infrared Module:Designed to detect infrared radiation, these specialized modules find use in night vision, thermal imaging, and industrial inspection tasks.
Volume placements concentrate in Standard Camera Module; the faster expansion belongs to High Resolution Module.
Technology:
Technology segmentation highlights the underlying sensor and image processing innovations that define module performance and miniaturization capabilities.
- Stacked Sensor:This technology layers the photodiode and processing circuitry, enabling smaller footprints, faster data readout, and enhanced computational photography. Supply concentration for these advanced sensors primarily resides with a few key manufacturers in Japan and South Korea.
- CMOS:Complementary Metal-Oxide-Semiconductor sensors are the dominant imaging technology, offering low power consumption and high integration capabilities. Global smartphone production drives the immense demand for CMOS sensors.
- BSI:Backside Illumination technology improves light-gathering efficiency by positioning circuitry behind the photodiode, enhancing low-light performance.
- FSI:Frontside Illumination sensors are a more traditional design, with circuitry placed in front of the photodiode, suitable for less demanding applications.
- CCD:Charge-Coupled Device sensors provide high image quality but are less common in compact modules due to higher power consumption and manufacturing costs.
Established CMOS technology commands market share, while Stacked Sensor technology demonstrates the steepest expansion trajectory.
Application:
Application segmentation categorizes modules based on their primary end-use within various electronic devices and systems, reflecting diverse functional requirements.
- Smartphones:Multi-camera systems in mobile phones represent the largest volume application, driving innovation in miniaturization, image processing, and resolution. Consumer demand for advanced photography features like portrait mode and optical zoom propels this segment.
- Industrial Inspection:This segment utilizes specialized modules, often infrared or high-resolution, for automated quality control, defect detection, and precision measurement in manufacturing. The industrial sector in Germany and Japan shows consistent demand for these robust solutions.
- Security Systems:Camera modules are integrated into surveillance cameras, doorbell cameras, and access control systems for monitoring and threat detection.
- Drones:Compact modules enable aerial photography, video recording, and navigation for both consumer and commercial unmanned aerial vehicles.
- Wearables:Small, low-power modules are used in smartwatches, augmented reality glasses, and body cameras for capturing images or tracking user movements.
Smartphones secure the largest market share, while Industrial Inspection applications are gaining share fastest due to automation trends.
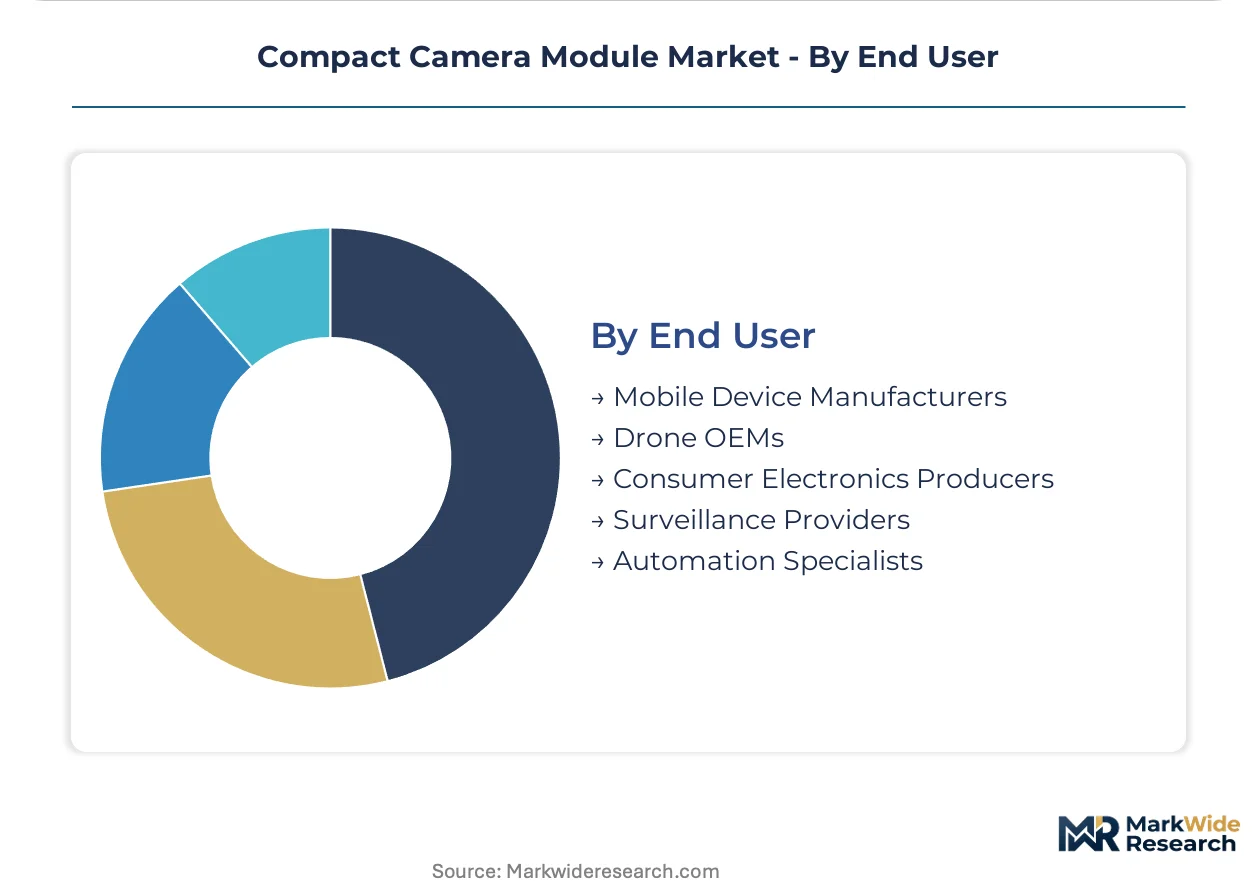
End User:
End user segmentation identifies the primary customer groups procuring compact camera modules, reflecting distinct purchasing patterns and integration needs.
- Mobile Device Manufacturers:These companies integrate millions of camera modules into smartphones and tablets, demanding high volumes, competitive pricing, and advanced imaging features. Their procurement strategies heavily influence module design and production capacity.
- Automation Specialists:Firms specializing in industrial automation and robotics procure modules for machine vision systems, requiring robust, high-precision, and often customized solutions. Germany's advanced manufacturing sector is a significant customer base.
- Consumer Electronics Producers:This category includes manufacturers of laptops, smart home devices, and other non-mobile consumer electronics that require integrated camera functionality.
- Surveillance Providers:Companies that design and install security and monitoring systems purchase modules for their cameras, prioritizing reliability and specific sensor capabilities.
- Drone OEMs:Original Equipment Manufacturers of drones integrate compact camera modules for flight navigation, photography, and specialized sensing tasks.
Mobile Device Manufacturers represent the largest purchasing segment, while Automation Specialists show increasing demand for tailored solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's advanced electronics manufacturing ecosystem heavily influences the global compact camera module market's production and innovation. This region's integrated supply chains concentrate component assembly and module fabrication for diverse applications. Demand drivers vary significantly across key global geographies.
China
China's vast smartphone market drives immense demand for multi-camera systems and high-resolution modules. The country's MIIT policies encourage domestic innovation and self-sufficiency in electronics components. Major manufacturing hubs in the Pearl River Delta, like Shenzhen, concentrate production and assembly for global brands.
United States
The United States experiences strong demand for high-resolution modules in telehealth devices and automotive ADAS systems. Components for security systems must comply with standards referenced by the FCC for telecommunications equipment. Silicon Valley and other tech clusters foster innovation in embedded vision and AI-on-the-edge applications.
Japan
Japanese manufacturers are crucial suppliers of advanced CMOS image sensors, foundational for compact camera modules. METI initiatives support research and development in next-generation imaging technologies and robotics. Tokyo and Osaka host key R&D centers and specialized industrial inspection module producers.
Germany
Germany's robust industrial automation sector fuels demand for specialized infrared and high-resolution modules for inspection systems. Strict EU RoHS directives influence material selection and manufacturing processes for electronic components. Bavaria and Baden-Württemberg are centers for automotive ADAS development and machine vision integration.
India
India's growing manufacturing base and PLI scheme initiatives are creating opportunities for localized production of specialized modules. The country's BIS standards guide quality and safety for electronic products. Bengaluru and Pune are emerging as hubs for industrial automation and smart city applications requiring embedded vision.
Compact Camera Module Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and manufacturing scale within the compact camera module market. The industry structure shows a clear tiering, with a few dominant sensor suppliers at the top, followed by module integrators and high-volume assemblers. Strategic archetypes include technology leaders, integrated manufacturers, and high-volume specialists. Dominant competitive moves involve technology licensing and capacity expansion.
On the premium-tier vector, Sony Corporation exemplifies leadership in CMOS sensor technology, anchoring innovation in high-performance modules, particularly for advanced smartphone and specialized industrial applications requiring superior image quality. LG Innotek, a South Korean-based manufacturing entity, occupies a position as an integrated module producer with strong relationships with major mobile device manufacturers, leveraging its scale and established supply networks. OFilm Group, a Chinese specialist, represents the high-volume segment, focusing on the mid-range smartphone market in Asia and optimizing for cost-effective mass production and rapid turnaround times.
| Leading Market Players |
|---|
| Sony Corporation |
| Sharp Corporation |
| LG Innotek |
| OmniVision Technologies |
| Chicony Electronics |
| Samsung Electro-Mechanics |
| OFilm Group |
| Cowell E Holdings |
| Sunny Optical Technology |
| Others |
Cost & Logistics Intelligence
Integrated manufacturers with established relationships with mobile device producers often dictate pricing discipline, influencing both supply behavior and market entry for specialized module types. Their volume commitments stabilize demand for core components.
Pricing Analysis
Value-based pricing for compact camera modules anchors on image quality and integration complexity. Premium-mid-economy pricing differentiation reflects sensor resolution, optical stabilization, and embedded processing capabilities. Cost compression in the standard module segment is intensifying due to high-volume manufacturing in China. Mobile device manufacturers exhibit the highest price sensitivity for mass-market modules, while industrial inspection customers prioritize performance over cost.
Supply Chain Analysis
Reverse logistics for specialized modules, particularly in industrial and medical applications, often involve component recovery and refurbishment to mitigate material costs. Supply concentration for advanced CMOS sensors resides primarily in Japan and South Korea. Rare earth elements, critical for lenses and actuators, represent a raw material dependency subject to commodity price volatility. Single-source vulnerability for advanced sensors poses a significant supply chain risk. Distribution runs through direct sales channels to major OEMs and specialized distributors for niche industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with stacked sensor architectures rapidly displacing traditional imaging solutions. This shift redefines module capabilities and application possibilities.
For Market Incumbents: Deepen research and development into AI-on-the-Edge processing directly within the module to create intelligent vision sensors. This defends against commoditization from high-volume Chinese players and leverages existing intellectual property in advanced imaging. Invest in certification for automotive and medical grades to secure high-margin, long-lifecycle segments.
For New Entrants and Emerging Players: Specialized industrial integrators in India represent an underserved buyer archetype for customized vision solutions. Target the burgeoning AR/VR headset market with low-latency, multi-camera module designs. A compelling go-to-market angle involves offering integrated hardware-software packages tailored for specific industrial automation tasks in emerging economies.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized module manufacturers in Japan and Germany with deep expertise in industrial inspection or automotive ADAS. The long-term viability of the sector remains strong, driven by pervasive embedded vision needs across industries. Practitioners should monitor AR/VR headset unit sales growth as a key inflection indicator for future demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in next-generation sensor R&D | Secures premium market leadership for advanced imaging features in smartphones and automotive ADAS. |
| Diversify rare earth element sourcing | Mitigates supply chain vulnerability and geopolitical risks for critical optical components. |
| Establish manufacturing capacity in India | Capitalizes on PLI scheme incentives and growing industrial automation demand in the region. |
| Develop AI-on-the-Edge processing capabilities | Transforms modules into intelligent vision sensors for smart home and autonomous drone applications. |
| Pursue strategic partnerships for AR/VR integration | Accelerates market penetration into nascent but high-growth augmented and virtual reality device segments. |
Research Approach
Document review covered technology patent databases, national electronics manufacturing policies from MIIT and METI, corporate financial filings, and trade association reports, complemented by interviews. Primary research engaged mobile device engineers, automotive ADAS developers, industrial automation specialists, and CMOS sensor manufacturers. Both bottom-up market sizing and top-down validation informed the analysis.
The cross-reference approach compares historical market data with expert panel input to construct the forecast. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and regional manufacturing output across the analysis window. Compound annual growth rates were derived from projected shifts in global smartphone shipment volumes and automotive ADAS penetration rates. Industry-specific forecast inputs included industrial robotics deployment figures.
Revisions become necessary when significant geopolitical shifts affecting rare earth element supply or faster-than-expected AR/VR adoption rates materialize. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Practitioners should monitor evolving EU RoHS directives and major OEM procurement shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Microscope Digital Cameras Market
Imaging
SDI Camera Market
Imaging
Machine Vision System Market
Imaging
Industrial Machine Vision Market
Imaging
Global 4K Camera Market
Imaging
Global Document Scanner Market
Imaging
Vision Processing Unit Market
Imaging
Thermal Imaging Systems Market
Imaging
Specific Imaging Solution Market
Imaging
Low-Light Imaging Market
Imaging
Thermal Camera Market
Imaging
Video Microscopes Market
Imaging
Machine Vision Camera Market
Imaging
3D Sensing and Imaging Market