
 Automated Microscopy Market | 2026-2036
Automated Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Microscopy Market Intelligence
Precision optics manufacturing concentration in Japan and Germany is realigning the supply chain for high-resolution components. Carl Zeiss AG leverages its deep expertise in optics to dominate the high-end confocal systems segment. Thermo Fisher Scientific competes by offering integrated workflows from sample preparation to analysis. Olympus Corporation sustains its market position through a strong presence in clinical diagnostics and research laboratories, building on its historical brand strength.
Automated microscopy involves robotic systems that control the microscope stage, focus, and image acquisition, often processing hundreds of samples without manual intervention. Its primary purpose is to accelerate high-throughput screening and quantitative analysis in life sciences and materials research. Slide scanners for digital pathology represent a high-growth product segment, driven by the digitization of histopathology workflows in clinical settings. Within applications, drug discovery commands significant investment due to its intensive use of high-content screening and cell imaging systems.
Regulatory frameworks, including the US FDA's guidelines for digital pathology and Europe's CE marking under the Medical Devices Regulation (MDR), govern the use of these systems in clinical diagnostics. These regulations mandate stringent validation and quality control, shaping product development cycles for manufacturers. Vendor decisions on integrating AI-based image analysis algorithms will determine future competitive differentiation in a crowded field.
Market Dynamics
The primary force shaping the automated microscopy market is the escalating demand for high-throughput quantitative data in life sciences research. This pressure from pharmaceutical drug discovery and academic cell biology is accelerating the integration of robotics and AI into optical systems.
Growth Catalysts
- AI-Powered Analytics:The integration of artificial intelligence for image segmentation and analysis automates previously manual, time-consuming tasks, significantly increasing throughput in high-content screening applications within pharmaceutical research.
- Digital Pathology Adoption:The push to digitize histopathology workflows in clinical diagnostics, supported by FDA guidance in the United States, is driving substantial investment in whole-slide imaging (WSI) systems.
- R&D Investment:Sustained government and private funding for biomedical research in hubs located in Germany and the United States provides the core customer base for advanced, high-value automated microscopy systems.
Market Restraints
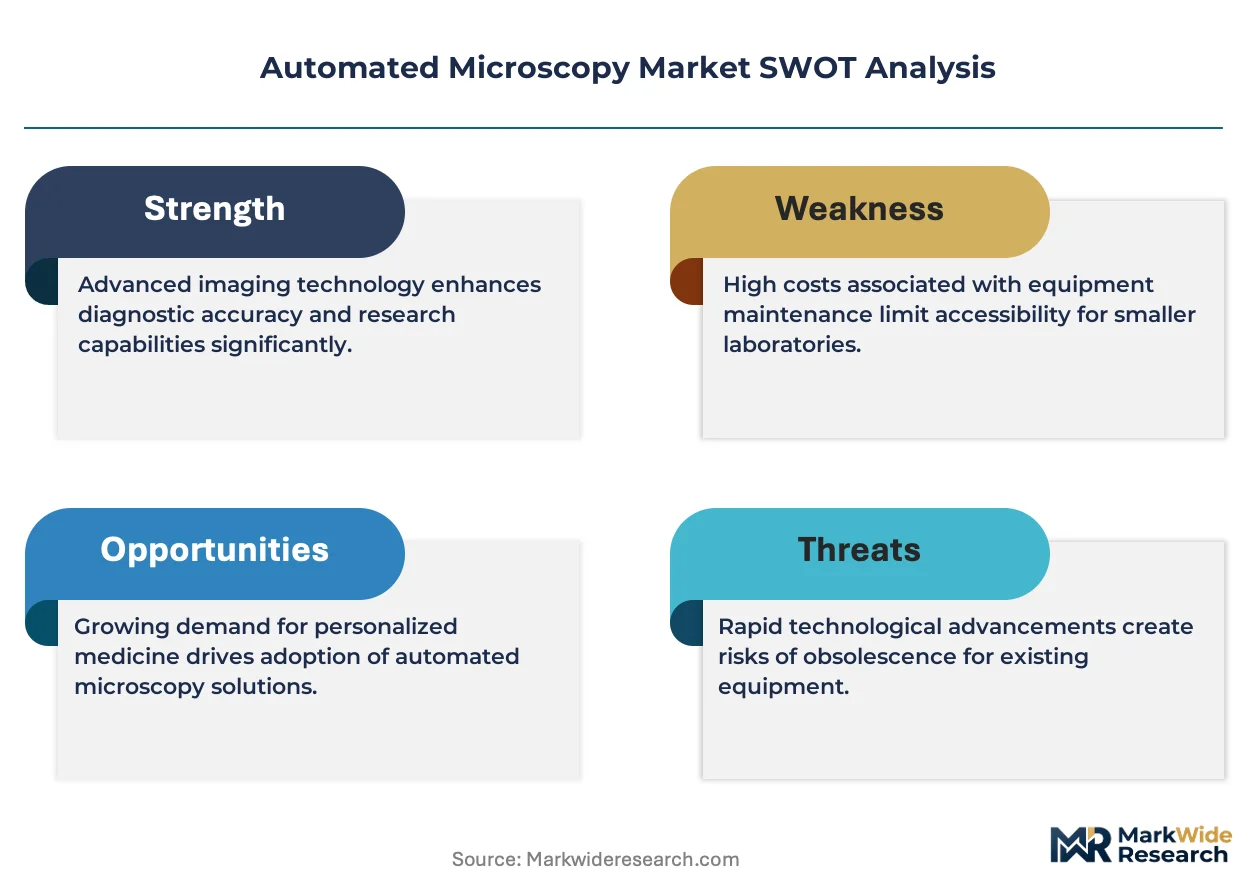
- High Capital Costs:The significant upfront investment required for high-end systems like confocal or live-cell imaging platforms restricts their adoption to well-funded research institutions and large pharmaceutical companies.
- Component Supply Concentration:A reliance on a few specialized manufacturers in Japan and Germany for critical high-precision optics and objective lenses creates potential supply chain vulnerabilities and pricing pressures.
- Data Infrastructure Burden:High-throughput automated imaging generates massive datasets, requiring significant investment in data storage, networking, and high-performance computing infrastructure, which can be a barrier for many labs.
Strategic Opportunities
- Materials Science Applications:Expanding use cases in industrial quality control, such as automated defect detection in semiconductors or composite materials, offer a new growth vector outside of traditional life sciences.
- Clinical Diagnostics in Emerging Markets:There is a significant opportunity for deploying automated slide scanners and simpler systems in countries like India and Brazil as their clinical laboratory infrastructure modernizes.
- Microfluidics Integration:Combining automated microscopy with microfluidic devices enables highly controlled, single-cell analysis experiments, opening new possibilities in genomics, proteomics, and personalized medicine research.
Industry Challenges
- Interdisciplinary Skills Gap:A scarcity of personnel possessing expertise in both cell biology and computational data analysis hinders the effective utilization and troubleshooting of complex automated imaging workflows.
- System Integration Complexity:Integrating automated microscopes with disparate third-party software, robotics, and existing Laboratory Information Management Systems (LIMS) remains a significant technical hurdle for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Microscopy Market |
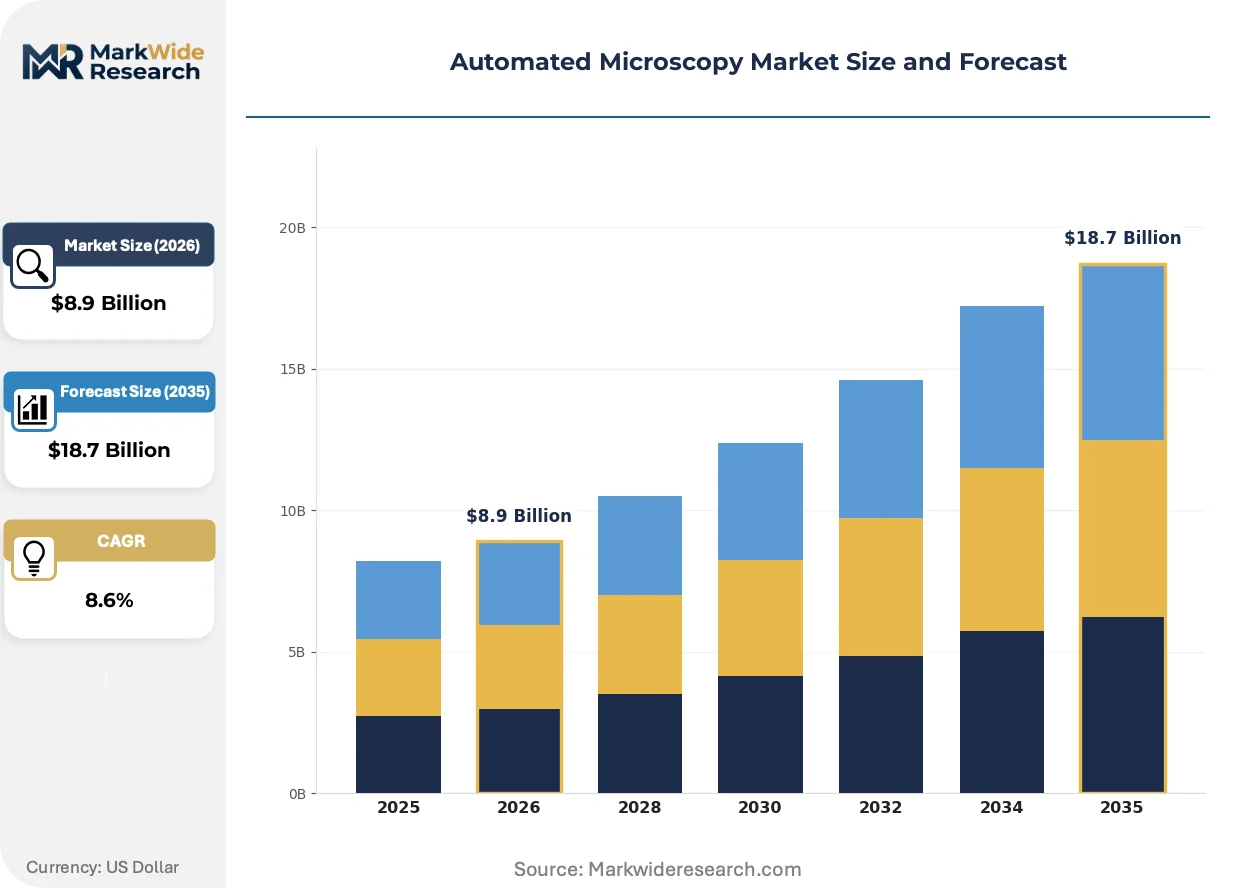
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $18.7 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slide Scanners, Cell Imaging Systems, Digital Microscopes, Fluorescence Microscopes Application: Histopathology, Molecular Biology, Drug Discovery, Clinical Diagnostics End User: Research Laboratories, Academic Institutions, Clinical Laboratories, Pharmaceutical Companies Technology: Confocal Microscopy, Electron Microscopy, Widefield Microscopy, Live Cell Imaging |
| Companies Covered | Agilent Technologies, Bruker Corporation, Carl Zeiss AG, Thermo Fisher Scientific, Hitachi High-Technologies, Olympus Corporation, Nikon Corporation, JEOL Ltd., HORIBA Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Microscopy Market Strategic Shifts & Innovations
The evolution of automated microscopy is defined by a fundamental shift from qualitative imaging to quantitative, data-driven cellular and material analysis. This transformation is powered by advancements in software, enabling systems to function with greater autonomy and analytical depth.
Artificial intelligence for image processing is the core enabling technology. Its primary function is to automate the identification, segmentation, and measurement of features within complex biological images. Pharmaceutical and biotechnology laboratories are the fastest adopters, implementing AI to accelerate high-content screening assays. This software capability is converging with robotic sample handling, creating intelligent platforms that can autonomously execute and optimize multi-day experiments.
Regulatory frameworks are solidifying standards for clinical use, particularly for digital pathology. Europe's Medical Devices Regulation (MDR) and the FDA's guidance in the US create stringent requirements for system validation, data integrity, and quality control. This directly impacts manufacturers of slide scanners and associated software, who must now build in comprehensive audit trails and performance qualification tools to achieve certification for diagnostic applications.
A notable behavioral change is the move toward service-oriented procurement models over direct capital purchases. This trend disrupts the traditional sales cycle for instrument vendors, as contract research organizations and smaller academic labs increasingly prefer reagent-rental or fee-per-sample agreements. The shift is most visible in North American research hubs, where it lowers the barrier to accessing state-of-the-art technology without a large upfront investment.
Automated Microscopy Market Segmentation
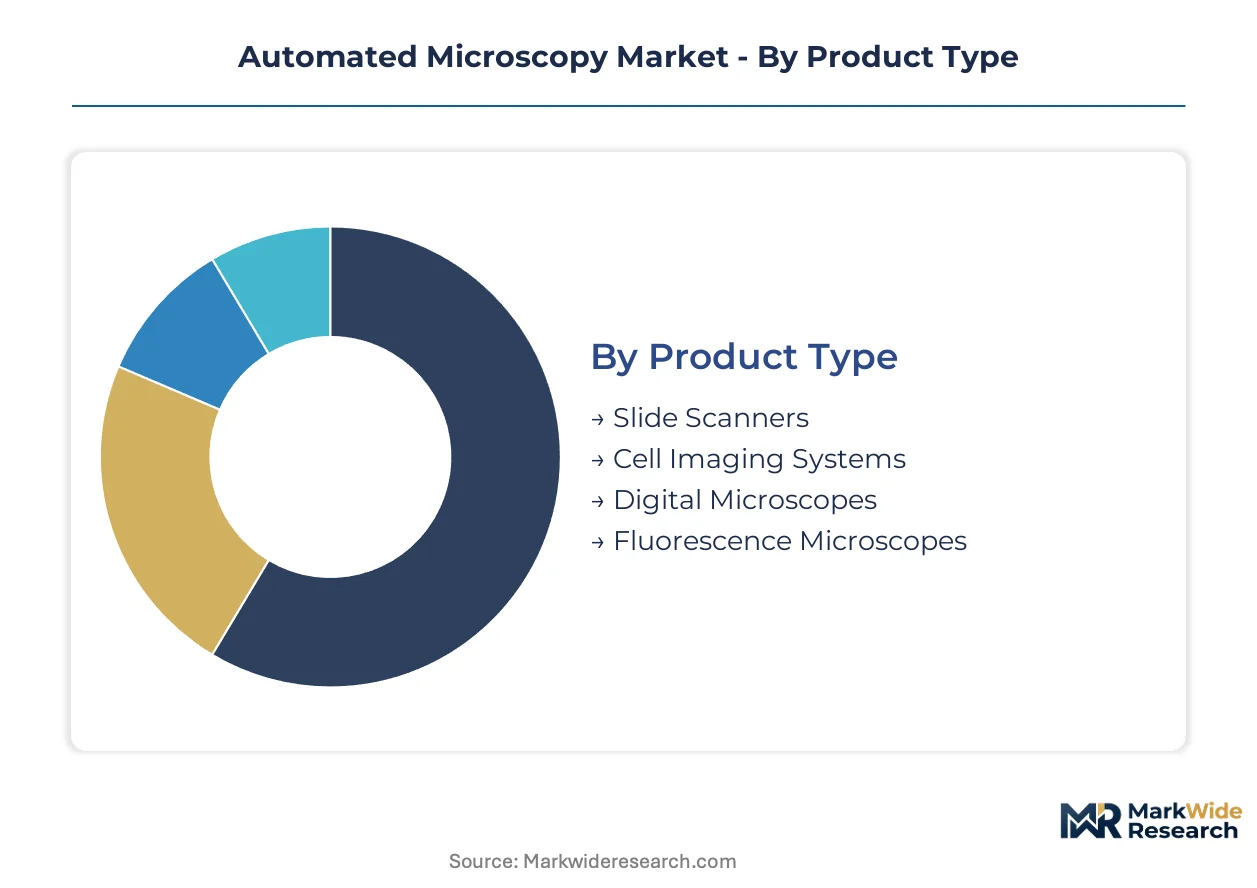
The automated microscopy market segments to reflect diverse technological capabilities and application-specific requirements across research and clinical domains. Understanding these distinctions helps manufacturers tailor product development and service offerings, from standardized high-throughput systems to specialized analytical platforms.
Product Type:
The product type segmentation highlights the balance between highly customized imaging solutions and more standardized, off-the-shelf instruments. Manufacturers develop specific hardware and software configurations to meet varying user needs, ranging from basic observation to complex multi-parametric analysis.
- Slide Scanners:These systems automate the digitization of glass slides, creating high-resolution whole-slide images for digital pathology workflows. Demand concentrates in clinical diagnostics and large research institutions seeking to streamline histopathological analysis and enable remote consultations, driven by regulatory approvals from the US FDA.
- Cell Imaging Systems:These platforms capture dynamic cellular processes, often incorporating live-cell capabilities and advanced analytical software for quantitative analysis. Pharmaceutical companies and academic research laboratories drive demand for these systems, utilizing them for drug discovery, toxicology screening, and fundamental cell biology studies.
- Digital Microscopes:These microscopes integrate digital cameras and software for image capture and basic analysis, replacing traditional eyepieces.
- Fluorescence Microscopes:These instruments use specific wavelengths of light to excite fluorescent molecules within samples, enabling visualization of specific cellular structures or proteins.
Most installed capacity flows through Slide Scanners. Expansion is steepest in Cell Imaging Systems.
Application:
Market application segmentation reveals where automated microscopy systems provide the most significant value, often correlating with the intensity of data generation and analytical complexity. Each application area demands specific features and performance metrics from the imaging platforms.
- Drug Discovery:This segment utilizes automated microscopy for high-content screening, phenotypic assays, and toxicology studies, requiring high throughput and sophisticated image analysis. Pharmaceutical companies invest heavily in these systems to accelerate lead compound identification and optimization.
- Clinical Diagnostics:Automated microscopy supports digital pathology, cytogenetics, and infectious disease diagnostics by digitizing slides and automating sample analysis. The drive for faster, more accurate diagnoses and regulatory compliance, such as Europe's MDR, increases adoption in hospital laboratories.
- Histopathology:This application involves the microscopic examination of tissue sections for disease diagnosis, heavily relying on automated slide scanning for digital workflows.
- Molecular Biology:Researchers in molecular biology use automated systems for gene expression analysis, protein localization studies, and cellular interaction observations.
Demand for Drug Discovery drives significant volume, while Clinical Diagnostics demonstrates rapid growth.
End User:
The end-user segmentation differentiates the market based on organizational structure, funding mechanisms, and specific research or clinical objectives. Each user type possesses distinct procurement patterns and technical requirements for automated microscopy solutions.
- Pharmaceutical Companies:These entities represent major purchasers of high-end automated microscopy systems for drug development, toxicology screening, and quality control. Their substantial R&D budgets allow for investment in advanced, integrated platforms.
- Clinical Laboratories:These facilities adopt automated slide scanners and digital pathology systems to streamline diagnostic workflows and improve turnaround times. Modernization of clinical laboratory infrastructure in countries like India and Brazil creates new opportunities.
- Research Laboratories:Academic and government research laboratories utilize automated microscopes for diverse life science studies, often driven by grant funding.
- Academic Institutions:Universities and colleges integrate automated microscopy into teaching and advanced research programs, focusing on fundamental biological and materials science.
Large-scale procurement from Pharmaceutical Companies defines market volume, with Clinical Laboratories showing emerging demand.
Technology:
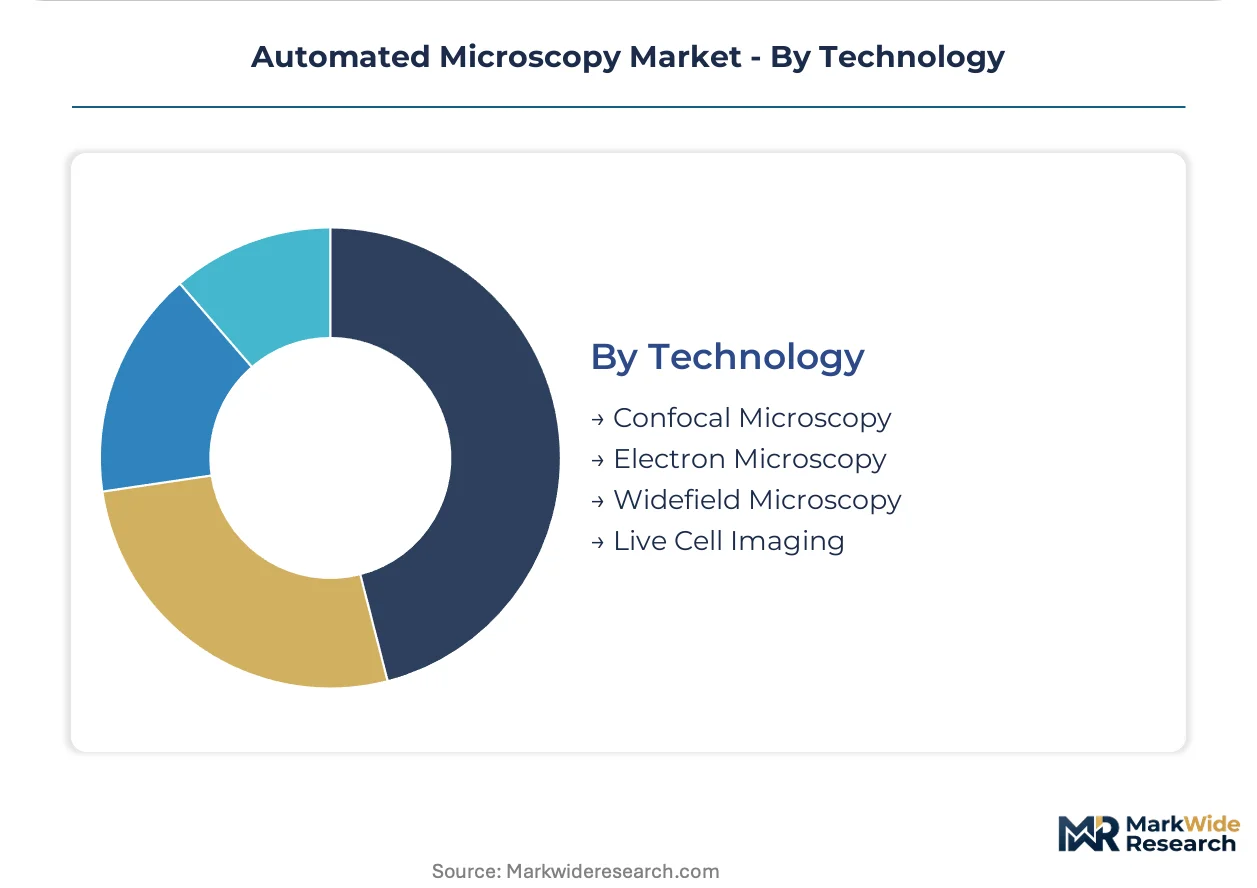
The technology segmentation highlights the diverse imaging principles employed by automated microscopy systems, each offering unique advantages for specific types of samples and analyses. The choice of technology often depends on resolution requirements, sample preparation, and desired depth of penetration.
- Live Cell Imaging:This technology allows for the observation of dynamic biological processes in living cells over extended periods, providing kinetic data on cellular behavior. Advancements in environmental control and image analysis drive its utility in cell biology and drug discovery.
- Confocal Microscopy:These systems provide high-resolution, optical sectioning capabilities by excluding out-of-focus light, ideal for three-dimensional reconstruction of thick biological samples. Carl Zeiss AG leverages its optics expertise in this high-end segment.
- Electron Microscopy:This technique uses electron beams to achieve much higher resolution than light microscopy, suitable for ultrastructural analysis of cells and materials.
- Widefield Microscopy:These systems capture images across a broad field of view, offering a cost-effective solution for basic imaging and high-throughput screening of fixed samples.
Established workflows utilize Widefield Microscopy, as Live Cell Imaging garners increasing investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks significantly influence the investment and manufacturing landscape for automated microscopy, with stringent compliance costs in developed markets sometimes leading to production realignment. This dynamic shapes where advanced systems are developed and deployed, impacting supply chain resilience and market access. Manufacturers navigate diverse regulatory environments, from clinical diagnostics to research applications, seeking efficiency.
United States
Demand for high-throughput screening in drug discovery drives significant investment in automated microscopy systems across the United States. The US FDA's guidance for digital pathology supports the adoption of whole-slide imaging systems in clinical settings. Major biomedical research hubs, including Boston and San Francisco, concentrate both R&D and end-user facilities for these advanced instruments.
Germany
German precision optics producers anchor the high-end segment, leveraging deep engineering expertise to advance confocal and live-cell imaging technologies. Europe's CE marking under the Medical Devices Regulation (MDR) mandates rigorous validation for clinical diagnostic systems, influencing product development cycles. The country's strong academic research institutions and pharmaceutical clusters in regions like Bavaria drive demand for sophisticated microscopy platforms.
Japan
Japan remains a critical hub for the manufacturing of high-precision optical components and objective lenses, essential for advanced automated microscopy. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical devices, ensuring quality and safety standards for clinical applications. Research and development centers in cities like Tokyo and Osaka contribute to innovations in imaging and materials science applications.
India
Modernization of clinical laboratory infrastructure in India creates emerging demand for automated slide scanners and simpler digital microscopy systems. The Central Drugs Standard Control Organization (CDSCO) governs medical device approvals, influencing market entry for manufacturers. Major metropolitan areas such as Mumbai and Bengaluru are experiencing growth in diagnostic services and biomedical research initiatives.
China
China's growing investment in life sciences research and pharmaceutical development fuels demand for automated microscopy, particularly in high-content screening. The National Medical Products Administration (NMPA) oversees the regulation of medical devices, impacting product localization and market access strategies. Industrial and research parks in regions like the Yangtze River Delta actively foster the development and adoption of advanced imaging technologies.
Automated Microscopy Market Key Industry Players
German producers anchor one tier, specializing in high-end optical engineering, while Japanese specialists hold a strong position in precision component manufacturing. The market structure exhibits both consolidation in core technology areas and fragmentation among solution providers integrating various components. Major players pursue strategic partnerships and portfolio diversification to address evolving application needs and expand geographic reach.
Within the high-end optical systems segment, Carl Zeiss AG exemplifies deep expertise in confocal systems, leveraging its heritage in precision manufacturing. Thermo Fisher Scientific competes by offering integrated workflows, spanning from sample preparation to advanced analysis, catering to comprehensive laboratory needs. Olympus Corporation sustains its market presence through a strong focus on clinical diagnostics and research laboratories, building on its historical brand strength and extensive distribution networks.
| Leading Market Players |
|---|
| Agilent Technologies |
| Bruker Corporation |
| Carl Zeiss AG |
| Thermo Fisher Scientific |
| Hitachi High-Technologies |
| Olympus Corporation |
| Nikon Corporation |
| JEOL Ltd. |
| HORIBA Scientific |
| Others |
Cost & Logistics Intelligence
Specialized optics engineering talent concentration in Germany and Japan drives a tiered pricing structure, where labor-cost differentials influence the premium for high-precision components. This dynamic creates a distinct value proposition for systems originating from these advanced manufacturing hubs.
Pricing Analysis
Distributor margin structures significantly impact end-user costs for automated microscopy systems. Value-based pricing dominates for high-end systems like confocal microscopes, reflecting their advanced capabilities and research impact. Price differentiation stems from component quality grades, such as objective lens resolution, and the level of after-sales service and software integration. Pricing pressure stems from increased competition in the digital microscope segment, where basic functionality is commoditizing. Academic institutions often exhibit higher price sensitivity compared to well-funded pharmaceutical companies.
Supply Chain Analysis
CE marking under Europe's MDR and US FDA guidance create significant qualification gating for clinical diagnostic components in the automated microscopy supply chain. Geographic supply concentration for critical high-precision optics rests heavily in Japan and Germany, with some specialized sensor manufacturing in the United States. Raw material dependencies include specialized glass types and rare earth elements for lens coatings. Single-source vulnerability for advanced optical components represents a structural risk. Downstream distribution runs through a mix of direct sales channels for large pharmaceutical clients and specialized distributors for academic and clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated microscopy market presents a margin-expansion story, driven by the increasing shift towards premium live-cell imaging systems and AI-powered analytical software. This evolution allows for higher value capture per system.
For Market Incumbents:
Anticipate continued consolidation through strategic M&A to control key optical component manufacturing and integrate advanced AI software platforms. Invest heavily in R&D for next-generation live-cell imaging technologies to counter emerging software-centric competitors. Develop comprehensive service contracts and data management solutions to address the data infrastructure burden faced by end-users. Regulatory shifts, such as stricter FDA guidelines for AI in diagnostics, pose a threat requiring proactive compliance.
For New Entrants and Emerging Players:
Smaller academic laboratories represent an underserved buyer archetype, seeking flexible, lower-cost access to high-throughput screening technologies. Target modular systems with cloud-based data storage and analysis to reduce upfront capital costs and data infrastructure burden. Offer reagent-rental or fee-per-sample agreements, particularly in North American research hubs, as a compelling go-to-market angle. Focus on specialized applications like microfluidics integration to create niche market entry points.
For Investors and Strategic Acquirers:
Integrated life sciences conglomerates are the most active acquirers in this space, seeking to expand their high-throughput screening and clinical diagnostics portfolios. Long-term viability for automated microscopy remains strong over the next decade, fueled by persistent demand from drug discovery and digital pathology. Target mid-sized software firms specializing in AI-driven image analysis to capture intellectual property and accelerate product differentiation. The signal to watch is the adoption rate of AI-validated digital pathology systems in European clinical settings.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Integration | Enhances image analysis capabilities and automates workflows for pharmaceutical companies. |
| Live-Cell Imaging R&D | Captures dynamic biological processes, crucial for drug discovery and academic research laboratories. |
| Service-Oriented Procurement Models | Lowers entry barriers for smaller academic labs and contract research organizations. |
| Precision Optics Manufacturing Partnerships | Secures supply of critical high-resolution components from Japanese and German specialists. |
| Digital Pathology Regulatory Compliance | Ensures market access for slide scanners in clinical diagnostics under Europe's MDR and US FDA guidance. |
Research Approach
Bottom-up end-user modeling reconciled against top-down OEM tracking forms the analytical core for this market study. Primary interviews with R&D directors, clinical pathologists, and procurement managers in pharmaceutical companies and academic institutions provided qualitative insights. Secondary validation drew from FDA guidance documents, Europe's MDR updates, and annual reports of key optical component manufacturers. This triangulation ensures robust market sizing and trend identification.
An input-output matrix frames the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type, application, end-user, technology, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data analysis and projected demand drivers. Key forecast inputs included R&D spending in life sciences and digital pathology adoption rates.
Underlying measurement precision varies by segment; slide scanners and cell imaging systems carry tighter precision than others due to clearer sales channels. Forecasts reflect assumptions regarding technological advancements and regulatory stability. A model refresh is warranted upon material change in global biomedical research funding or major digital pathology regulatory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Illuminometer Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
HERG Screening Market
Analytical Instruments
Disintegration Analyzer Market