
 Hybrid Imaging Systems Market | 2026-2036
Hybrid Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Imaging Systems Market Foresight
Modular scanner bundling is shifting buyer choice in hybrid imaging systems, as hospitals weigh standalone upgrades against integrated platform replacements. Siemens Healthineers leverages its dual-source CT backbone to dominate PET/CT configurations globally. GE HealthCare anchors its position through in-house radioisotope supply chains that reduce procurement friction. Canon Medical Systems differentiates via detector material science advances that improve signal-to-noise ratios in SPECT/CT systems.
Hybrid imaging systems combine two or more diagnostic modalities into unified hardware platforms, typically merging anatomical imaging with functional or molecular data acquisition through shared patient positioning systems and fused reconstruction algorithms. PET/CT retains the largest installed base among product types due to mature reimbursement pathways and proven oncology workflows, while PET/MRI represents the fastest-expanding segment as cardiac and neurologic applications justify premium capital outlays. Digital imaging technology underpins next-generation platform architectures, though molecular imaging capabilities increasingly determine specialist purchasing decisions at research institutes.
The FDA regulates hybrid systems as Class II or Class III medical devices under 510(k) and PMA pathways, with breakthrough device designations compressing review timelines for novel multimodal combinations. In Europe, the MDR and CE marking requirements impose stricter clinical evidence standards on PET/MRI platforms than predecessor directives, reshaping manufacturer market access strategies. Stakeholders must monitor evolving radioisotope supply security and reimbursement parity between hybrid and sequential scanning protocols to calibrate capital deployment decisions.
Market Dynamics
Radioisotope supply concentration and the FDA's breakthrough device designation pathway are compressing procurement timelines while elevating molecular imaging capabilities as the primary purchasing criterion for academic medical centers.
Growth Catalysts
- Oncology Workflow Integration:PET/CT's mature reimbursement pathways at US academic medical centers create predictable capital recovery cycles. Hospital administrators prioritize platforms with established CPT codes over experimental configurations.
- Breakthrough Device Designation:The FDA's 21st Century Cures Act framework accelerates multimodal system approvals. Manufacturers leverage compressed review timelines to commercialize PET/MRI combinations ahead of European MDR certification.
- Cardiac Application Expansion:German university hospitals anchor research networks validating PET/MRI for myocardial perfusion imaging. Clinical evidence generation in Bavaria and Baden-Württemberg drives procurement decisions across Central European healthcare systems.
Market Restraints
- Molybdenum-99 Supply Volatility:Ageing research reactors in Canada and the Netherlands concentrate technetium-99m production. Shutdown maintenance cycles create diagnostic imaging backlogs that idle SPECT/CT installations.
- MDR Clinical Evidence Burden:Europe's Medical Device Regulation imposes stricter post-market surveillance on PET/MRI platforms than predecessor directives. Small manufacturers face disproportionate compliance costs relative to installed base.
- Sequential Scanning Substitution:Standalone PET followed by separate MRI acquisition achieves comparable diagnostic yield for non-oncologic indications. Payers in cost-sensitive markets reimburse sequential protocols at parity with hybrid examinations.
Strategic Opportunities
- Neurologic Application White Space:Alzheimer's disease biomarker imaging remains underpenetrated in Japan's geriatric care infrastructure. METI funding for dementia diagnostics creates procurement incentives for amyloid-capable PET/MRI configurations.
- Digital Detector Convergence:Solid-state silicon photomultipliers paired with artificial intelligence reconstruction algorithms reduce scan duration. Technology convergence enables outpatient clinic deployment previously restricted to hospital radiology departments.
- Radioisotope Supply Chain Regionalization:India's PLI scheme for medical isotope production attracts cyclotron manufacturers. Domestic technetium-99m generation reduces import dependency for South Asian diagnostic networks.
Industry Challenges
- Multidisciplinary Team Assembly:PET/MRI operation demands simultaneous nuclear medicine technologist and MRI physicist availability. Academic medical centers in secondary cities struggle to recruit dual-qualified personnel.
- Legacy PACS Integration:Hospital information systems require middleware development to fuse PET attenuation correction data with MRI sequences. Vendor-neutral archive compatibility extends implementation timelines.
- Site Planning Complexity:Combined magnetic fringe field and radiation shielding specifications exceed standalone modality requirements. Renovation costs for existing radiology suites often match equipment capital outlay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Imaging Systems Market |
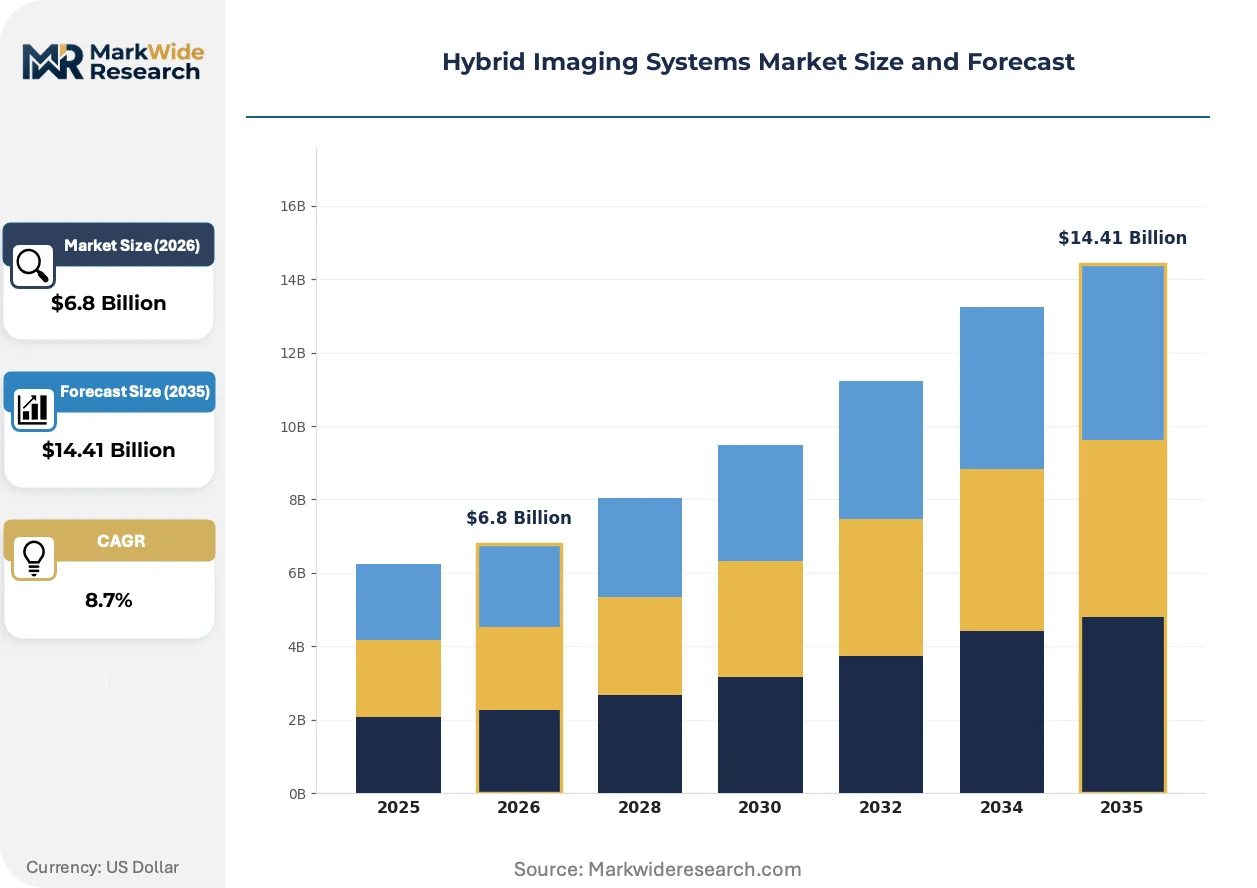
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET/CT, SPECT/CT, PET/MRI, SPECT/MRI Technology: Digital Imaging, Molecular Imaging, Optical Imaging, Ultrasound Imaging End User: Hospitals, Diagnostic Centers, Research Institutes, Imaging Centers Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Canon Medical Systems Corporation, Hitachi Ltd., GE HealthCare, Mediso Ltd., Bruker Corporation, Siemens Healthineers, Shanghai United Imaging Healthcare, MILabs B.V., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Imaging Systems Market Shifts & Advancements
Digital detector architectures and AI-enabled reconstruction are compressing examination duration while regulatory frameworks on both sides of the Atlantic accelerate novel multimodal combinations toward commercialization.
Silicon photomultiplier arrays are unifying gamma-ray detection across PET and SPECT modalities with improved timing resolution and magnetic field immunity. Siemens Healthineers and GE HealthCare have accelerated adoption timelines at European university hospitals seeking to replace vacuum photomultiplier tubes before end-of-service. This solid-state transition is unifying procurement specifications across hybrid imaging categories that previously required distinct detector technologies.
The EU's Medical Device Regulation now mandates clinical performance studies for Class III multimodal systems that predecessor directives addressed through equivalence arguments. Manufacturers must generate prospective data on diagnostic accuracy improvements versus sequential scanning. PET/MRI platforms face the steepest evidence requirements, prompting strategic delays in CE marking applications until cardiac and neurologic outcome studies complete enrollment.
Hospital purchasing committees now require total cost-of-ownership models spanning ten-year operational horizons rather than capital expenditure comparisons alone. Service contract unbundling allows third-party technical service organizations to compete with manufacturer captive service divisions. This behavioral shift is most visible in Germany's university hospital procurement consortia, where shared service agreements across multiple institutions reduce per-site technical staffing requirements.
Hybrid Imaging Systems Market Segmentation
Procurement committees evaluate hybrid imaging platforms through multiple lenses simultaneously. Product configuration determines capital recovery timelines. Application focus shapes detector specification requirements. End-user category dictates service contract complexity.
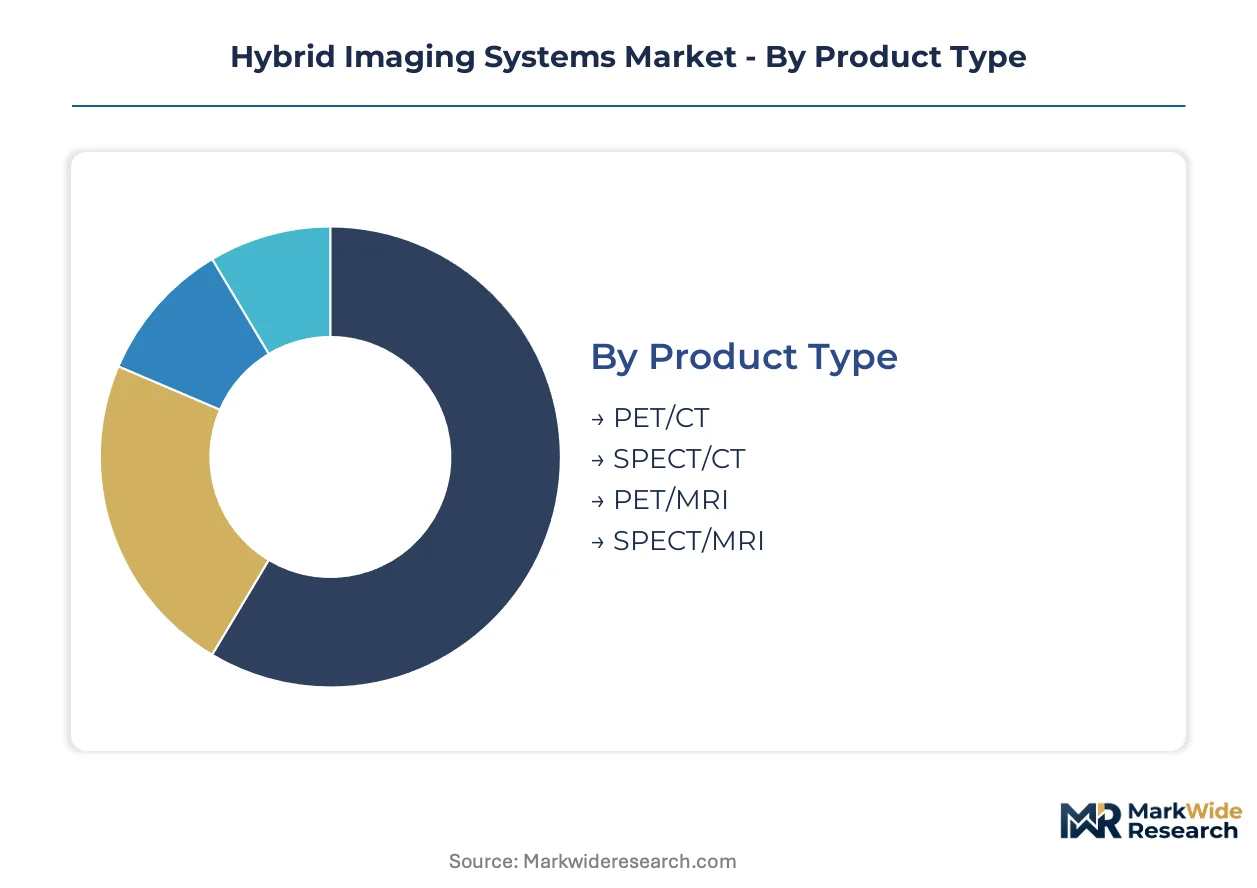
Product Type:
Replacement cycles accelerate as university hospitals phase out first-generation hybrid installations. Digital detector upgrades create upgrade-versus-replace decisions at mid-cycle evaluation points.
- PET/CT:Combines positron emission tomography with computed tomography through shared patient positioning systems and fused attenuation correction algorithms. US academic medical centers anchor procurement volume, driven by established CPT reimbursement codes for oncology staging protocols.
- PET/MRI:Integrates metabolic imaging with magnetic resonance sequences without ionizing radiation from CT-based attenuation correction. German university hospitals in Bavaria and Baden-Württemberg drive demand validation through cardiac perfusion research networks.
- SPECT/CT:Merges single-photon emission computed tomography with anatomical CT for functional imaging at lower isotope cost. Diagnostic networks in India prioritize technetium-99m workflows.
- SPECT/MRI:Combines gamma-ray detection with magnetic resonance imaging for neurologic receptor studies. Research institutes in Japan evaluate configurations for amyloid imaging protocols.
PET/CT sits at the top of the volume ranking, with PET/MRI climbing the fastest.
Technology:
Cost tiers separate premium molecular imaging capabilities from standard anatomical platforms. Detector material science advances widen performance gaps between technology tiers.
- Digital Imaging:Silicon photomultiplier arrays replace vacuum photomultiplier tubes with improved timing resolution and magnetic field immunity. European university hospitals accelerate adoption timelines ahead of end-of-service deadlines for legacy detector systems.
- Molecular Imaging:Radioisotope-dependent functional acquisition determines specialist purchasing decisions at research institutes. Supply chain regionalization in India under the PLI scheme reduces procurement friction for South Asian diagnostic networks.
- Optical Imaging:Near-infrared fluorescence guidance integrates with hybrid platforms for surgical navigation applications.
- Ultrasound Imaging:Photoacoustic combinations enable real-time functional assessment without ionizing radiation exposure.
Digital imaging commands the highest installed base, with molecular imaging gaining share fastest.
End User:
Customer type determines service contract structure and technical staffing requirements. Research institutes demand unbundled service agreements unavailable to smaller diagnostic centers.
- Hospitals:Integrated radiology departments require simultaneous nuclear medicine technologist and MRI physicist availability. Academic medical centers in secondary US cities struggle with dual-qualified personnel recruitment.
- Research Institutes:Prospective clinical outcome studies mandate flexible platform configurations for protocol development. Germany's university hospital procurement consortia share service agreements across multiple institutions.
- Diagnostic Centers:Outpatient clinic deployment depends on compressed examination duration enabled by AI reconstruction algorithms.
- Imaging Centers:Standalone facilities prioritize total cost-of-ownership models spanning ten-year operational horizons.
Hospitals dominate current procurement volume, with research institutes expanding fastest.
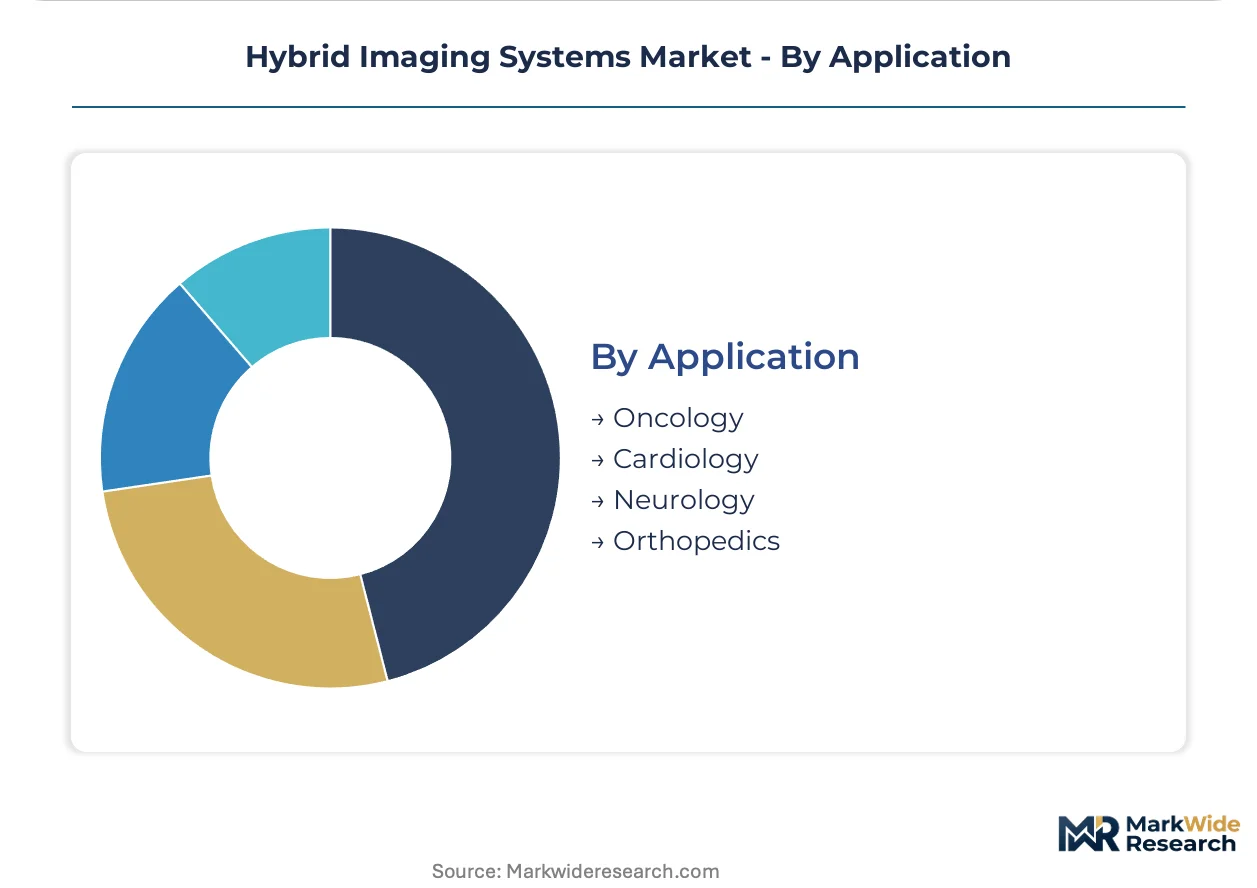
Application:
Maturity levels vary sharply across clinical domains. Oncology workflows carry mature reimbursement pathways unavailable to emerging neurologic indications.
- Oncology:PET/CT staging protocols command established reimbursement at US academic medical centers. Hospital administrators prioritize platforms with proven capital recovery cycles over experimental configurations.
- Cardiology:PET/MRI myocardial perfusion imaging validates through German research networks. Clinical evidence generation in Bavaria drives procurement decisions across Central European healthcare systems.
- Neurology:Alzheimer's disease biomarker imaging remains underpenetrated in Japan's geriatric care infrastructure. METI funding for dementia diagnostics creates procurement incentives.
- Orthopedics:Combined metabolic and structural assessment supports infection detection in prosthetic joint evaluations.
Oncology sits at the top of the volume ranking, with neurology climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hybrid imaging systems industry traces its commercial roots to university hospital consortia in Germany and the United States, where PET/CT platforms first achieved clinical validation during the early 2000s before diffusing into broader diagnostic networks.
United States
Academic medical centers in Boston and Houston anchor procurement volume for PET/CT configurations, driven by established CPT reimbursement codes for oncology staging. The FDA's breakthrough device designation pathway compresses review timelines for novel multimodal combinations. Research networks at MD Anderson and Memorial Sloan Kettering validate cardiac PET/MRI protocols ahead of broader clinical adoption.
Germany
University hospitals in Bavaria and Baden-Württemberg drive European demand validation through myocardial perfusion imaging research consortia. The EU's Medical Device Regulation imposes stricter clinical evidence standards on PET/MRI platforms than predecessor directives. Siemens Healthineers maintains development facilities in Erlangen that supply detector arrays across Central European healthcare systems.
Japan
Geriatric care infrastructure in the Kanto and Kansai regions creates procurement incentives for amyloid-capable PET/MRI configurations targeting Alzheimer's disease biomarker imaging. METI funding for dementia diagnostics accelerates capital deployment timelines. Research institutes in Tokyo and Osaka evaluate SPECT/MRI combinations for neurologic receptor studies.
India
Diagnostic networks in Maharashtra and Karnataka prioritize technetium-99m workflows for SPECT/CT systems serving outpatient oncology staging. The PLI scheme for medical isotope production attracts cyclotron manufacturers seeking domestic technetium-99m generation. Apollo Hospitals and Max Healthcare anchor procurement volume in Delhi-NCR and Mumbai metropolitan clusters.
United Kingdom
NHS England's specialized commissioning frameworks concentrate PET/CT procurement at designated cancer centers in London and Manchester. The MHRA operates post-Brexit regulatory pathways that parallel FDA breakthrough designations for accelerated multimodal approvals. Imperial College London and University College Hospital anchor research networks validating digital detector architectures.
Hybrid Imaging Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detector material science and radioisotope supply chain integration, with consolidated control over silicon photomultiplier arrays and captive isotope production distinguishing tier-one positions from assembly-dependent competitors. The vendor base organizes around three strategic archetypes: diversified health technology conglomerates with in-house isotope capabilities, specialized molecular imaging pure-plays with research institute relationships, and emerging Asian platform manufacturers leveraging cost-advantaged production. Dominant competitive moves include M&A targeting detector technology assets and strategic partnerships securing regional radioisotope supply agreements.
Within the diversified conglomerate tier, Siemens Healthineers and GE HealthCare exemplify premium positioning through integrated hardware-isotope portfolios, while Shanghai United Imaging Healthcare occupies a scale-driven position among Asia-Pacific platform manufacturers. Canon Medical Systems anchors a specialization vector in detector material science advances. These named entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Hitachi Ltd. |
| GE HealthCare |
| Mediso Ltd. |
| Bruker Corporation |
| Siemens Healthineers |
| Shanghai United Imaging Healthcare |
| MILabs B.V. |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
The EU's Medical Device Regulation gates both qualified supply and premium-tier pricing access for hybrid imaging systems, as manufacturers must generate prospective clinical performance studies before CE marking eligibility, while academic medical centers restrict procurement to certified platforms with established reimbursement pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PET/MRI configurations with cardiac validation from oncology-focused PET/CT platforms and refurbished SPECT/CT installations. Price differentiation rests on detector material science certification and after-sales service bundling, with silicon photomultiplier arrays commanding premiums over vacuum photomultiplier tubes. Cost compression in the economy tier is intensifying because India's PLI scheme enables domestic isotope production that undercuts import-dependent service contracts. Diagnostic centers in South Asia exhibit highest price sensitivity, while German university hospital consortia demonstrate lowest sensitivity due to shared service agreements.
Supply Chain Analysis
Single-source vulnerability sits with ageing research reactors in Canada and the Netherlands that concentrate technetium-99m production for SPECT/CT systems. Component sourcing draws from Germany for detector arrays, the United States for MRI magnet assemblies, and Japan for silicon photomultiplier substrates. Tariff exposure on radioisotope imports threatens margin stability for European diagnostic networks. Distribution runs through manufacturer-direct sales teams serving academic medical centers, with third-party technical service organizations penetrating mid-tier hospital accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's breakthrough device designation pathway compounds demand acceleration for multimodal systems, compressing procurement timelines as academic medical centers prioritize platforms with accelerated regulatory clearance.
For Market Incumbents: Lock in radioisotope supply chain control through backward integration into cyclotron manufacturing or long-term offtake agreements with India's PLI scheme beneficiaries. Siemens Healthineers and GE HealthCare should extend silicon photomultiplier replacement programs ahead of European end-of-service deadlines, neutralizing emerging Asian detector manufacturers. Certification investment in cardiac PET/MRI protocols represents the critical defensive lever against research institute defections to specialized molecular imaging pure-plays. For New Entrants and Emerging Players: Direct-to-research-institute digital sales channels bypass manufacturer-captive service divisions that dominate hospital procurement. Amyloid-capable PET/MRI configurations for Japan's geriatric care infrastructure offer the most penetrable white space, given METI funding availability and limited domestic competition. Outpatient diagnostic centers seeking compressed examination duration present a secondary entry vector through AI reconstruction algorithm partnerships. For Investors and Strategic Acquirers: Roll-up economics work for specialized molecular imaging pure-plays because the EU's MDR imposes disproportionate compliance costs that force small manufacturers toward acquisition. The five-to-ten year viability window favors platforms with demonstrated cardiac or neurologic outcome data over oncology-saturated PET/CT configurations. Acquisition targets should demonstrate unbundled service agreement traction with German university hospital consortia. The signal to monitor is FDA breakthrough designation grants for novel multimodal combinations, which precede capital deployment surges at academic medical centers.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Device Designation Pursuit | FDA's compressed review timelines accelerate commercialization ahead of European MDR certification requirements. |
| Radioisotope Supply Chain Regionalization | India's PLI scheme attracts cyclotron manufacturers seeking domestic technetium-99m generation capacity. |
| Digital Detector Architecture Migration | Solid-state silicon photomultiplier adoption unifies procurement specifications across hybrid imaging categories. |
| Hospital System Partnership Development | Shared service agreements across German university hospital consortia reduce per-site technical staffing requirements. |
| Software Companion Development | AI reconstruction algorithms enable outpatient clinic deployment previously restricted to hospital radiology departments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with nuclear medicine technologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) and PMA filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up installation base modeling and top-down market sizing triangulated volume estimates across product configurations.
Historical reference periods anchored the projection horizon to replacement cycle patterns and regulatory approval timelines, with segmentation modeling across product type, technology tier, application focus, and end-user category. CAGRs derived from fitted growth curves incorporating radioisotope supply volatility assumptions and reimbursement pathway maturity differentials. Forecast inputs included detector technology transition rates and academic medical center capital expenditure survey responses.
The model assumes a particular technology adoption path; alternative pathways for solid-state detector migration would alter the outlook. Forecasts reflect assumptions regarding MDR enforcement consistency and breakthrough designation grant rates. Radioisotope reactor maintenance schedules and payer reimbursement parity decisions constitute revision triggers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Machine Vision System Market
Imaging
North America IP Camera Market
Imaging
Instant Digital Cameras Market
Imaging
Automotive Compact Camera Module Market
Imaging
Europe Image Sensors Market
Imaging
Electron Microscopy Market
Imaging
Photo Kiosk Market
Imaging
Micro Computed Tomography Market
Imaging
North America Image Sensors Market
Imaging
Industrial Machine Vision Market
Imaging
Mobile Imaging Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Wearable IP Camera Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Global Digital Binoculars Market
Imaging
Whole Slide Imaging Systems Market