
 Network Tester Market | 2026-2036
Network Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Network Tester Market Outlook
Aftermarket service revenue is tilting toward calibration and firmware subscription models as hardware margins compress. Keysight Technologies leverages its in-house semiconductor fabrication to control test module supply chains. Fluke Networks anchors its position through channel density in enterprise IT procurement. EXFO Inc. specializes in optical layer validation for fiber-dense metro networks.
A network tester is an electronic instrument that generates, captures, and analyzes traffic packets across physical and virtual network layers, typically operating from Layer 1 through Layer 7 with port speeds from 1 Gbps to 800 Gbps. Its primary purpose is to certify network performance, isolate faults, and validate security postures before production deployment. Portable testers capture the largest volume share due to field technician mobility requirements, while rack-mounted testers command premium pricing in hyperscale data center qualification labs. Ethernet technology dominates unit shipments, though fiber optics segments expand fastest where coherent DSP upgrades strain existing test infrastructure.
The FCC enforces equipment authorization rules that mandate electromagnetic compatibility testing for all network connectivity devices sold in the United States. The EU Cybersecurity Act and CE marking requirements under the Radio Equipment Directive create parallel compliance pathways for vendors accessing European telecom procurement. China's MIIT issues network access licenses that require domestic type approval testing. Stakeholders must monitor divergence between national certification regimes when planning modular test platform roadmaps.
Market Dynamics
800 Gbps port speeds are fragmenting test equipment architectures as coherent DSP validation demands outpace legacy chassis upgrade paths, forcing vendors to modularize optical and electrical test functions.
Growth Catalysts
- 5G Backhaul Expansion:Telecom operators in Germany and China are deploying massive MIMO infrastructure that requires field-portable Layer 1-7 validation tools for fiber-to-the-antenna links.
- FCC Broadband Labeling Rules:The FCC's mandated performance disclosure requirements for internet service providers are creating compliance-driven refresh cycles for throughput measurement equipment.
- Smart Manufacturing Investments:Industrial automation networks in the United States are adopting time-sensitive Ethernet test protocols to certify deterministic latency for robotic control systems.
Market Restraints
- GaAs and InP Component Concentration:Specialized III-V semiconductor foundries in Taiwan and Japan create single-source dependencies for high-frequency test module substrates.
- EU Cybersecurity Act Certification Friction:The CE marking pathway under RED now requires third-party cybersecurity assessment, extending type approval timelines by 4-6 months for modular platforms.
- Software-Defined Radio Substitution:Open-source test signal generation libraries on commodity hardware are capturing low-complexity Layer 2-3 validation workloads from purpose-built instruments.
Strategic Opportunities
- India Smart Cities Mission:Municipal fiber backbone deployments under the Ministry of Housing and Urban Affairs mandate are creating demand for ruggedized OTDR and Ethernet combo testers.
- AI-Driven Predictive Maintenance:Convergence of machine learning inference at the network edge with continuous performance telemetry is enabling subscription-based tester fleet optimization services.
- Data Center Interconnect Buildouts:Hyperscale cloud providers in Northern Virginia and Frankfurt are qualifying 400ZR coherent pluggable optics, requiring new polarization multiplexing test capabilities.
Industry Challenges
- Multi-Gigabit SerDes Validation Expertise:The scarcity of engineers proficient in PAM4 signal integrity analysis is constraining R&D throughput for 112 Gbps lane test modules.
- Legacy Chassis Integration Complexity:Backward compatibility requirements with 15-year-old mainframe architectures are consuming 30-40% of firmware development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Tester Market |
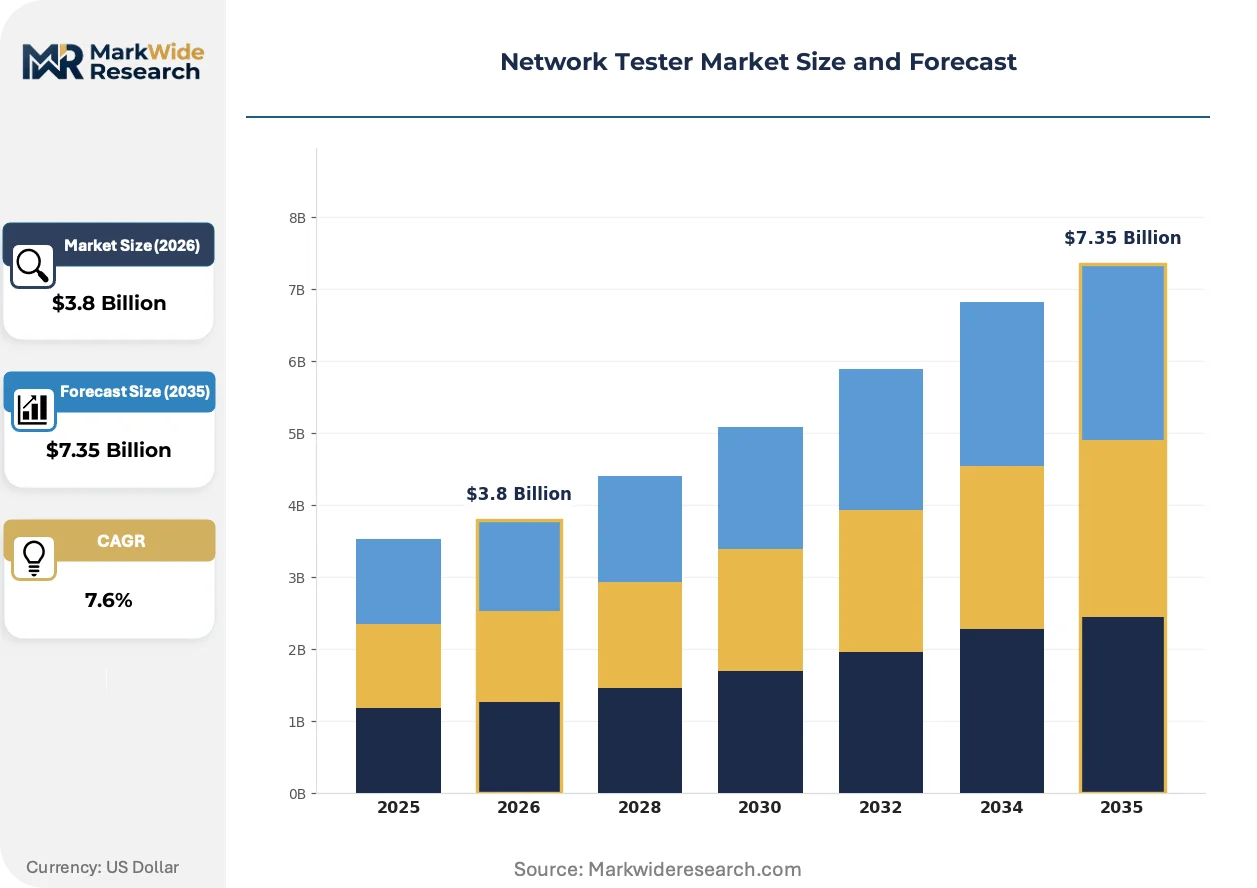
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Rack-mounted Testers, Bench Testers, Optical Testers Technology: Ethernet, Wi-Fi, Fiber Optics, Bluetooth End User: Telecom Operators, IT Departments, Network Installers, Managed Service Providers Application: Network Configuration, Fault Diagnosis, Performance Monitoring, Security Testing |
| Companies Covered | Keysight Technologies, Fluke Networks, EXFO Inc., VIAVI Solutions Inc., Rohde & Schwarz, Anritsu Corporation, Spirent Communications, NetScout Systems, Tektronix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Tester Market Strategic Shifts
Test instrumentation architectures are bifurcating between cloud-native analytics platforms and edge-resident capture engines, with virtualization layers decoupling measurement hardware from analysis software.
Coherent optical test modules are hybridizing electrical and photonic subsystems within single field-replaceable units. Metro network operators in Japan and South Korea are deploying these converged instruments to validate both client-side Ethernet and line-side DWDM performance without chassis swaps. This consolidation is compressing capital equipment footprints at fiber splice points while extending calibration intervals through shared reference clock architectures.
The EU Cybersecurity Act's Common Criteria certification pathway is mandating hardware security module integration for test equipment handling encrypted traffic analysis. Equipment vendors accessing European telecom procurement must now embed tamper-resistant key storage and attestation capabilities. This requirement is most acute in Germany, where Bundesnetzagentur type approval now rejects test platforms lacking EAL4+ rated secure enclaves.
Enterprise IT procurement teams are unbundling hardware acquisition from calibration and firmware entitlement contracts. Value-added distributors in the United States are capturing recurring revenue streams through multi-year service agreements that decouple initial capital outlays from ongoing compliance verification. This shift is most visible in healthcare and financial services verticals, where Joint Commission and FFIEC audit requirements mandate documented test equipment traceability.
Network Tester Market Segmentation
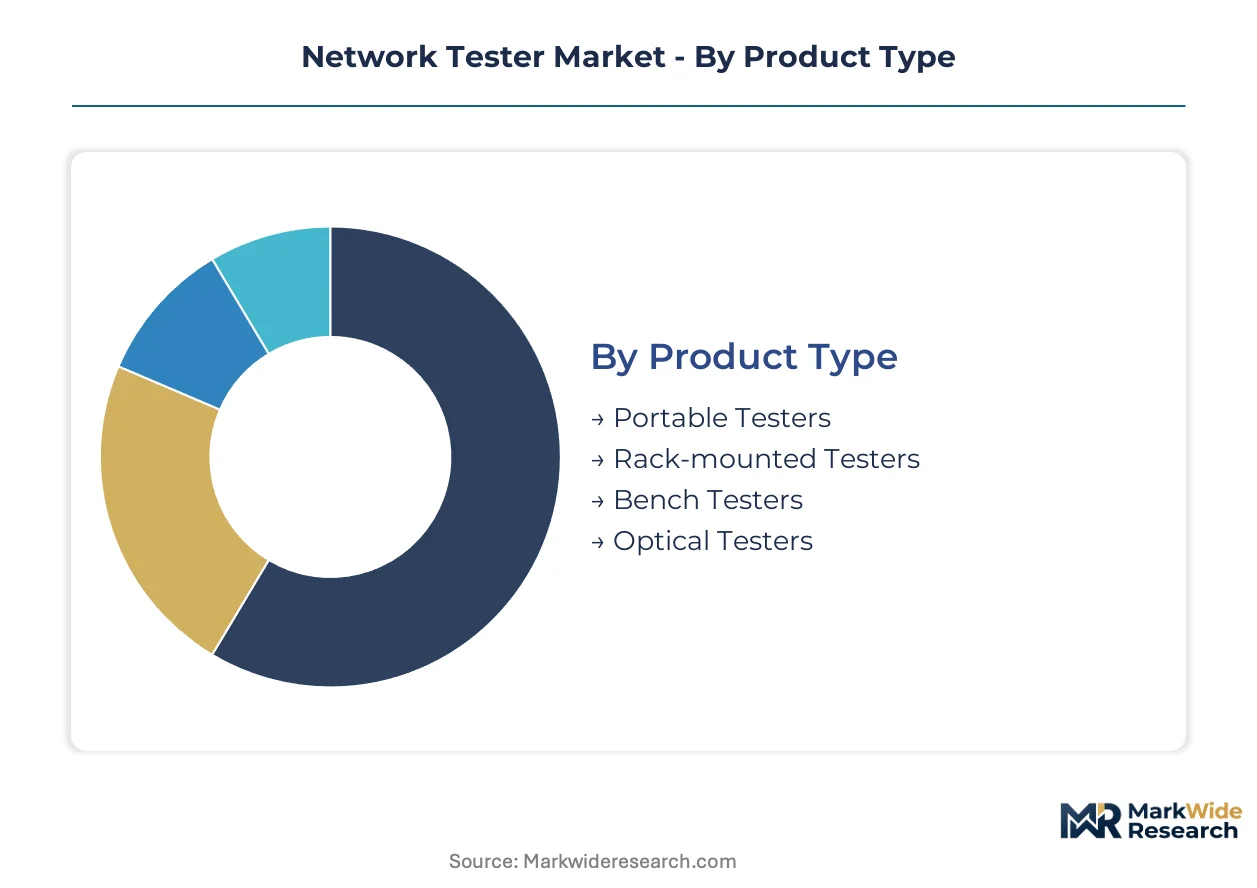
Network tester segmentation reveals divergent hardware architectures and validation protocols across deployment environments. Product form factors, underlying transmission technologies, and end-user operational models each create distinct procurement patterns and service lifecycle requirements.
Product Type:
Cost tier differentiation separates field-deployable units from capital-intensive lab infrastructure, with pricing spanning an order of magnitude between entry-level portable units and multi-slot chassis systems.
- Portable Testers:Battery-powered handheld instruments integrate Layer 1-7 traffic generation with touchscreen analytics for technician mobility. Telecom field crews in Germany and China deploy these for 5G fiber-to-the-antenna validation where truck rolls demand rapid fault isolation.
- Rack-mounted Testers:Modular chassis systems accommodate hot-swappable optical and electrical test modules for hyperscale data center qualification labs. Northern Virginia cloud facilities utilize these for 400ZR coherent pluggable certification where port density justifies premium positioning.
- Bench Testers:Laboratory-grade instruments with precision calibration references serve R&D environments and manufacturing test floors.
- Optical Testers:OTDR and power meter combinations address fiber characterization requirements in metro network buildouts.
Portable testers hold installed capacity. Rack-mounted testers are rotating up the share rankings.
Technology:
Application requirements dictate physical layer selection, with copper-based validation dominating unit volume while photonic test functions command premium pricing.
- Ethernet:Dominates shipment volumes across 1 Gbps to 800 Gbps port speeds with PAM4 signal integrity validation. Enterprise IT departments in the United States standardize on these for time-sensitive Ethernet certification in smart manufacturing deployments.
- Fiber Optics:Coherent DSP validation for DWDM and ZR pluggable optics expands fastest where metro network upgrades strain existing test infrastructure. Japan and South Korea operators deploy converged electrical-photonic modules to compress equipment footprints at fiber splice points.
- Wi-Fi:Supports enterprise WLAN deployment and residential broadband installation verification.
- Bluetooth:Addresses IoT device certification and short-range wireless protocol validation in industrial automation settings.
Ethernet maintains volume leadership. Fiber optics is climbing the fastest in revenue contribution.
End User:
Customer type determines procurement channel and service contract structure, with enterprise IT favoring distributor relationships while carriers direct-source from manufacturers.
- Telecom Operators:Drive 5G backhaul and fiber-to-the-home deployment cycles with multi-year fleet refresh programs. FCC broadband labeling rules in the United States mandate performance disclosure capabilities that shape their throughput measurement equipment specifications.
- IT Departments:Healthcare and financial services verticals prioritize documented test equipment traceability for Joint Commission and FFIEC audit compliance, favoring subscription-based calibration entitlements.
- Network Installers:Independent contractors and contractor fleets require ruggedized instruments for outdoor plant construction and turn-up services.
- Managed Service Providers:Multi-tenant infrastructure operators seek cloud-native analytics integration for distributed network monitoring.
Telecom operators hold installed capacity. IT departments are rotating up the share rankings.
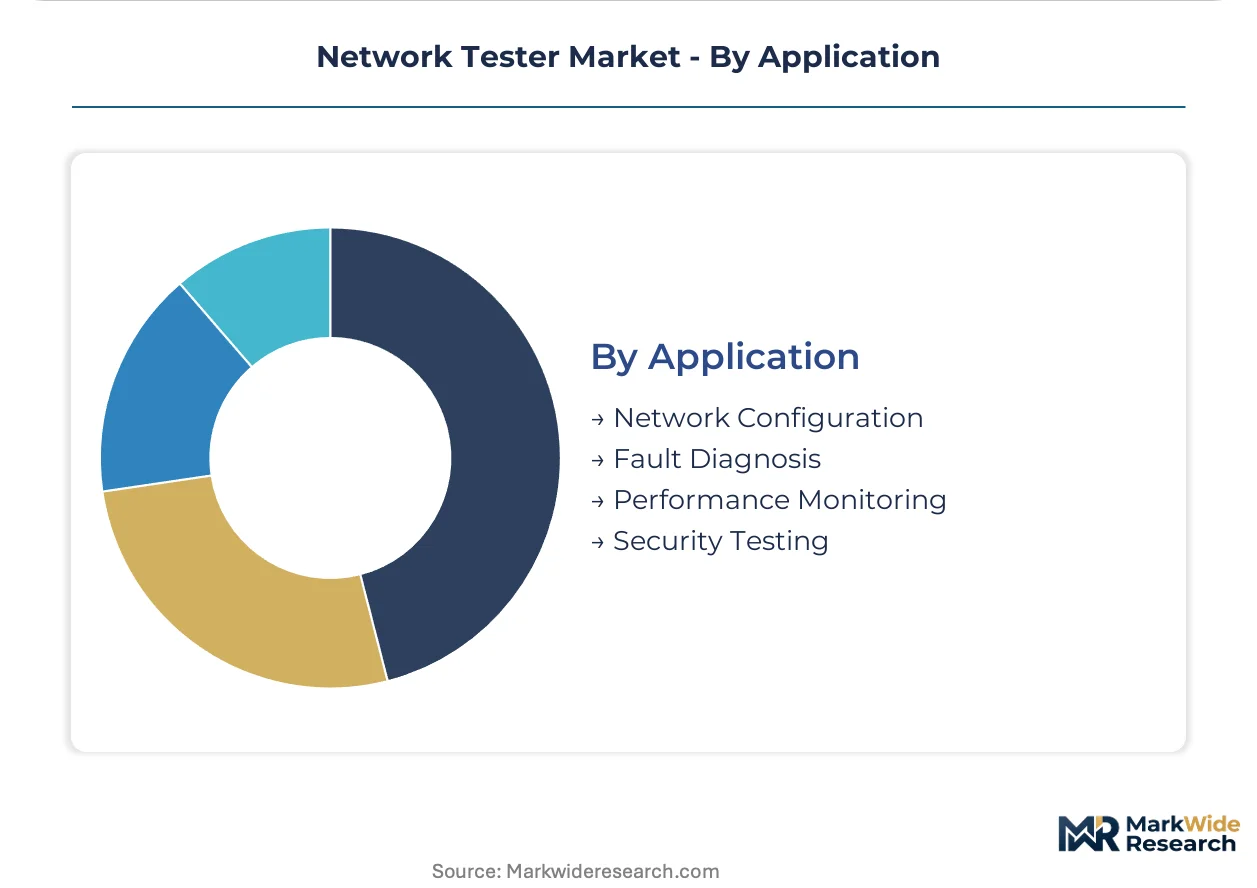
Application:
Functional use case segmentation aligns with network lifecycle phases, from initial deployment through ongoing operational assurance.
- Network Configuration:Baseline performance establishment and protocol compliance verification precede production handoff. EU Cybersecurity Act Common Criteria certification now mandates hardware security module integration for encrypted traffic analysis in European deployments.
- Fault Diagnosis:Real-time isolation of physical layer impairments and protocol anomalies minimizes mean-time-to-repair. Field technicians in India Smart Cities Mission deployments utilize OTDR-Ethernet combo testers for municipal fiber backbone troubleshooting.
- Performance Monitoring:Continuous telemetry collection supports SLA verification and capacity planning.
- Security Testing:Penetration testing and vulnerability assessment functions validate network posture against evolving threat landscapes.
Network configuration holds installed capacity. Security testing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
III-V semiconductor foundries in Taiwan and Japan concentrate supply for high-frequency test module substrates, creating geographic dependencies that shape procurement strategies across deployment regions. The FCC, EU Cybersecurity Act, and China's MIIT establish divergent certification pathways that vendors must navigate. Demand clusters in specific metro markets where data center construction and telecom infrastructure investments accelerate.
United States
Hyperscale cloud providers in Northern Virginia and Dallas-Fort Worth are qualifying 400ZR coherent pluggable optics, driving demand for polarization multiplexing test capabilities. The FCC's broadband labeling rules mandate performance disclosure requirements for internet service providers, creating compliance-driven refresh cycles for throughput measurement equipment. Healthcare and financial services verticals in New York and Chicago prioritize documented test equipment traceability for Joint Commission and FFIEC audit compliance.
Germany
Telecom operators deploy massive MIMO infrastructure requiring field-portable Layer 1-7 validation tools for fiber-to-the-antenna links across industrial corridors. The Bundesnetzagentur now rejects test platforms lacking EAL4+ rated secure enclaves under EU Cybersecurity Act Common Criteria certification pathways. Manufacturing automation networks in Bavaria and Baden-Württemberg adopt time-sensitive Ethernet test protocols to certify deterministic latency for robotic control systems.
China
MIIT network access licenses require domestic type approval testing for all equipment deployed in 5G backhaul and fiber-to-the-home buildouts. Smart manufacturing investments in the Yangtze River Delta and Pearl River Delta accelerate adoption of industrial Ethernet validation tools. Metro network operators in Beijing and Shanghai deploy converged electrical-photonic modules to compress equipment footprints at fiber splice points.
Japan
METI industrial policy supports coherent DSP validation infrastructure upgrades as metro networks transition to 800 Gbps port speeds. Operators in Tokyo and Osaka deploy hybridized optical test modules that validate both client-side Ethernet and line-side DWDM performance without chassis swaps. Shared reference clock architectures in these converged instruments extend calibration intervals at fiber splice points.
India
The Ministry of Housing and Urban Affairs Smart Cities Mission mandates municipal fiber backbone deployments, creating demand for ruggedized OTDR and Ethernet combo testers. Field technicians in Delhi and Mumbai utilize these instruments for outdoor plant construction and turn-up services. Independent contractor fleets require battery-powered handheld units that integrate Layer 1-7 traffic generation with touchscreen analytics.
Network Tester Market Competitive Environment
Test equipment specialists and diversified electronic measurement firms split the market between purpose-built validation platforms and modular multi-application chassis systems. The vendor base concentrates around three strategic archetypes: semiconductor-integrated manufacturers controlling module supply chains, channel-anchored enterprises with dense IT procurement relationships, and optical-layer specialists serving fiber-dense metro networks. Competitive moves center on modular platform roadmaps that accommodate divergent national certification regimes and subscription-based service contracts that decouple hardware acquisition from ongoing calibration entitlements.
Among diversified measurement and communications test specialists, Keysight Technologies, Fluke Networks, and EXFO Inc. occupy distinct archetype positions. Keysight exemplifies the semiconductor-integrated manufacturer archetype through in-house fabrication capabilities. Fluke Networks represents the channel-anchored enterprise model with established procurement relationships. EXFO sits within the optical-layer specialist tier serving fiber-dense infrastructure deployments. These three companies illustrate how vendor strategies diverge across hardware margin compression, firmware subscription transitions, and calibration service bundling.
| Leading Market Players |
|---|
| Keysight Technologies |
| Fluke Networks |
| EXFO Inc. |
| VIAVI Solutions Inc. |
| Rohde & Schwarz |
| Anritsu Corporation |
| Spirent Communications |
| NetScout Systems |
| Tektronix Inc. |
| Others |
Value Chain & Pricing Dynamics
GaAs and InP substrate dependencies in Taiwan and Japan determine both pricing tier spreads and supply chain shape, compressing margins on high-frequency test modules while forcing vendors toward modular architectures that accommodate divergent national certification timelines.
Pricing Analysis
The EU Cybersecurity Act dictates the pricing tier structure through its Common Criteria certification pathway, which mandates hardware security module integration and EAL4+ rated secure enclaves for European telecom procurement. Three-tier pricing structure across premium, standard, and economy levels separates chassis systems with embedded security modules from field-portable units and open-source SDR alternatives. Cost compression in the standard tier is intensifying because software-defined radio substitution captures low-complexity Layer 2-3 validation workloads. Enterprise IT departments demonstrate highest price sensitivity due to unbundled hardware acquisition models, while hyperscale data center operators show lowest sensitivity given 400ZR coherent pluggable qualification requirements.
Supply Chain Analysis
Extended payment terms from Taiwanese and Japanese III-V semiconductor foundries strain working capital for test module manufacturers assembling chassis systems in the United States and Germany. Supply concentration in Taiwan, Japan, and the United States creates single-source vulnerability for GaAs and InP substrates essential to 112 Gbps lane test modules. Raw material dependencies center on specialized semiconductor wafers, precision optical components, and high-speed SerDes integrated circuits. Distribution runs through value-added distributors capturing recurring revenue streams via multi-year calibration and firmware entitlement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
800 Gbps coherent DSP validation demands are fragmenting test equipment architectures faster than legacy chassis upgrade paths can accommodate, creating a high-growth disruption window for vendors with modular platform roadmaps.
For Market Incumbents: Entrench position through backward integration into III-V semiconductor substrate supply chains, reducing dependency on Taiwanese and Japanese foundries while accelerating 112 Gbps lane module R&D throughput. Lock in channel density across enterprise IT procurement relationships before software-defined radio substitution erodes low-complexity validation margins. Prioritize firmware subscription transitions that decouple initial capital outlays from ongoing compliance verification. For New Entrants and Emerging Players: Establish a beachhead in India's Smart Cities Mission municipal fiber backbone deployments, where ruggedized OTDR-Ethernet combo testers face limited incumbent presence and price-sensitive procurement by independent contractor fleets. Target cloud-native analytics integration for managed service providers seeking distributed network monitoring capabilities. Pursue white-label partnerships with value-added distributors already entrenched in healthcare and financial services verticals. For Investors and Strategic Acquirers: The market sits at a modularization phase that favors optical-layer specialists with coherent DSP validation expertise and established European cybersecurity certification pathways. Long-term viability hinges on subscription-based service contract penetration rather than hardware shipment volumes. Monitor divergence between FCC broadband labeling rules and EU Cybersecurity Act certification timelines as the primary inflection indicator for platform consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Roadmap Development | Accommodates 800 Gbps port speed fragmentation and divergent national certification regimes. |
| Subscription-Based Service Contract Transition | Captures recurring revenue from healthcare Joint Commission and FFIEC audit compliance requirements. |
| Coherent DSP Validation Capability Buildout | Addresses 400ZR pluggable optics qualification demands from Northern Virginia and Frankfurt hyperscalers. |
| Hardware Security Module Integration | Satisfies Bundesnetzagentur EAL4+ requirements under EU Cybersecurity Act Common Criteria pathways. |
| India Distribution Channel Expansion | Positions for Ministry of Housing and Urban Affairs Smart Cities Mission municipal fiber deployments. |
Study Parameters
Initial hypotheses were tested against primary input from test equipment product managers, telecom operator network engineering directors, data center qualification lab managers, and value-added distributor sales executives and refined through secondary validation against FCC equipment authorization databases, EU Cybersecurity Act Common Criteria certification registries, and MIIT network access license filings. Bottom-up triangulation of port speed adoption curves and top-down reconciliation with hyperscaler capex disclosures anchored volume and value estimates.
Demand-supply balance across the projection horizon was modeled through segmented analysis by product form factor, transmission technology, end-user procurement channel, and application lifecycle phase. CAGRs were derived from installed base refresh cycles, 5G backhaul deployment trajectories, and smart manufacturing Ethernet validation adoption patterns. Forecast inputs incorporated coherent DSP upgrade roadmaps, fiber-to-the-home buildout schedules, and regulatory compliance timeline divergence.
Stress conditions across III-V semiconductor substrate availability, EU Cybersecurity Act certification friction, and software-defined radio substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about modular platform upgrade compatibility and subscription service attach rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
North America Automated Test Equipment Market
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Oscilloscope Market