
 Global CBCT/Cone Beam Imaging Market | 2026-2036
Global CBCT/Cone Beam Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global CBCT/Cone Beam Imaging Market Foresight
The gap between premium imaging systems and entry-level cone beam units is rebalancing as flat panel detector costs drop and software differentiation becomes the primary margin lever. VATECH Co., Ltd. leverages its Korean manufacturing base to dominate price-sensitive Asian markets. Danaher Corporation sustains premium positioning through integrated workflow software that locks in dental clinic loyalty. Planmeca Oy anchors Nordic market share with compact footprint designs suited for high-rent urban practices.
Cone beam computed tomography captures volumetric anatomical data using a rotating X-ray source and flat panel detector, producing sub-millimeter resolution 3D reconstructions with radiation doses substantially lower than conventional CT. Dental CBCT commands the largest installed base while orthopedic CBCT grows fastest as weight-bearing extremity scanning gains traction in sports medicine practices. Flat panel detector technology leads unit economics due to falling amorphous silicon substrate costs, though CMOS detectors are displacing legacy CCD architectures in price-sensitive segments.
The FDA's 510(k) clearance framework shapes US market access timelines, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on new CBCT entrants. Japan's PMDA maintains rigorous radiation safety protocols that filter out lower-tier manufacturers. Stakeholders must monitor how AI-integrated reconstruction algorithms reshape regulatory classification boundaries and service revenue models.
Market Dynamics
Flat panel detector cost deflation and AI-embedded reconstruction software are compressing hardware margins while elevating software and service revenue streams across the CBCT value chain.
Growth Catalysts
- Implant dentistry volume:South Korean and Japanese dental clinics are expanding CBCT installations for pre-surgical planning, creating sustained equipment refresh cycles.
- FDA 510(k) pathway:The streamlined clearance framework accelerates new cone beam device entry into the US market, reducing time-to-revenue for manufacturers.
- Amorphous silicon substrates:Falling substrate costs for flat panel detectors are democratizing access to mid-range imaging systems across price-sensitive Asian markets.
Market Restraints
- CMOS detector transition costs:Legacy CCD architecture obsolescence forces capital-intensive retooling for manufacturers serving economy segments.
- Radiation safety compliance:Japan's PMDA maintains rigorous protocols that filter out lower-tier manufacturers, constraining supplier base expansion.
- Conventional CT substitution:Hospital-based radiology departments in developed markets retain preference for full CT in complex maxillofacial cases.
Strategic Opportunities
- Weight-bearing extremity imaging:Orthopedic CBCT for sports medicine practices represents an emerging application with limited installed base competition.
- EU MDR clinical evidence requirements:Stricter evidentiary standards create competitive moats for established players with robust documentation capabilities.
- AI-integrated reconstruction algorithms:Convergence of machine learning with volumetric imaging opens new service revenue models and regulatory classification boundaries.
Industry Challenges
- Reconstruction algorithm expertise:Shortage of computational imaging specialists slows AI feature deployment and regulatory submission preparation.
- Legacy PACS integration:Dental clinics face technical friction connecting new cone beam systems to existing practice management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CBCT/Cone Beam Imaging Market |
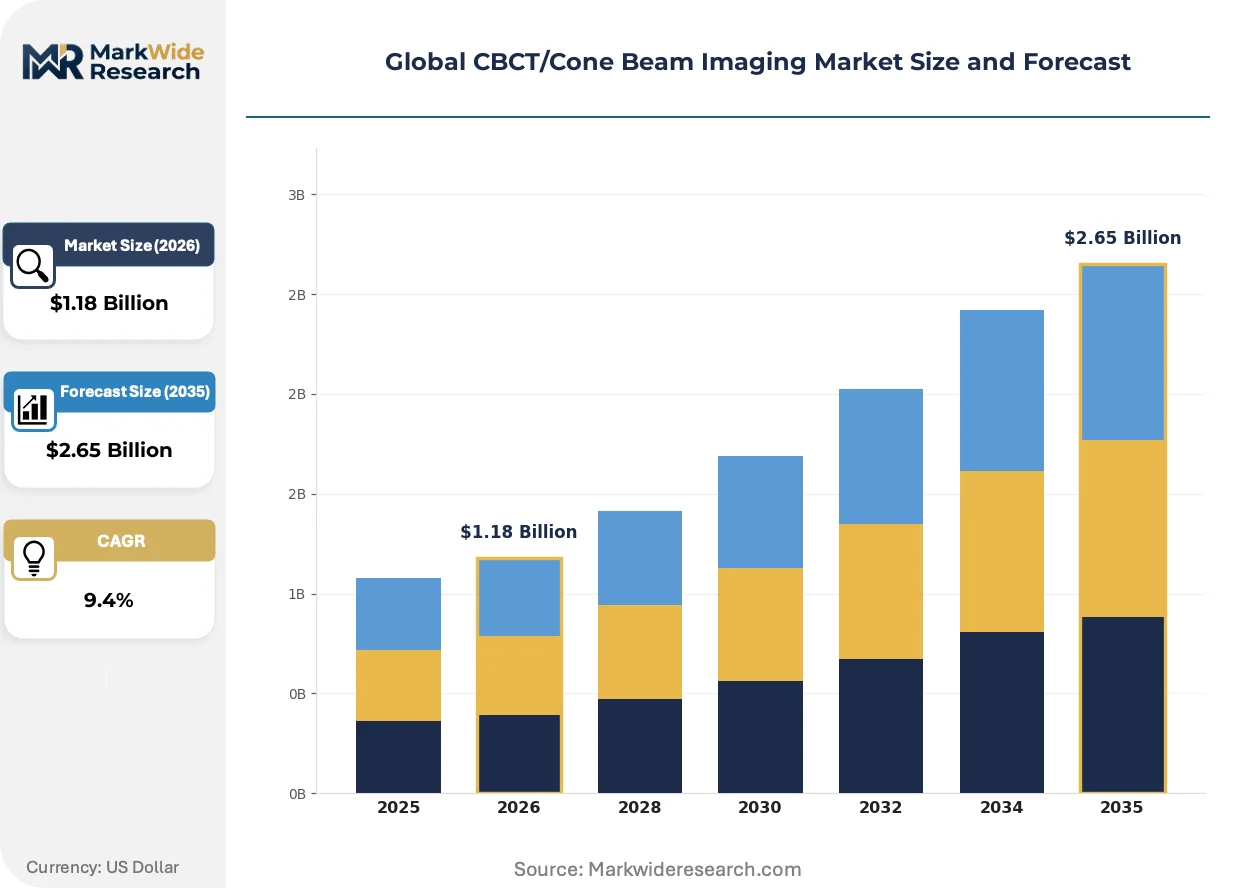
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental CBCT, Orthopedic CBCT, ENT CBCT, Veterinary CBCT, Industrial CBCT Technology: Flat Panel Detector, Image Intensifier, CMOS Detector, Amorphous Silicon Detector, CCD Detector Application: Oral Surgery, Otolaryngology, Musculoskeletal Analysis, Veterinary Diagnostics, Industrial Inspection End User: Dental Clinics, Specialty Hospitals, Veterinary Clinics, Industrial Quality Control, Imaging Centers |
| Companies Covered | VATECH Co., Ltd., Danaher Corporation, Planmeca Oy, Cefla Medical Equipment, KaVo Dental, Dentsply Sirona, J. Morita Corporation, Acteon Group, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CBCT/Cone Beam Imaging Market Shifts & Advancements
Software-defined imaging architectures are displacing hardware-centric value capture, while regulatory frameworks struggle to classify algorithm-enhanced medical devices.
Deep learning reconstruction algorithms are integrating into CBCT workflows to reduce scan times and radiation exposure while maintaining diagnostic image quality. Large dental service organizations in Germany's precision manufacturing corridor are adopting these systems fastest, compressing the competitive window for lagging equipment suppliers.
The EU Medical Device Regulation imposes stricter clinical evidence requirements on new CBCT entrants than predecessor directives. Manufacturers must generate prospective performance data, extending time-to-market by 12-18 months for novel features. Premium-tier suppliers with established quality management systems absorb these costs more readily than mid-tier competitors.
Equipment-as-a-service contracts are displacing outright purchase models among high-rent urban practices seeking to preserve capital. Nordic dental clinics pioneered this shift, with compact footprint designs enabling per-scan pricing structures. German and Japanese markets now replicate this pattern, unbundling hardware from software maintenance and algorithm update subscriptions.
Global CBCT/Cone Beam Imaging Market Segmentation
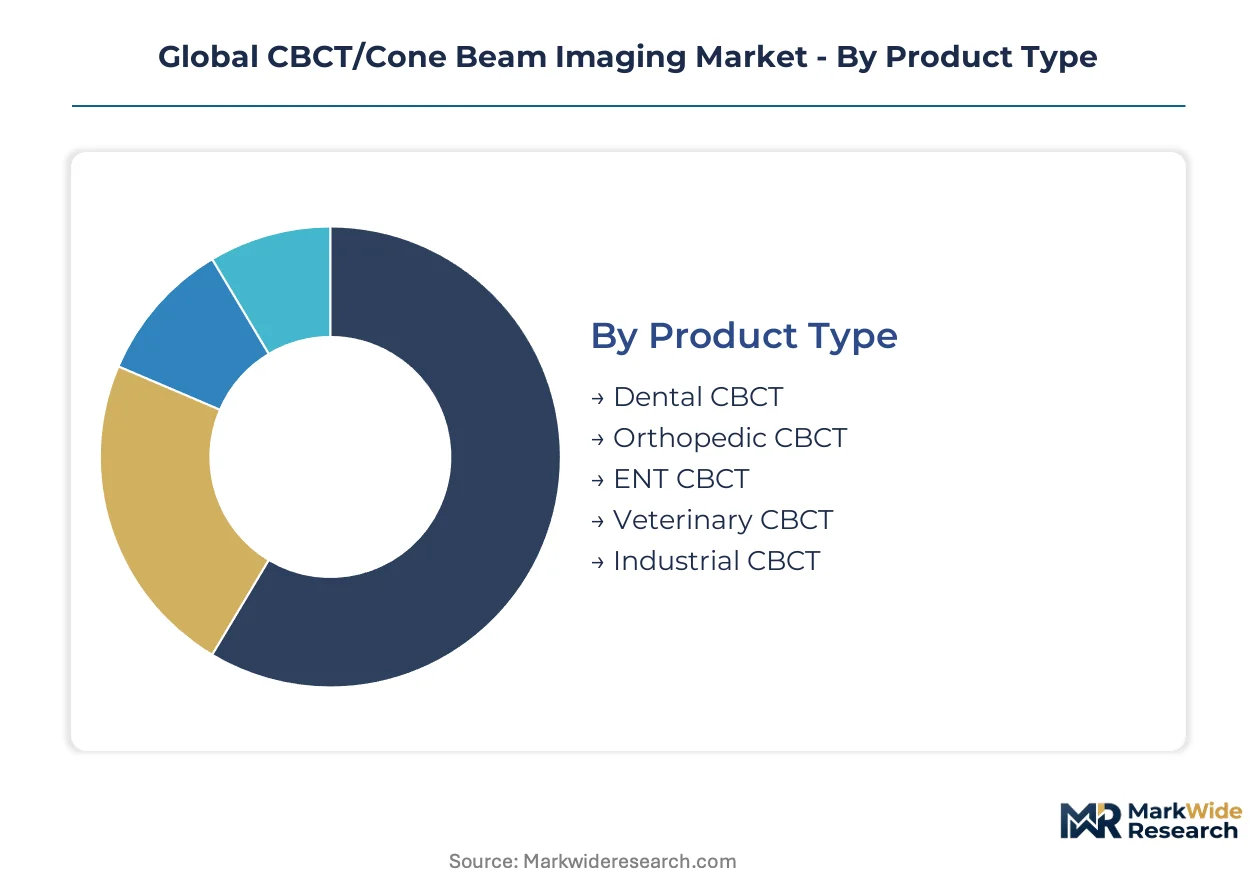
CBCT market segmentation reveals how hardware specifications, clinical workflows, and procurement economics fragment demand across divergent use cases. Understanding these divides exposes where volume concentrates versus where margins expand.
Product Type:
Standalone imaging systems dominate high-throughput environments, while embedded cone beam modules integrate into surgical navigation platforms and chairside manufacturing workflows.
- Dental CBCT:Rotating gantry systems with 5-20 cm field-of-view capture maxillofacial anatomy at sub-millimeter voxel resolution. South Korean and Japanese dental clinics drive replacement cycles as implant dentistry volume climbs. Volume placements concentrate in this segment; the faster expansion belongs to orthopedic applications.
- Orthopedic CBCT:Weight-bearing extremity scanners with horizontal patient positioning enable 3D joint analysis under physiological load. Sports medicine practices in Germany's precision manufacturing corridor adopt these for ankle and knee diagnostics.
- ENT CBCT:Compact footprint units with enhanced soft-tissue contrast algorithms serve otolaryngology suites for sinus and temporal bone imaging.
- Veterinary CBCT:Modified gantry geometries accommodate quadruped positioning for equine dental and small animal orthopedic applications.
- Industrial CBCT:High-energy sources and large field-of-view detectors penetrate dense materials for non-destructive testing in aerospace component validation.
Equipment procurement in dental and orthopedic settings outpaces ENT and veterinary installations by a substantial margin.
Technology:
Detector substrate economics stratify the supply base, with amorphous silicon cost curves enabling mid-tier system proliferation while CMOS architectures displace legacy CCD in price-sensitive segments.
- Flat Panel Detector:Amorphous silicon substrates on thin-film transistor arrays deliver high detective quantum efficiency at falling unit costs. Dental clinics across Asia-Pacific markets access mid-range systems previously restricted to premium tiers.
- CMOS Detector:Complementary metal-oxide-semiconductor photodiode arrays enable faster readout speeds and lower electronic noise than CCD predecessors. Entry-level manufacturers in South Korea and China pivot production to capture economy-segment share.
- Amorphous Silicon Detector:Direct conversion layers skip scintillation steps for improved spatial resolution in high-contrast anatomical imaging.
- Image Intensifier:Legacy vacuum tube technology persists in retrofitted industrial inspection systems with minimal diagnostic requirements.
- CCD Detector:Charge-coupled device architectures face obsolescence as foundry capacity shifts toward CMOS fabrication.
Flat panel and CMOS detector shipments together capture the dominant equipment volume; CMOS conversion rates determine competitive survival for second-tier suppliers.
Application:
Clinical reimbursement patterns and procedural volume economics determine which applications justify capital-intensive cone beam deployment versus outsourced imaging center referrals.
- Oral Surgery:Pre-implant bone assessment, third molar extraction planning, and orthognathic surgical navigation consume the largest installed base capacity. German dental service organizations compress scan-to-treatment timelines through in-house cone beam ownership.
- Musculoskeletal Analysis:Weight-bearing foot and ankle scanning differentiates sports medicine practices from hospital radiology departments constrained to conventional CT protocols.
- Otolaryngology:Sinonasal pathology evaluation and cochlear implant planning drive ENT suite installations with specialized low-dose protocols.
- Veterinary Diagnostics:Equine dental floating guidance and small animal tibial plateau leveling osteotomy planning concentrate demand in specialty veterinary hospitals.
- Industrial Inspection:Additive manufacturing defect detection and turbine blade porosity analysis require penetrating energies beyond medical specifications.
Oral surgery applications anchor the installed base; musculoskeletal analysis gains share fastest as weight-bearing protocols standardize.
End User:
Capital availability and utilization economics separate high-volume clinic purchasers from imaging center renters and hospital department lessees.
- Dental Clinics:Solo and group practices with implant-focused service mixes achieve scan volume thresholds that justify ownership over referral. South Korean urban clinics lead per-capita installation density.
- Specialty Hospitals:Otolaryngology and orthopedic departments within academic medical centers prioritize research-compatible systems with open architecture software.
- Imaging Centers:Independent diagnostic facilities aggregate demand from multiple referring practices, spreading capital costs across higher throughput.
- Veterinary Clinics:Specialty referral hospitals with surgical capabilities capture companion animal cone beam demand ahead of general practice adoption.
- Industrial Quality Control:Aerospace and automotive Tier-1 suppliers operate captive inspection departments with customized acquisition geometries.
Dental clinics and imaging centers together absorb the dominant equipment flow; specialty hospital procurement climbs steepest as integrated surgical navigation bundles proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district hosts the densest concentration of CBCT installations worldwide, with South Korean dental clinics achieving per-capita equipment penetration rates unmatched elsewhere.
United States
Implant dentistry volume in Texas and Florida drives equipment refresh cycles among large dental service organizations. The FDA's 510(k) clearance pathway compresses time-to-market for new cone beam devices, accelerating competitive entry. Chicago's medical technology corridor anchors distribution infrastructure for Midwestern dental markets.
Germany
Precision dental manufacturing clusters in Bavaria and Baden-Württemberg generate sustained demand for high-resolution imaging systems. The EU Medical Device Regulation imposes stricter clinical evidence requirements than predecessor directives, extending approval timelines for novel features. Munich's dental technology district concentrates equipment procurement for Central European export markets.
Japan
Tokyo and Osaka dental clinics expand CBCT installations for pre-surgical implant planning as procedural volume climbs. The PMDA maintains rigorous radiation safety protocols that filter out lower-tier manufacturers, constraining supplier base expansion. Yokohama's medical device testing facilities certify equipment for Asia-Pacific re-export.
South Korea
Seoul's urban dental practices achieve the highest per-capita CBCT installation density globally, driven by aesthetic dentistry specialization and medical tourism flows. The MFDS enforces radiation dose monitoring standards that shape equipment specification requirements. Suwon's electronics manufacturing corridor supplies flat panel detector components to domestic and regional equipment assemblers.
China
Shanghai and Beijing dental chains accelerate CBCT adoption as private healthcare investment expands imaging capabilities. The NMPA's medical device registration system requires local clinical trials for imported equipment, extending market entry timelines. Shenzhen's hardware manufacturing ecosystem produces CMOS detector arrays for entry-level system integrators.
Global CBCT/Cone Beam Imaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software integration and detector substrate quality dimensions. The vendor base stratifies into three tiers: integrated workflow providers commanding loyalty through proprietary software ecosystems, compact-system specialists capturing high-rent urban practices, and price-driven manufacturers leveraging Asian production bases. Strategic moves center on AI-embedded reconstruction algorithm development and equipment-as-a-service contract structures that unbundle hardware from recurring software revenue.
Within the integrated-workflow tier, Danaher Corporation and Planmeca Oy exemplify premium positioning through software-defined value capture. VATECH Co., Ltd. occupies a position among Korean manufacturers leveraging domestic detector supply chains for price-sensitive Asian market penetration. These three anchors illustrate how geographic manufacturing concentration, regulatory compliance depth, and software architecture choices separate margin tiers across the competitive landscape.
| Leading Market Players |
|---|
| VATECH Co., Ltd. |
| Danaher Corporation |
| Planmeca Oy |
| Cefla Medical Equipment |
| KaVo Dental |
| Dentsply Sirona |
| J. Morita Corporation |
| Acteon Group |
| Carestream Health |
| Others |
Supply & Pricing Matrix
Captive flat panel detector production in South Korea and Japan anchors both supply security and pricing power for integrated CBCT manufacturers serving premium dental markets. This backward integration into amorphous silicon substrate fabrication insulates dominant suppliers from component cost volatility while enabling software-defined value capture through bundled algorithm subscriptions.
Pricing Analysis
Throughput-based pricing tied to scan volume thresholds dominates equipment-as-a-service contracts among high-rent urban dental practices. Three-tier pricing structure across premium, standard, and economy levels separates AI-embedded reconstruction bundles from basic hardware-only configurations, with certification grade under FDA 510(k) versus CE marking pathways driving further differentiation. Cost compression in entry-level CMOS-based systems is intensifying because Chinese detector foundries are flooding Asian markets with commoditized arrays. Price sensitivity concentrates among solo dental clinics in emerging markets, while German precision manufacturing clusters exhibit lowest sensitivity due to bundled workflow software lock-in.
Supply Chain Analysis
Dual-sourcing requirements for flat panel detectors are becoming standard among large dental service organizations seeking to mitigate single-source vulnerability during geopolitical disruptions. Manufacturing concentrates in South Korea, Japan, and China, with amorphous silicon substrates, CMOS photodiode arrays, and precision gantry bearings serving as critical component dependencies. Tariff exposure on Chinese detector imports into the US market threatens margin structures for non-integrated assemblers. Distribution runs through specialized dental equipment distributors with regional service capabilities, though direct manufacturer-to-clinic relationships are proliferating for software update delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global CBCT/Cone Beam Imaging Market functions as a cost-of-compliance story where the EU Medical Device Regulation's clinical evidence requirements erect formidable barriers-to-entry moats for players with established quality management systems.
For Market Incumbents: Lock in dental clinic loyalty through proprietary AI reconstruction algorithm ecosystems that embed switching costs into daily workflows. Expand captive flat panel detector capacity in Suwon's electronics corridor to secure component supply against Chinese foundry competition. Prioritize CE marking pathway investments ahead of EU MDR enforcement waves that will strand mid-tier competitors lacking prospective clinical data capabilities. For New Entrants and Emerging Players: Veterinary specialty hospitals represent the most penetrable end-user segment, with equine dental and small animal orthopedic applications exhibiting minimal installed base competition and lighter regulatory scrutiny than human medical pathways. Target weight-bearing extremity imaging for sports medicine practices in Germany's precision manufacturing corridor, where differentiated horizontal patient positioning creates white space outside dental saturation. Pursue equipment-as-a-service contract structures to bypass capital expenditure barriers among high-rent urban practices. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by dental technology conglomerates seeking AI reconstruction algorithm capabilities and installed base expansion. Long-term viability hinges on software-defined revenue streams recurring across decade-long equipment lifecycles rather than transactional hardware margins. Monitor FDA 510(k) clearance velocity for AI-integrated devices as the inflection indicator signaling whether regulatory classification boundaries will compress hardware margins or elevate service revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| AI Reconstruction Algorithm Development | FDA 510(k) submissions for machine learning-embedded devices reshape competitive positioning through regulatory moats. |
| Equipment-as-a-Service Contract Expansion | Per-scan pricing structures in Seoul and Tokyo dental clinics unbundle hardware from recurring software subscriptions. |
| CMOS Detector Manufacturing Pivot | South Korean foundries capture economy-segment share as legacy CCD architectures face obsolescence. |
| EU MDR Clinical Evidence Investment | Prospective performance data requirements extend approval timelines and filter out undercapitalized entrants. |
| Orthopedic Application Segment Entry | Weight-bearing extremity scanners differentiate sports medicine practices from hospital radiology departments. |
Research Methodology
SEC filings, FDA 510(k) clearance databases, and EU Medical Device Regulation submission records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with biomedical engineers at German precision manufacturing clusters, dental clinic procurement managers in Seoul's Gangnam district, and GPO contracts managers at US dental service organizations validated demand assumptions and pricing dynamics. Bottom-up unit shipment estimates triangulated against top-down revenue aggregation across detector technology tiers and application segments.
Historical trendline analysis of flat panel detector cost curves and implant dentistry procedural volumes anchored the projection framework across the analysis window. Segmentation modeling incorporated product type, detector substrate technology, clinical application, and end-user procurement archetype dimensions. CAGRs derived from regression analysis of equipment replacement cycles, software subscription attach rates, and regional regulatory approval velocity. Industry-specific inputs included PMDA radiation safety protocol evolution and MFDS dose monitoring standard implementation timelines.
Caveats apply where AI-integrated reconstruction algorithm regulatory reclassification or amorphous silicon substrate supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding dental clinic capital expenditure recovery and orthopedic CBCT protocol standardization. A model refresh is warranted upon material change in FDA 510(k) clearance timelines for machine learning-embedded devices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
Europe CT Market
Imaging
Global CMOS Image Sensors Market
Imaging
Automotive Compact Camera Module Market
Imaging
Thermal Imaging Systems Market
Imaging
Europe Image Sensors Market
Imaging
Semiconductor Microscopes Market
Imaging
Widefield Imaging Systems Market
Imaging
Microscopic Camera Market
Imaging
Microscope Digital Cameras Market
Imaging
Global Waterproof Camera Market
Imaging
Global High-Speed Digital Camera Market
Imaging
Digital Image Processing Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
In Vivo Imaging Systems Market