
 Electron Beam Welding Systems Market | 2026-2036
Electron Beam Welding Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electron Beam Welding Systems Market Insights
Real-time adaptive beam control is reshaping how precision manufacturers achieve defect-free joints in reactive metals. PRO-BEAM leverages decades of European vacuum-chamber expertise to anchor high-value aerospace contracts. Sciaky Inc dominates large-scale deposition welding for titanium structures through its proprietary wire-feed electron beam technology. Mitsubishi Heavy Industries sustains competitive positioning via integrated in-house production of both beam generators and motion platforms.
Electron beam welding systems generate concentrated thermal energy by accelerating electrons in a high-vacuum environment, typically achieving power densities exceeding 10^5 W/cm² to fuse refractory and dissimilar metals without atmospheric contamination. The primary industrial purpose centers on producing deep, narrow weld profiles with minimal distortion in titanium, nickel superalloys, and hardened steels. CNC systems capture premium margin pools where multi-axis trajectory programming enables complex aerospace component geometries. Vacuum systems retain the largest installed base but face selective displacement by hybrid configurations that combine electron beam precision with reduced chamber evacuation burdens. Medical device applications represent the fastest-growing demand segment as miniaturized implantable hardware requires hermetic sealing of biocompatible alloys.
EASA airworthiness directives and FAA certification standards govern weld procedure specifications for flight-critical structures, compelling system vendors to validate process repeatability through exhaustive qualification protocols. ISO 15614-11 and AWS D17.1 establish baseline acceptance criteria for electron beam welds in aerospace fabrication, creating compliance barriers for non-specialized equipment suppliers. Stakeholders must monitor evolving defense procurement specifications from the Pentagon and allied ministries, as classified material processing requirements increasingly mandate domestic-source beam welding capability with traceable parameter logging.
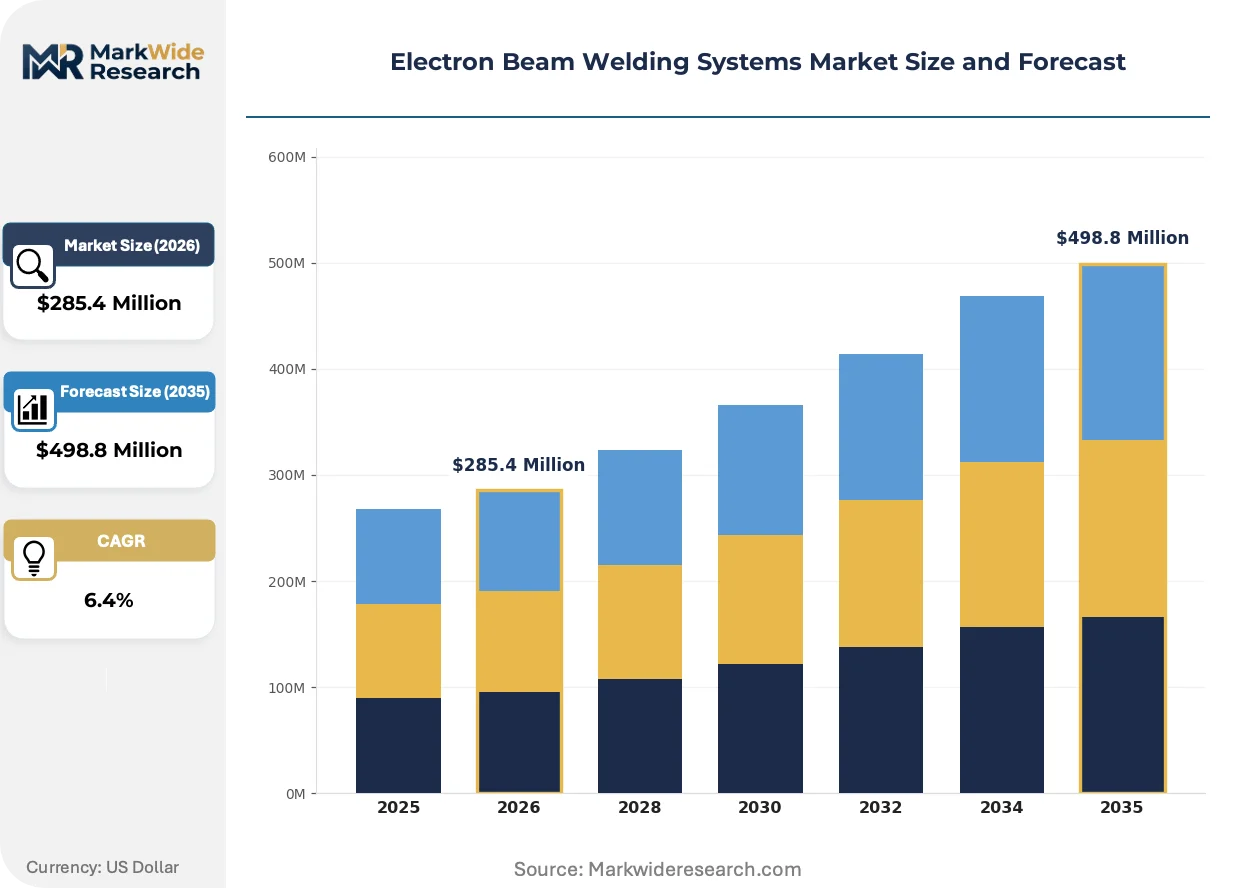
Market Dynamics
Real-time adaptive beam control is compressing defect rates in reactive metal joints while EASA and FAA certification mandates force OEMs toward automated vacuum-chamber systems with traceable parameter logging.
Growth Catalysts
- FAA Airworthiness Directives:Flight-critical structure mandates compel aerospace manufacturers to validate electron beam weld repeatability through exhaustive qualification protocols, expanding system procurement.
- Titanium airframe fabrication:German and French aerospace clusters are accelerating vacuum-based EBW adoption for deep, narrow weld profiles in next-generation airframe joints.
- Hermetic sealing demand:Miniaturized implantable medical hardware in Swiss and US fabrication clusters requires precision sealing of biocompatible alloys, pulling high-vacuum systems into medical device production lines.
Market Restraints
- High-vacuum infrastructure costs:Chamber evacuation systems and cryogenic pumping hardware impose capital intensity that excludes mid-tier fabrication shops from electron beam adoption.
- Beam generator supply concentration:European and Japanese suppliers dominate high-voltage electron gun manufacturing, creating single-source vulnerability for North American system integrators.
- Laser welding substitution:Fiber laser systems with atmospheric welding capability are capturing lower-tolerance aerospace and automotive applications where vacuum purity is not mandatory.
Strategic Opportunities
- Hybrid vacuum-atmospheric configurations:Reduced-chamber systems combining electron beam precision with localized shielding are opening price-accessible tiers for medical device contract manufacturers.
- Defense procurement specifications:Pentagon traceable-parameter mandates for classified material processing are creating captive demand for domestic-source beam welding capability with encrypted logging architectures.
- Wire-feed electron beam deposition:Large-scale additive repair applications for titanium aerospace structures are expanding addressable market beyond traditional fusion welding.
Industry Challenges
- Vacuum technician scarcity:Specialized expertise in high-vacuum chamber maintenance and electron optics alignment remains concentrated among aging European workforces, constraining operational scaling.
- ISO 15614-11 qualification timelines:Exhaustive weld procedure specification validation for aerospace certification creates 18-24 month sales cycles that strain vendor cash conversion.
- Legacy CNC integration friction:Retrofitting adaptive beam control onto existing multi-axis motion platforms requires proprietary interface development that fragments vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electron Beam Welding Systems Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $498.8 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Beam, Portable Beam, Multi-Beam, CNC Systems Applications: Aerospace, Automotive Manufacturing, Medical Devices, Tool Making End User: Manufacturing Plants, Research Institutions, Defense Contractors, Repair Shops Technology: Vacuum Systems, Electron Beam Process, Hybrid Systems, Automated Control |
| Companies Covered | PTR-Precision Technologies, Inc., PRO-BEAM, Acceleron, ACCEL Instruments GmbH, Nissin Electric Co., Ltd., EB Industries, Bodycote, Mitsubishi Heavy Industries, Sciaky Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electron Beam Welding Systems Market Trends and Innovations
Adaptive process control architectures are digitizing weld parameter optimization while regulatory traceability mandates and procurement model evolution reshape how precision manufacturers source beam welding capability.
Sensor-fusion process monitoring is digitizing defect prediction in electron beam welding. Aerospace Tier-1 suppliers in Germany and France are deploying machine-vision and spectroscopic feedback loops to adjust beam focus and traverse speed in real time. This capability is compressing rework rates in titanium airframe production while reducing qualification burden for EASA certification submissions.
EU F-Gas Regulation phase-down schedules are accelerating adoption of closed-loop vacuum pumping architectures. Industrial fabricators face refrigerant restrictions on diffusion pump fluids, pushing investment in oil-free turbomolecular and cryogenic pumping systems. Medical device manufacturers in Switzerland are responding fastest, retrofitting hermetic sealing lines to eliminate fluorinated compound dependency ahead of enforcement timelines.
Performance-based service contracts are displacing capital purchase models for high-value EBW installations. US aerospace subcontractors now procure beam welding capacity as guaranteed joint-per-hour output rather than equipment ownership, transferring uptime risk to system vendors. This shift concentrates vendor margins in consumables and remote diagnostics while compressing upfront revenue recognition cycles.
Electron Beam Welding Systems Market Segmentation
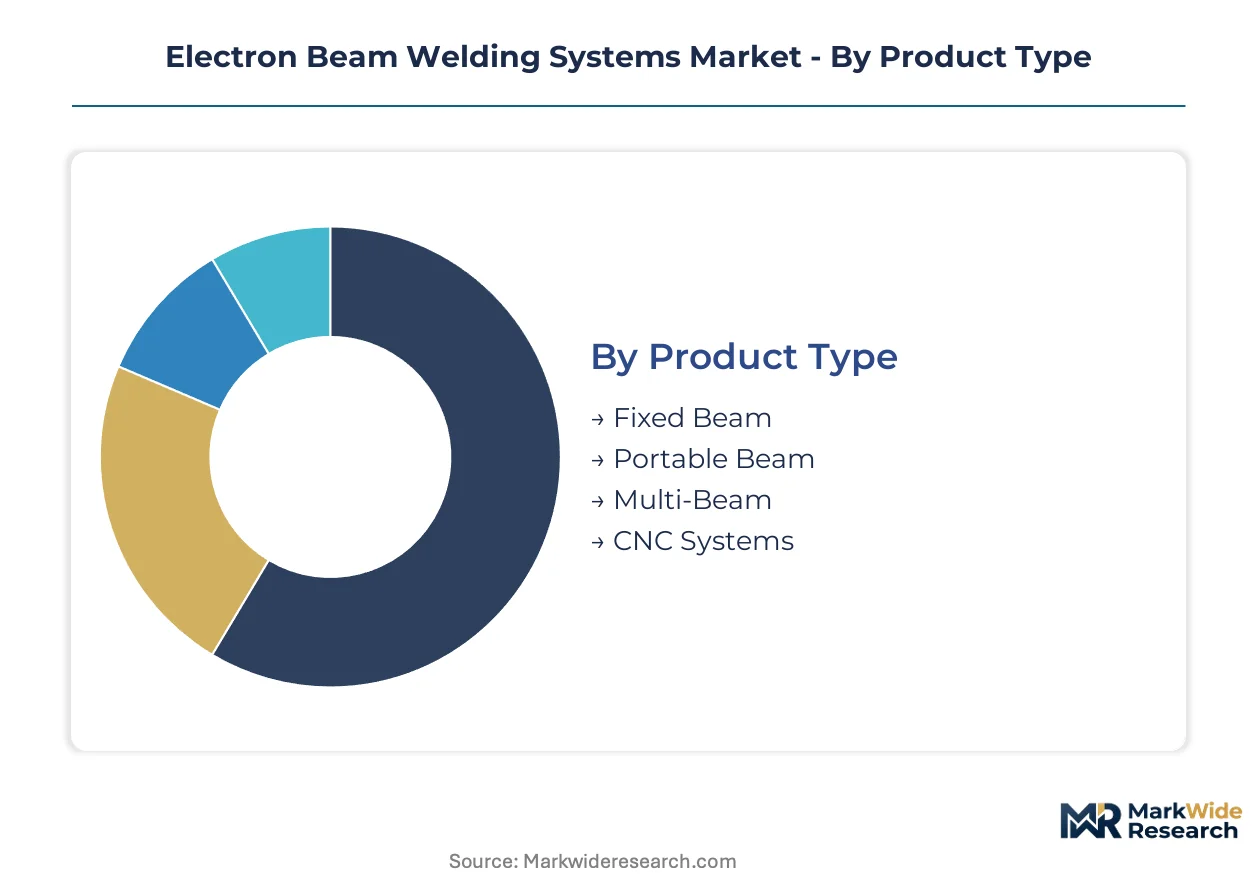
Electron beam welding systems fragment across four structural dimensions that determine capital deployment patterns and vendor competitive intensity. Product architecture dictates vacuum infrastructure requirements, while application mix shapes regulatory compliance burdens and qualification timelines.
Product Type:
Cost tier differentiation separates commodity-accessible configurations from precision-engineered platforms with adaptive control architectures.
- Fixed Beam:Stationary electron gun assemblies mounted on rigid vacuum chambers deliver consistent power density for high-volume aerospace component runs. German airframe manufacturers anchor demand as EASA weld-integrity mandates compress defect tolerance thresholds.
- CNC Systems:Multi-axis trajectory programming enables complex geometries in titanium medical implants and nickel superalloy turbine blades. Swiss precision fabricators concentrate procurement where hermetic sealing specifications require sub-millimeter beam positioning repeatability.
- Portable Beam:Reduced-vacuum field units target on-site repair applications with localized shielding rather than full chamber evacuation.
- Multi-Beam:Synchronized gun arrays accelerate throughput for large-format aerospace structures requiring simultaneous weld initiation.
CNC systems command the established base. The steepest expansion runs through portable beam configurations.
Applications:
End-use concentration patterns reveal where vacuum purity requirements override cost sensitivity in procurement decisions.
- Aerospace:Flight-critical titanium and nickel superalloy joints demand deep penetration with minimal heat-affected zones. FAA certification pathways compel exhaustive weld procedure validation, extending sales cycles but locking in long-term vendor relationships.
- Medical Devices:Miniaturized implantable hardware requires hermetic sealing of biocompatible alloys under ISO 13485 quality systems. Swiss and United States fabrication clusters drive specification intensity for pacemaker enclosures and orthopedic fasteners.
- Automotive Manufacturing:High-strength steel transmission components adopt electron beam welding where laser systems cannot achieve required penetration depth.
- Tool Making:Hardened steel die repair applications leverage concentrated thermal energy for minimal distortion in precision mold geometries.
Aerospace commands the established base. Medical devices show the steepest expansion trajectory.
End User:
Customer type determines procurement model preferences between capital acquisition and performance-based service contracting.
- Manufacturing Plants:High-volume production facilities integrate vacuum-chamber systems into continuous flow lines for aerospace and medical component output.
- Defense Contractors:Pentagon traceable-parameter mandates for classified material processing require encrypted logging architectures and domestic-source beam welding capability.
- Research Institutions:Universities and national laboratories prioritize beam parameter flexibility over throughput for materials science experimentation.
- Repair Shops:Independent service providers adopt hybrid vacuum-atmospheric configurations to access price tiers below full chamber systems.
Manufacturing plants command the established base. Defense contractors are climbing the fastest.
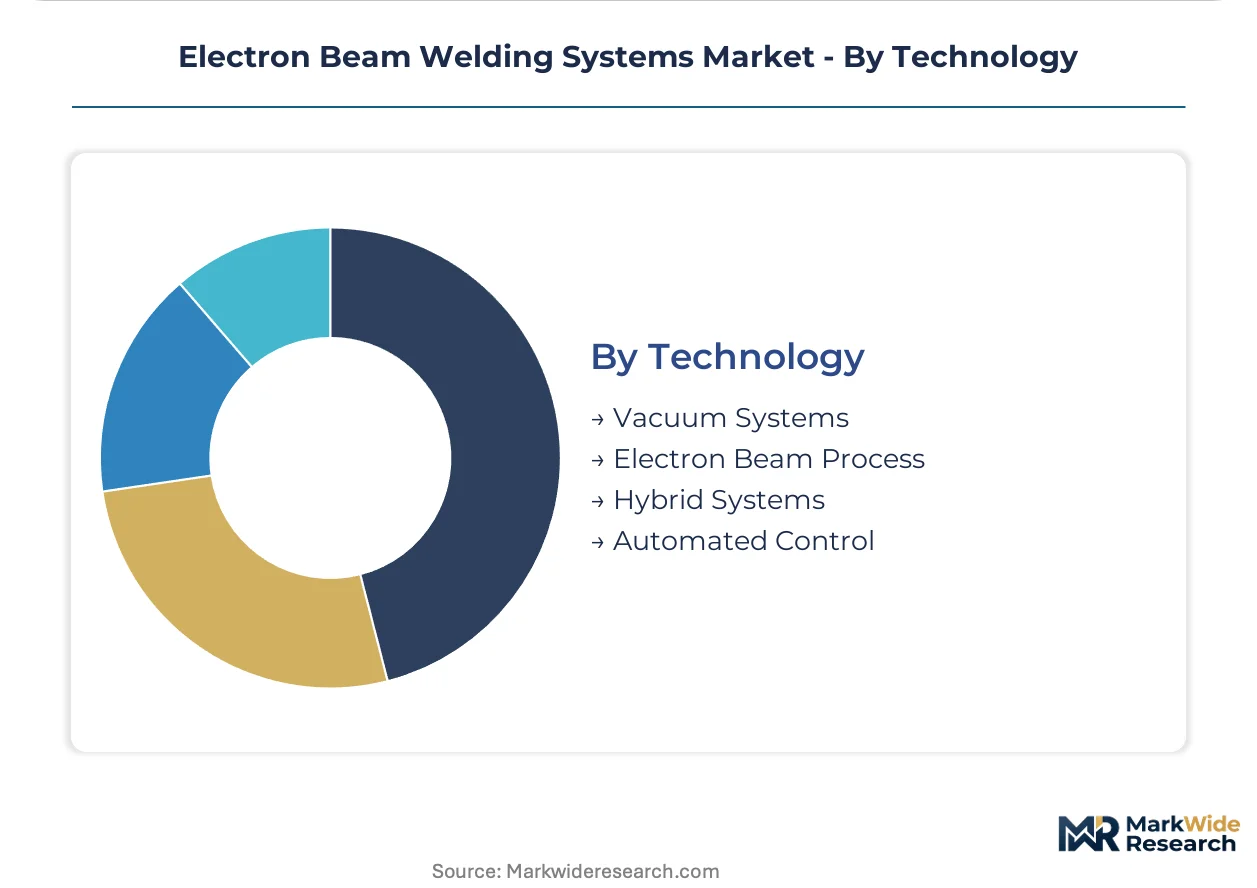
Technology:
Technical architecture choices balance weld quality precision against infrastructure burden and operational complexity.
- Vacuum Systems:High-vacuum environments eliminate atmospheric contamination for reactive metal fusion. EU F-Gas Regulation phase-down schedules accelerate adoption of oil-free turbomolecular pumping to replace fluorinated diffusion pump fluids.
- Automated Control:Real-time adaptive beam control with machine-vision feedback compresses defect rates in titanium airframe production. French and German Tier-1 suppliers deploy spectroscopic monitoring to adjust focus and traverse speed during weld initiation.
- Electron Beam Process:Core acceleration and focusing technology achieves power densities exceeding 10^5 W/cm² for refractory metal penetration.
- Hybrid Systems:Reduced-chamber configurations combine electron beam precision with localized shielding, opening medical device contract manufacturing to mid-tier fabrication shops.
Vacuum systems command the established base. Automated control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace subcontractors and medical device contract manufacturers concentrate procurement of electron beam welding systems across four distinct national markets. Each geography exhibits unique regulatory compliance burdens and industrial clustering patterns that shape vendor selection criteria.
United States
Pentagon traceability mandates for classified titanium processing drive defense contractor procurement of encrypted-logging EBW systems. FAA certification pathways for flight-critical structures extend vendor qualification timelines to 18-24 months. Medical device fabricators in Minneapolis and Boston clusters specify hermetic sealing systems for pacemaker enclosures under FDA quality system regulations.
Germany
Airbus Tier-1 suppliers in Hamburg and Munich accelerate vacuum-chamber EBW adoption for next-generation titanium airframe joints. EASA airworthiness directives compel exhaustive weld procedure validation through ISO 15614-11 protocols. The country's automotive transmission specialists leverage electron beam penetration for high-strength steel components where laser systems fail.
Japan
METI industrial technology roadmaps prioritize domestic beam generator manufacturing to reduce import dependency for precision welding equipment. Mitsubishi Heavy Industries anchors demand through integrated in-house production of acceleration systems and motion platforms. Osaka-area precision fabricators serve aerospace and medical device export markets with sub-millimeter positioning repeatability requirements.
Switzerland
Swissmedic quality system mandates for implantable devices drive specification intensity in Geneva and Basel medical device clusters. EU F-Gas Regulation phase-down schedules accelerate retrofitting of hermetic sealing lines with oil-free turbomolecular pumping. Watchmaking precision heritage translates into orthopedic fastener fabrication demanding vacuum purity for biocompatible alloy fusion.
France
Safran and Dassault supply chain requirements push aerospace subcontractors toward automated EBW systems with real-time adaptive beam control. ANSM medical device regulations align with MDR compliance timelines for hermetic sealing validation. Toulouse and Bordeaux fabrication clusters concentrate titanium airframe welding capacity for narrow-body and business jet programs.
Electron Beam Welding Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. European vacuum-chamber specialists and Japanese integrated industrial conglomerates anchor the premium tier with captive beam generator manufacturing. Mid-tier system integrators source high-voltage electron guns from concentrated European and Japanese suppliers, exposing them to single-source vulnerability. Competitive dynamics center on M&A consolidation of regional service networks and technology licensing agreements for adaptive control architectures.
Among German precision engineering specialists, PRO-BEAM and ACCEL Instruments GmbH occupy positions reflecting decades of European vacuum-chamber expertise. Japanese industrial conglomerates exemplify integrated production models, with Mitsubishi Heavy Industries and Nissin Electric Co., Ltd. representing captive supply chain configurations. US-based Sciaky Inc anchors the large-scale deposition welding segment, while PTR-Precision Technologies, Inc. and EB Industries sit within the North American system integration tier serving defense and medical device contract manufacturers.
| Leading Market Players |
|---|
| PTR-Precision Technologies, Inc. |
| PRO-BEAM |
| Acceleron |
| ACCEL Instruments GmbH |
| Nissin Electric Co., Ltd. |
| EB Industries |
| Bodycote |
| Mitsubishi Heavy Industries |
| Sciaky Inc |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European vacuum-chamber manufacturing is compressing margins for system integrators while simultaneously extending payment terms for North American buyers seeking traceable-parameter EBW platforms. This utilization imbalance forces German and Japanese beam generator suppliers to prioritize defense contractor procurement with encrypted logging architectures over mid-tier medical device fabricators.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate long-term EBW system procurement between aerospace Tier-1 suppliers and European vendors. Three-tier pricing structure across premium CNC systems, standard fixed-beam configurations, and economy portable units separates EASA-certified platforms from uncertified alternatives. Pricing pressure stems from fiber laser substitution in lower-tolerance automotive applications where vacuum purity is not mandatory. Medical device contract manufacturers in Switzerland exhibit highest price sensitivity due to ISO 13485 compliance burdens, while Pentagon defense contractors absorb premium pricing for domestic-source capability with traceable parameter logging.
Supply Chain Analysis
High-voltage electron gun manufacturing draws from concentrated production bases in Germany, Japan, and Switzerland, with tungsten cathode and ceramic insulator feedstocks sourced from specialized European metallurgical suppliers. Beam generator assembly rests on precision-machined vacuum chambers from Italian and Austrian metalworking clusters, creating single-source vulnerability for North American system integrators. Tariff exposure on European-sourced turbomolecular pumping hardware threatens margin stability for US-based defense contractors. Distribution runs through direct OEM relationships for aerospace applications and regional service networks for medical device contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron beam welding systems constitute a defensive-moat market where EASA and FAA regulatory entrenchment creates prohibitive switching costs for certified aerospace suppliers. This structural barrier protects incumbent positioning while constraining new entrant penetration.
For Market Incumbents: Harden defensive positioning through backward integration into beam generator manufacturing and captive vacuum-chamber production. Fiber laser substitution in automotive transmission welding represents immediate margin pressure requiring adaptive control R&D investment. Capacity addition in Swiss medical device clusters captures hermetic sealing specification intensity before hybrid system commoditization.
For New Entrants and Emerging Players: Pursue white-space opportunities in reduced-vacuum portable configurations for on-site aerospace repair applications. Medical device contract manufacturing in Minneapolis and Boston clusters offers most penetrable entry point given ISO 13485 quality system requirements that favor specialized service bundling over capital equipment sales.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier system integrators with established EASA qualification protocols and regional service network density. Long-term viability centers on defense procurement specification capture with encrypted logging architectures. Watch Pentagon domestic-source mandates as inflection signal for North American vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Control Architecture Development | Machine-vision feedback integration compresses defect rates in titanium airframe production for EASA certification. |
| Backward Integration into Beam Generators | Captive electron gun manufacturing eliminates single-source vulnerability from European and Japanese suppliers. |
| Hybrid Vacuum-Atmospheric System Launch | Reduced-chamber configurations open medical device contract manufacturing to mid-tier fabrication shops. |
| Defense Procurement Specification Capture | Encrypted logging architectures satisfy Pentagon traceable-parameter mandates for classified titanium processing. |
| Regional Service Network Consolidation | Post-warranty maintenance contracts concentrate recurring revenue from aerospace Tier-1 suppliers. |
Research Methodology
Operator-level perspectives from vacuum chamber technicians, aerospace welding engineers, medical device quality managers, and defense procurement officers anchored the qualitative base. Primary interviews combined with secondary validation from EASA airworthiness directives, FAA certification standards, ISO 15614-11 weld procedure specifications, and SEC filings from disclosed EBW system vendors. Customs data on high-voltage electron gun imports and aerospace subcontractor procurement disclosures provided quantitative cross-checks. Bottom-up installation base analysis triangulated against top-down market sizing from identified vendor revenue disclosures.
Scenario-bracketing around EASA regulatory enforcement intensity and Pentagon domestic-source mandate timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, application mix, end-user procurement model, and technology configuration with regional regulatory cluster overlay. CAGRs derived from vendor shipment disclosures and aerospace production forecasts with titanium airframe penetration assumptions. Wire-feed electron beam deposition expansion and EU F-Gas Regulation phase-down schedules served as industry-specific forecast inputs.
Sensitivities concentrate around EASA certification timeline acceleration and fiber laser technological substitution in lower-tolerance applications. Forecasts reflect documented assumptions on defense procurement specification evolution and medical device hermetic sealing specification intensity. Cross-checking against disclosed vendor backlog data and aerospace OEM capital expenditure guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Industrial Refrigeration Systems Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Magnetizing Equipment Market