
 Image Intensifier Market | 2026-2036
Image Intensifier Market Size, Share, and Industry Trends Forecast 2026-2036
Image Intensifier Market Analysis
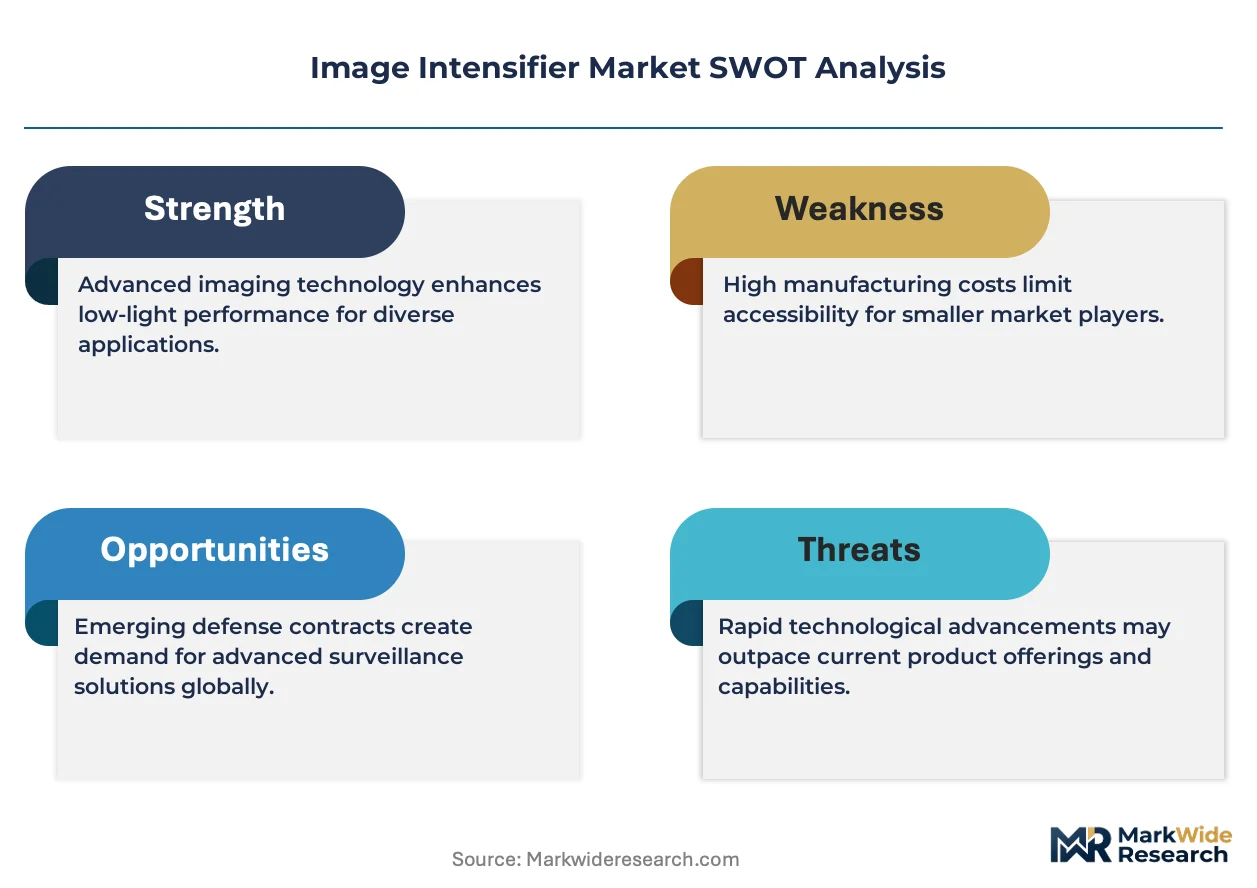
Asset-light leasing models for high-value night vision systems is rewriting competitive access rules in defense procurement. L3Harris Technologies leverages captive government relationships to sustain multi-year service contracts. Elbit Systems anchors its position through vertical integration into tube manufacturing and helmet-mounted displays. Photek Limited specializes in scientific-grade photon counting intensifiers for research institutions.
An image intensifier is a vacuum tube device that amplifies visible and near-infrared light through photocathode electron emission, microchannel plate multiplication, and phosphor screen conversion, typically achieving luminous gains of 10,000 to 50,000 for detection below 10^-6 lux. Night vision devices dominate military procurement volumes while thermal imaging systems command premium pricing in industrial predictive maintenance. Scientific instruments represent the fastest-growing technology segment as photon counting intensifiers displace conventional CCDs in quantum optics research. CCTV technology retains cost advantages in perimeter security despite digital imaging encroachment in commercial applications.
FDA regulates medical diagnostic intensifiers under 21 CFR 1020.32 fluoroscopic equipment standards, while the Wassenaar Arrangement controls dual-use night vision exports through national licensing regimes. The EU AI Act and emerging autonomous targeting regulations will reshape certification requirements for intensifier-integrated sensor fusion systems. Stakeholders must monitor evolving classification thresholds that determine whether intensified imaging modules fall under standard commercial or restricted military export categories.
Market Dynamics
Defense procurement cycles are compressing as NATO member states accelerate soldier modernization timelines, forcing tube manufacturers to retool for higher-throughput photocathode production while navigating stricter Wassenaar Arrangement export licensing.
Growth Catalysts
- Night vision modernization mandates:NATO defense ministries are standardizing helmet-mounted displays across infantry units, creating sustained demand pull for Gen III+ intensifier tubes.
- Wassenaar Arrangement compliance infrastructure:Dual-use classification clarity is reducing licensing uncertainty for scientific instrument exports to research institutions.
- Photocathode materials science:Gallium arsenide and indium gallium arsenide formulations are extending spectral sensitivity into near-infrared bands for low-light surveillance.
Market Restraints
- Microchannel plate supply concentration:Production of high-quality lead glass substrates clusters in a limited number of specialized foundries, creating single-source vulnerability.
- Export licensing friction:National Wassenaar implementation varies across member states, fragmenting compliance costs for multinational equipment vendors.
- Thermal imaging substitution:Uncooled bolometer arrays are capturing perimeter security applications where absolute image fidelity matters less than all-weather performance.
Strategic Opportunities
- Scientific photon counting:Quantum optics laboratories are replacing conventional CCDs with time-resolved intensifiers for single-photon detection experiments.
- EU AI Act certification pathway:Intensifier-integrated sensor fusion systems for autonomous targeting platforms face emerging compliance frameworks that early certifiers can shape.
- Asset-light defense leasing:Multi-year service contracts for high-value night vision systems are opening access for mid-tier contractors without full capital deployment.
Industry Challenges
- Tube manufacturing skill scarcity:Vacuum processing and photocathode activation require specialized technicians with decades of hands-on experience that training programs struggle to replicate.
- Legacy system integration:New intensifier modules must interface with existing helmet mounts, weapon rails, and vehicle display architectures through proprietary connector standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image Intensifier Market |
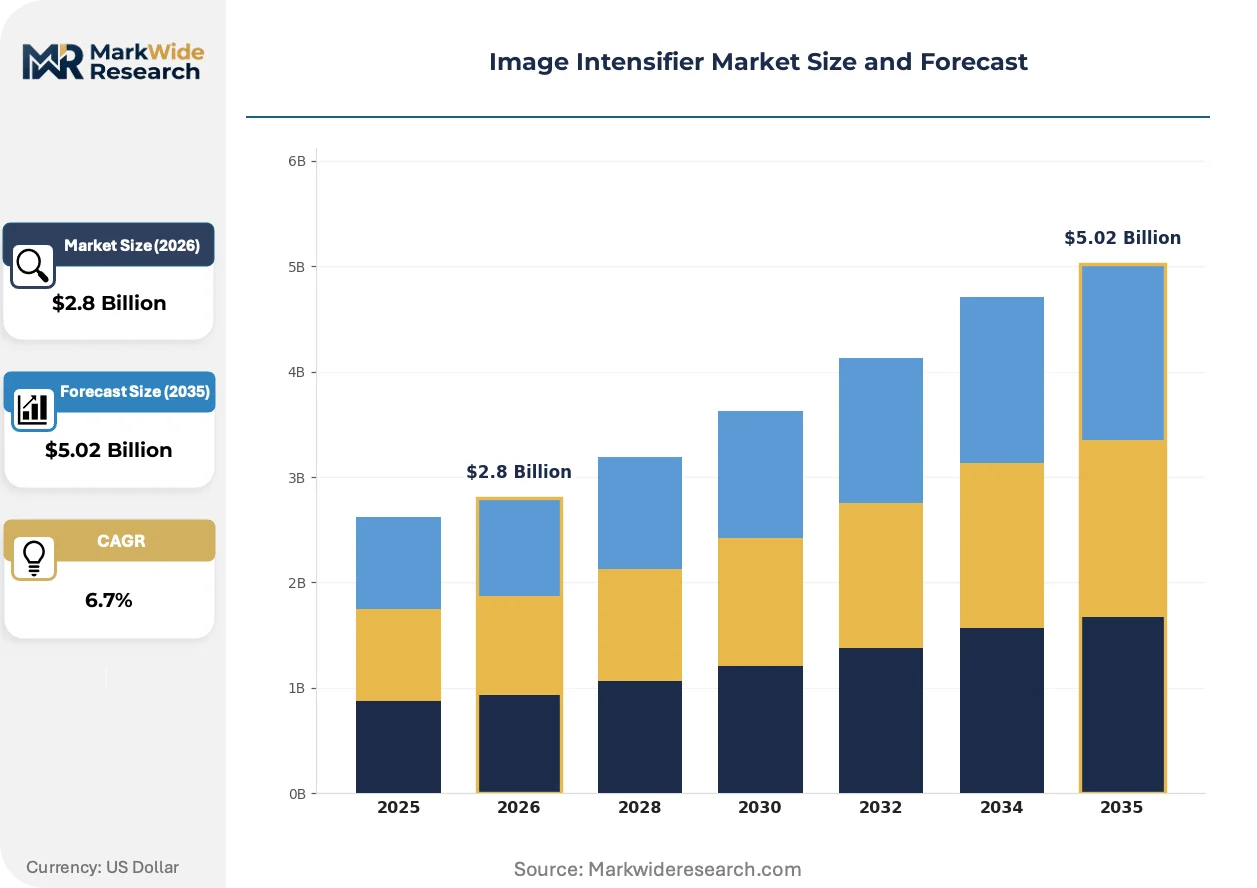
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Light Cameras, Night Vision Devices, Thermal Imaging Systems, Scientific Instruments Technology: CCTV, Infrared Technology, Digital Imaging, Photon Counting End User: Defense, Healthcare, Industrial, Astronomy Application: Surveillance, Medical Diagnostics, Research, Rescue Operations |
| Companies Covered | Exosens, Photek Limited, L3Harris Technologies, Canon Inc., Katod LLC, Elbit Systems, Thales Group, Teledyne FLIR, Hamamatsu Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image Intensifier Market Emerging Trajectories
Digital sensor fusion is eroding the boundary between intensified and thermal imaging, while regulatory frameworks struggle to classify hybrid systems under existing dual-use controls.
White phosphor P-45 and P-43 formulations are replacing traditional green P-20 phosphors in military night vision devices, offering improved contrast discrimination and reduced eye fatigue during extended operations. Special operations units across NATO forces are driving rapid adoption, compressing procurement cycles from multi-year to 18-month fielding timelines. This phosphor transition is rendering obsolete legacy green-tube inventory in secondary defense markets.
The EU AI Act's risk-based classification system is imposing new documentation burdens on intensifier manufacturers supplying sensor modules for semi-autonomous targeting systems. Equipment integrators must now demonstrate human-in-the-loop safeguards and algorithmic transparency for export certification. Scientific instrumentation vendors with purely manual observation products face lighter compliance loads than defense contractors building fused sensor platforms.
Defense agencies are unbundling hardware acquisition from lifecycle support, separating tube procurement from maintenance, refurbishment, and upgrade services. Original equipment manufacturers are responding by establishing captive service divisions or exclusive partnerships with certified depot facilities. This service separation is most advanced in United States Army and Marine Corps programs, where performance-based logistics contracts now cover 60% of deployed night vision systems.
Image Intensifier Market Segmentation
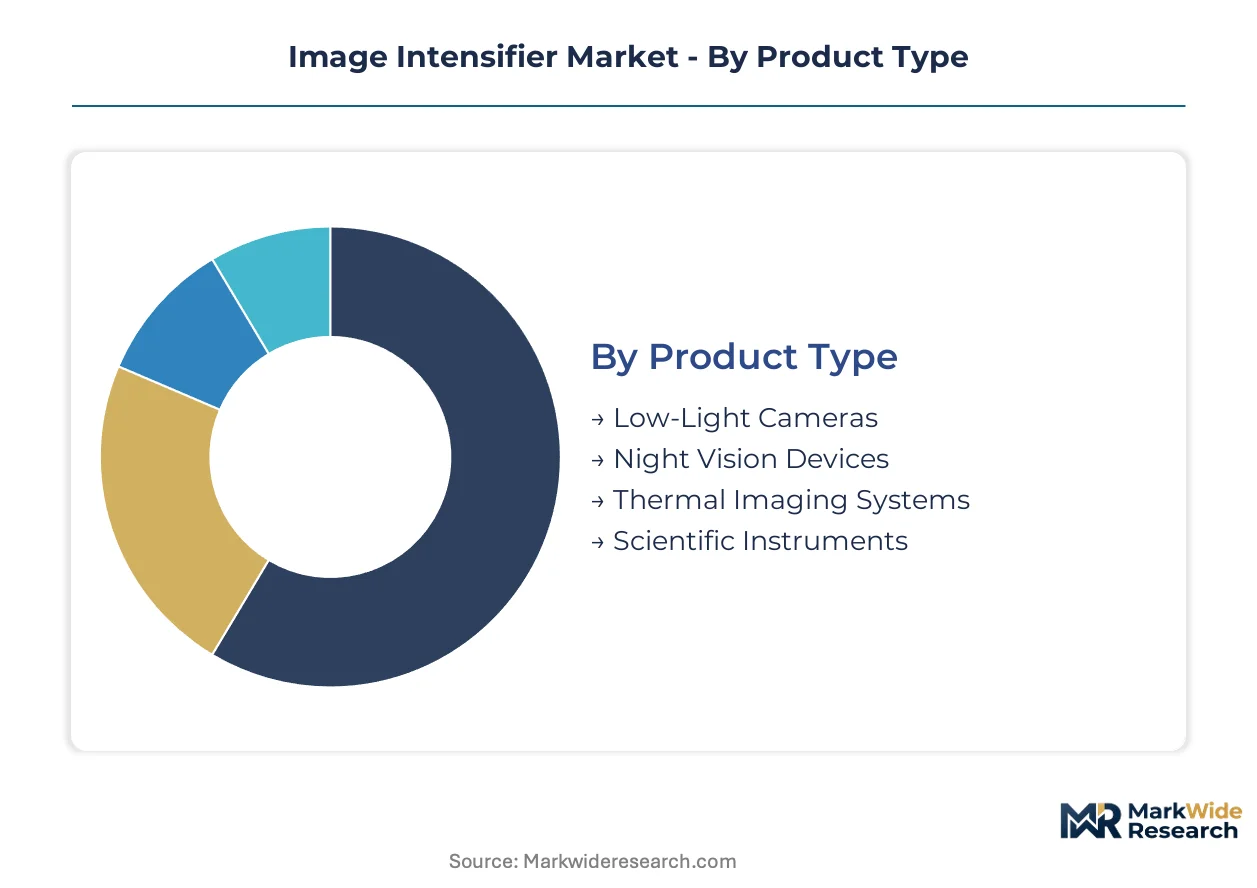
Image intensifier segmentation reveals divergent technical requirements across defense procurement, scientific research, and commercial security verticals. Each dimension—product architecture, detection methodology, customer category, and use case—carries distinct certification burdens and supply chain configurations that reshape competitive access.
Product Type:
Cost tier stratification separates military-grade tube assemblies from scientific and commercial alternatives with vastly different margin structures.
- Night Vision Devices:Helmet-mounted and weapon-sighted configurations utilize Gen III+ vacuum tubes with gallium arsenide photocathodes, achieving 50,000+ luminous gain. NATO soldier modernization programs in the United States, United Kingdom, and Germany concentrate procurement volume for infantry and special operations units facing compressed 18-month fielding timelines.
- Scientific Instruments:Time-resolved photon counting intensifiers with picosecond gating capabilities displace conventional CCDs in quantum optics laboratories. Research institutions in Switzerland, Japan, and the United States drive replacement cycles as single-photon detection experiments demand higher temporal resolution.
- Thermal Imaging Systems:Uncooled bolometer arrays serve perimeter security and predictive maintenance with all-weather operational reliability.
- Low-Light Cameras:Intensified CCD and CMOS hybrids address broadcast journalism and wildlife documentation where extreme sensitivity meets portability requirements.
Night vision devices hold installed capacity. Scientific instruments are rotating up the share rankings.
Technology:
Application context determines whether analog intensification, digital fusion, or photon-resolved detection delivers optimal performance.
- Photon Counting:Gated microchannel plate architectures enable time-correlated single-photon counting with sub-nanosecond resolution. Quantum optics research facilities in Germany, the United States, and Japan prioritize these systems for entanglement studies and fluorescence lifetime microscopy, bypassing the shot noise limitations of analog amplification.
- Digital Imaging:Electron-multiplying CCDs and scientific CMOS sensors with on-chip multiplication gain are penetrating life sciences microscopy. Pharmaceutical screening operations in Switzerland and Massachusetts deploy these for high-throughput cellular imaging where vacuum tube maintenance is operationally prohibitive.
- Infrared Technology:Near-infrared intensification extends spectral sensitivity to 1000nm for covert surveillance and semiconductor inspection.
- CCTV:Conventional intensified cameras retain cost advantages in perimeter security installations across commercial and municipal infrastructure.
Infrared technology holds installed capacity. Digital imaging is rotating up the share rankings.
End User:
Customer type dictates certification pathway, with defense and healthcare facing the most stringent regulatory barriers.
- Defense:Military procurement operates through national security-cleared supply chains subject to Wassenaar Arrangement export licensing. The United States Army and Marine Corps account for the largest national demand through performance-based logistics contracts covering tube procurement, refurbishment, and lifecycle support.
- Healthcare:FDA regulates fluoroscopic intensifiers under 21 CFR 1020.32 equipment standards, while the EU MDR imposes clinical evidence requirements on diagnostic imaging systems. Hospital systems in Germany, France, and California represent concentrated demand for surgical navigation and angiography suites.
- Industrial:Non-destructive testing and semiconductor wafer inspection drive volume for compact intensifier modules.
- Astronomy:Observatory adaptive optics and exoplanet detection programs specify large-format intensified detectors.
Defense holds installed capacity. Healthcare is rotating up the share rankings.
Application:
Use case urgency and observation duration determine whether intensified or alternative imaging modalities prevail.
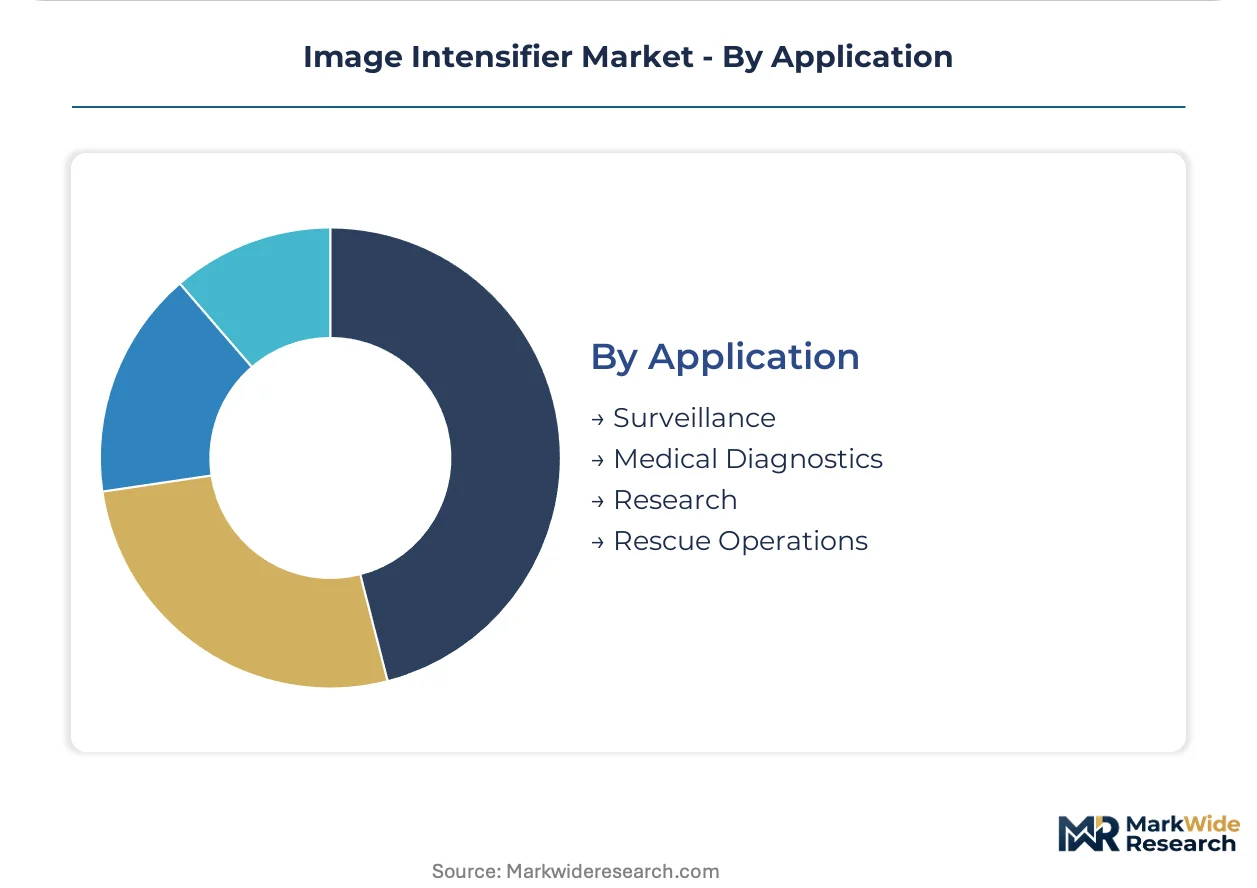
- Surveillance:Border security and critical infrastructure protection combine intensified low-light performance with thermal fusion for 24-hour operational coverage. Customs and border protection agencies in Arizona, Texas, and Sicily deploy hybrid sensor towers where ambient illumination varies across moon phases.
- Medical Diagnostics:Fluoroscopy and surgical navigation demand real-time intensification with minimized radiation dose. Cardiac catheterization labs in Cleveland Clinic, Mayo Clinic, and Charité Berlin specify high-resolution image intensifiers for interventional procedures.
- Research:Spectroscopy and microscopy applications in university and national laboratory settings prioritize photon counting precision.
- Rescue Operations:Urban search and urban fire departments utilize helmet-mounted intensifiers for smoke-obscured environment navigation.
Surveillance holds installed capacity. Medical diagnostics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export licensing asymmetries are redirecting trade flows in image intensification equipment, with manufacturing concentration in Wassenaar Arrangement signatory states creating supply advantages for NATO-aligned procurement programs.
United States
The Army and Marine Corps drive tube demand through performance-based logistics contracts covering procurement, refurbishment, and lifecycle support for helmet-mounted displays. FDA regulates medical fluoroscopic intensifiers under 21 CFR 1020.32 equipment standards. Rochester, New York hosts specialized foundries producing high-quality lead glass substrates for microchannel plates.
Germany
Quantum optics laboratories in Munich and Heidelberg prioritize time-resolved photon counting intensifiers for single-photon detection experiments. The EU AI Act imposes documentation burdens on manufacturers supplying sensor modules for semi-autonomous targeting systems. Bavaria's precision optics cluster around Oberkochen supplies photocathode activation equipment to tube manufacturers.
United Kingdom
Special operations units are compressing procurement cycles to 18-month fielding timelines for white phosphor night vision devices. Wassenaar Arrangement national licensing regimes control dual-use exports through the Export Control Organisation. Photek Limited in St Leonards-on-Sea anchors scientific-grade photon counting intensifier production for research institutions.
Japan
Hamamatsu Photonics drives demand for picosecond-gated microchannel plate architectures in fluorescence lifetime microscopy applications. METI oversees national implementation of dual-use export controls aligned with Wassenaar Arrangement classifications. The Hamamatsu precision optics corridor supplies electron-multiplying CCD components for life sciences imaging.
Switzerland
Research institutions in Geneva and Zurich are replacing conventional CCDs with photon counting intensifiers for entanglement studies. Swissmedic regulates medical diagnostic equipment while maintaining alignment with EU MDR clinical evidence requirements. The Basel pharmaceutical corridor deploys high-throughput cellular imaging systems where vacuum tube maintenance is operationally prohibitive.
Image Intensifier Market Vendor Landscape
On the supply side, the industry is consolidating around defense contractors with captive government relationships and scientific specialists with proprietary photocathode formulations. Three archetypes dominate: vertically integrated tube manufacturers controlling upstream materials, systems integrators bundling hardware with multi-year service contracts, and niche photon counting specialists serving research institutions. Competitive moves center on M&A to secure microchannel plate supply and strategic partnerships to access Wassenaar-cleared export channels.
Within the defense contractor tier, L3Harris Technologies and Elbit Systems exemplify divergent approaches to government market access. L3Harris occupies a position sustained by multi-year service contracts, while Elbit Systems anchors its presence through backward integration into tube manufacturing and helmet-mounted displays. Photek Limited represents the scientific specialist archetype, serving research institutions with time-resolved intensifier systems. Thales Group and Teledyne FLIR sit within the European-North American systems integration segment, while Hamamatsu Photonics exemplifies the Asia-Pacific precision optics tradition. Canon Inc. and Katod LLC occupy positions bridging commercial imaging and specialized intensification applications.
| Leading Market Players |
|---|
| Exosens |
| Photek Limited |
| L3Harris Technologies |
| Canon Inc. |
| Katod LLC |
| Elbit Systems |
| Thales Group |
| Teledyne FLIR |
| Hamamatsu Photonics |
| Others |
Supply Flow & Price Mechanics
Trans-Atlantic air freight corridors linking Rochester, New York to Oberkochen, Germany transmit microchannel plate substrates at premium rates that cascade into three-tier pricing stratification across defense, scientific, and commercial tiers. Lead glass foundry concentration in upstate New York and Bavaria creates asymmetric freight cost absorption that tube manufacturers pass differentially to NATO procurement programs versus research institution buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that separate Gen III+ military tubes from scientific photon counting intensifiers and commercial CCTV alternatives. Price differentiation rests on Wassenaar Arrangement certification grade and after-sales service bundling rather than raw component costs. Cost compression in the scientific tier is intensifying because electron-multiplying CCDs from Hamamatsu erode vacuum tube maintenance premiums. Defense procurement offices show least price sensitivity due to performance-based logistics mandates, while university research labs negotiate aggressively on replacement cycle timing.
Supply Chain Analysis
High-purity lead glass feedstock draws from specialized foundries clustered in the United States, Germany, and Japan, with gallium arsenide photocathode materials sourcing from compound semiconductor fabs in the United Kingdom and Israel. Raw material dependencies include bismuth-activated photocathode substrates, precision-machined ceramic spacers, and phosphor screen coatings. Single-source vulnerability concentrates in lead glass microchannel plate manufacturing where two Rochester-area facilities supply NATO-aligned defense programs. Distribution runs through defense-cleared logistics channels for military-grade tubes and academic procurement networks for scientific instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Image intensifier markets are cycling upward on NATO soldier modernization procurement waves that compress fielding timelines from multi-year programs to 18-month delivery cycles. Defense R&D spending trajectories in the United States and Germany sustain this cyclical momentum through performance-based logistics contract expansion.
For Market Incumbents: Entrench photocathode activation capabilities through captive technician training pipelines that replicate decades of vacuum processing expertise threatened by workforce attrition. Secure exclusive refurbishment depot partnerships with Army and Marine Corps logistics commands to lock in lifecycle revenue streams against emerging service competitors. Backward integration into gallium arsenide substrate supply insulates against compound semiconductor foundry allocation conflicts.
For New Entrants and Emerging Players: Scientific photon counting intensifiers for quantum optics laboratories in Switzerland and Japan represent the most penetrable entry point given lighter Wassenaar licensing burdens and shorter qualification cycles than defense procurement. Mid-tier defense contractors seeking asset-light night vision access through leasing models offer partnership channels without full capital deployment. Target university research procurement officers with time-resolved gating specifications that established vendors underserve.
For Investors and Strategic Acquirers: Specialized microchannel plate foundries with Wassenaar-cleared export channels command scarcity premiums as NATO procurement accelerates. Long-term viability hinges on dual-use classification stability across the analysis window where intensifier-integrated sensor fusion triggers EU AI Act compliance thresholds. Watch for EU autonomous targeting regulation finalization as the inflection signal that reshapes certification investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Photocathode Materials Science Investment | Gallium arsenide and indium gallium arsenide formulations extend spectral sensitivity for low-light surveillance applications. |
| Performance-Based Logistics Contracting | Army and Marine Corps programs now cover lifecycle support for sixty percent of deployed night vision systems. |
| White Phosphor Formulation Transition | P-45 and P-43 phosphors replace legacy green P-20 tubes across NATO special operations procurement. |
| Scientific Instrument Certification Pathway | EU AI Act documentation burdens favor manual observation products over fused sensor platforms for export. |
| Microchannel Plate Supply Security | Rochester foundry concentration creates single-source vulnerability requiring alternative substrate qualification. |
Methodological Framework
Desk research of Wassenaar Arrangement dual-use control classifications, FDA 21 CFR equipment standards, and EU AI Act regulatory texts preceded structured interviews with defense procurement officers, photocathode manufacturing technicians, scientific instrument procurement managers, and export compliance specialists. Primary fieldwork with tube refurbishment depot operators and helmet-mounted display integrators combined with secondary validation against SEC filings from L3Harris and Elbit Systems, customs trade data for gallium arsenide substrates, and GPO contract databases for medical fluoroscopic equipment. Bottom-up shipment data triangulated against top-down defense budget appropriations.
Assumptions held fixed include Wassenaar Arrangement membership stability and NATO soldier modernization program continuity, while variables included EU AI Act implementation timing and thermal imaging substitution rates in perimeter security. The analytical framework modeled product type segmentation across night vision devices, scientific instruments, thermal systems, and low-light cameras; technology segmentation across photon counting, digital imaging, infrared, and CCTV; and end-user segmentation across defense, healthcare, industrial, and astronomy verticals. CAGRs derived from shipment volume trajectories weighted by average selling price movements across certification tiers, with photocathode materials science advancement and export licensing friction as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in defense procurement budget cycles or compound semiconductor substrate pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and thermal imaging competitive displacement. Cross-checking against NATO defense expenditure databases and national export license issuance statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global CMOS Image Sensors Market
Imaging
Microwave Imaging Market
Imaging
Global Thermal Imager Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
US Near Infrared Imaging Market
Imaging
North America Digital Camera Market
Imaging
High-Speed Camera Market
Imaging
Global Panoramic Camera Market
Imaging
Phosphor Screen Scanner Market
Imaging
Smart Camera Market
Imaging
Europe Image Sensors Market
Imaging
Wide Field Imaging Devices Market
Imaging
Global Digital Binoculars Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Cinematographic Camera Market