
 Mexico Medical Cannabis Market | 2026-2036
Mexico Medical Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Medical Cannabis Market Intelligence
Chronic pain clinics are redrawing the buyer landscape as oncologists and neurologists expand cannabis-based protocols. HempMeds leverages its early regulatory approvals to sustain distribution advantages across Mexican hospital networks. Aurora Cannabis anchors cultivation supply through its Colombian operations, while PharmaCielo.com differentiates via specialized oil extraction capabilities tailored to COFEPRIS pharmaceutical-grade standards.
Medical cannabis comprises standardized cannabinoid formulations—primarily CBD and THC extracts processed to precise milligram concentrations for therapeutic dosing—used to manage refractory symptoms in regulated clinical settings. Oils dominate current volume as physicians prefer titratable dosing for pain management protocols, while capsules capture growing share among homecare patients seeking discrete administration. The therapy area segmentation reveals epilepsy and cancer treatment applications commanding premium positioning due to specialized formulation requirements and specialist gatekeeping.
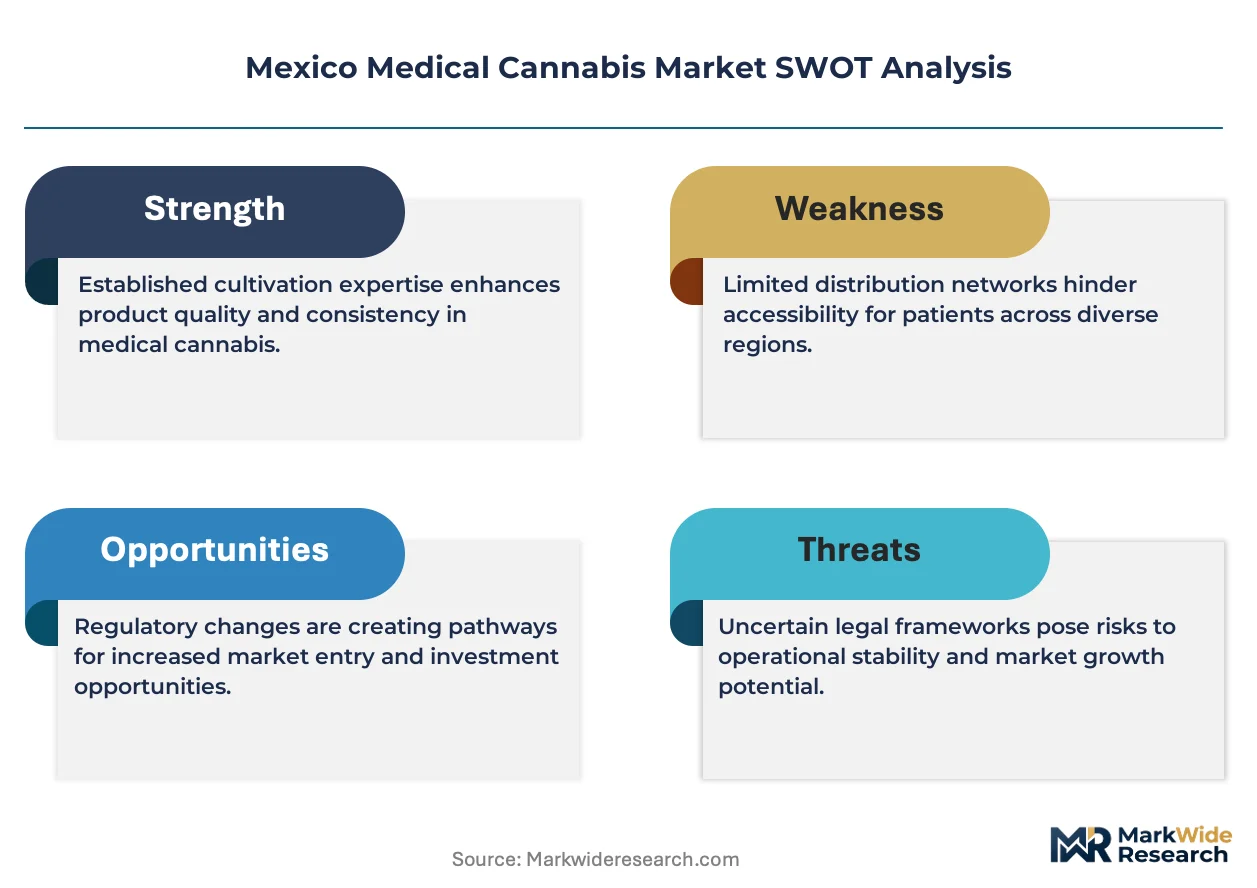
COFEPRIS maintains centralized control over cannabis import permits and pharmaceutical manufacturing licenses, creating a bottleneck that shapes competitive timelines. Mexico's General Health Law amendments and subsequent secondary regulations establish THC thresholds and GMP compliance mandates that filter market participation. Stakeholders must monitor pending judicial interpretations of constitutional cannabis access rights against pharmaceutical exclusivity frameworks.
Market Dynamics
COFEPRIS pharmaceutical-grade GMP mandates are compressing market access timelines while concentrating distribution authority among licensed importers and hospital-network partners. This regulatory bottleneck is reshaping competitive positioning around import permit velocity and specialist physician relationships.
Growth Catalysts
- Chronic Pain Protocol Expansion:Hospital-based pain management departments are integrating cannabinoid formulations into refractory symptom protocols, creating institutional demand pull through specialist gatekeepers.
- COFEPRIS Import Permit Maturation:The regulatory pathway for cannabis-derived medicines has stabilized operational clarity for licensed distributors, reducing approval uncertainty for pharmaceutical-grade products.
- Metropolitan Physician Clustering:Mexico City's concentration of neurologists and oncologists trained in cannabinoid therapeutics is generating prescription density that anchors national demand formation.
Market Restraints
- Import Dependency Concentration:Raw extract supply chains route through limited Colombian and Canadian cultivation sources, exposing Mexican formulators to cross-border shipment delays and customs clearance variability.
- THC Threshold Rigidity:Mexico's General Health Law amendments impose strict psychoactive content ceilings that filter product portfolios and complicate formulation flexibility for complex symptom management.
- Specialist Access Bottleneck:The narrow pool of COFEPRIS-authorized prescribing physicians restricts patient eligibility expansion beyond metropolitan hospital networks.
Strategic Opportunities
- Guadalajara-Monterrey Corridor Expansion:Secondary metropolitan zones lack specialist density but show rising diagnostic capacity that could support satellite prescription hubs with appropriate physician training investment.
- Homecare Capsule Formulations:Discrete oral administration formats address stigma-sensitive patient segments seeking alternatives to hospital-based oil titration protocols.
- Epilepsy Adjunct Therapy Positioning:Pediatric neurology protocols represent an underpenetrated application area where standardized CBD ratios could displace conventional anticonvulsant escalation pathways.
Industry Challenges
- GMP Certification Timeline Compression:COFEPRIS manufacturing license requirements demand facility validation periods that strain working capital for domestic production entrants.
- Pharmaceutical-Exclusivity Interpretation Risk:Pending judicial review of constitutional cannabis access rights against patented formulation frameworks creates IP enforcement uncertainty for imported specialty extracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Medical Cannabis Market |
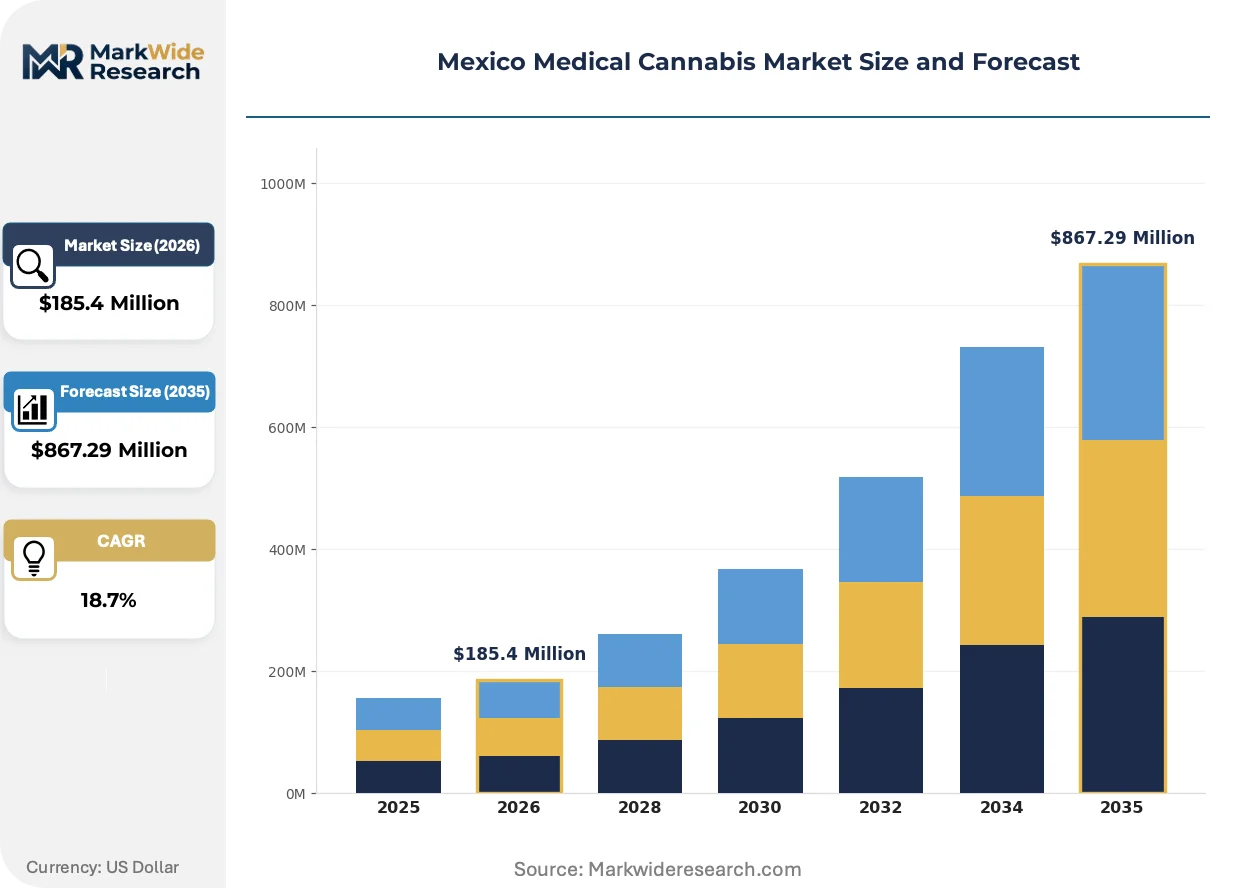
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $867.29 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Tinctures, Capsules, Topicals Therapy Area: Pain Management, Anxiety Disorders, Epilepsy, Cancer Treatment End User: Hospitals, Clinics, Pharmacies, Homecare Delivery Mode: Oral, Inhalation, Transdermal, Sublingual |
| Companies Covered | Jazz Pharmaceuticals, Inc., HempMeds, Aurora Cannabis, PharmaCielo.com, Isodiol International Inc., Canopy Growth Corporation, CBD Life, Elixinol, GW Pharmaceuticals, plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Medical Cannabis Market Strategic Shifts & Innovations
Extraction technology specialization and distribution channel restructuring are reconfiguring how cannabinoid formulations reach prescribing physicians and end patients. These shifts are compressing legacy import-dependent models while elevating quality-certification premiums.
Nanoemulsion and liposomal delivery technologies are bifurcating the formulation landscape between hospital-grade precision dosing and consumer-oriented bioavailability claims. Pain management specialists in Mexico City hospital networks are adopting microencapsulated oils for faster onset profiles, while retail-adjacent channels promote water-soluble formats with unverified absorption advantages. This technological divergence is compressing mid-tier extractors lacking either pharmaceutical certification or consumer marketing scale.
COFEPRIS has tightened contaminant testing protocols for imported cannabis extracts, extending laboratory validation requirements for heavy metals and residual solvents. This regulatory tightening is filtering distributor portfolios toward suppliers with captive analytical capabilities or third-party ISO 17025-certified testing partnerships. Oncology-focused formulators are absorbing compliance costs most aggressively, given their patient population's immunocompromised vulnerability profiles.
Hospital procurement departments are consolidating cannabinoid purchasing through centralized pharmacy committees rather than individual physician import authorizations. This buyer concentration is displacing fragmented distributor relationships with network-exclusive supply contracts that bundle formulation, testing, and patient education services. The shift is most visible in Mexico City's Instituto Nacional de Cancerología and affiliated tertiary care complexes.
Mexico Medical Cannabis Market Segmentation
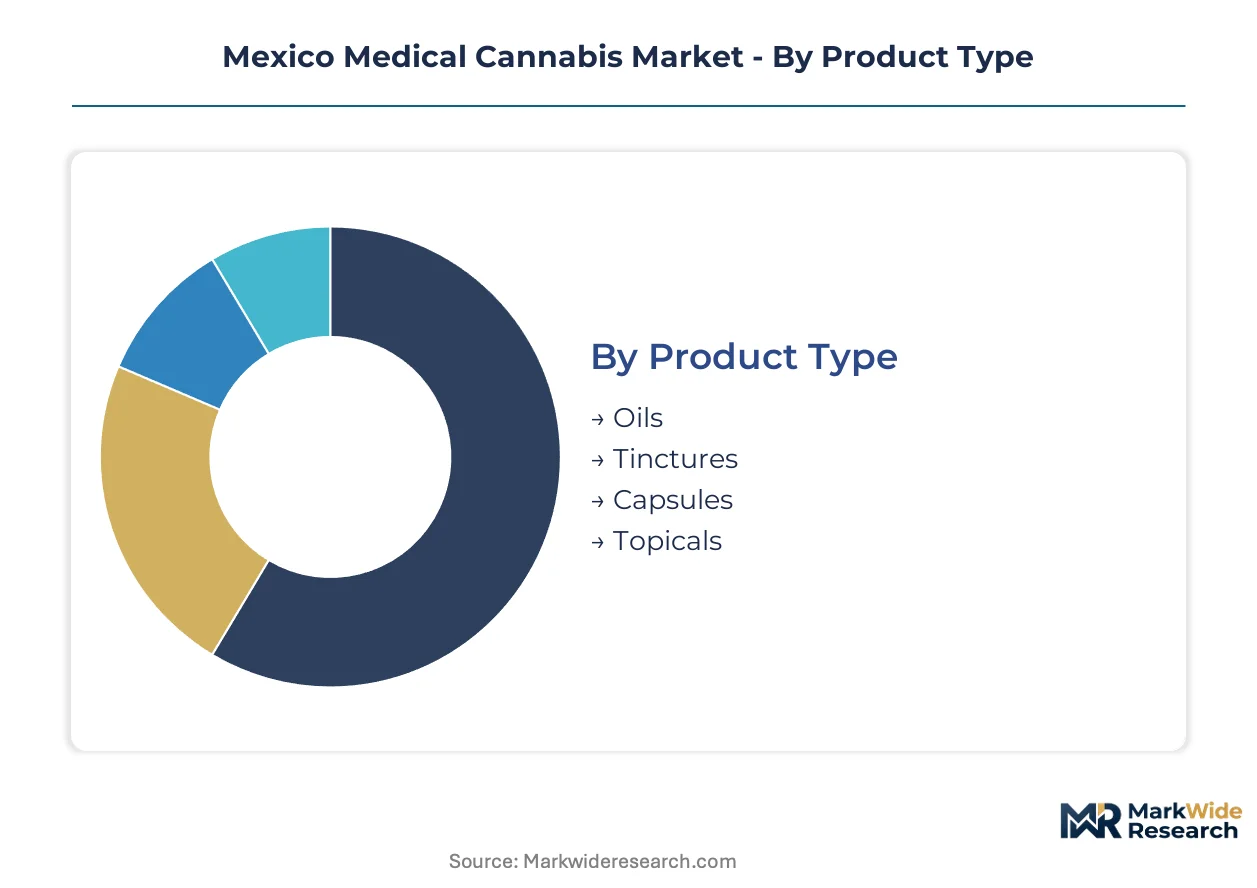
Segmentation in Mexico's medical cannabis market reflects COFEPRIS regulatory tiers and prescribing physician concentration patterns. Product form factors, therapy applications, and delivery modes each carry distinct margin profiles shaped by pharmaceutical-grade compliance costs and hospital procurement centralization.
Product Type:
Margins concentrate in formulations requiring the most intensive COFEPRIS certification and analytical validation protocols.
- Oils:Standardized cannabinoid extracts processed to precise milligram concentrations enable titratable dosing protocols preferred by Mexico City hospital pain management departments. Demand clusters in tertiary care networks where neurologists and oncologists require flexible dose escalation for refractory symptoms.
- Capsules:Discrete oral administration formats capture homecare patients seeking alternatives to hospital-based oil protocols. Prescription density is rising fastest in metropolitan zones where stigma-sensitive patients prioritize administration privacy over titration precision.
- Tinctures:Alcohol-based extracts with rapid sublingual absorption profiles serve patients requiring faster onset than oral capsules without inhalation.
- Topicals:Transdermal formulations address localized pain applications with minimal systemic absorption, appealing to patients excluded from psychoactive thresholds.
Oils hold installed capacity. Capsules are rotating up the share rankings.
Therapy Area:
Application-specific formulation requirements create tiered pricing power based on specialist gatekeeping density and patient acuity.
- Pain Management:Chronic pain protocols in hospital settings generate the highest prescription volumes as COFEPRIS-authorized physicians integrate cannabinoid formulations into refractory symptom management. Mexico City's Instituto Nacional de Cancerología and affiliated complexes anchor institutional demand.
- Cancer Treatment:Oncology-focused applications command premium positioning due to immunocompromised patient vulnerability profiles demanding the most stringent contaminant testing and GMP compliance. Formulators absorb elevated analytical costs to serve this segment.
- Epilepsy:Pediatric neurology protocols represent an underpenetrated area where standardized CBD ratios could displace conventional anticonvulsant escalation pathways.
- Anxiety Disorders:Psychiatric applications face tighter THC threshold constraints that limit formulation flexibility compared to pain and oncology protocols.
Pain Management holds installed capacity. Cancer Treatment maintains the steepest expansion trajectory.
End User:
Channel concentration shapes working capital requirements and regulatory interface complexity across the value chain.
- Hospitals:Centralized pharmacy committees at tertiary care complexes in Mexico City are consolidating purchasing through network-exclusive supply contracts. This buyer concentration bundles formulation, testing, and patient education services into single-source agreements.
- Clinics:Specialist outpatient facilities outside metropolitan cores face narrower COFEPRIS-authorized prescribing pools that restrict patient eligibility expansion.
- Homecare:Direct-to-patient channels are gaining traction as capsule formulations enable discrete administration beyond hospital supervision.
- Pharmacies:Retail-adjacent distribution remains limited by import permit bottlenecks and specialist prescription requirements that filter mass-market access.
Hospitals hold installed capacity. Homecare is rotating up the share rankings.
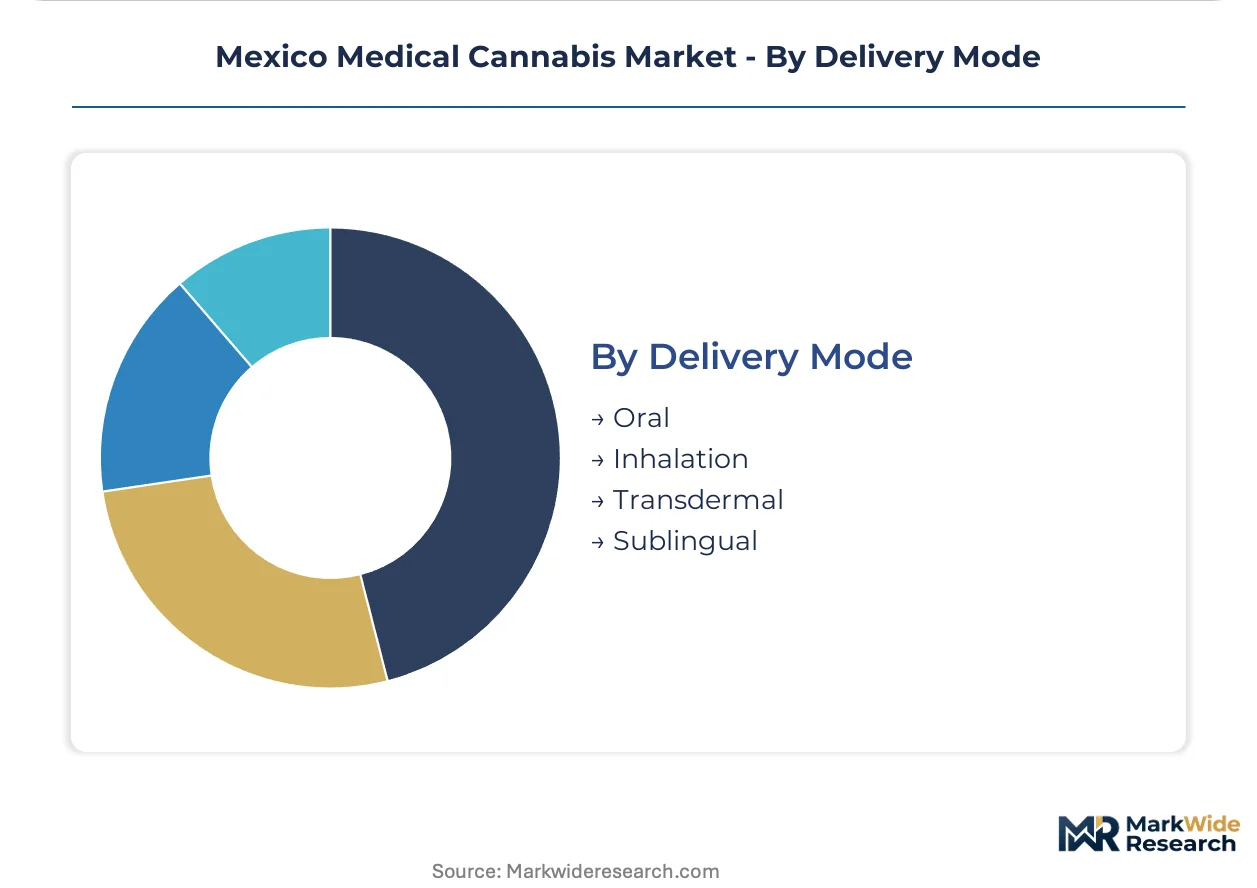
Delivery Mode:
Onset characteristics and administration setting determine technology selection and patient compliance profiles.
- Oral:Capsule and oil ingestion dominates current volume through predictable pharmacokinetics suitable for chronic dosing regimens. COFEPRIS pharmaceutical-grade standards favor this route for institutional protocols.
- Sublingual:Tincture and oil drops under the tongue offer faster absorption than gastrointestinal processing, bridging hospital precision and homecare convenience.
- Inhalation:Vaporized delivery faces regulatory headwinds under Mexico's General Health Law amendments that impose strict psychoactive content ceilings complicating dose standardization.
- Transdermal:Patch and topical applications serve localized symptom management with minimal systemic exposure, appealing to patients at THC threshold limits.
Oral holds installed capacity. Sublingual is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombian and Canadian cultivation operations supply raw extract to Mexican formulators through cross-border shipment corridors. COFEPRIS import permits filter which suppliers gain market access. Metropolitan hospital networks in Mexico City concentrate prescription demand.
Mexico City Metro
Instituto Nacional de Cancerología and affiliated tertiary complexes anchor institutional cannabinoid procurement through centralized pharmacy committees. COFEPRIS pharmaceutical-grade GMP mandates filter supplier eligibility for oncology and pain management protocols. Neurologist and oncologist clustering generates prescription density that shapes national demand formation.
Nuevo León
Monterrey's expanding diagnostic capacity supports satellite prescription hub development with targeted physician training investment. The state's industrial infrastructure attracts pharmaceutical distributors seeking northern Mexico logistics positioning. Hospital networks here lag Mexico City in specialist density but show rising chronic pain protocol adoption.
Jalisco
Guadalajara's medical tourism corridor creates patient flow that intersects with cannabinoid therapy demand from international visitors seeking COFEPRIS-regulated treatments. The metropolitan zone lacks Mexico City's specialist concentration but demonstrates growing outpatient clinic capacity. Regional distributors target this gap with physician education programs.
Bajío Region
Querétaro and Guanajuato pharmaceutical manufacturing clusters face GMP certification timeline compression under COFEPRIS manufacturing license requirements. Facility validation periods strain working capital for domestic production entrants seeking to reduce import dependency. The region's industrial real estate offers expansion capacity for compliant extract processing.
Northern Border States
Baja California and Chihuahua proximity to US markets creates regulatory arbitrage risks as patients cross for unregulated products. COFEPRIS enforcement concentrates on legitimate import channels rather than informal flows. Licensed distributors in Tijuana and Ciudad Juárez face competitive pressure from uncontrolled alternatives.
Mexico Medical Cannabis Market Key Industry Players
Listed leaders compete with private specialists across import permit velocity and hospital network penetration. The vendor base concentrates among licensed distributors with COFEPRIS pharmaceutical manufacturing partnerships rather than fragmented retail channels. Three archetypes dominate: early regulatory entrants with established permit portfolios, Colombian-anchored cultivators with captive supply chains, and specialized extractors with ISO 17025-certified testing capabilities. Competitive moves center on hospital procurement committee capture and GMP certification acceleration.
Among North American-listed operators, Canopy Growth Corporation and Aurora Cannabis exemplify scale-driven archetypes with cultivation assets positioned for cross-border supply. Jazz Pharmaceuticals, Inc. occupies a position within the pharmaceutical-integrated tier, reflecting specialty drug development heritage applied to cannabinoid therapeutics. HempMeds represents early-mover advantage in regulatory navigation, with its name signaling medical-channel positioning distinct from consumer-oriented competitors.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals, Inc. |
| HempMeds |
| Aurora Cannabis |
| PharmaCielo.com |
| Isodiol International Inc. |
| Canopy Growth Corporation |
| CBD Life |
| Elixinol |
| GW Pharmaceuticals, plc |
| Others |
Cost & Logistics Intelligence
Ninety-day import permit processing windows at COFEPRIS concentrate pricing power among pre-approved distributors with validated inventory positions, while hospital procurement committees exploit buyer concentration to compress margins on non-exclusive supply contracts. This lead-time rigidity rewards early regulatory entrants with working capital advantages that latecomers cannot replicate without GMP-certified manufacturing partnerships.
Pricing Analysis
Extraction-technology pricing gaps separate pharmaceutical-grade nanoemulsion oils from standard ethanol extracts and unvalidated water-soluble formats. Three-tier pricing structure across GMP-certified specialty, COFEPRIS-registered standard, and unregistered economy levels reflects analytical validation intensity and contaminant testing burden. Pricing pressure stems from hospital procurement centralization bundling formulation with patient education services. Oncology networks show least price sensitivity given immunocompromised patient vulnerability profiles; homecare capsule buyers drive hardest volume discounts.
Supply Chain Analysis
COFEPRIS import authorization bottlenecks filter raw extract flows from Colombian cultivation zones and Canadian pharmaceutical-grade operations into Mexican formulators. Supply chains draw from THC-compliant biomass, ISO 17025-certified testing partnerships, and specialized oil extraction equipment. Single-source vulnerability concentrates in cross-border shipment corridors exposed to customs clearance variability. Distribution runs through hospital-network exclusive contracts rather than fragmented retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
COFEPRIS regulatory platform maturation creates ecosystem interoperability inflection as hospital procurement systems integrate cannabinoid protocols with existing pharmaceutical inventory management. Specialist physician credentialing databases now interoperate with distributor permit verification, lowering search friction for institutional buyers.
For Market Incumbents: Secure GMP manufacturing license acceleration through captive laboratory partnerships or third-party ISO 17025-certified testing alliances. Deepen hospital procurement committee relationships via bundled patient education services that raise switching costs for competitor displacement. Defend against Colombian-anchored cultivators seeking direct COFEPRIS import permits by locking network-exclusive supply contracts before regulatory pathway stabilization completes. For New Entrants and Emerging Players: Lead with pediatric epilepsy protocols as the most penetrable therapy area where standardized CBD ratios face limited incumbent formulation specialization. Target Guadalajara-Monterrey corridor expansion where diagnostic capacity outpaces specialist physician density. Deploy physician training investments as primary go-to-market mechanism rather than distributor margin sharing. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because COFEPRIS permit velocity determines competitive survival more than cultivation scale or extraction technology. Acquisition target archetype: specialized extractors with validated analytical capabilities and existing hospital-network relationships. Watch COFEPRIS manufacturing license approval timelines as the critical inflection signal for domestic production economics versus import-dependent models.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Import Permit Acceleration | Reduces approval uncertainty for pharmaceutical-grade cannabinoid products entering Mexican hospital networks. |
| GMP Manufacturing License Investment | Enables domestic production economics that compress working capital requirements versus import-dependent competitors. |
| Hospital Procurement Committee Capture | Locks network-exclusive supply contracts bundling formulation, testing, and patient education services. |
| Specialist Physician Training Programs | Expands COFEPRIS-authorized prescribing pool beyond Mexico City metropolitan concentration. |
| Pediatric Epilepsy Protocol Development | Positions standardized CBD ratios to displace conventional anticonvulsant escalation pathways. |
Research Approach
The analysis maps cannabinoid formulation sub-sectors, each validated through regulatory affairs specialists at COFEPRIS-licensed distributors, hospital pharmacy procurement managers, and specialist physicians in pain management and oncology departments. Primary interviews with import permit holders, GMP facility operators, and patient advocacy organizations combined with secondary validation against COFEPRIS public filings, Mexican General Health Law amendments, and hospital procurement database records. Bottom-up prescription volume modeling triangulated with top-down market sizing across therapy area concentration patterns.
Consistency checks validated volume and value outputs against external benchmarks including cross-border trade flows, competitor disclosed capacity positions, and regulatory approval timelines. The analytical framework segmented by product form factor, therapy application, end-user channel, and delivery mode across the projection horizon. CAGRs derived from prescription density trajectories in metropolitan hospital networks, specialist physician training pipeline estimates, and regulatory pathway maturation indicators including COFEPRIS staffing and budget allocations.
The analysis sits within stated boundaries; outcomes outside COFEPRIS regulatory enforcement continuity, constitutional cannabis access rights judicial stability, or Colombian-Canadian supply corridor reliability would require recalibration. Forecasts reflect documented assumptions regarding permit processing efficiency and hospital procurement centralization pace. Practitioners should keep alternative scenarios live as COFEPRIS manufacturing license approval velocity and constitutional access litigation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
North America Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
Synthetic Cannabinoids Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
CBD Gummies Market