
 Cannabidiol (CBD) Oil Market | 2026-2036
Cannabidiol (CBD) Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabidiol (CBD) Oil Market Outlook
FDA enforcement discretion is repositioning the cost-of-entry calculus for new CBD oil entrants, forcing capital allocation toward compliant manufacturing infrastructure and toxicology dossiers. Canopy Growth Corporation anchors its North American position through controlled-environment cultivation and downstream extraction assets. Tilray Brands Inc. leverages pharmaceutical-grade certification to access restricted distribution channels. Charlotte's Web Holdings Inc. differentiates through vertically integrated hemp sourcing and direct-to-consumer channel control.
Cannabidiol oil comprises a non-psychoactive hemp extract standardized to contain less than 0.3% delta-9 tetrahydrocannabinol by dry weight, typically formulated as tinctures, softgels, or topical bases for therapeutic and wellness applications. CO2 extraction dominates premium manufacturing due to solvent-free output and terpene preservation, while solvent extraction occupies cost-sensitive volume tiers. Full spectrum products command the highest consumer preference in wellness retail, whereas isolate formats lead pharmaceutical compounding and international export due to simplified regulatory pathways.
The FDA maintains active oversight of CBD as a drug ingredient under the Federal Food, Drug, and Cosmetic Act, while the USDA administers hemp cultivation compliance through interim final rules on THC testing protocols. The European Food Safety Authority classifies CBD as a novel food, requiring pre-market authorization that filters out undercapitalized suppliers. Stakeholders must monitor pending FDA rulemaking on permitted health claims and dosage thresholds to determine whether to prioritize pharmaceutical development or consumer packaged goods expansion.
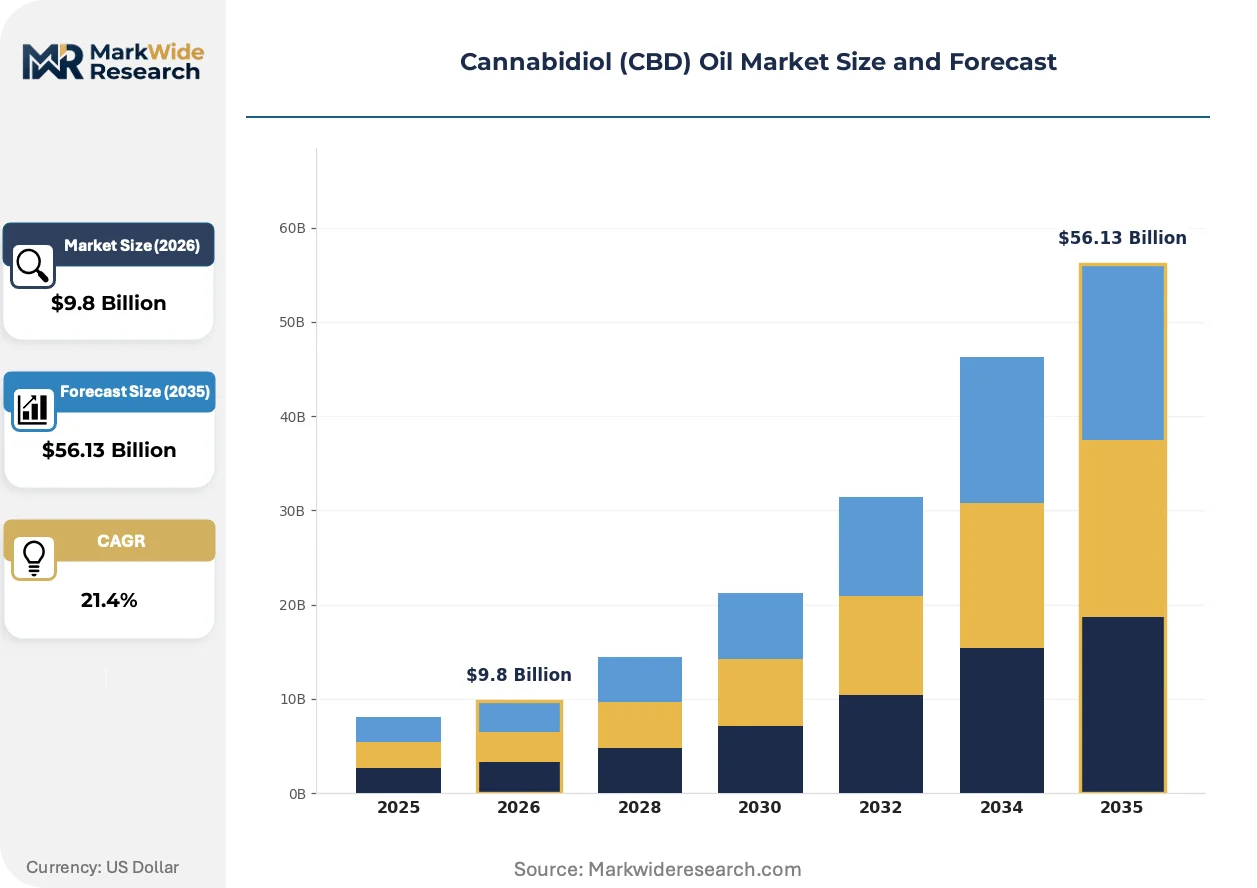
Market Dynamics
FDA enforcement discretion on health claims has compressed the operational runway for CBD oil entrants, forcing capital reallocation from marketing toward toxicology dossiers and cGMP-certified manufacturing infrastructure. This regulatory friction is concentrating production capacity among firms with pharmaceutical-grade certification capabilities.
Growth Catalysts
- US Farm Bill Pathway:The 2018 Farm Bill's hemp reclassification unlocked interstate commerce for derivatives containing under 0.3% THC, enabling scale economies in CO2 extraction infrastructure.
- EFSA Novel Food Authorization:Pre-market safety assessments in Europe are filtering out undercapitalized suppliers, creating shelf-space scarcity that rewards compliant dossier holders with pharmacy network access.
- Topical Formulation Integration:Wellness and personal care brands now specify CBD as a standard active ingredient in dermatological bases, pulling volume through established cosmetic distribution channels.
Market Restraints
- THC Testing Volatility:USDA interim final rules mandate pre-harvest sampling protocols that generate false-positive rates near 5%, destroying crop value and elevating insurance costs for cultivators.
- Extraction Input Concentration:Supercritical CO2 equipment suppliers cluster in Germany and Italy, creating 14-16 week lead times that throttle capacity expansion for North American processors.
- Regulatory Arbitrage Limits:FDA's active oversight under the FD&C Act blocks interstate shipment of CBD-labeled dietary supplements, fragmenting demand across state-by-state compliance regimes.
Strategic Opportunities
- Pharmaceutical Compounding Channel:Isolate formats with simplified DEA scheduling pathways can access hospital formularies and veterinary therapeutics, bypassing crowded wellness retail.
- USDA Organic Certification:The 5-year transition window for hemp acreage creates first-mover advantages in premium pricing tiers for certified organic CBD oil.
- Nanoemulsion Technology Convergence:Lipid-based delivery systems paired with beverage manufacturing partnerships are opening functional drink applications with 5x bioavailability claims.
Industry Challenges
- Analytical Chemistry Talent Scarcity:HPLC method validation for cannabinoid quantification requires specialized chromatography expertise that commands 40% wage premiums over general food safety roles.
- Batch Release Timeline Compression:Third-party laboratory turnaround for Certificate of Analysis documentation now averages 10-14 days, binding working capital in finished goods inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabidiol (CBD) Oil Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $56.13 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Spectrum, Broad Spectrum, Isolate, Crude Extract End User: Retail Customers, Wholesalers, Pharmacies, E-commerce Application: Topical, Edible, Inhalation, Capsules Extraction Method: CO2 Extraction, Solvent Extraction, Olive Oil Extraction, Steam Distillation |
| Companies Covered | Aurora Cannabis Inc., Canopy Growth Corporation, Charlotte's Web Holdings Inc., Elixinol Global, ENDOCA, Medical Marijuana Inc., The Cronos Group, Tilray Brands Inc., GW Pharmaceuticals plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabidiol (CBD) Oil Market Strategic Shifts
Extraction technology maturation and regulatory clarity are bifurcating the competitive landscape into pharmaceutical-grade suppliers and commoditized wellness ingredient providers. Firms are repositioning capital toward either toxicology-heavy drug development or high-throughput CPG manufacturing.
Supercritical CO2 extraction systems with integrated winterization and decarboxylation modules are integrating into mid-scale processing facilities. Craft distilleries and regional hemp cooperatives in Colorado and Oregon are adopting these skid-mounted units to capture margin previously lost to toll processors. The technology is integrating quality control directly into extraction workflows, compressing the need for separate downstream refinement contracts and enabling real-time potency adjustment.
EFSA's novel food safety opinion requirements are reshaping European market access protocols. The mandate for comprehensive toxicological data packages has industrialized the dossier preparation process, with specialized regulatory consultancies now offering fixed-fee submission packages. Pharmaceutical-grade isolate manufacturers with existing stability studies are capturing disproportionate shelf space in German and UK pharmacy chains as food-grade entrants face 18-24 month authorization delays.
Direct-to-consumer subscription models are displacing conventional retail replenishment cycles for tincture and softgel formats. Charlotte's Web and comparable vertically integrated brands are capturing recurring revenue through personalized dosing algorithms and telehealth consultation bundling. This channel pivot is most visible in US metropolitan markets where pharmacy retail access remains restricted by FDA enforcement discretion, pushing demand toward compliant e-commerce fulfillment infrastructure.
Cannabidiol (CBD) Oil Market Segmentation
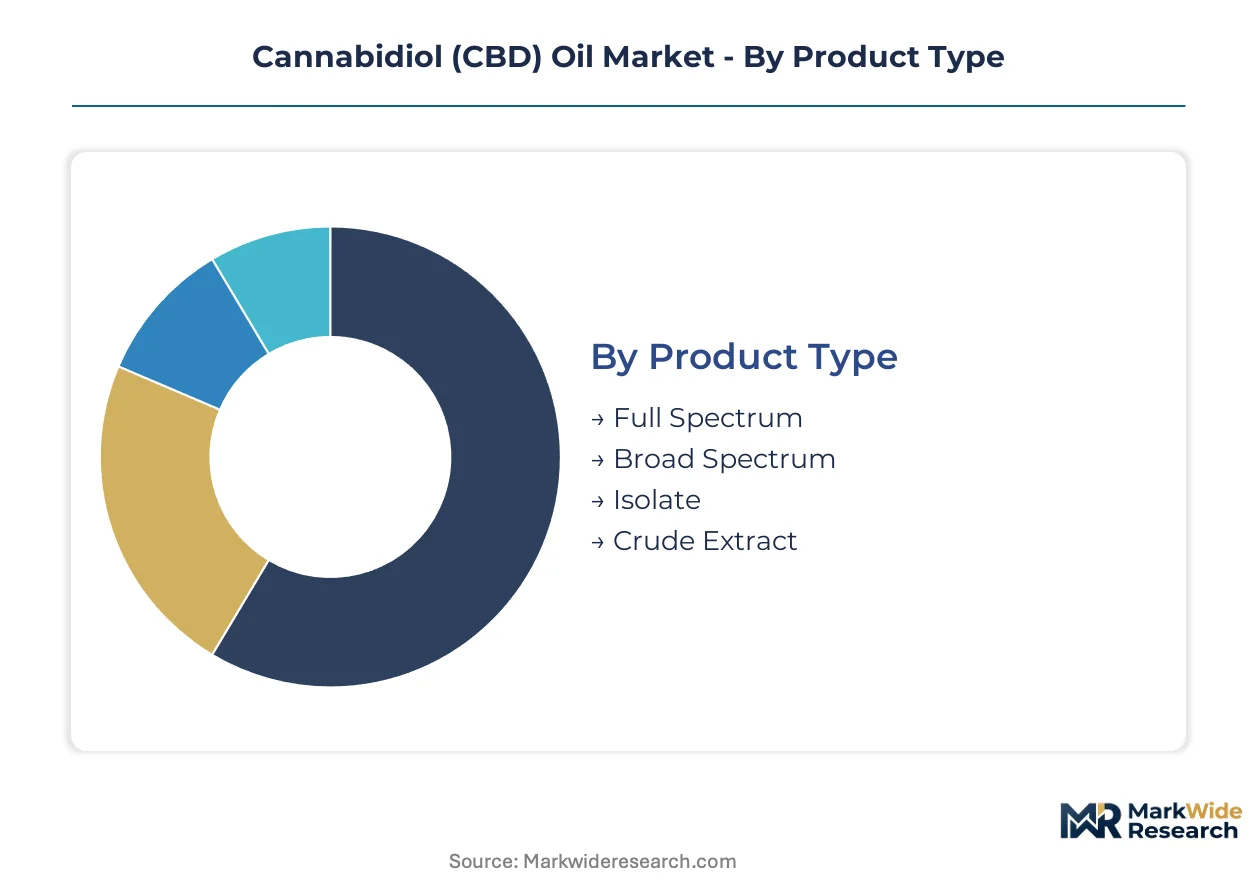
CBD oil segmentation reflects divergent regulatory pathways and margin structures across pharmaceutical, wellness, and commodity ingredient channels. Buyers prioritize different specifications—cannabinoid retention profiles for wellness retail, THC compliance thresholds for pharmacy networks, and input cost efficiency for bulk commodity supply.
Product Type:
Wellness buyers seek entourage-effect formulations; pharmaceutical compounders demand single-molecule purity for dosing precision.
- Full Spectrum:Contains the complete cannabinoid and terpene matrix from hemp biomass, including trace THC below the 0.3% federal threshold. Demand concentrates in US wellness retail channels where consumers prioritize the entourage effect and whole-plant synergy claims. Colorado and Oregon craft processors dominate supply through controlled-environment cultivation partnerships.
- Isolate:Refined to 99%+ pure CBD crystalline form through multi-stage chromatography and winterization. European pharmacy networks in Germany and the UK specify isolate for novel food compliance and simplified EFSA dossier pathways. Pharmaceutical compounding applications favor this format for precise milligram dosing in pediatric and veterinary therapeutics.
- Broad Spectrum:THC-free cannabinoid matrix retaining minor compounds including CBG and CBN. Appeals to athletes and professionals subject to workplace drug screening protocols.
- Crude Extract:Unrefined hemp oil requiring downstream distillation or winterization. Serves as feedstock for toll processors and white-label manufacturers seeking cost-efficient input material.
Volume sits with Full Spectrum wellness formulations; growth tilts toward Isolate formats gaining pharmacy shelf space through EFSA authorization.
End User:
Channel control determines pricing power—direct relationships command premium realization while intermediary layers compress margins.
- Retail Customers:Individual purchasers through brick-and-mortar wellness stores and pharmacy counters. German pharmacy chains require EFSA novel food authorization, filtering out undercapitalized suppliers and creating shelf scarcity for compliant dossier holders.
- E-commerce:Direct-to-consumer platforms with subscription replenishment models and personalized dosing algorithms. US metropolitan markets drive volume where FDA enforcement discretion restricts pharmacy access, pushing demand toward compliant fulfillment infrastructure.
- Pharmacies:Licensed dispensaries and hospital formularies requiring pharmaceutical-grade certification and batch-level Certificate of Analysis documentation.
- Wholesalers:Regional distributors serving independent retailers and cosmetic manufacturers with bulk volume pricing and private-label packaging services.
Transaction volume flows through E-commerce subscriptions; margin expansion concentrates in Pharmacy channels with restricted access credentials.
Application:
Formulation chemistry dictates bioavailability claims and regulatory classification—lipid-based delivery faces novel food scrutiny while topical routes avoid ingestion protocols.
- Topical:Dermatological bases including balms, serums, and transdermal patches. Wellness and personal care brands specify CBD as a standard active ingredient, pulling volume through established cosmetic distribution channels in North American retail.
- Edible:Beverage and food infusions requiring nanoemulsion technology for bioavailability enhancement. Lipid-based delivery systems paired with manufacturing partnerships open functional drink applications with absorption claims.
- Capsules:Softgel and hard-shell formats for precise dosing and extended shelf stability. Preferred by pharmaceutical compounders for hospital formulary inclusion.
- Inhalation:Vaporizable oils and concentrates subject to pulmonary toxicology scrutiny and state-level cannabis regulation variance.
Manufacturing throughput centers on Topical formulations; steepest expansion trajectory belongs to Edible applications leveraging beverage industry partnerships.
Extraction Method:
Capital intensity and output quality separate premium positioning from commodity supply—supercritical systems command 14-16 week lead times from German and Italian equipment suppliers.
- CO2 Extraction:Supercritical carbon dioxide systems delivering solvent-free output with terpene preservation. Premium wellness manufacturers specify this method for full-spectrum retail products; craft distilleries in Colorado adopt skid-mounted units to capture margin previously lost to toll processors.
- Solvent Extraction:Ethanol or hydrocarbon-based processing for cost-sensitive volume tiers. Occupies commodity ingredient supply chains where residual solvent testing adds regulatory compliance burden.
- Olive Oil Extraction:Cold-infusion method for small-batch artisanal production with limited scalability but clean-label appeal.
- Steam Distillation:Terpene isolation technique rarely used for CBD recovery due to cannabinoid degradation at elevated temperatures.
Processing capacity concentrates in CO2 extraction infrastructure; capacity expansion tilts toward solvent methods as ethanol supply chains mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colorado's Opportunity Zone tax incentives have concentrated hemp processing infrastructure along the Front Range corridor, drawing extraction equipment investment and downstream formulation capacity into a tight geographic cluster.
United States
FDA enforcement discretion on interstate CBD commerce has fragmented distribution into state-specific compliance regimes, while the USDA administers pre-harvest THC testing protocols that generate false-positive risks near 5%. Colorado and Oregon craft processors dominate full-spectrum supply through controlled-environment cultivation partnerships.
Germany
EFSA novel food authorization requirements filter undercapitalized suppliers from pharmacy shelf access, creating scarcity premiums for dossier-compliant isolate manufacturers. The country's pharmaceutical distribution networks specify pharmaceutical-grade certification and batch-level documentation for hospital formulary inclusion.
United Kingdom
Post-Brexit regulatory divergence from EU novel food frameworks has opened parallel authorization pathways that extend timeline uncertainty for continental suppliers. London-based wellness retail channels drive e-commerce subscription volume where pharmacy access remains restricted.
Canada
Health Canada's cannabis regulations provide clearer federal pathways for CBD as a controlled substance derivative, contrasting with US interstate commerce fragmentation. British Columbia and Ontario processing clusters leverage existing licensed producer infrastructure for extraction scale economies.
Switzerland
Swissmedic's distinct regulatory framework permits CBD with up to 1% THC content, attracting formulation tourism and regional distribution hub status. Geneva and Basel pharmaceutical service providers industrialize toxicology dossier preparation for EFSA-aligned market access.
Cannabidiol (CBD) Oil Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a market structure bifurcating between pharmaceutical-grade certification holders and commoditized wellness ingredient suppliers. Tiered concentration emerges: multinational cannabis operators with downstream extraction assets anchor the premium tier, while regional hemp cooperatives and craft processors occupy mid-market positioning through controlled-environment cultivation partnerships. Dominant competitive moves include pharmaceutical-grade certification acquisition for restricted channel access and backward integration into captive hemp supply to secure input cost stability.
Among North American operators, Canopy Growth Corporation and Tilray Brands Inc. exemplify the diversified multinational archetype with pharmaceutical-grade certification capabilities, while Charlotte's Web Holdings Inc. represents vertically integrated specialists leveraging direct-to-consumer channel control. These three entities occupy distinct positioning vectors: certification-heavy drug development, high-throughput consumer packaged goods manufacturing, and subscription-driven wellness retail respectively.
| Leading Market Players |
|---|
| Aurora Cannabis Inc. |
| Canopy Growth Corporation |
| Charlotte's Web Holdings Inc. |
| Elixinol Global |
| ENDOCA |
| Medical Marijuana Inc. |
| The Cronos Group |
| Tilray Brands Inc. |
| GW Pharmaceuticals plc. |
| Others |
Value Chain & Pricing Dynamics
Captive hemp cultivation through controlled-environment partnerships anchors both input security and premium pricing power for full-spectrum processors, while toll-dependent operators absorb margin compression from extraction equipment lead times and third-party testing bottlenecks. This integration choice separates pharmacy-grade isolate manufacturers commanding scarcity premiums from commoditized crude extract suppliers competing on biomass throughput.
Pricing Analysis
Fourteen-to-sixteen-week lead times for German and Italian supercritical CO2 equipment create premium pricing tiers for processors with installed capacity, while spot-market crude extract trades at discounts reflecting downstream refinement requirements. Three-tier pricing structure across pharmaceutical-grade isolate, premium full-spectrum, and commodity crude levels differentiates by certification tier and cannabinoid retention profile. Cost compression in crude extract tiers is intensifying because toll processor overcapacity and hemp biomass oversupply concentrate bargaining power with biomass aggregators. Wellness retail buyers show highest price sensitivity, whereas hospital formularies and pharmacy networks prioritize batch documentation and DEA scheduling compliance over unit cost.
Supply Chain Analysis
Direct-to-pharmacy channels handle German and UK hospital formulary demand, while e-commerce fulfillment infrastructure serves US metropolitan markets where FDA enforcement discretion fragments retail access. Geographic supply concentrates in Colorado and Oregon craft processing clusters, Italian and German extraction equipment manufacturing hubs, and Canadian licensed producer infrastructure drawing from British Columbia cultivation zones. Raw material flows rest on hemp biomass from controlled-environment partnerships, supercritical CO2 systems with integrated winterization modules, and HPLC-grade reference standards for cannabinoid quantification. Single-source vulnerability sits with German and Italian equipment suppliers, where concentrated manufacturing capacity creates chokepoint exposure for North American processor expansion. Distribution runs through pharmacy networks in Europe, wellness retail chains in North America, and direct-to-consumer subscription platforms where compliance infrastructure substitutes for restricted physical retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction with integrated quality control modules is displacing legacy toll-processing arrangements, compressing batch release timelines and enabling real-time potency adjustment that legacy outsourced refinement cannot match.
For Market Incumbents: Acquire pharmaceutical-grade certification capabilities to defend pharmacy channel access against EFSA novel food authorization requirements that filter undercapitalized competitors. Backward integration into captive hemp supply secures input cost stability against USDA pre-harvest THC testing volatility that destroys crop value. Capacity addition in Colorado and Oregon controlled-environment cultivation partnerships reinforces full-spectrum positioning against isolate-focused entrants.
For New Entrants and Emerging Players: Pharmacy network partnerships in Germany and the UK represent the most penetrable white-space target, where EFSA dossier delays create 18-to-24-month scarcity windows for compliant isolate manufacturers. Nanoemulsion technology convergence with beverage manufacturing partnerships opens functional drink applications bypassing crowded wellness retail. Direct-to-consumer subscription bundling with telehealth consultation services offers go-to-market differentiation where FDA enforcement discretion restricts pharmacy access.
For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade certification holders with existing EFSA novel food dossiers and stability studies, positioned for hospital formulary inclusion and veterinary therapeutics compounding. Long-term viability favors vertically integrated operators with controlled-environment cultivation assets and downstream extraction infrastructure, as toll-processing margin compression accelerates consolidation. Pending FDA rulemaking on permitted health claims and dosage thresholds signals the inflection point between pharmaceutical development prioritization and consumer packaged goods expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Submission | Pre-market authorization unlocks German and UK pharmacy network shelf access for isolate manufacturers. |
| Supercritical CO2 Capacity Expansion | Integrated winterization modules compress batch release timelines and capture margin from toll processors. |
| Direct-to-Consumer Subscription Launch | Personalized dosing algorithms with telehealth bundling displace conventional retail replenishment cycles. |
| Captive Hemp Cultivation Partnership | Controlled-environment supply secures input cost stability against USDA THC testing volatility. |
| Nanoemulsion Technology Partnership | Lipid-based delivery systems with beverage manufacturers open functional drink applications with bioavailability claims. |
Study Parameters
Independent corroboration across extraction equipment manufacturers, hemp cultivation cooperatives, and pharmacy procurement directors underwrites the qualitative findings on capacity constraints and channel access dynamics. Primary interviews with regulatory affairs consultants, toxicology dossier specialists, and wellness brand formulation scientists combined with secondary validation from FDA enforcement discretion documentation, EFSA novel food safety opinions, and USDA interim final rule filings. Bottom-up triangulation across state-level hemp program administrators and top-down reconciliation through customs trade data on extraction equipment imports anchored supply-side sizing.
Rate-of-change decomposition across the analysis window separated volume expansion from price realization effects, with CAGRs derived from segment-level growth trajectory convergence. Segmentation dimensions modeled include product type spectrum, end-user channel structure, application formulation chemistry, and extraction method capital intensity. Industry-specific forecast inputs incorporated EFSA authorization pipeline status, FDA rulemaking timeline uncertainty, and supercritical equipment order backlogs from German and Italian suppliers.
Several conditions sit outside the modeled scope, including pending FDA final rulemaking on permitted health claims, DEA scheduling pathway revisions for isolate formats, and state-level hemp program regulatory divergence. Forecasts reflect assumptions on EFSA novel food authorization timelines, USDA THC testing protocol stability, and pharmacy network shelf-space allocation continuity. Periodic stress-testing of base assumptions is recommended against regulatory enforcement discretion shifts and extraction equipment supply chain disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
CBD Pouches Market