
 Medical Cannabis Market | 2026-2036
Medical Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Cannabis Market Intelligence
Subscription-based physician consultation platforms is repositioning how medical cannabis reaches patients, shifting transactions toward recurring care relationships rather than single-product purchases. Curaleaf Holdings Inc. leverages vertically integrated cultivation networks across multiple state jurisdictions. Green Thumb Industries anchors its position through branded retail dispensaries with controlled patient education protocols. Tilray Brands Inc. competes on pharmaceutical-grade manufacturing certifications that meet strict quality benchmarks.
Medical cannabis comprises dried flower, extracts, and synthesized cannabinoid formulations standardized for delta-9-tetrahydrocannabinol and cannabidiol concentrations, produced through supercritical CO2 extraction or ethanol-based refinement for therapeutic dosing consistency. Its primary purpose is to deliver symptom relief for conditions where conventional pharmaceuticals demonstrate insufficient efficacy or unacceptable side-effect profiles. Oil formulations command the dominant share of product type revenue due to superior shelf stability and precise titration capabilities. Chronic pain therapy areas generate the largest patient volumes, though epilepsy applications attract premium pricing tied to orphan-drug positioning. Inhalation delivery modes retain established user bases, yet oral formats capture the fastest growth as geriatric and pediatric populations require non-smoking administration pathways.
The FDA maintains Schedule I restrictions on cannabis-derived compounds while permitting Epidiolex as an approved prescription therapy, creating a bifurcated compliance environment where pharmaceutical pathways diverge from state-regulated medical programs. Germany's BfArM and Australia's TGA impose batch-testing requirements and GMP manufacturing standards that filter out uncertified suppliers. Stakeholders must monitor how rescheduling proceedings and insurance reimbursement expansions reshape competitive entry barriers without assuming uniform federal alignment.
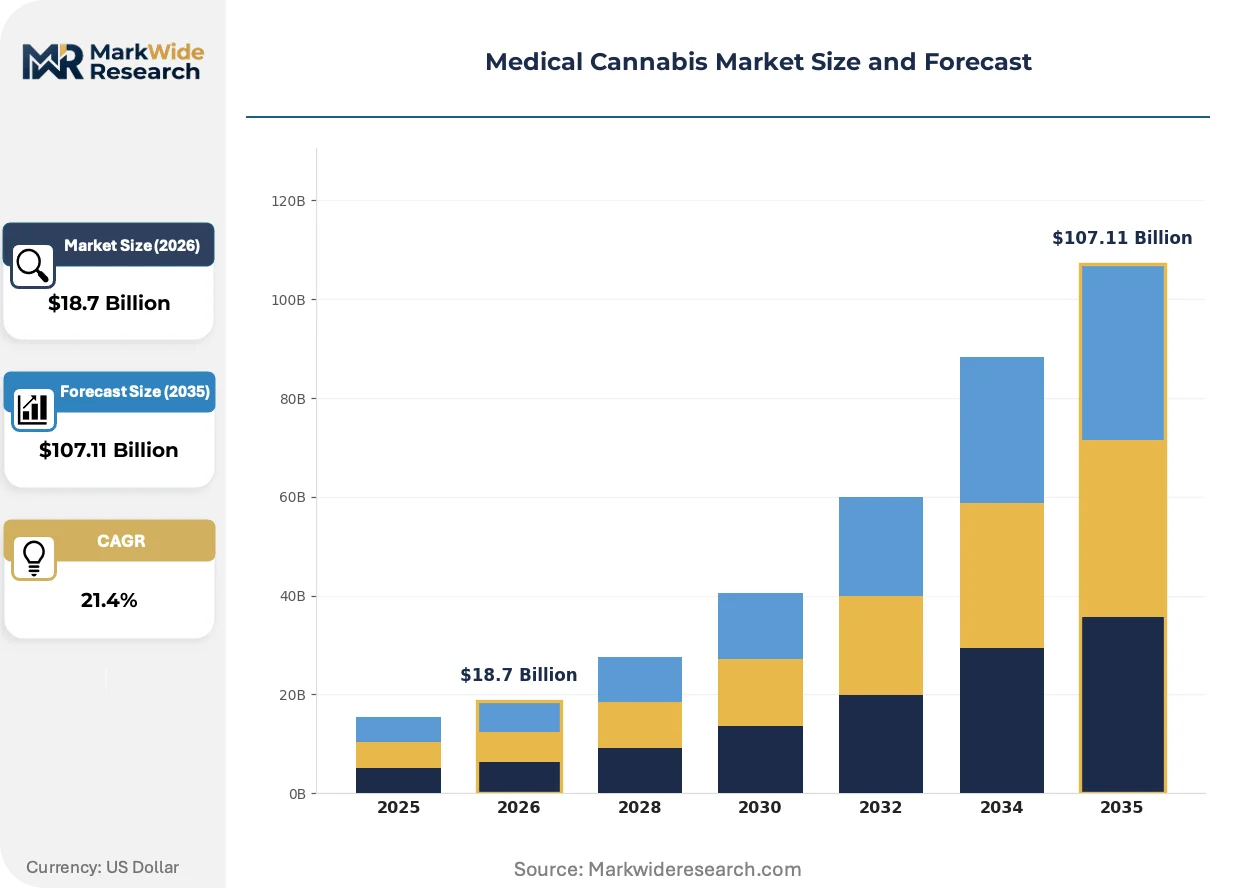
Market Dynamics
The medical cannabis sector is experiencing a fundamental restructuring as insurance reimbursement frameworks in Germany and Australia expand coverage for prescription cannabinoids, forcing cultivators to adopt pharmaceutical-grade manufacturing standards or exit regulated channels entirely.
Growth Catalysts
- BfArM Licensing Streamlining:Germany's federal cannabis agency has reduced domestic cultivation permit processing timelines, enabling local producers to displace imported supply in hospital pharmacy channels.
- Chronic Pain Protocol Expansion:North American hospital systems are integrating standardized cannabinoid therapies into multidisciplinary pain management programs, creating institutional demand pull.
- Supercritical CO2 Extraction Scale-Up:Equipment manufacturers have deployed larger-capacity systems that reduce per-unit extraction costs while improving delta-9-THC consistency for oral formulations.
Market Restraints
- FDA Schedule I Classification:Federal restrictions on cannabis-derived compounds prevent interstate banking access and limit institutional capital deployment in US markets.
- Input Supply Concentration:Pharmaceutical-grade ethanol for cannabinoid refinement is sourced from a limited number of chemical suppliers, creating vulnerability to price volatility.
- Batch Testing Bottlenecks:Australia's TGA and Germany's BfArM impose mandatory third-party laboratory verification that extends time-to-market for new product launches.
Strategic Opportunities
- Japan's PMDA Pathway:The pharmaceutical regulator's emerging framework for cannabidiol isolate prescriptions offers first-mover positioning in an underpenetrated East Asian market.
- Pediatric Epilepsy Formulations:Orphan-drug positioning for rare seizure disorders commands premium pricing and accelerated regulatory review timelines.
- Subscription Care Platforms:Recurring physician consultation models are displacing transactional dispensary relationships, enabling patient data capture and adherence monitoring.
Industry Challenges
- GMP Certification Timelines:Good Manufacturing Practice compliance for EU market access requires 18-24 month facility validation processes that strain working capital.
- Formulation Standardization Delays:Inconsistent delta-9-THC degradation rates across oil-based products complicate shelf-life claims and insurance formulary acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Cannabis Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Capsule, Tincture, Topical Therapy Area: Chronic Pain, Epilepsy, Cancer, Multiple Sclerosis Delivery Mode: Inhalation, Oral, Transdermal, Vaporization End User: Hospitals, Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | Curaleaf Holdings Inc., Green Thumb Industries, Tilray Brands Inc., Canopy Growth Corporation, Aurora Cannabis Inc., Trulieve Cannabis Corp., Jazz Pharmaceuticals plc, Verano Holdings, Acreage Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Cannabis Market Strategic Shifts & Innovations
Pharmaceutical manufacturing methodologies are penetrating medical cannabis production, compressing quality variance between regulated and legacy supply channels while enabling new delivery formats.
Nanoemulsion technology is unifying lipid-soluble cannabinoid delivery with aqueous beverage matrices, enabling precise dose titration in liquid formats. Geriatric care facilities in Germany and Australia are adopting these formulations for patients with dysphagia. The technology is unifying previously separate pharmaceutical and nutraceutical manufacturing competencies within single production facilities.
Germany's BfArM has implemented mandatory serialization requirements for all prescription cannabis products, forcing supply chain transparency upgrades across import and domestic distribution networks. Wholesale distributors must now maintain end-to-end track-and-trace infrastructure previously required only for controlled synthetic pharmaceuticals. Smaller cultivators without ERP integration capabilities are consolidating into licensed pharmacy cooperative structures.
Hospital procurement committees are consolidating vendor relationships around suppliers with dual GMP and EU-GDP certifications, displacing fragmented multi-source purchasing patterns. This concentration is most visible in German statutory health insurance reimbursement channels, where single-source contracts now cover standardized oil formulations for chronic pain cohorts. Dispensary-direct purchasing persists in cash-pay segments but is losing share in institutional settings.
Medical Cannabis Market Segmentation
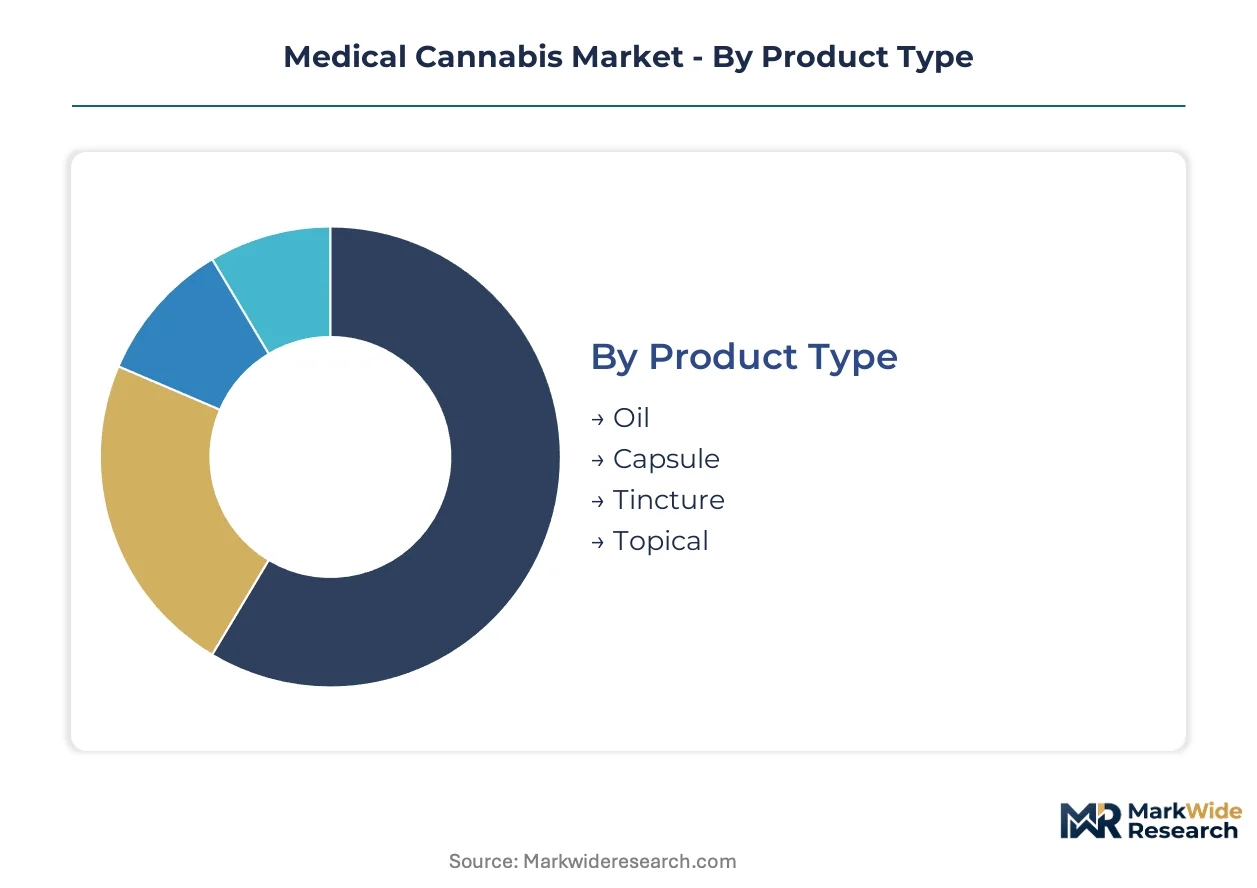
Medical cannabis segmentation reveals how regulatory frameworks fragment commercial pathways. Certification requirements vary sharply across product formats, creating divergent margin structures and competitive moats for compliant versus non-compliant suppliers.
Product Type:
Oil formulations carry the heaviest GMP certification burden for EU market access, while topicals navigate lighter cosmetic-grade pathways in most jurisdictions.
- Oil:Supercritical CO2 extraction yields standardized delta-9-THC and cannabidiol concentrations with shelf stability exceeding 24 months. German statutory health insurance reimbursement channels concentrate demand for pharmaceutical-grade oil, though batch-testing bottlenecks at BfArM-authorized laboratories constrain supply expansion.
- Capsule:Hard-shell gelatin and HPMC encapsulation enable precise unit dosing for geriatric populations with dysphagia. Australian TGA registration requirements for capsule formats are accelerating consolidation among manufacturers with in-house tableting capabilities.
- Tincture:Ethanol-based extraction preserves minor cannabinoid profiles for boutique therapeutic positioning.
- Topical:Transdermal penetration enhancers face variable cosmetic-versus-pharmaceutical classification across state-level US jurisdictions.
Oil sits at the top of the volume ranking, with capsules climbing the fastest.
Therapy Area:
Cost tier stratification separates orphan-drug premium positioning from commoditized chronic pain management.
- Chronic Pain:Multidisciplinary hospital protocols in Germany and North America generate institutional procurement volumes for standardized cannabinoid therapies. Insurance reimbursement expansion is compressing margins on non-specialized formulations while creating volume anchors for GMP-certified suppliers.
- Epilepsy:Dravet and Lennox-Gastaut syndrome applications command premium pricing tied to FDA-approved Epidiolex positioning and accelerated regulatory review pathways. Australia's TGA orphan-drug framework offers analogous commercial advantages for compliant entrants.
- Cancer:Chemotherapy-induced nausea applications compete with established 5-HT3 antagonist pricing benchmarks.
- Multiple Sclerosis:Spasticity management indications face reimbursement scrutiny from UK's NICE and comparable health technology assessment bodies.
Chronic pain captures the largest patient volumes, with epilepsy delivering the steepest expansion trajectory.
Delivery Mode:
Patient age demographics are forcing migration from inhalation toward formats compatible with institutional care settings.
- Inhalation:Dried flower vaporization retains established user bases in North American dispensary channels but faces exclusion from German hospital pharmacy procurement due to dosing inconsistency concerns. Combustion-based inhalation is losing reimbursement eligibility across Australian private insurance frameworks.
- Oral:Sublingual sprays and oromucosal solutions enable precise titration for pediatric epilepsy protocols. Japan's PMDA emerging cannabidiol pathway prioritizes oral formats with pharmaceutical-grade stability data.
- Transdermal:Patch technologies require novel excipient registrations that extend time-to-market in EU member states.
- Vaporization:Medical device classification in Germany and Canada imposes additional conformity assessment burdens on hardware suppliers.
Inhalation retains volume leadership among legacy patient cohorts, with oral formats gaining share fastest.
End User:
Procurement concentration is shifting toward integrated health systems with centralized formulary control.
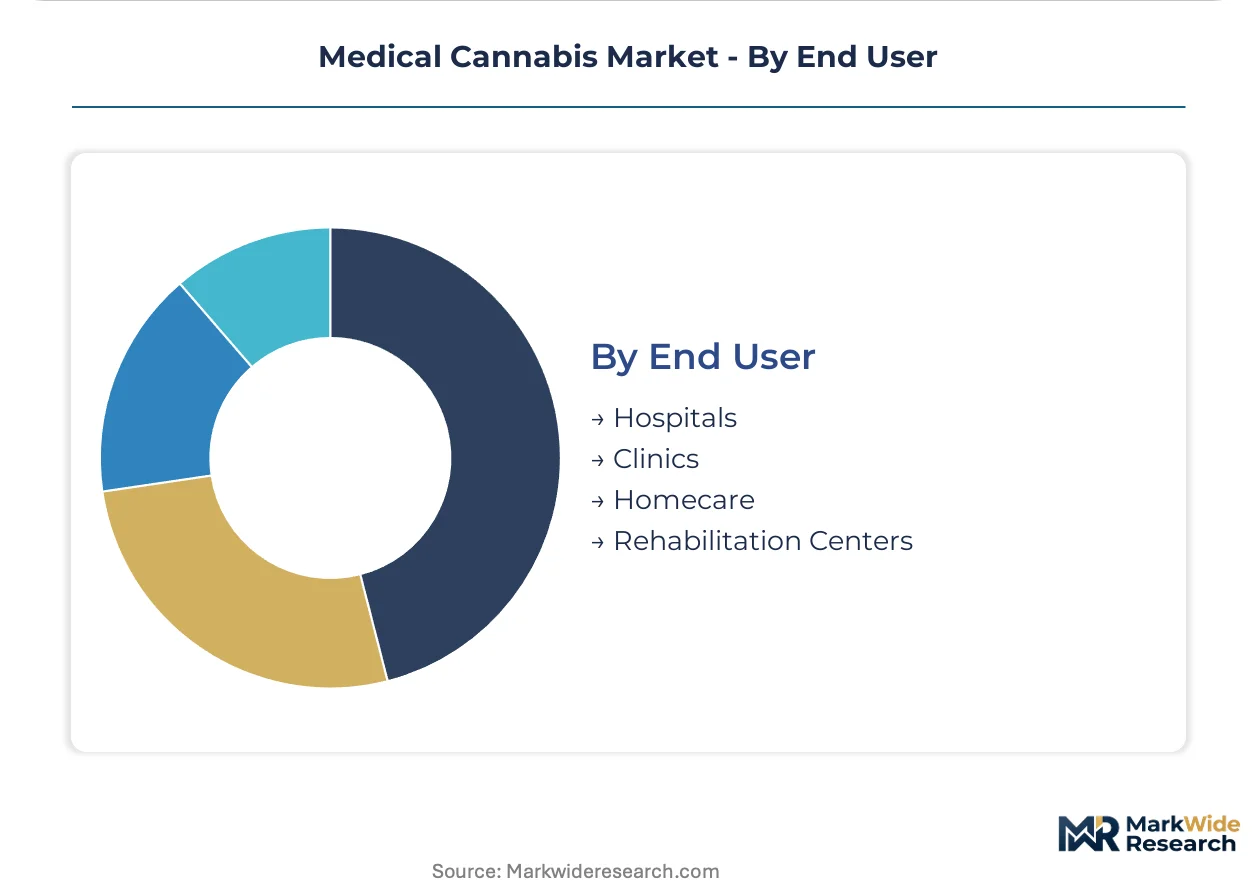
- Hospitals:German statutory health insurance contracting now consolidates around single-source suppliers with dual GMP and EU-GDP certifications, displacing fragmented multi-source purchasing. North American academic medical centers are embedding cannabinoid protocols within accredited pain management programs.
- Homecare:Subscription-based physician consultation platforms are repositioning patient access toward recurring care relationships with dose monitoring capabilities. Australia's TGA Special Access Scheme enables direct-to-patient dispensing for homecare segments.
- Clinics:Private pain management practices in US state-regulated programs face banking access constraints from FDA Schedule I classification.
- Rehabilitation Centers:Workers' compensation reimbursement variability creates geographic concentration in Canadian and Australian markets.
Hospitals command the dominant procurement volumes, with homecare expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance reimbursement expansion contrasts with Australia's Special Access Scheme limitations, revealing how divergent regulatory architectures shape patient access velocity across comparable developed markets.
United States
FDA Schedule I classification restricts interstate banking access for state-regulated medical cannabis operators, while institutional capital deployment remains constrained. The 2024 Farm Bill deliberations signal potential cannabidiol pathway clarifications. California's Central Valley cultivation clusters and Colorado's Denver metro extraction facilities concentrate vertically integrated supply capacity.
Germany
BfArM licensing streamlining reduced domestic cultivation permit timelines from 18 months to 8 months, accelerating local production scale-up. Statutory health insurance reimbursement now covers standardized oil formulations for chronic pain, creating volume anchors. North Rhine-Westphalia's pharmaceutical manufacturing corridor hosts GMP-certified extraction facilities serving hospital pharmacy channels.
Australia
TGA Special Access Scheme Category B enables specialist physician prescribing for unapproved therapeutic goods, though batch-testing bottlenecks at authorized laboratories extend product launch timelines. Private insurance frameworks increasingly exclude combustion-based inhalation formats. Victoria's Gippsland region and Queensland's Sunshine Coast host licensed domestic cultivation operations.
Canada
Health Canada's cannabis regulations permit direct-to-consumer medical sales parallel to recreational channels, preserving distinct patient access pathways. Workers' compensation boards in British Columbia and Alberta expanded cannabinoid therapy coverage for chronic pain claims. Ontario's Niagara region and British Columbia's Okanagan Valley concentrate greenhouse cultivation infrastructure.
Japan
PMDA's emerging cannabidiol isolate prescription framework prioritizes pharmaceutical-grade stability data and oral delivery formats. The regulator's 2023 guidance document established purity thresholds that filter out non-pharmaceutical supply sources. Tokyo's pharmaceutical R&D corridor and Osaka's manufacturing hub attract first-mover positioning for compliant entrants.
Medical Cannabis Market Key Industry Players
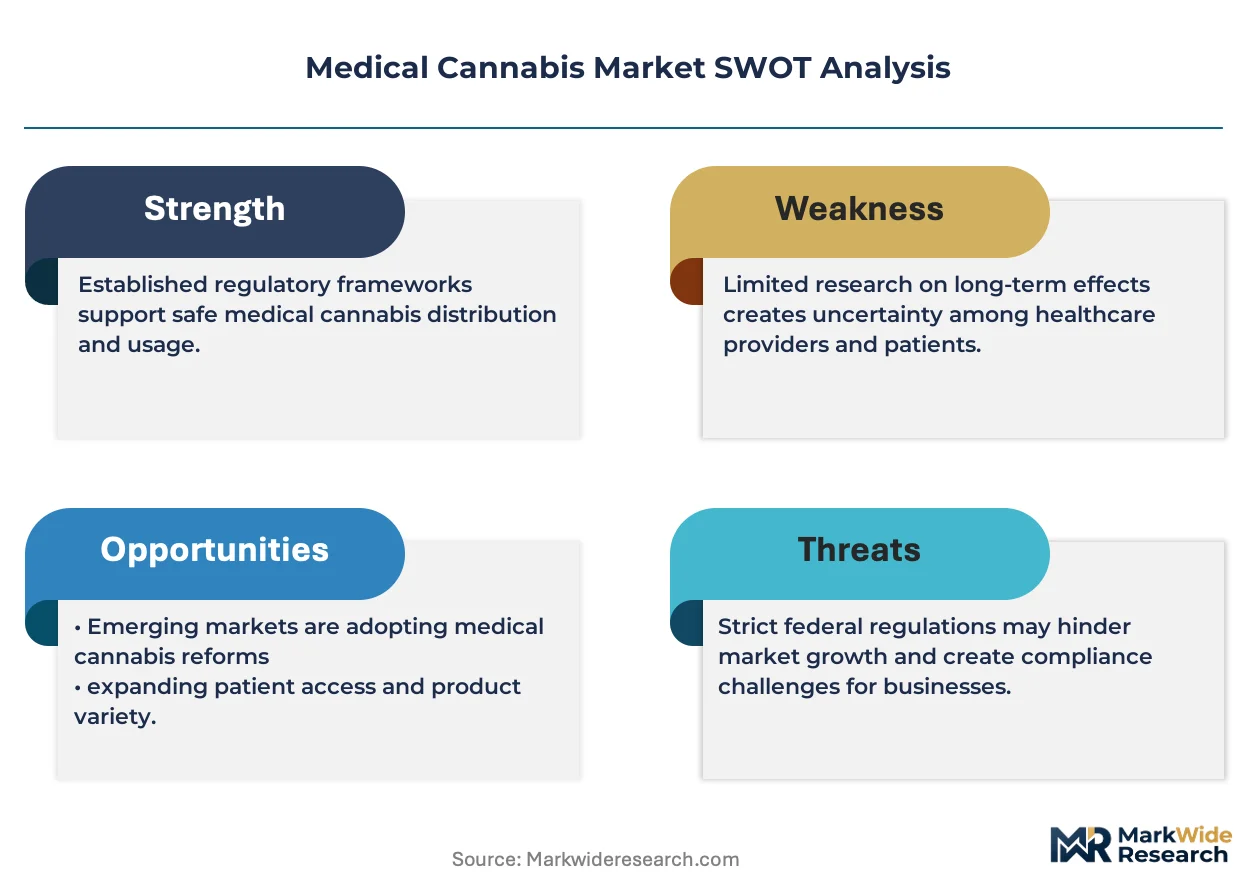
Top-tier vendors anchor GMP-certified pharmaceutical channels, while mid-tier operators compete in state-regulated dispensary networks with fragmented compliance requirements. The vendor base stratifies across three archetypes: vertically integrated multi-state operators, pharmaceutical-grade manufacturers with dual EU-GDP certifications, and subscription-based physician consultation platforms. Capacity expansion into supercritical CO2 extraction infrastructure and strategic pharmacy cooperative consolidations represent dominant competitive vectors.
Within the vertically integrated tier, Curaleaf Holdings Inc. and Green Thumb Industries exemplify multi-jurisdictional cultivation and retail positioning, while Tilray Brands Inc. occupies a pharmaceutical-grade manufacturing niche with EU market access capabilities.
| Leading Market Players |
|---|
| Curaleaf Holdings Inc. |
| Green Thumb Industries |
| Tilray Brands Inc. |
| Canopy Growth Corporation |
| Aurora Cannabis Inc. |
| Trulieve Cannabis Corp. |
| Jazz Pharmaceuticals plc |
| Verano Holdings |
| Acreage Holdings |
| Others |
Cost & Logistics Intelligence
German statutory health insurance reimbursement expansion for pharmaceutical-grade oil formulations is forcing cultivators to absorb GMP certification costs or surrender institutional contracts to compliant competitors, compressing margins on non-certified supply while premium tiers capture pricing power through batch-tested consistency guarantees.
Pricing Analysis
Capacity additions in Germany's North Rhine-Westphalia pharmaceutical corridor are reshaping price floors for GMP-certified extracts, displacing premium import premiums that previously protected Canadian and Dutch suppliers. Three-tier pricing structure across pharmaceutical-grade, medical-use, and wellness channels separates EU-GDP certified oils from state-regulated dispensary products from unregulated hemp-derived alternatives. Cost compression in the wellness tier is intensifying because Australian and German regulators are tightening purity thresholds that filter out uncertified suppliers. Hospital procurement committees demonstrate the lowest price sensitivity due to single-source contracting power, while homecare patients through subscription platforms show moderate sensitivity to dose-precision premiums.
Supply Chain Analysis
Product returns and batch-failure flows from BfArM-mandated laboratory testing create reverse-logistics burdens that smaller cultivators cannot absorb, accelerating consolidation into pharmacy cooperatives with integrated quality control. Cultivation concentrates in Canada, Germany, and Australia, with extraction and formulation capacity clustering in North Rhine-Westphalia and Ontario's Niagara region. Pharmaceutical-grade ethanol for cannabinoid refinement draws from limited chemical suppliers, creating single-source vulnerability for GMP-certified manufacturers. Distribution runs through hospital pharmacy channels in Germany, direct-to-patient Special Access Scheme pathways in Australia, and vertically integrated retail dispensaries in North American state-regulated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where patient outcomes data and insurance formulary acceptance now outweigh first-mover advantages, with demand shifting toward pharmaceutical-grade specifications that only certified manufacturers can satisfy.
For Market Incumbents: Extend GMP certification coverage into pediatric epilepsy formulations to capture orphan-drug premium positioning before Australia's TGA and Japan's PMDA finalize comparable pathways. Backward integration into supercritical CO2 extraction equipment ownership defends margin position against input cost volatility from specialized machinery suppliers. Curaleaf Holdings Inc. and Tilray Brands Inc. demonstrate how dual EU-GDP and GMP credentials create procurement moats that fragment competitors into cash-pay dispensary channels. For New Entrants and Emerging Players: Begin with Japan's PMDA cannabidiol isolate pathway, where pharmaceutical-grade stability requirements filter out incumbent cannabis suppliers lacking small-molecule pharmaceutical manufacturing experience. Australia's TGA Special Access Scheme Category B offers the most penetrable entry point for compliant oil formulations targeting specialist physician prescribing networks. A subscription-based physician consultation platform with integrated dose monitoring captures patient data assets that incumbent dispensary models cannot replicate. For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade manufacturers possessing dual GMP and EU-GDP certifications, as hospital procurement consolidation favors single-source suppliers with institutional track records. Long-term viability hinges on formulary acceptance velocity across German statutory health insurance and Australian private reimbursement frameworks. Watch for FDA rescheduling proceedings as the inflection indicator that would unlock interstate banking access and institutional capital deployment in US markets.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Expansion | BfArM and TGA batch-testing requirements filter out uncertified competitors from hospital pharmacy channels. |
| Subscription Care Platform Launch | Recurring physician consultation models capture patient adherence data that insurers value for risk-based contracting. |
| Pediatric Epilepsy Formulation Development | Orphan-drug positioning commands premium pricing through accelerated regulatory review at FDA and TGA. |
| Supercritical CO2 Extraction Scale-Up | Larger-capacity systems reduce per-unit costs while improving delta-9-THC consistency for oral formulations. |
| Japan PMDA Pathway Entry | First-mover positioning in East Asia's emerging cannabidiol prescription market rewards pharmaceutical-grade stability expertise. |
Research Approach
Coverage spans Germany, Australia, Canada, the United States, and Japan, with primary inputs from each market's regulatory cluster. Primary interviews with drug development executives, regulatory affairs leads at BfArM and TGA, hospital procurement managers, and formulary directors combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and statutory health insurance reimbursement databases. Bottom-up patient volume estimates by therapy area triangulated against top-down market value reconstructions from customs and trade data.
Granularity-level modeling operated at product type, therapy area, delivery mode, and end-user dimensions, with additional segmentation by regulatory framework cluster. CAGRs derived from fitted growth curves applied to base-year estimates across the projection horizon, with cross-checks against equipment manufacturer order backlogs and cultivation license issuance rates. Forecast inputs included BfArM permit processing timelines, TGA batch-testing capacity expansion, and PMDA guidance document implementation trajectories.
Several conditions sit outside the modeled scope, including FDA Schedule I rescheduling outcomes, German recreational cannabis legalization impacts on medical channel diversion, and raw material price shocks in pharmaceutical-grade ethanol supply. Practitioners should monitor regulatory harmonization signals between EU member states and insurance reimbursement expansion velocity for early indicators of competitive entry barrier shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Global Cannabis Extract Market