
 Synthetic Cannabinoids Market | 2026-2036
Synthetic Cannabinoids Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Cannabinoids Market Outlook
Modular formulation packaging is decoupling research-grade from pharmaceutical-grade procurement, giving buyers flexibility to source by purity tier rather than bundled catalog offerings. Cayman Chemical leverages captive synthesis capabilities to sustain leadership in certified reference standards. Johnson Matthey anchors high-volume pharmaceutical supply through in-house production of active pharmaceutical ingredients. Purisys LLC differentiates via geographic dominance in North American custom synthesis for preclinical programs.
Synthetic cannabinoids comprise laboratory-engineered compounds that mimic delta-9-tetrahydrocannabinol by binding to CB1 and CB2 receptors, typically synthesized via condensation reactions between indole or indazole cores and naphthoyl or adamantoyl substituents for receptor affinity modulation. These compounds serve primarily as controlled-substance analogs for forensic calibration, neuropharmacology research, and emerging therapeutic pipelines targeting spasticity and chemotherapy-induced nausea. Research applications occupy the largest volume share due to sustained demand from forensic laboratories and academic institutions requiring DEA-compliant reference materials. Pharmaceutical development represents the fastest-expanding segment as cannabinoid receptor modulators advance through clinical trials for rare neurological indications. Raw powder formulations dominate procurement among research laboratories, while liquid formulations capture margin concentration in therapeutic development due to stricter stability and bioavailability specifications.
The US Drug Enforcement Administration schedules novel synthetic cannabinoids under the Controlled Substances Act, compelling manufacturers to maintain Schedule I compliance and batch-level documentation for interstate distribution. The European Medicines Agency and national competent authorities in Germany and France enforce Good Manufacturing Practice certification for cannabinoid active substances entering clinical trials, raising barriers for uncertified suppliers. Stakeholders must monitor evolving substance-specific scheduling decisions and invest in analytical method validation to preserve market access across jurisdictions.
Market Dynamics
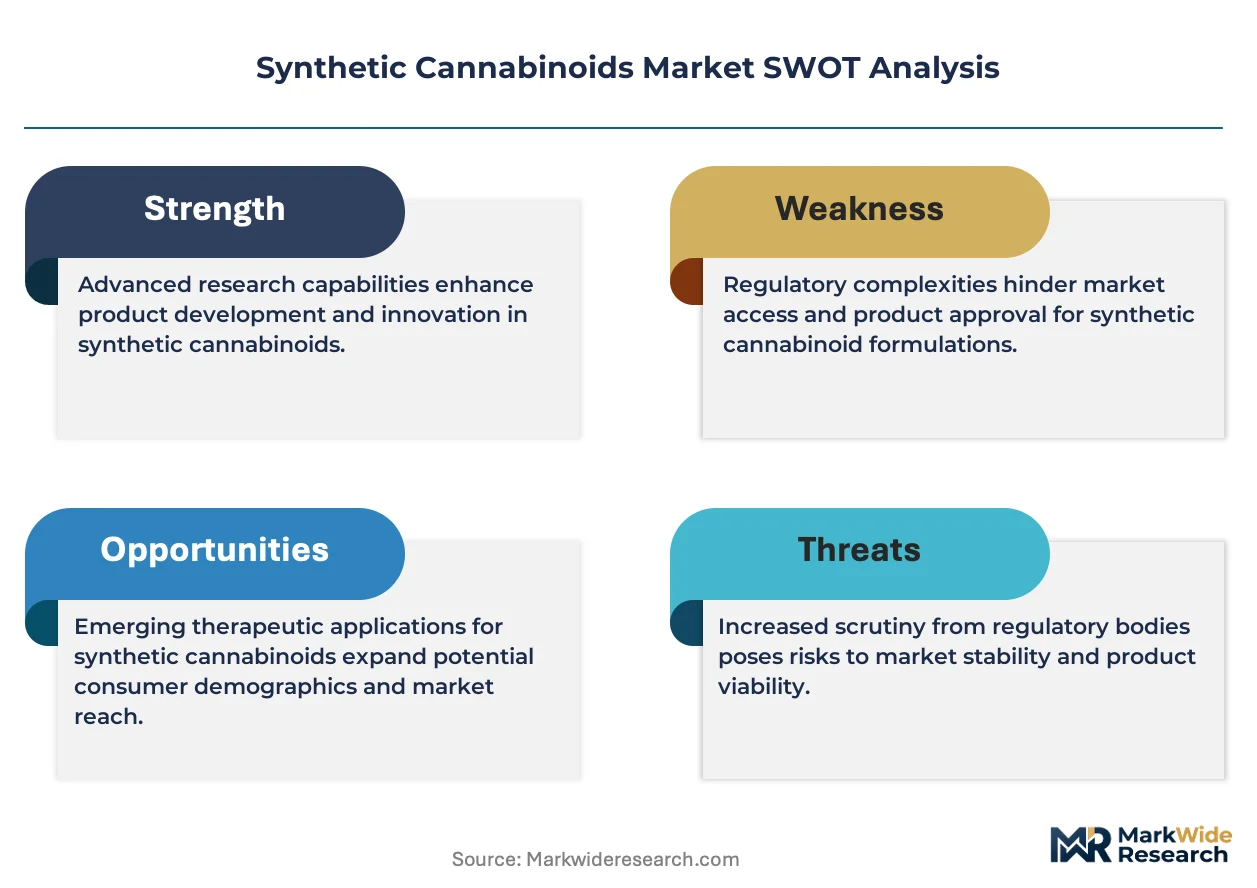
Regulatory fragmentation between research-grade and pharmaceutical-grade pathways is forcing suppliers to maintain dual compliance architectures, diverting capital from R&D toward documentation and certification infrastructure.
Growth Catalysts
- EMA clinical trial pathways:Germany and France have streamlined cannabinoid active substance approvals, accelerating pharmaceutical pipeline entry for European developers.
- Forensic reference standard demand:DEA-compliant batch certification requirements from US crime laboratories sustain recurring procurement of high-purity analytical materials.
- Spasticity therapeutics:Neurology clinics in the United Kingdom are expanding off-label cannabinoid receptor modulator protocols ahead of formal indication approvals.
Market Restraints
- Indole core supply concentration:Three Chinese chemical manufacturers control bulk indole production, creating price volatility and import dependency for Western synthesizers.
- Schedule I documentation burden:The US Controlled Substances Act mandates batch-level chain-of-custody records that add administrative overhead exceeding standard pharmaceutical APIs.
- Analytical method obsolescence:Rapid substance scheduling updates render validated detection protocols obsolete within 18-24 months, forcing continuous revalidation investment.
Strategic Opportunities
- Canadian therapeutic cannabis integration:Health Canada's regulatory framework permits synthetic cannabinoid blending with natural extracts, opening formulation differentiation for pain management developers.
- Modular synthesis platforms:Continuous flow chemistry is converging with automated purification to enable kilogram-scale custom production without dedicated batch facilities.
- Preclinical CRO outsourcing:Contract research organizations in Switzerland are building captive synthetic cannabinoid capabilities to serve biotech clients seeking integrated pharmacology services.
Industry Challenges
- DEA registration timelines:Schedule I manufacturer licensing requires 14-18 month approval cycles that delay commercial launch schedules and strain working capital.
- Analytical chemist scarcity:Forensic laboratories and pharmaceutical quality control departments compete for talent proficient in high-resolution mass spectrometry of novel psychoactive substances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Cannabinoids Market |
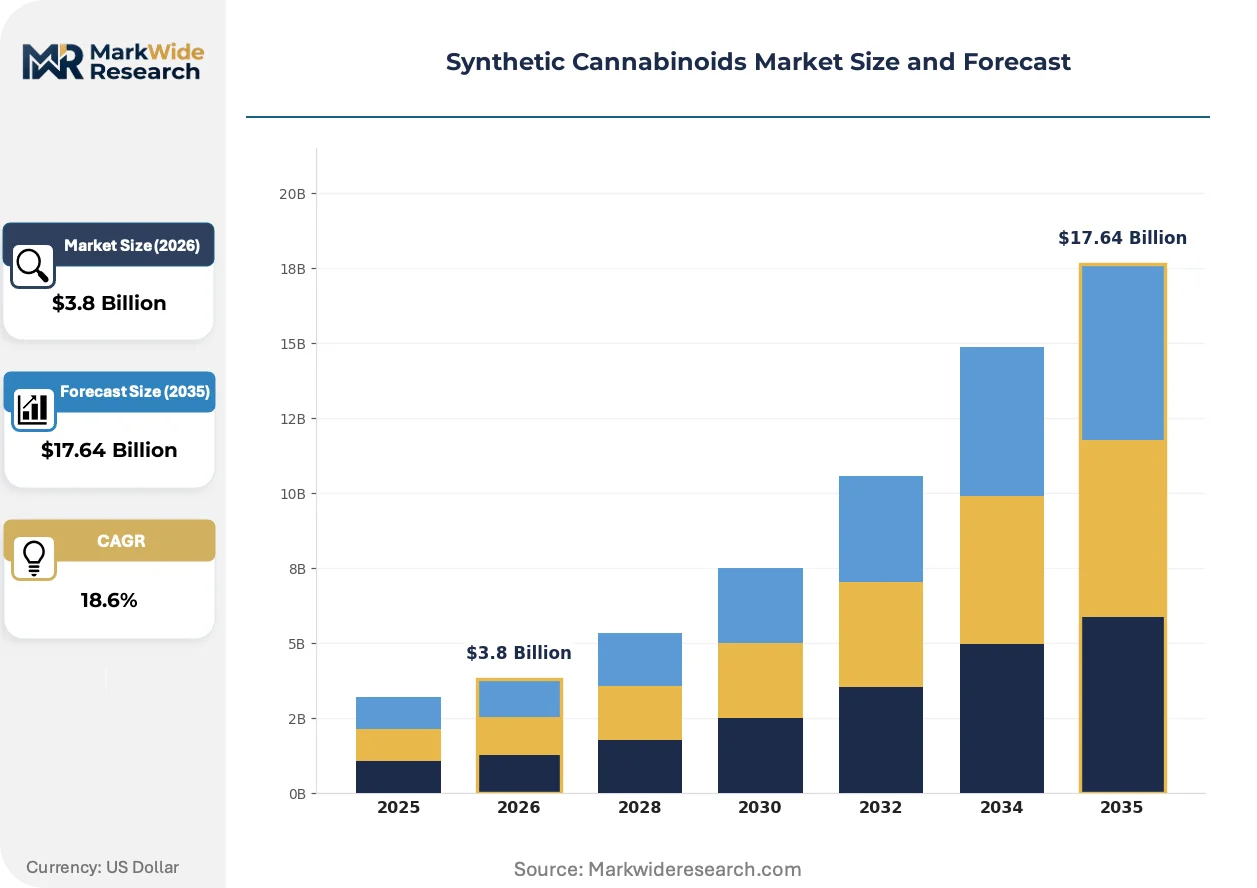
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: JWH-018, JWH-073, AM-2201, UR-144 Formulation: Raw Powder, Liquid, Capsule, Spray Application: Research, Therapeutic Use, Recreational Use, Pharmaceutical Development End User: Research Laboratories, Hospitals, Pharmacies, Manufacturers |
| Companies Covered | Restek Corporation, Cayman Chemical, Johnson Matthey, Skye Bioscience, Cerilliant Corporation, Harmony Biosciences, Noramco Inc., Purisys LLC, BioVectra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Cannabinoids Market Strategic Shifts
Continuous manufacturing technologies and regulatory data harmonization initiatives are compressing the gap between research discovery and pharmaceutical-grade production, reshaping supplier capability requirements.
Flow chemistry reactor systems are replacing traditional batch condensation for indole-naphthoyl coupling reactions, achieving tighter temperature control and higher yields. Pharmaceutical API manufacturers in Germany and the United Kingdom are adopting these platforms to meet EMA Good Manufacturing Practice standards for cannabinoid active substances. This technology is expanding into mid-scale custom synthesis, enabling contract manufacturers to serve preclinical programs without dedicated capital investment per compound.
REACH registration requirements for novel synthetic cannabinoid intermediates are compelling European suppliers to submit full toxicological dossiers before commercial distribution. The European Chemicals Agency's substance evaluation process adds 12-18 months to market entry for new research-grade materials. Forensic reference standard producers are responding by pre-registering structural analogs and maintaining evergreen dossier updates to preserve distribution rights.
Academic procurement departments are consolidating vendor lists and demanding multi-year framework agreements with locked pricing for DEA-exempt research quantities. This concentration is displacing spot-market purchasing for reference standards and forcing smaller suppliers to integrate with larger distribution networks. The shift is most visible in United States National Institutes of Health-funded laboratories, where procurement compliance officers now mandate sole-source justification for non-preferred vendor selection.
Synthetic Cannabinoids Market Segmentation
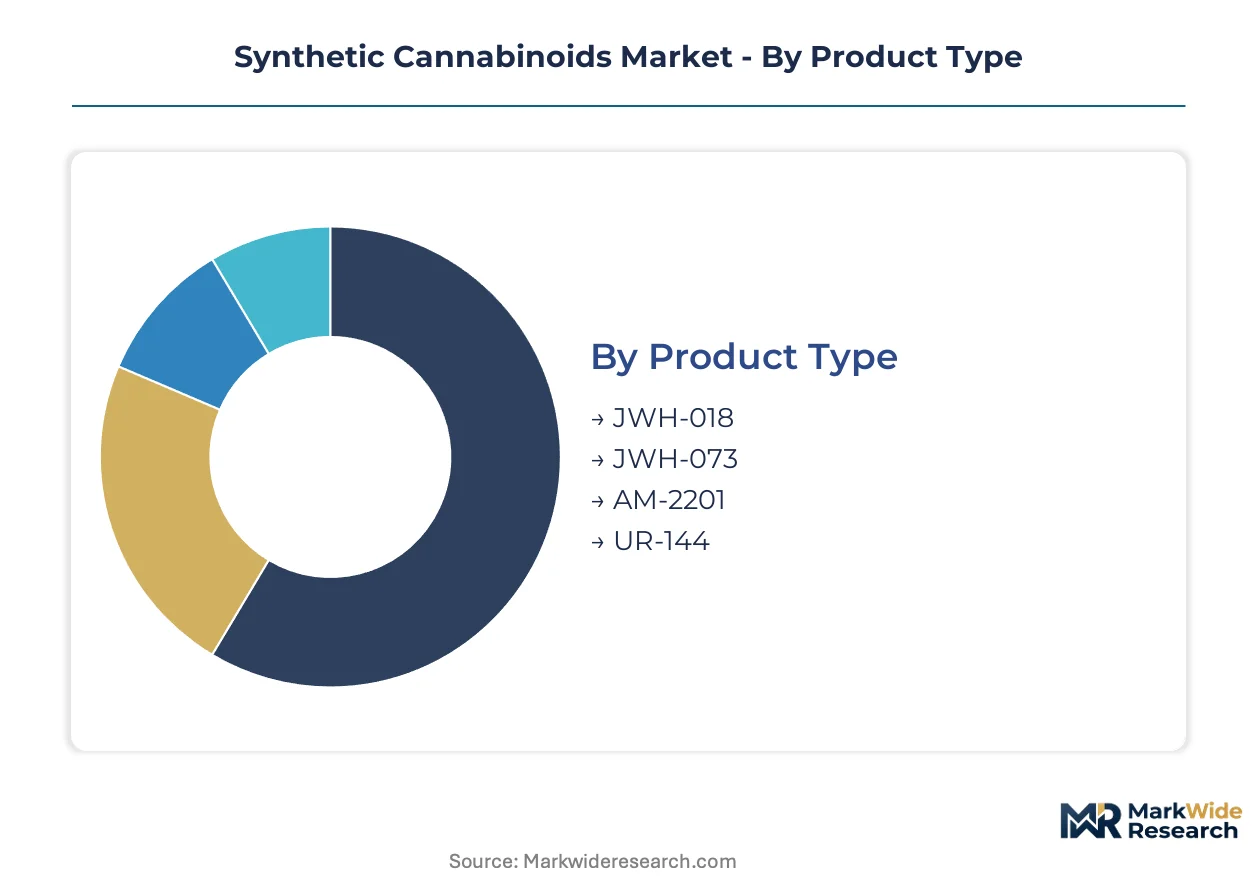
Segmentation in synthetic cannabinoids reflects divergent purity specifications, regulatory pathways, and end-use requirements that shape procurement behavior across forensic, pharmaceutical, and research verticals. Understanding these divides enables suppliers to align certification investments with addressable demand tiers.
Product Type:
Structural core chemistry determines receptor binding affinity, metabolic stability, and scheduling status across jurisdictions.
- JWH-018:The naphthoylindole scaffold pioneered forensic reference standard demand. DEA-compliant batch certification from US crime laboratories sustains recurring procurement despite its Schedule I status since 2011.
- JWH-073:A butyl homolog with modified lipophilicity profiles. Research laboratories in Germany and the United Kingdom concentrate demand for comparative metabolism studies against JWH-018 benchmarks.
- AM-2201:Fluoropentyl substitution extends metabolic half-life, creating analytical detection challenges that drive forensic method development contracts. Academic institutions in the United States fund quantitative metabolism protocols using this compound.
- UR-144:Tetramethylcyclopropyl substitution shifts CB1/CB2 selectivity ratios. Preclinical programs in Switzerland explore this pharmacological profile for spasticity indications under EMA exploratory trial frameworks.
JWH-018 leads on scale; UR-144 leads on momentum.
Formulation:
Physical presentation dictates stability requirements, handling protocols, and margin capture across the value chain.
- Raw Powder:Unformulated crystalline material dominates research laboratory procurement for custom solution preparation. DEA-exempt research quantities move through academic procurement frameworks with locked multi-year pricing agreements.
- Liquid:Dissolved formulations in organic solvents capture therapeutic development margins due to stricter bioavailability and stability specifications. EMA Good Manufacturing Practice certification requirements in Germany and France raise barriers for uncertified suppliers entering this tier.
- Capsule:Oral dosage forms serve preclinical pharmacokinetic studies requiring standardized dosing. Contract research organizations in Switzerland build captive filling capabilities to integrate with synthetic chemistry services.
- Spray:Aerosolized delivery systems target pulmonary absorption studies. Health Canada's regulatory framework permits synthetic-natural cannabinoid blending, opening formulation differentiation for Canadian developers.
Raw powder leads on scale; liquid leads on momentum.
Application:
End-use purpose separates exempt research pathways from controlled therapeutic development, with distinct compliance architectures.
- Research:Forensic calibration and neuropharmacology studies occupy the largest volume share. DEA batch-level documentation mandates and ECHA REACH registration requirements in Europe divert supplier capital toward certification infrastructure.
- Pharmaceutical Development:Cannabinoid receptor modulators for epilepsy and chronic pain represent the steepest expansion trajectory. EMA streamlined approval pathways in Germany and France accelerate pipeline entry for European developers.
- Therapeutic Use:Off-label protocols in United Kingdom neurology clinics expand ahead of formal indication approvals. Spasticity management drives prescriber familiarity with synthetic receptor modulators.
- Recreational Use:Illicit consumption patterns shape forensic detection demand and scheduling updates. Rapid substance scheduling renders validated analytical protocols obsolete within 18-24 months.
Research leads on scale; pharmaceutical development leads on momentum.
End User:
Customer type determines order scale, certification requirements, and relationship dynamics with suppliers.
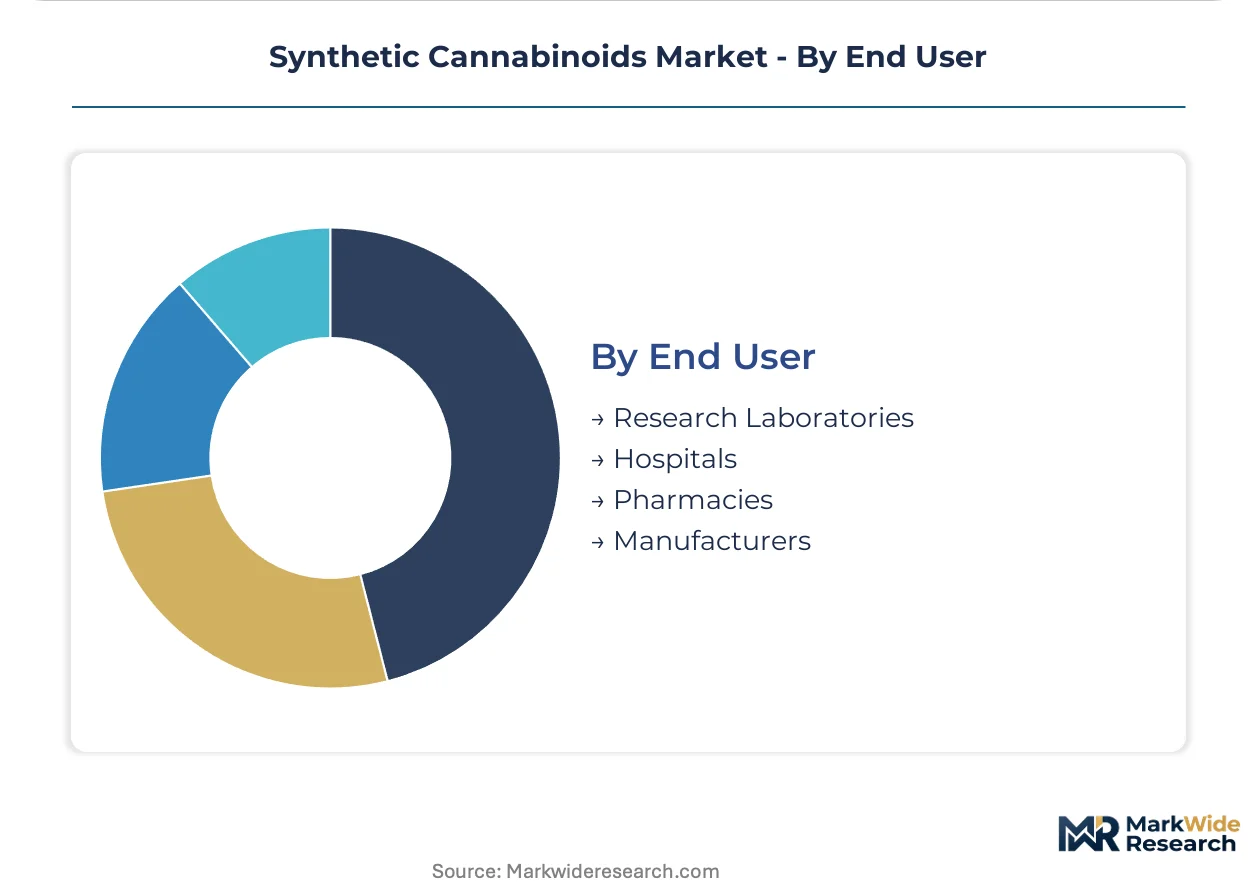
- Research Laboratories:Academic and forensic institutions drive reference standard demand. US National Institutes of Health-funded laboratories now mandate sole-source justification for non-preferred vendor selection, consolidating procurement concentration.
- Manufacturers:API producers and formulation developers source pharmaceutical-grade materials. Johnson Matthey anchors high-volume supply through in-house active pharmaceutical ingredient production.
- Hospitals:Clinical research units administer investigational cannabinoid protocols. United Kingdom neurology departments expand off-label spasticity programs ahead of regulatory approvals.
- Pharmacies:Compounding operations serve specialized therapeutic access programs. Modular formulation packaging enables flexibility to source by purity tier rather than bundled catalog offerings.
Research laboratories lead on scale; manufacturers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic cannabinoid research and pharmaceutical development trace their institutional roots to United States academic laboratories and forensic agencies that pioneered reference standard protocols. Germany and Switzerland subsequently established GMP-certified manufacturing corridors. Today, demand concentrates in four national markets with distinct regulatory pathways.
United States
Forensic laboratories and NIH-funded research institutions drive recurring procurement of DEA-compliant batch-certified materials. The Controlled Substances Act mandates Schedule I manufacturer licensing with 14-18 month approval cycles. Boston and Research Triangle Park host concentrated analytical chemistry clusters serving federal crime laboratories.
Germany
EMA streamlined approval pathways accelerate cannabinoid active substance entry into clinical trials for epilepsy and spasticity indications. The national competent authority enforces GMP certification for pharmaceutical-grade materials entering human studies. Frankfurt and Heidelberg anchor high-purity API manufacturing for European developers.
United Kingdom
Neurology clinics expand off-label cannabinoid receptor modulator protocols for spasticity management ahead of formal indication approvals. The Medicines and Healthcare products Regulatory Agency oversees investigational medicinal product compliance. London and Cambridge concentrate preclinical pharmacology research and contract synthesis services.
Switzerland
Contract research organizations build captive synthetic cannabinoid capabilities to serve biotech clients seeking integrated pharmacology services. Swissmedic regulates clinical trial material quality for cannabinoid therapeutics. Basel and Zurich host formulation development clusters blending synthetic and natural cannabinoid extracts.
Canada
Health Canada's regulatory framework permits synthetic cannabinoid blending with natural extracts for pain management formulation differentiation. The PMRA oversees therapeutic product quality standards. Toronto and Vancouver concentrate preclinical CRO operations serving North American pharmaceutical developers.
Synthetic Cannabinoids Market Competitive Environment
The competitive structure tilts toward reference standard specialists with captive synthesis capabilities. Three to five established players dominate DEA-compliant batch certification, while mid-scale custom synthesis operators serve preclinical programs. Strategic archetypes include forensic-grade certifiers, pharmaceutical API manufacturers, and geographic-focused custom synthesis shops. Capacity expansion and modular formulation packaging represent the dominant competitive moves as suppliers decouple purity tiers from bundled catalog offerings.
Among North American operators, Cayman Chemical and Purisys LLC occupy positions within the reference standard and custom synthesis archetypes respectively. Johnson Matthey anchors the pharmaceutical-grade API tier through in-house active ingredient production. Restek Corporation and Cerilliant Corporation exemplify the forensic certification specialist model with established DEA-compliant distribution networks.
| Leading Market Players |
|---|
| Restek Corporation |
| Cayman Chemical |
| Johnson Matthey |
| Skye Bioscience |
| Cerilliant Corporation |
| Harmony Biosciences |
| Noramco Inc. |
| Purisys LLC |
| BioVectra |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between pharmaceutical and research tiers splits procurement economics along compliance investment lines. DEA Schedule I batch documentation and EMA Good Manufacturing Practice certification create parallel cost structures that reshape supplier capital allocation and buyer qualification thresholds across United States and European distribution networks.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, research-grade, and forensic-reference tiers dominates synthetic cannabinoid procurement. Price differentiation rests on DEA compliance certification and EMA GMP validation as primary drivers. Cost compression in research-grade materials is intensifying because academic procurement departments now mandate multi-year framework agreements with locked pricing. Forensic laboratories demonstrate lowest price sensitivity due to regulatory mandate requirements, while preclinical CROs exhibit highest sensitivity to per-gram pricing volatility.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical API manufacturers mandate qualified supplier redundancy for indole core inputs and naphthoyl chloride intermediates. Geographic supply concentrates in China for bulk indole production, Germany for GMP-certified active substances, and Switzerland for custom synthesis services. Raw material dependencies center on fluoropentyl bromides, adamantoyl chlorides, and high-purity organic solvents. Single-source vulnerability in Chinese indole manufacturing creates structural exposure to import disruption. Distribution runs through DEA-registered chemical distributors and ECHA-compliant specialty chemical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic cannabinoids market functions as a stable compounder sustained by recurring forensic reference standard demand from DEA-mandated crime laboratory procurement cycles.
For Market Incumbents: Anchor defensive positioning through captive synthesis of indole core intermediates to offset Chinese supply concentration risk. Deepen EMA GMP certification coverage across expanded cannabinoid receptor modulator portfolios to capture pharmaceutical pipeline volume. Accelerate batch-level documentation automation to reduce Schedule I compliance overhead.
For New Entrants and Emerging Players: Capture white-space opportunity in continuous flow chemistry contract manufacturing for preclinical CROs seeking kilogram-scale production without dedicated facility investment. Target Swiss and Canadian therapeutic cannabis blending formulations as the most penetrable segment. Pursue Health Canada regulatory alignment as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where DEA registration timelines stretch working capital and analytical chemist scarcity constrains quality control scaling. The market supports 5-10 year viability for reference standard specialists with captive synthesis capabilities. Acquisition target archetype: mid-scale custom synthesis operators with pre-existing EMA documentation infrastructure. Watch for substance scheduling acceleration as the inflection signal indicating revalidation investment surge.
| Strategic Initiative | Industry Significance |
|---|---|
| DEA Schedule I Manufacturer Registration | Enables interstate distribution to federal crime laboratories and NIH-funded research institutions. |
| EMA Good Manufacturing Practice Certification | Unlocks pharmaceutical-grade supply contracts for cannabinoid active substances entering European clinical trials. |
| Continuous Flow Chemistry Platform Deployment | Reduces capital intensity for kilogram-scale custom synthesis serving preclinical CRO programs. |
| REACH Registration for Novel Intermediates | Preserves European distribution rights for research-grade materials under ECHA substance evaluation protocols. |
| Modular Formulation Packaging Expansion | Decouples purity-tier sourcing from bundled catalog offerings to capture pharmacy compounding flexibility demand. |
Study Parameters
Direct dialogue with synthetic chemistry directors, forensic laboratory procurement officers, pharmaceutical regulatory affairs leads, and preclinical CRO sourcing managers grounded the qualitative assessment. Secondary validation drew from DEA Controlled Substances Act filings, EMA scientific advice letters, ECHA REACH registration databases, and United States National Institutes of Health grant award records. Bottom-up demand modeling across purity tiers and top-down market sizing triangulated volume estimates.
Segmented outputs across structural core chemistry, formulation type, application purpose, and end-user archetype fed the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns against regulatory pipeline expansion indicators. Forecast inputs incorporated EMA streamlined approval pathway utilization rates and DEA scheduling update frequency as industry-specific demand drivers.
Underlying measurement precision varies by segment; forensic reference standards carry tighter precision than emerging therapeutic applications. Forecasts reflect documented assumptions regarding regulatory pathway maturation and substance scheduling velocity. Deviation in DEA registration timeline acceleration or indole supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
North America Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Medical Cannabis Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
Thailand Medical Cannabis Market