
 North America Cannabidiol (CBD) Market | 2026-2036
North America Cannabidiol (CBD) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cannabidiol (CBD) Market Analytics
The extraction-scale gap between large cultivators and boutique processors is redrawing competitive boundaries across the sector. Canopy Growth Corporation leverages its greenhouse infrastructure to secure biomass supply across multiple provinces and states. Charlotte's Web Holdings, Inc. anchors its position through proprietary hemp genetics and direct-to-consumer channel control. Medterra CBD, LLC differentiates via third-party certification programs and pharmacy retail partnerships.
Cannabidiol is a non-psychoactive phytocannabinoid extracted from Cannabis sativa L., typically comprising crystalline formulations at 99% purity or full-spectrum oils retaining complementary terpenes and minor cannabinoids; manufacturers deploy CO2 or ethanol extraction followed by winterization and distillation to achieve regulatory-compliant THC thresholds below 0.3%. Oils and tinctures dominate current revenue flows due to established dosing protocols and practitioner familiarity, while capsules attract pharmaceutical-format interest from consumers seeking standardized intake. The wellness use case leads volume generation, though pain relief applications show accelerating clinical trial investment that could expand reimbursable indications.
The FDA maintains enforcement discretion over CBD food additives and dietary supplements pending safety review completion, while Health Canada regulates CBD as a cannabis product under the Cannabis Act with distinct licensing tiers for cultivation and processing. Individual U.S. states impose additional testing mandates through departments of agriculture, creating compliance patchwork that favors multi-jurisdiction operators. Stakeholders must monitor pending federal rescheduling proceedings and corresponding state-level alignment adjustments to anticipate distribution channel access changes.
Market Dynamics
The extraction-scale gap between large cultivators and boutique processors is redrawing competitive boundaries across the sector. Concentrated biomass supply in California and Colorado favors operators with captive greenhouse infrastructure, while smaller processors struggle to secure consistent feedstock at viable unit economics.
Growth Catalysts
- 2018 Farm Bill:Interstate hemp commerce legalization enabled vertically integrated supply chains to scale across state lines, reducing regulatory fragmentation for compliant operators.
- Nutraceutical wellness demand:Practitioner familiarity with CBD oils and tinctures is expanding standardized dosing protocols into pharmacy retail channels.
- CO2 extraction technology:Supercritical systems achieving 99% cannabinoid purity are lowering THC remediation costs for full-spectrum product lines.
Market Restraints
- FDA enforcement discretion:Pending safety reviews block CBD food additive and dietary supplement approvals, freezing mainstream retail channel access for ingestible formats.
- Biomass supply concentration:California and Colorado greenhouse networks control premium hemp feedstock, squeezing margin for non-integrated processors.
- Ethanol input cost volatility:Winterization solvent expenses fluctuate with agricultural commodity markets, compressing extraction economics at smaller scale.
Strategic Opportunities
- Canadian pharmacy channel:Health Canada's distinct licensing tiers for cultivation and processing create structured pathways for CBD product distribution through provincial retailers.
- Pain relief clinical trials:Accelerating investigational investment into reimbursable indications could expand insurance coverage beyond current wellness positioning.
- Third-party certification convergence:USP-verified and NSF-certified programs are creating quality differentiation that pharmacy buyers prioritize over unverified alternatives.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC and mass spectrometry expertise for cannabinoid profiling and THC threshold verification commands premium compensation in tight labor markets.
- Multi-jurisdiction compliance timelines:State departments of agriculture impose divergent testing mandates that extend product launch cycles and increase regulatory overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cannabidiol (CBD) Market |
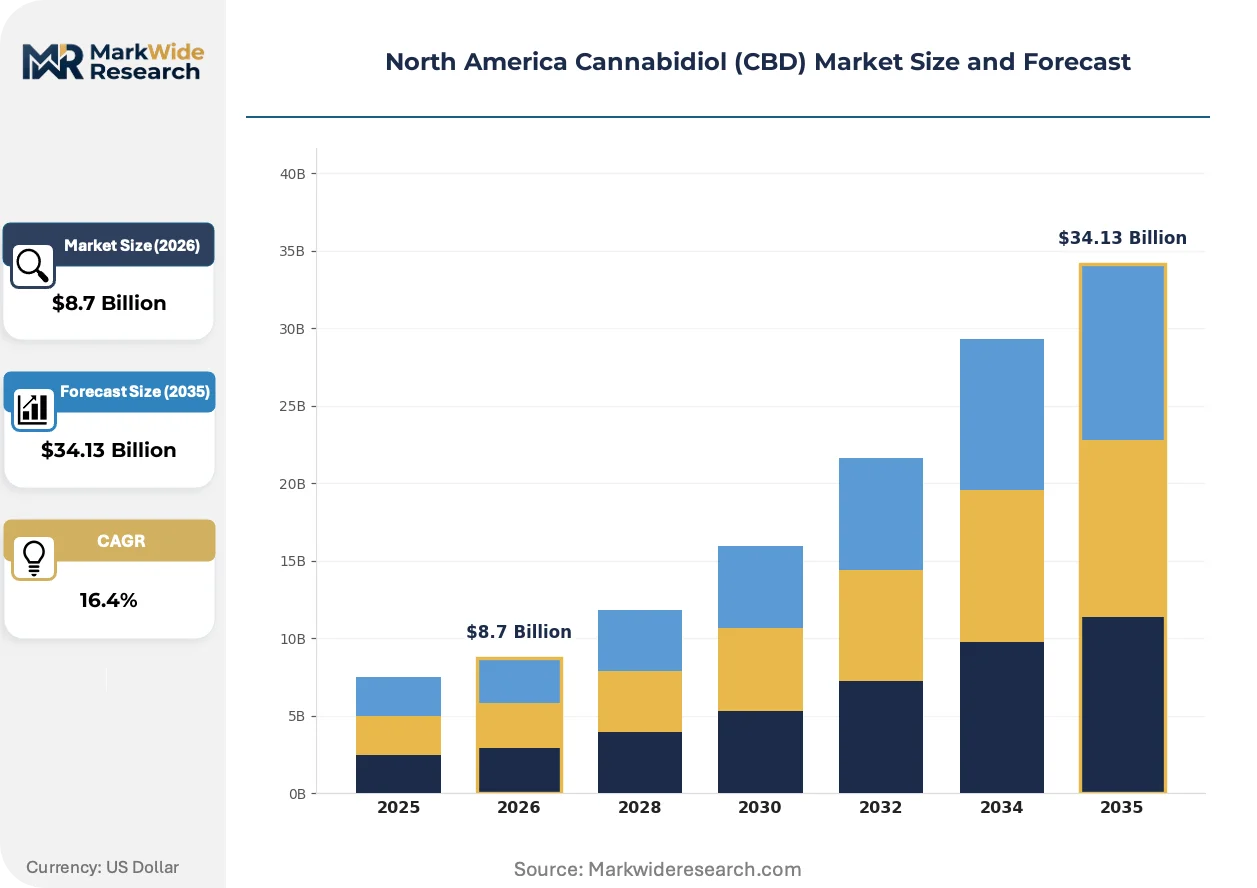
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Oils, Tinctures, Capsules Use Case: Wellness, Pain Relief, Anxiety Management, Sleep Aid Form: Liquid, Solid, Edible, Vapor Distribution Channel: Online, Retail, Dispensary, Wholesale |
| Companies Covered | CV Sciences, Inc., Charlotte’s Web Holdings, Inc., Medical Marijuana, Inc., Aurora Cannabis Inc., Canopy Growth Corporation, Tilray Brands Inc., Medterra CBD, LLC, Green Roads LLC, NuLeaf Naturals, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cannabidiol (CBD) Market Evolving Landscape
Processing technology and regulatory clarity are converging to reshape product formats and distribution channels. Operators are repositioning around certification credibility and extraction efficiency to capture pharmacy and practitioner segments.
Supercritical CO2 extraction systems with integrated winterization are supplanting standalone ethanol setups in mid-scale facilities. Colorado processors adopting these unified platforms report 40% throughput gains and reduced solvent handling compliance burdens. The technology is compressing capital requirements for 99% purity crystalline production, enabling smaller operators to compete on specification rather than scale alone.
FDA guidance evolution on CBD-infused products is forcing format diversification toward topicals and cosmetics where enforcement discretion is narrower. California manufacturers are accelerating skincare and transdermal development to bypass ingestible regulatory limbo. The shift favors operators with existing cosmetic chemistry capabilities and established relationships with contract manufacturers.
Pharmacy buyers are consolidating supplier relationships around third-party certified producers with documented chain-of-custody protocols. Independent pharmacies in Texas and Florida are replacing fragmented distributor relationships with direct sourcing from USP-verified cultivators. The pattern concentrates procurement volume among compliance-heavy operators, marginalizing uncertified competitors in professional channels.
North America Cannabidiol (CBD) Market Segmentation
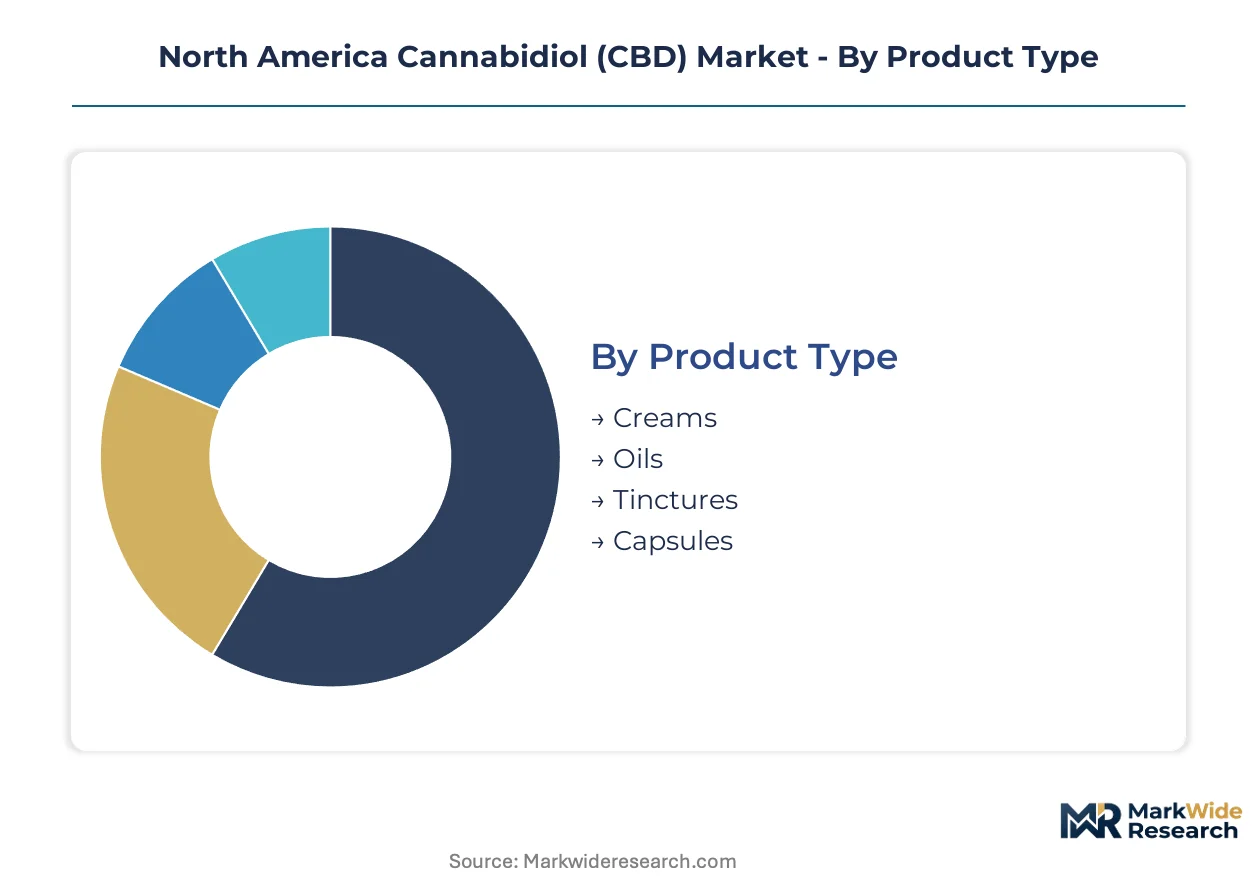
Channel access restrictions in North America fragment demand across incompatible regulatory frameworks. Dispensary networks in California and Colorado operate under state cannabis laws, while pharmacy retail channels navigate FDA enforcement discretion. Product format decisions cascade from these channel constraints, with topicals bypassing ingestible restrictions and oils leveraging practitioner familiarity.
Product Type:
Oils and tinctures flow through practitioner and pharmacy channels where dosing standardization matters; creams target cosmetic retail to evade FDA dietary supplement jurisdiction.
- Oils:Full-spectrum formulations retain complementary terpenes and minor cannabinoids through CO2 extraction. California's vertically integrated greenhouse operators dominate biomass supply for high-purity oil production, though THC remediation costs compress margins at smaller scale.
- Tinctures:Ethanol-based extraction yields standardized cannabinoid concentrations in dropper formats. Colorado dispensary networks concentrate demand for tinctures with established dosing protocols, while pharmacy buyers in Texas and Florida prioritize USP-verified alternatives.
- Creams:Topical formulations bypass FDA dietary supplement restrictions. Manufacturers with cosmetic chemistry capabilities in California accelerate skincare development to capture retail channel access frozen for ingestibles.
- Capsules:Pharmaceutical-format solid dosing attracts standardized intake demand. Health Canada's distinct licensing tiers enable structured distribution through provincial pharmacy retailers.
Oils dominate installed base through practitioner channel penetration. Tinctures are where expansion concentrates as pharmacy buyers consolidate around certified suppliers.
Use Case:
Wellness applications generate volume through nutraceutical positioning, while pain relief investment targets reimbursable indications beyond current out-of-pocket spending.
- Wellness:General health maintenance drives nutraceutical format adoption. California's established dispensary networks and Colorado's vertically integrated supply chains channel wellness demand through direct-to-consumer and retail pathways.
- Pain Relief:Clinical trial investment accelerates toward insurance-eligible indications. Health Canada regulatory frameworks provide clearer pathways for pain relief product registration than FDA enforcement discretion allows.
- Anxiety Management:Practitioner-prescribed protocols favor standardized dosing formats. Pharmacy retail partnerships in Canada and select US states concentrate procurement among third-party certified producers.
- Sleep Aid:Melatonin-CBD combination products target supplement aisle placement. FDA pending safety reviews block explicit sleep claims for ingestible formats, pushing development toward topical and cosmetic positioning.
Wellness commands current volume through accessible channels. Pain relief is climbing the fastest as investigational investment targets reimbursable status.
Form:
Physical form determines regulatory pathway and manufacturing capital requirements, with liquid formats suiting pharmacy channels and edibles facing FDA additive restrictions.
- Liquid:Oils and tinctures enable precise titration and rapid absorption. Supercritical CO2 extraction systems with integrated winterization compress capital requirements for 99% purity production.
- Solid:Capsules and tablets standardize dosing for practitioner protocols. Health Canada pharmacy channel access favors solid formats with documented stability data.
- Edible:Gummies and infused foods confront FDA enforcement discretion over CBD additives. California manufacturers pivot toward compliant topicals as interstate food commerce remains restricted.
- Vapor:Inhalation formats concentrate in state-licensed dispensary networks. Colorado and California regulatory frameworks permit vapor products under cannabis licensing tiers.
Liquid forms anchor pharmacy and practitioner channels. Solid formats are gaining share fastest as certification programs standardize procurement.
Distribution Channel:
Channel selection determines regulatory burden and customer access, with online direct-to-consumer bypassing state-by-state retail fragmentation.
- Online:Direct-to-consumer platforms enable interstate commerce under Farm Bill compliance. Charlotte's Web Holdings anchors position through proprietary genetics and channel control.
- Retail:Pharmacy and health store placement requires third-party certification. Independent Texas and Florida pharmacies replace fragmented distributors with direct USP-verified sourcing.
- Dispensary:State-licensed cannabis retailers operate under distinct regulatory tiers. California's established networks and Colorado's vertical integration concentrate premium product flow.
- Wholesale:Bulk supply to downstream processors and white-label manufacturers. Biomass supply concentration in greenhouse-heavy states squeezes margin for non-integrated wholesale operators.
Dispensary channels dominate premium product volume. Online direct-to-consumer is expanding most quickly as certification programs reduce buyer risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates wellness-oriented CBD consumption through direct-to-consumer and pharmacy channels, while Canada channels demand through provincial retailers under stricter federal oversight. Mexico represents an emerging frontier with nascent regulatory frameworks and limited formal distribution infrastructure.
United States
California's established dispensary networks and Colorado's vertically integrated supply chains concentrate premium product flow through state-licensed cannabis frameworks. FDA maintains enforcement discretion over CBD food additives and dietary supplements pending safety review completion, freezing mainstream retail channel access for ingestible formats. Texas and Florida independent pharmacies are replacing fragmented distributor relationships with direct sourcing from USP-verified cultivators.
Canada
Health Canada regulates CBD as a cannabis product under the Cannabis Act with distinct licensing tiers for cultivation and processing, creating structured pathways for provincial pharmacy distribution. Ontario and Quebec anchor volume through provincial retailer procurement concentration. British Columbia's processing infrastructure supports extraction-scale operations serving multiple provincial markets under unified federal standards.
Mexico
Nascent medical cannabis regulations permit CBD importation and limited domestic cultivation, though formal retail channels remain underdeveloped. Mexico City Metro concentrates early practitioner adoption and wellness consumer awareness. Northern Border States leverage cross-border commerce familiarity to pilot pharmacy retail placement pending regulatory clarification.
North America Cannabidiol (CBD) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with greenhouse infrastructure operators commanding biomass supply advantages over non-integrated processors. The extraction-scale gap between large cultivators and boutique processors redistributes margin toward captive supply chain control. Three archetypes dominate: vertically integrated greenhouse operators with multi-province reach, proprietary genetics holders with direct-to-consumer channel control, and certification-focused specialists with pharmacy retail partnerships. Competitive intensity concentrates around backward integration into biomass supply and third-party certification convergence for professional channel access.
Within the integrated cultivation tier, Canopy Growth Corporation and Aurora Cannabis Inc. represent scale-driven infrastructure deployment across multiple provinces and states. Charlotte's Web Holdings, Inc. exemplifies genetics-based differentiation with direct-to-consumer channel anchoring. Medterra CBD, LLC occupies the certification-specialist position through pharmacy retail partnership structures.
| Leading Market Players |
|---|
| CV Sciences, Inc. |
| Charlotte's Web Holdings, Inc. |
| Medical Marijuana, Inc. |
| Aurora Cannabis Inc. |
| Canopy Growth Corporation |
| Tilray Brands Inc. |
| Medterra CBD, LLC |
| Green Roads LLC |
| NuLeaf Naturals, LLC |
| Others |
Value Network & Pricing Analysis
USP-verified certification gates both supplier qualification and price differentiation simultaneously, creating tiered access to pharmacy procurement channels where uncertified biomass commands lower unit economics. Three-tier pricing structure across premium, standard, and economy levels reflects extraction scale, certification status, and captive greenhouse infrastructure ownership.
Pricing Analysis
Long-term offtake contracts dominate biomass procurement between California greenhouse operators and mid-scale processors, while spot markets serve boutique extractors facing feedstock volatility. Price differentiation rests on USP-verified status and CO2 extraction scale, with pharmacy buyers paying premiums for documented chain-of-custody. Cost compression in standard-tier oils is intensifying because ethanol input costs fluctuate with agricultural commodity markets. Independent pharmacies in Texas and Florida exhibit highest price sensitivity, whereas Canadian provincial retailers prioritize certification compliance over unit cost.
Supply Chain Analysis
Colorado's vertically integrated greenhouse networks constitute a chokepoint controlling premium hemp biomass flow to non-integrated processors across North America. Supply concentrates in California, Colorado, and British Columbia, with extraction infrastructure drawing from captive cultivation, third-party biomass brokers, and imported isolate. Single-source vulnerability runs through California's greenhouse-dominant feedstock regions. Distribution runs through direct-to-consumer platforms, pharmacy retail partnerships, and state-licensed dispensary networks with incompatible regulatory requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel fragmentation across FDA enforcement discretion, Health Canada licensing tiers, and state cannabis frameworks creates multiple entry niches for differentiated positioning. Practitioner-prescribed protocols and pharmacy retail consolidation favor operators with certification credibility and documented quality systems.
For Market Incumbents: Consolidate biomass supply through greenhouse infrastructure acquisition in California and Colorado to secure feedstock cost advantages against emerging contract manufacturers. Lock in pharmacy retail partnerships through USP-verified certification investment before Health Canada's provincial distribution pathways mature. Defensive priority centers on backward integration into CO2 extraction capacity.
For New Entrants and Emerging Players: Lead with third-party certification programs targeting independent Texas and Florida pharmacies replacing fragmented distributor relationships. White-space opportunity concentrates in topical and cosmetic formats bypassing FDA dietary supplement restrictions. Go-to-market angle should emphasize cosmetic chemistry capabilities and established contract manufacturing relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-scale CO2 extraction operations as integrated winterization platforms compress equipment requirements. Long-term viability favors operators with pharmacy channel access and proprietary genetics libraries. Acquisition target archetype: certification-focused specialists with documented Health Canada licensing progress. Signal to watch: FDA rescheduling proceedings and corresponding state-level alignment adjustments.
| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Program | Pharmacy buyers in Texas and Florida consolidate procurement around certified suppliers with documented chain-of-custody protocols. |
| Greenhouse Infrastructure Expansion | California and Colorado operators secure captive biomass supply against ethanol cost volatility squeezing non-integrated processors. |
| Topical Format Development | California manufacturers accelerate skincare positioning to bypass FDA enforcement discretion freezing ingestible channel access. |
| Provincial Pharmacy Partnership | Health Canada's distinct licensing tiers enable structured distribution through Ontario and Quebec provincial retailers. |
| Proprietary Genetics Investment | Direct-to-consumer channel control anchors market position against commodity biomass competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with extraction facility managers, pharmacy procurement directors, regulatory affairs specialists at licensed cultivators, and independent dispensary owners. Secondary validation drew from FDA guidance documents, Health Canada licensing databases, state department of agriculture testing mandates, and provincial retailer procurement disclosures. Bottom-up volume estimates from biomass supply and extraction capacity were triangulated against top-down demand segmentation across product formats and use cases.
Across the analysis window, the analytical framework modeled value and volume trajectories through product type, use case, physical form, and distribution channel dimensions with regulatory framework as a cross-cutting variable. CAGRs were derived from segment-level growth rate synthesis anchored in channel access expansion and certification program adoption curves. Forecast inputs included practitioner prescribing pattern surveys and pharmacy retail partnership formation rates.
Forecasts assume regulatory continuity in FDA enforcement discretion and Health Canada Cannabis Act frameworks; material policy shifts would require re-modeling channel access assumptions and product format viability. Practitioners should keep alternative scenarios live as federal rescheduling proceedings and state-level alignment adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Trichome Separator/Extractor Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Legal Cannabis Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Cannabinoid CB2 Products Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market