
 Australia Medicinal Cannabis Testing Market | 2026-2036
Australia Medicinal Cannabis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Medicinal Cannabis Testing Market Insights
Pharmaceutical-grade certification is bifurcating the competitive landscape into TGO 93-compliant laboratories and general analytical service providers. Agilent Technologies leverages its chromatography portfolio to anchor high-throughput potency workflows for licensed producers. Merck KGaA sustains its position through reagent and reference standard supply chains that feed quality control protocols. Shimadzu Scientific Instruments differentiates via localized technical support networks spanning Sydney and Melbourne analytical clusters.
Australia medicinal cannabis testing encompasses analytical verification of cannabinoid profiles, terpene quantification, and contaminant detection across microbial, heavy metal, and pesticide matrices using validated chromatographic and spectroscopic methods to ensure patient safety and regulatory compliance. Chromatography systems process the bulk of THC and CBD potency determinations given their established precision for complex botanical matrices. Microbial testing commands premium pricing due to mandatory TGO 93 requirements and the technical complexity of pathogen detection in herbal substrates. Licensed producers represent the fastest-growing end user segment as cultivation scale expands and internal quality control budgets mature.
The Therapeutic Goods Administration enforces TGO 93 standards that mandate batch release testing, while the Office of Drug Control oversees licensing conditions that embed analytical requirements into production permits. State-level health departments in Victoria and New South Wales layer additional compliance obligations for patient access schemes and clinical trial supply chains. Stakeholders must monitor evolving cannabinoid scheduling decisions and potential harmonization with international pharmacopeial standards to anticipate testing volume shifts and method validation investments.
Market Dynamics
TGO 93 compliance deadlines are compressing testing turnaround times across New South Wales and Victoria, forcing licensed producers to internalize quality control or lock in multi-year service contracts with analytical laboratories.
Growth Catalysts
- Patient Access Scheme Expansion:Victoria's Special Access Scheme and New South Wales compassionate access programs are generating batch-release testing volume for novel cannabinoid formulations.
- TGO 93 Batch Compliance Mandates:The Therapeutic Goods Administration's tightening microbial and heavy metal thresholds are expanding mandatory testing panels beyond basic potency verification.
- Cultivation Scale-Up:Licensed producers in suburban Melbourne and Sydney fringe zones are commissioning dedicated in-house chromatography suites to manage throughput.
Market Restraints
- Reference Standard Import Dependency:Certified cannabinoid reference materials ship primarily from European suppliers, exposing laboratories to euro-denominated cost volatility and customs clearance delays.
- Technical Talent Concentration:Analytical chemists with botanical matrix experience cluster in Sydney and Melbourne, creating recruitment bottlenecks for regional testing facilities in Brisbane and Perth.
- Equipment Capex Burden:LC-MS/MS systems required for pesticide screening represent capital commitments that exclude smaller independent laboratories from TGO 93 accreditation pathways.
Strategic Opportunities
- Queensland Clinical Trial Pipeline:The state's emerging psychedelic-assisted therapy research institutions are creating adjacent demand for GMP-certified analytical services.
- Terpenoid Profiling Differentiation:Full-spectrum chemotyping beyond THC/CBD is enabling laboratories to command premium positioning for strain-specific therapeutic formulations.
- Office of Drug Control Export Licensing:Permitted international shipments are opening batch certification revenue streams for laboratories with ISO 17025 and TGA mutual recognition arrangements.
Industry Challenges
- Method Validation Timelines:TGO 93 requires laboratory-developed test procedures for novel matrices, extending accreditation cycles for cannabis-specific workflows.
- LIMS Integration Complexity:Legacy laboratory information management systems require custom configuration to capture TGA-mandated chain-of-custody documentation and batch traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Medicinal Cannabis Testing Market |
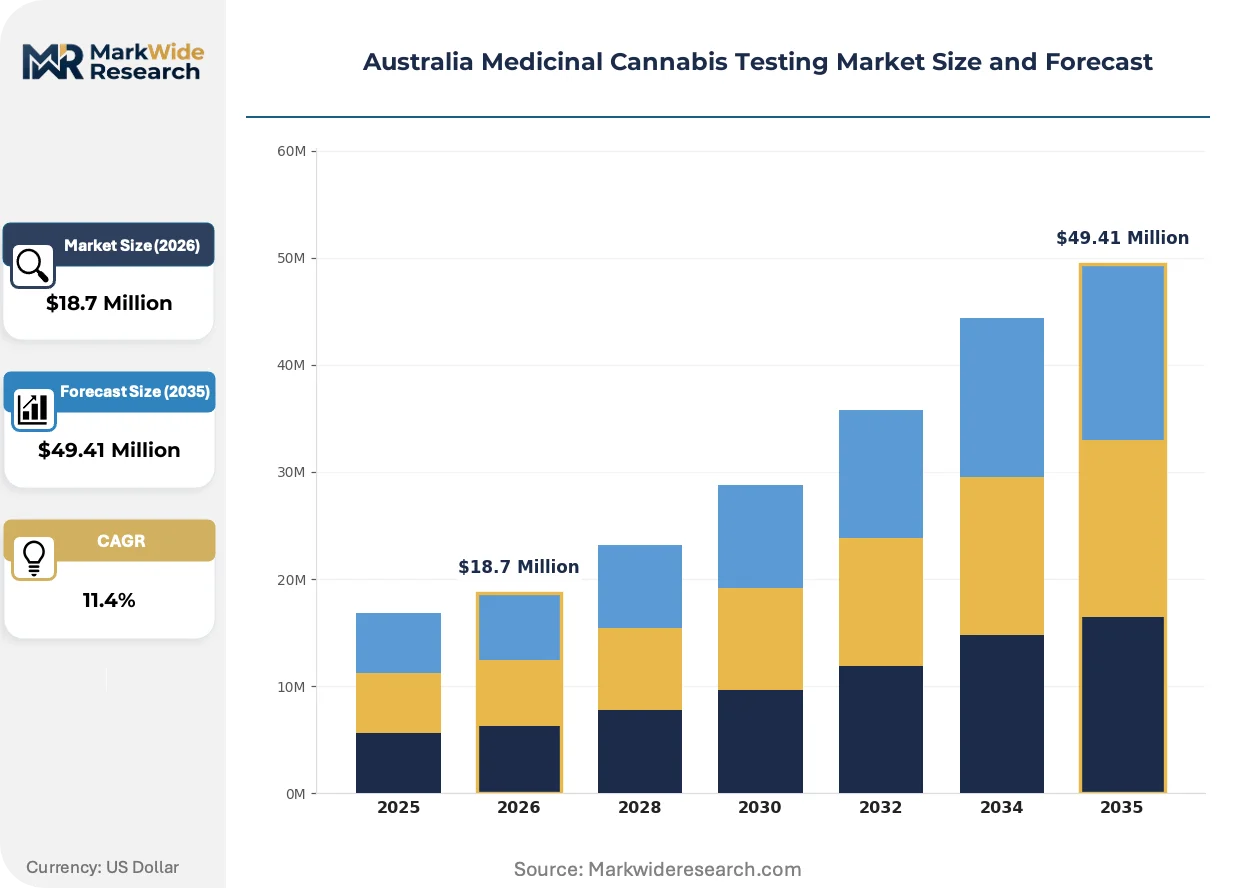
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lab Testing, Quality Control, Certificate of Analysis, Strain Identification Technology: Chromatography, Spectroscopy, Bioassays, Microbial Testing End User: Clinics, Licensed Producers, Research Institutions, Regulatory Agencies Application: THC Testing, CBD Testing, Contaminant Screening, Potency Analysis |
| Companies Covered | Agilent Technologies, Inc., Merck KGaA, PerkinElmer Inc., Quantum Analytics, Shimadzu Scientific Instruments, Medcan Australia Pty Ltd, Medical Cannabis Australia Pty Ltd, Medigrowers Pty Ltd, Medigrowth Australia Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Medicinal Cannabis Testing Market Trends and Innovations
High-resolution mass spectrometry is penetrating potency workflows previously dominated by UV detection, while regulatory data integrity requirements are reshaping laboratory automation priorities across Australian analytical clusters.
Ultra-high-performance liquid chromatography paired with photodiode array detection is decomposing the traditional HPLC-UV standard for routine THC and CBD quantification. Licensed producers in Melbourne's northern suburbs are adopting these platforms to compress method runtimes from thirty minutes to under eight minutes. The technology is decomposing pricing power for generalist analytical service providers lacking high-throughput capabilities.
TGA's 2023 guidance on analytical procedure lifecycle management is embedding continuous verification requirements into laboratory quality systems. Facilities must now demonstrate statistical process control for potency assays rather than relying on initial method validation. Small independent operators in Perth and Adelaide are responding by consolidating into multi-site networks to spread compliance infrastructure costs.
Fixed-fee annual testing contracts are displacing per-batch pricing for large licensed producers with predictable cultivation volumes. The model transfers volume risk to laboratories while locking in guaranteed revenue streams for multi-year periods. This shift is most visible among vertically integrated producers in Victoria's Gippsland and New South Wales' Hunter Valley regions with expansion-phase cultivation facilities.
Australia Medicinal Cannabis Testing Market Segmentation
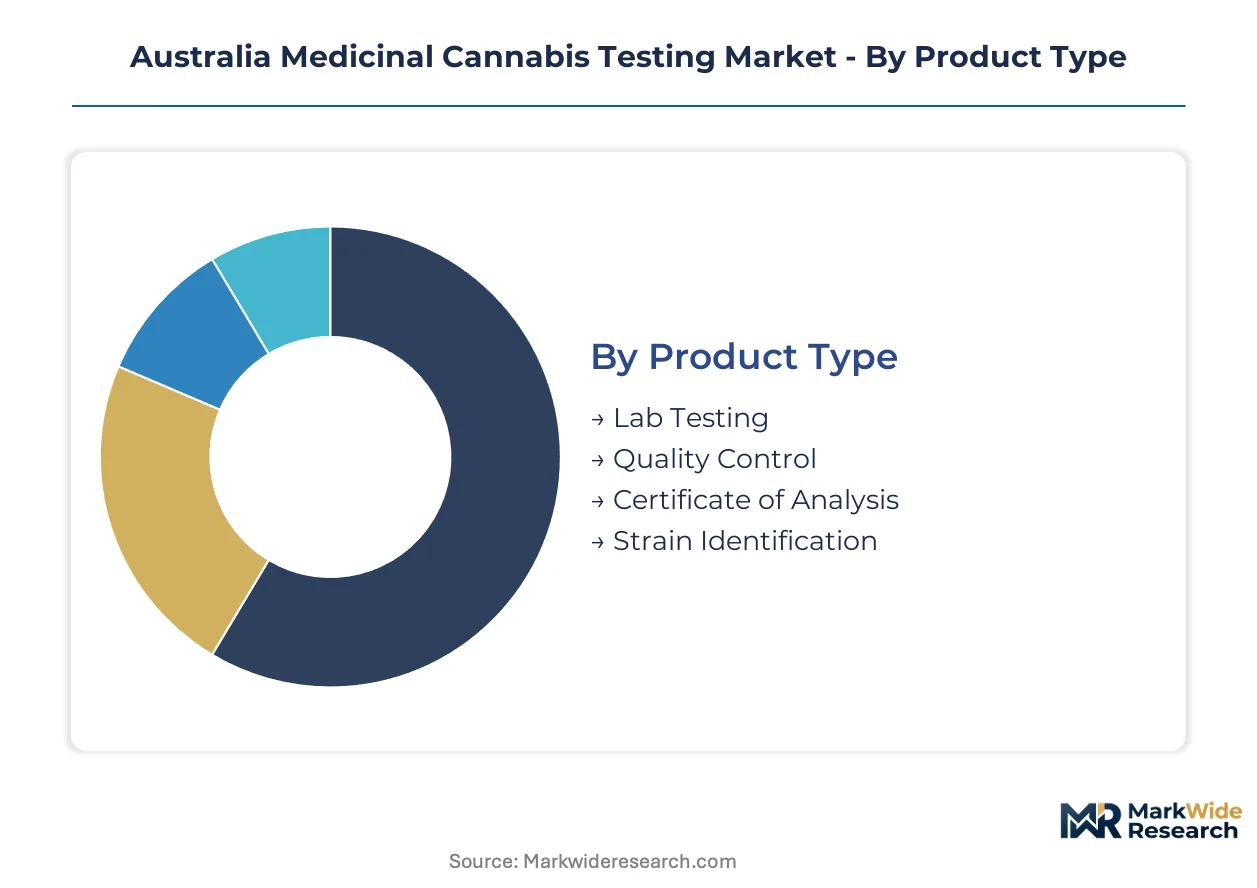
Segmentation in the Australia medicinal cannabis testing market reveals how TGO 93 compliance requirements cascade through different service delivery models. Testing providers configure their portfolios around the regulatory intensity each customer segment demands.
Product Type:
Service flows diverge sharply between external laboratory outsourcing and internal quality control capabilities that licensed producers are building.
- Lab Testing:Third-party analytical services process batch-release verification for clinics and smaller producers lacking in-house capabilities. Demand concentrates in Sydney and Melbourne metropolitan clusters where TGA-accredited facilities maintain ISO 17025 certification.
- Quality Control:In-house analytical capabilities embed chromatography suites within cultivation facilities to compress turnaround times for TGO 93 compliance. Licensed producers in Victoria's Gippsland and New South Wales' Hunter Valley regions are commissioning dedicated quality control infrastructure as cultivation scales.
- Certificate of Analysis:Documentation packages accompany every batch release for patient access schemes and export consignments.
- Strain Identification:Chemotyping services verify genetic consistency and terpenoid profiles for therapeutic formulation development.
By volume, Lab Testing leads. By growth pace, Quality Control is climbing the fastest.
Technology:
Capital intensity and technical specialization create distinct margin tiers across the analytical technology stack.
- Chromatography:HPLC and UHPLC systems dominate THC and CBD potency quantification given established precision for complex botanical matrices. Licensed producers in suburban Melbourne are adopting UHPLC-PDA platforms to compress method runtimes below eight minutes.
- Microbial Testing:Pathogen detection commands premium pricing due to mandatory TGO 93 requirements and technical complexity in herbal substrates. Facilities require specialized containment infrastructure that excludes smaller independent operators from accreditation pathways.
- Spectroscopy:UV-Vis and mass spectrometry methods support terpenoid profiling and contaminant screening workflows.
- Bioassays:Cell-based and receptor binding assays validate biological activity for novel cannabinoid formulations entering clinical trials.
Chromatography generates the highest testing volume. Microbial Testing delivers the steepest margin expansion.
End User:
Customer procurement maturity determines contract structures and service bundling preferences across the value chain.
- Licensed Producers:Vertically integrated cultivation facilities in New South Wales and Victoria are shifting from per-batch pricing to multi-year fixed-fee contracts as internal quality control budgets mature. These customers demand high-throughput potency workflows and dedicated technical support.
- Clinics:Patient access scheme administrators require rapid turnaround on small batch volumes for compassionate supply programs.
- Research Institutions:Universities and clinical trial sponsors in Queensland's emerging psychedelic-assisted therapy sector need GMP-certified analytical services with full method documentation.
- Regulatory Agencies:TGA and state health departments commission confirmatory testing and laboratory audits to enforce compliance.
Licensed Producers anchor revenue concentration. Research Institutions are expanding most quickly.
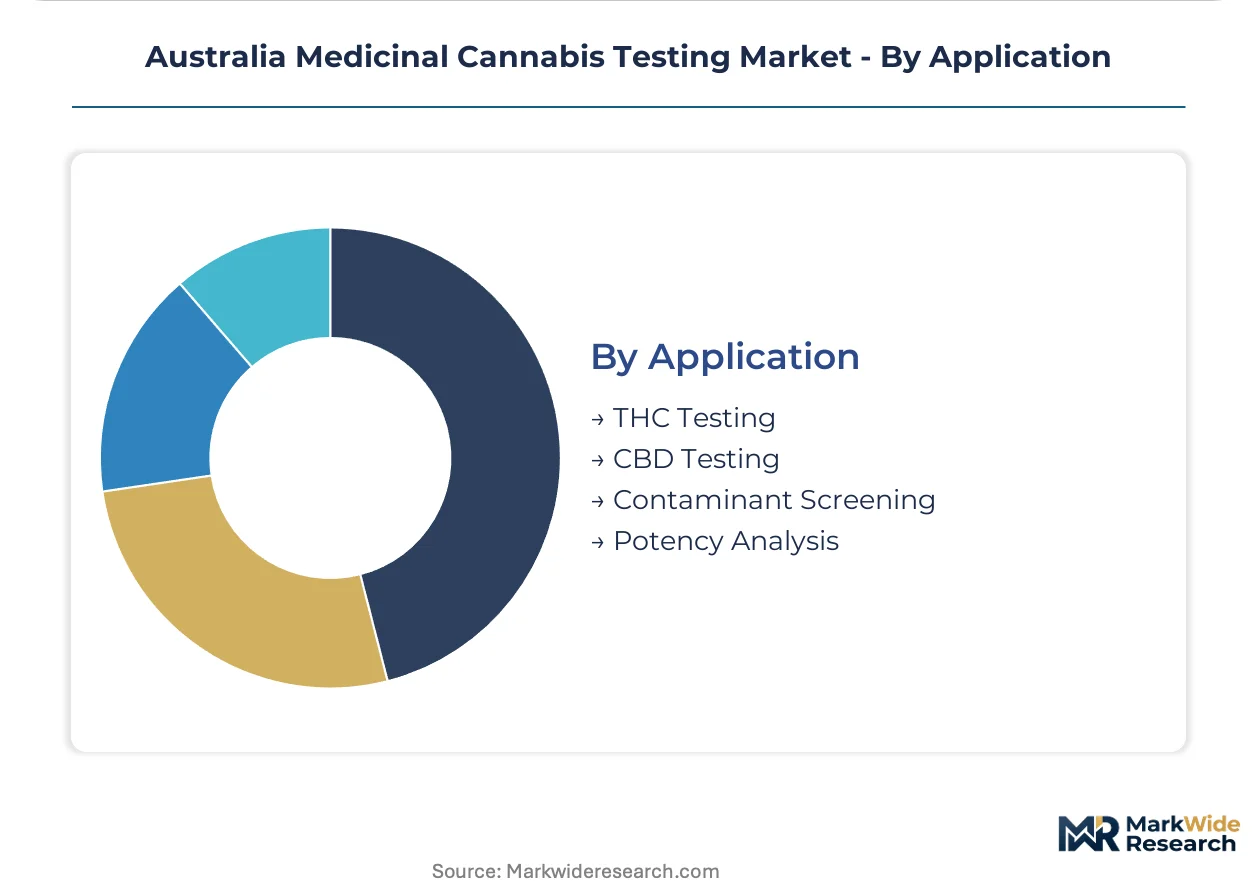
Application:
Regulatory thresholds and clinical relevance shape which analytical applications command priority investment.
- Contaminant Screening:Microbial, heavy metal, and pesticide detection represents non-negotiable TGO 93 requirements with zero tolerance for batch release failures. Tightening thresholds are expanding mandatory testing panels beyond basic potency verification.
- Potency Analysis:THC and CBD quantification underpins dosing accuracy for therapeutic formulations and drives the bulk of routine testing volume.
- THC Testing:Specific quantification supports scheduling compliance and export certification requirements.
- CBD Testing:Cannabidiol verification enables product positioning for non-psychoactive therapeutic indications.
Contaminant Screening carries the highest compliance burden. Potency Analysis processes the greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's medicinal cannabis testing market exhibits pronounced geographic concentration, with import dependency for reference standards and capital equipment shaping regional competitive dynamics. Testing demand clusters around licensed cultivation zones and metropolitan analytical hubs.
New South Wales
Licensed producers in Sydney's fringe zones and the Hunter Valley are commissioning in-house chromatography suites to manage TGO 93 batch compliance. The state's Special Access Scheme generates consistent testing volume for compassionate supply programs. Sydney anchors the nation's densest cluster of TGA-accredited analytical laboratories.
Victoria
Gippsland cultivation facilities are shifting from per-batch pricing to multi-year fixed-fee contracts as quality control budgets mature. The Therapeutic Goods Administration's tightening microbial thresholds are expanding mandatory testing panels beyond basic potency verification. Melbourne's northern suburbs host the highest concentration of UHPLC-PDA platform adoption.
Queensland
Brisbane faces recruitment bottlenecks for analytical chemists with botanical matrix experience, slowing regional testing facility expansion. The state's emerging psychedelic-assisted therapy research institutions are creating adjacent demand for GMP-certified analytical services. Queensland's clinical trial pipeline is attracting laboratories seeking to diversify beyond cannabis-specific workflows.
Western Australia
Perth-based independent operators are consolidating into multi-site networks to spread TGA compliance infrastructure costs across lower testing volumes. The state's geographic isolation exacerbates reference standard import delays from European suppliers. Regional testing demand concentrates around patient access scheme administrators requiring rapid turnaround on small batch volumes.
South Australia
Adelaide laboratories are responding to TGA's 2023 analytical procedure lifecycle management guidance by embedding continuous verification requirements into quality systems. The city's smaller market scale limits capital investment in LC-MS/MS systems required for pesticide screening accreditation. Local producers rely heavily on third-party testing services for TGO 93 compliance.
Australia Medicinal Cannabis Testing Market Competitive Landscape
Listed analytical instrumentation leaders compete with private testing specialists across accreditation tiers and service delivery models. The market structures around three layers: multinational equipment vendors supplying chromatography and spectroscopy platforms, third-party laboratories processing batch-release verification, and licensed producers building captive in-house capabilities. Two dominant competitive moves are reshaping positioning: fixed-fee annual contracts transferring volume risk from producers to service providers, and multi-site laboratory consolidation spreading compliance costs across regional networks.
Within the equipment supply tier, Agilent Technologies and Shimadzu Scientific Instruments exemplify chromatography-focused market presence, while Merck KGaA occupies a position in reagent and reference standard supply chains. Among Australia-based testing specialists, Medcan Australia Pty Ltd and Medical Cannabis Australia Pty Ltd represent the private laboratory archetype serving licensed producers and clinics. Quantum Analytics sits within the emerging tier of providers targeting terpenoid profiling differentiation beyond basic THC and CBD quantification. These named entities anchor industry-level commentary on how TGO 93 compliance requirements cascade through competitive positioning.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Merck KGaA |
| PerkinElmer Inc. |
| Quantum Analytics |
| Shimadzu Scientific Instruments |
| Medcan Australia Pty Ltd |
| Medical Cannabis Australia Pty Ltd |
| Medigrowers Pty Ltd |
| Medigrowth Australia Pty Ltd |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at TGA-accredited laboratories in Sydney and Melbourne determines price floors across the Australian medicinal cannabis testing market, with high-throughput facilities commanding premium positioning while smaller regional operators absorb volume risk through fixed-fee contracts.
Pricing Analysis
Licensed producers anchor pricing structure through multi-year fixed-fee contracts that transfer volume risk from cultivation facilities to analytical service providers. Three-tier pricing structure across premium, standard, and economy levels segments the market by accreditation tier and turnaround speed, with TGO 93-compliant laboratories capturing premium positioning. Cost compression in routine potency testing is intensifying because UHPLC-PDA platform adoption compresses method runtimes below eight minutes. Smaller independent operators in Perth and Adelaide exhibit highest price sensitivity due to capital constraints on LC-MS/MS systems required for pesticide screening accreditation.
Supply Chain Analysis
Germany and the Netherlands anchor certified cannabinoid reference material production, with European suppliers feeding quality control protocols across Australian testing facilities. The supply chain draws from euro-denominated reagent shipments, LC-MS/MS instrumentation manufactured in Japan and the United States, and specialized containment infrastructure sourced from domestic fabrication. Single-source vulnerability concentrates in reference standard import pathways, exposing laboratories to customs clearance delays and currency volatility. Distribution runs through direct manufacturer relationships for capital equipment and distributor networks for consumables and reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's medicinal cannabis testing market represents early-cycle expansion, with TGO 93 compliance deadlines compressing testing turnaround times and forcing licensed producers to lock in multi-year service contracts before capacity constraints harden.
For Market Incumbents: Fortify market position by embedding continuous verification capabilities into laboratory quality systems per TGA's analytical procedure lifecycle management guidance, and pursue multi-site consolidation across Perth and Adelaide to spread compliance infrastructure costs. Emerging UHPLC-PDA platform adoption by Melbourne's northern suburban producers threatens pricing power for generalist service providers lacking high-throughput workflows. For New Entrants and Emerging Players: Anchor in Queensland's emerging psychedelic-assisted therapy research institutions, where GMP-certified analytical demand outpaces established cannabis-focused laboratory capacity. Brisbane's recruitment bottlenecks for analytical chemists with botanical matrix experience create white-space opportunity for specialized terpenoid profiling services beyond THC/CBD quantification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors laboratories with ISO 17025 and TGA mutual recognition arrangements that can capture export certification revenue streams as Office of Drug Control licensing permits international shipments. Acquisition targets should demonstrate established method validation timelines for novel matrices and embedded LIMS configurations capturing chain-of-custody documentation. The signal to monitor is harmonization with international pharmacopeial standards, which would trigger method validation investment cycles and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| TGO 93 Accreditation Investment | Batch compliance mandates from the Therapeutic Goods Administration create non-negotiable entry barriers for testing facilities. |
| UHPLC-PDA Platform Deployment | Melbourne's licensed producers compress method runtimes from thirty minutes to under eight minutes, reshaping throughput economics. |
| Multi-Site Laboratory Consolidation | Perth and Adelaide operators spread TGA compliance infrastructure costs across regional networks with lower testing volumes. |
| Terpenoid Profiling Capability Buildout | Full-spectrum chemotyping beyond THC/CBD enables premium positioning for strain-specific therapeutic formulations. |
| Export Certification Pathway Development | ISO 17025 and TGA mutual recognition arrangements open batch certification revenue for international shipments. |
Research Methodology
A spread of perspectives from TGA regulatory affairs specialists, licensed producer quality control directors, analytical laboratory technical managers, and chromatography equipment procurement officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through TGO 93 guidance documents, Office of Drug Control licensing databases, and ISO 17025 accreditation records. Bottom-up triangulation across testing volume estimates from metropolitan analytical clusters and top-down validation against cultivation scale-up announcements anchored the market sizing framework.
Segmentation dimensions modeled include testing service delivery model, analytical technology platform, end-user procurement maturity, and application regulatory intensity across the projection horizon. CAGRs were derived from testing volume elasticities to licensed producer expansion timelines and TGO 93 compliance deadline schedules. Industry-specific forecast inputs incorporated reference standard import dependency patterns and analytical chemist labor market concentration in Sydney and Melbourne.
Material uncertainties — evolving cannabinoid scheduling decisions, potential harmonization with international pharmacopeial standards, and TGA threshold tightening for microbial and heavy metal detection — sit outside the modeled envelope. Forecasts reflect assumptions about accreditation pathway timelines and cultivation facility commissioning schedules that could shift with regulatory process changes. Recalibration cycles align with material shifts in TGA guidance releases and Office of Drug Control licensing volume trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
US Medical Marijuana Market