
 North America Hemp-Derived Cannabidiol Market | 2026-2036
North America Hemp-Derived Cannabidiol Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hemp-Derived Cannabidiol Market Intelligence
Direct-to-consumer e-commerce is tilting toward subscription models and telehealth integrations. Charlotte's Web Holdings, Inc. leverages its established retail pharmacy partnerships to sustain shelf presence across mass-market channels. CV Sciences, Inc. anchors its position through rigorous third-party testing protocols that differentiate quality tiers. Kazmira competes by controlling upstream extraction capacity, while Bluebird Botanicals specializes in certified organic sourcing that commands premium positioning.
Hemp-derived cannabidiol refers to non-intoxicating cannabinoids extracted from Cannabis sativa L. containing less than 0.3% delta-9 THC by dry weight, typically isolated through CO2 or ethanol extraction methods for use in therapeutic and wellness formulations. The primary commercial purpose centers on delivering purported anti-inflammatory and anxiolytic benefits without psychoactive effects. Oils and tinctures currently dominate volume as established delivery formats with proven bioavailability profiles, while edibles represent the fastest-expanding margin pool as food and beverage manufacturers integrate CBD into functional product lines. The wellness application segment captures the broadest consumer base, whereas healthcare-directed sales remain constrained by FDA prohibition on disease claims.
The FDA maintains enforcement discretion over CBD-infused food and dietary supplements, while the 2018 Farm Bill delegated hemp cultivation oversight to state departments of agriculture, creating a patchwork of compliance requirements across state lines. Individual states such as California and New York impose additional testing, labeling, and registration mandates that raise barriers to market entry. Stakeholders must monitor pending federal rulemaking on CBD safety profiles and corresponding state alignment decisions that will determine whether interstate distribution networks consolidate or fragment.
Market Dynamics
The North America hemp-derived cannabidiol market operates under persistent regulatory fragmentation, where state-level THC threshold variations and FDA enforcement discretion over food and dietary supplements create divergent compliance costs that reshape competitive positioning across interstate distribution networks.
Growth Catalysts
- Telehealth integration:Direct-to-consumer platforms now embed subscription models with remote consultation workflows, expanding access beyond traditional retail pharmacy channels into wellness-directed personal care routines.
- 2018 Farm Bill delegation:USDA oversight of hemp cultivation transferred to state departments of agriculture, enabling California and Colorado to develop mature vertically integrated supply clusters that reduce interstate friction.
- CO2 extraction scaling:Supercritical fluid methods achieve higher cannabinoid retention rates than ethanol alternatives, driving quality-tier differentiation that commands premium shelf positioning in mass-market channels.
Market Restraints
- Input cost volatility:Hemp biomass prices fluctuate with weather-dependent cultivation yields across the American Midwest, compressing margin predictability for downstream extractors.
- Regulatory friction:FDA prohibition on disease claims for CBD-infused products blocks healthcare-directed sales expansion, constraining revenue diversification beyond wellness applications.
- Substitution threat:Synthetic cannabinoids and minor cannabinoid isolates (CBG, CBN) capture formulation attention from hemp-derived CBD in functional beverage development pipelines.
Strategic Opportunities
- Underpenetrated sub-regions:Texas and Florida retail corridors show limited CBD shelf density relative to California and Colorado, presenting first-mover expansion potential for compliant operators.
- Regulatory tailwind:Pending federal rulemaking on CBD safety profiles may align state testing mandates, reducing patchwork compliance burdens that currently fragment interstate distribution networks.
- Distribution innovation:Pharmacy benefit manager partnerships and employer wellness program integrations represent emerging B2B channels beyond conventional e-commerce and retail placements.
Industry Challenges
- Analytical chemistry talent scarcity:Third-party testing laboratories face recruitment bottlenecks for chromatography specialists capable of verifying sub-0.3% THC compliance across diverse product matrices.
- Certification timeline compression:Organic certification processes through USDA-accredited bodies extend 18-24 months, delaying premium positioning strategies for certified sourcing claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hemp-Derived Cannabidiol Market |
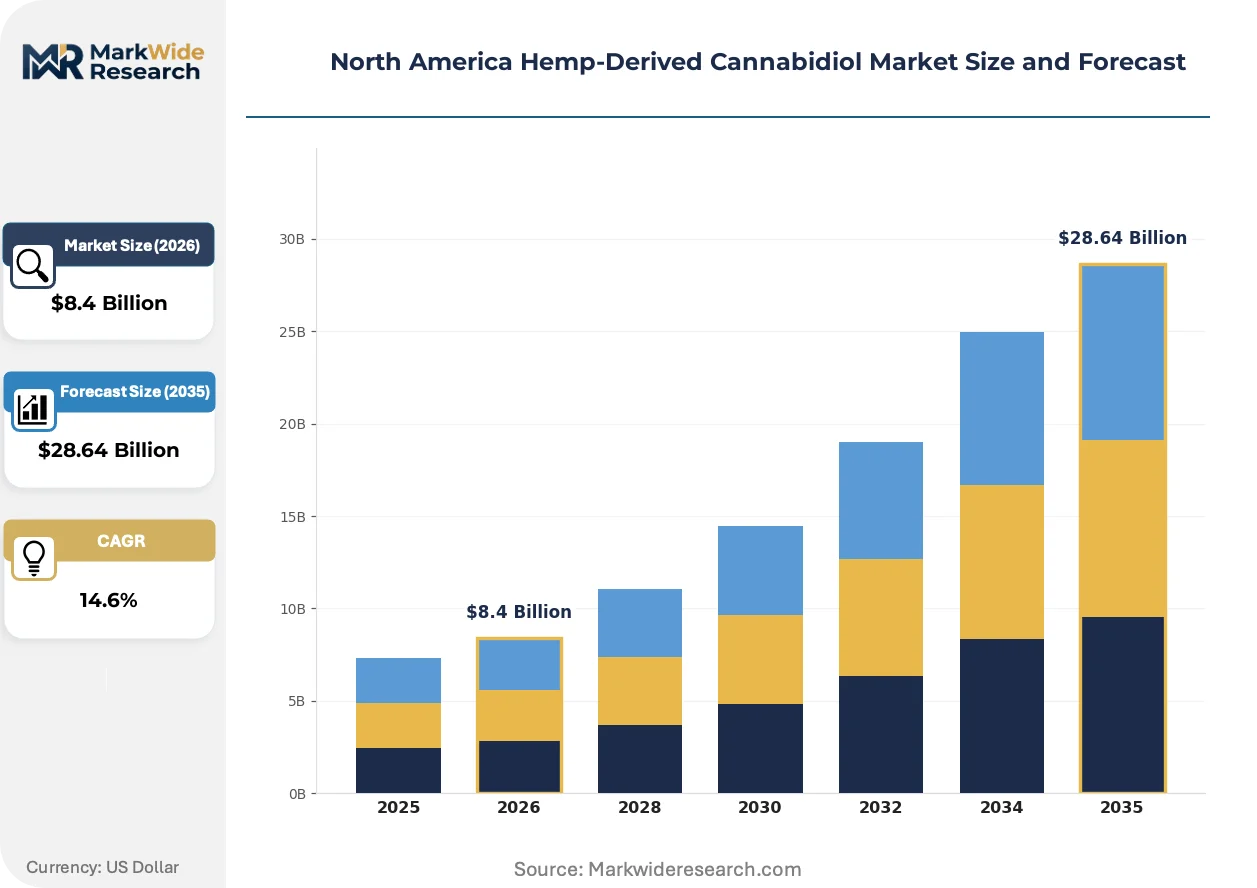
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Edibles, Capsules, Tinctures End User: Retail Consumers, Health Professionals, Manufacturers, Distributors Application: Healthcare, Wellness, Beauty Products, Food & Beverage Sales Channel: Online Retail, Brick-and-Mortar Stores, Dispensaries, Wholesale |
| Companies Covered | CV Sciences, Inc., Charlotte’s Web Holdings, Inc., Elixinol, ENDOCA, CBD American Shaman, Kazmira, Bluebird Botanicals, HempMeds, Medterra CBD, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hemp-Derived Cannabidiol Market Strategic Shifts & Innovations
Digital infrastructure is virtualizing how hemp-derived CBD reaches consumers, compressing traditional wholesale-retail hierarchies while regulatory clarity efforts and shifting wellness consumption patterns reshape competitive entry points across North American markets.
Blockchain-enabled supply chain verification is virtualizing provenance documentation for hemp-derived CBD products. Premium wellness brands and mass-market retailers now demand immutable batch records from biomass origin through finished goods. This technology is virtualizing trust mechanisms that previously required extensive third-party laboratory relationships, reducing verification costs while accelerating consumer confidence formation in direct-to-consumer channels.
FDA enforcement discretion over CBD-infused food and dietary supplements continues creating industrial uncertainty. The agency's pending safety assessment framework will determine whether interstate commerce normalizes or fragments further. California and New York's additional state-level registration mandates are forcing national brands to maintain parallel compliance systems, raising operational complexity for multi-state operators.
Subscription-based replenishment models are displacing one-time e-commerce purchases among repeat wellness consumers. Direct-to-consumer platforms now embed automated delivery scheduling with telehealth consultation access, replacing traditional retail pharmacy discovery patterns. This behavioral shift concentrates most visibly in Colorado and California urban corridors where digitally native wellness brands have established mature customer bases.
North America Hemp-Derived Cannabidiol Market Segmentation
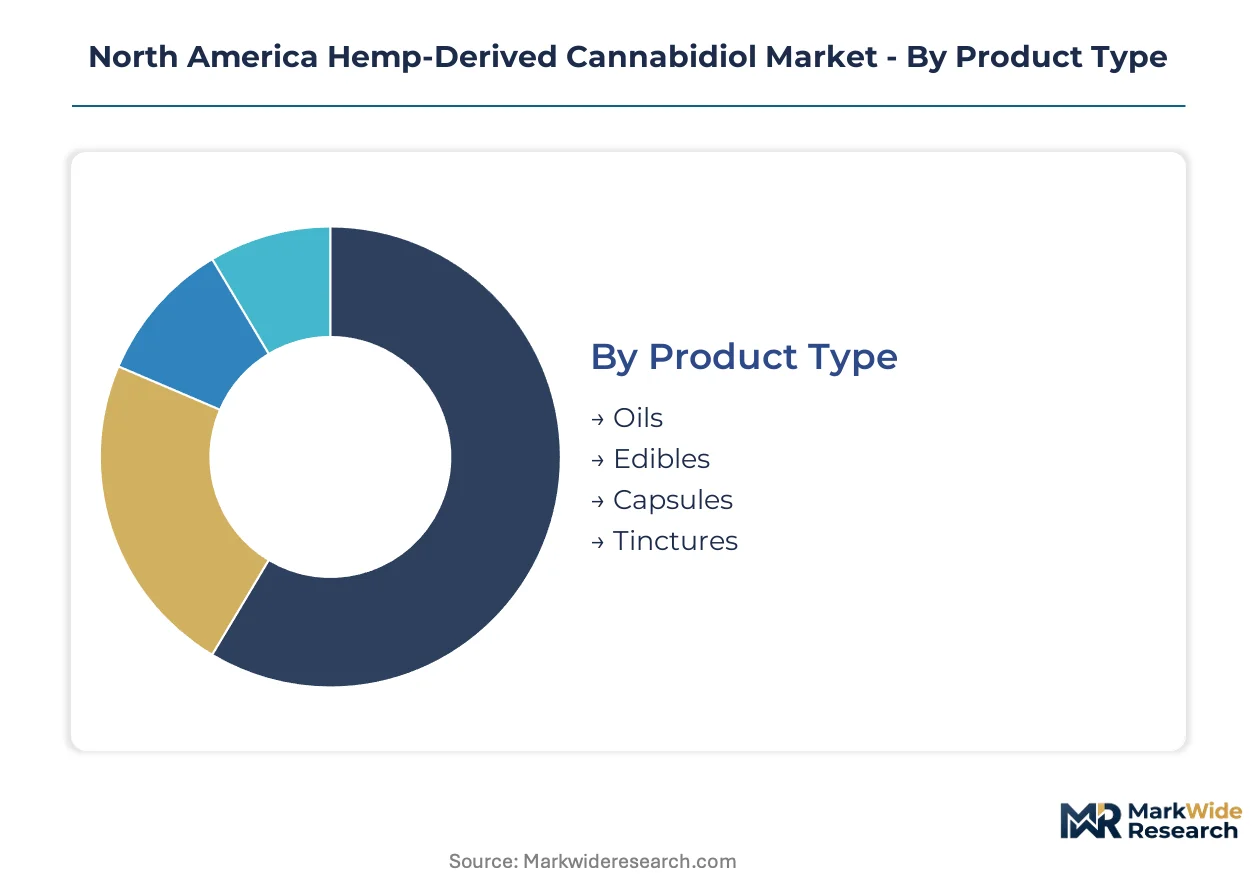
Segmentation in hemp-derived CBD markets determines compliance pathways, margin capture, and distribution architecture. Product format dictates extraction method and testing burden. Channel selection shapes regulatory exposure and customer acquisition economics.
Product Type:
Inventory velocity varies dramatically across formats, with edibles turning fastest due to impulse purchasing patterns and oils maintaining the slowest rotation due to extended shelf-stability expectations.
- Oils:Concentrated lipid-soluble formulations typically suspended in MCT or hemp seed carrier oils, standardized to milligram CBD declarations. California and Colorado wellness retailers stock these as core SKUs, though FDA prohibition on disease claims constrains healthcare-directed positioning.
- Edibles:CBD-infused food and beverage formats including gummies, chocolates, and functional beverages subject to state-level food safety mandates. Texas and Florida retail corridors show accelerating shelf placement as mass-market grocers test category performance.
- Capsules:Encapsulated isolate or full-spectrum powder in gelatin or vegetable-based shells, offering precise dosing for supplement regimens.
- Tinctures:Alcohol or glycerin-based liquid extracts with faster sublingual absorption profiles, historically the format of choice for pharmacy channel placement.
Oils dominate installed base. Edibles are where expansion concentrates.
End User:
Procurement authority and volume scale separate these constituencies, with manufacturers commanding largest lot sizes and retail consumers driving frequency.
- Retail Consumers:Individual purchasers seeking wellness applications through direct-to-consumer platforms or mass-market retail, with subscription models displacing one-time purchases in Colorado and California urban corridors.
- Health Professionals:Clinicians and wellness practitioners recommending CBD as adjunctive support, constrained by liability concerns and absence of FDA-approved prescribing guidelines.
- Manufacturers:B2B purchasers of bulk isolate, distillate, or crude extract for downstream formulation into finished goods.
- Distributors:Intermediaries managing logistics, state compliance documentation, and retailer relationships across fragmented regulatory environments.
Retail consumers anchor volume. Health professionals represent the steepest expansion trajectory if federal rulemaking clarifies permissible communication.
Application:
Margin structure and regulatory scrutiny diverge sharply, with beauty products commanding premium positioning and food and beverage facing the most intensive compliance layering.
- Healthcare:Therapeutic-directed use currently limited by FDA enforcement discretion over disease claims, with most activity concentrated in wellness-adjacent positioning rather than clinical protocols.
- Wellness:Stress relief, sleep support, and recovery applications capturing the broadest consumer base through personal care routine integration.
- Beauty Products:Topical formulations leveraging anti-inflammatory positioning in skincare and haircare, with premium pricing tied to certified organic sourcing claims.
- Food & Beverage:Functional ingredient integration requiring navigation of state-level registration mandates in California and New York alongside federal food safety frameworks.
Wellness commands current revenue concentration. Food and beverage is climbing the fastest as CPG manufacturers accelerate formulation pipelines.
Sales Channel:
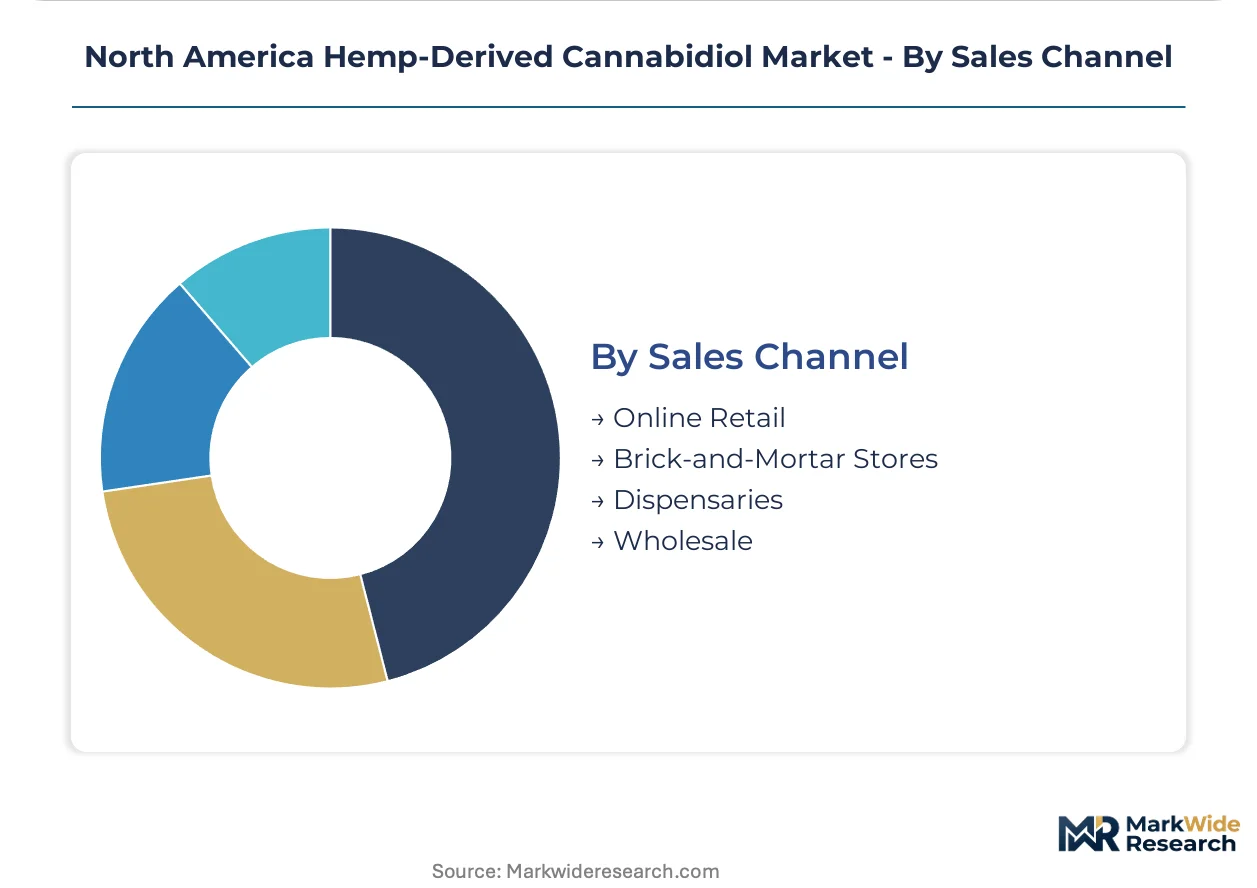
Customer acquisition cost and regulatory burden trade off across channels, with dispensaries carrying highest compliance overhead and online retail offering broadest geographic reach.
- Online Retail:Direct-to-consumer platforms embedding subscription automation and telehealth consultation access, compressing traditional wholesale-retail hierarchies.
- Brick-and-Mortar Stores:Mass-market retail and specialty wellness shops where Charlotte's Web Holdings sustains shelf presence through established pharmacy partnerships.
- Dispensaries:Cannabis-licensed retail environments with strict THC verification requirements, concentrated in states with adult-use frameworks.
- Wholesale:B2B supply to downstream formulators and retailers, where Kazmira competes through upstream extraction capacity control.
Online retail dominates customer acquisition efficiency. Brick-and-mortar stores are gaining share fastest as conventional retailers normalize CBD category placement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 5 corridor anchors transcontinental distribution for hemp-derived CBD, linking Pacific Northwest cultivation zones to Southern California processing clusters and cross-border Canadian terminals.
United States
California and Colorado wellness corridors concentrate mature retail infrastructure and vertically integrated extraction capacity. FDA enforcement discretion over food and dietary supplements creates compliance layering that favors multi-state operators with dedicated regulatory affairs teams. Denver-Boulder and Los Angeles-San Diego clusters host supercritical CO2 extraction facilities serving national distribution networks.
Canada
Alberta and British Columbia prairie cultivation supplies biomass to Ontario and Quebec formulation hubs. Health Canada oversees hemp licensing under the Cannabis Act, with provincial regulators managing retail distribution frameworks. Toronto-Waterloo corridor processors leverage proximity to US border crossings for cross-border ingredient trade.
Mexico
Jalisco and Nuevo León states pilot hemp cultivation programs under federal agricultural reform initiatives. COFEPRIS pharmaceutical regulator evaluates CBD safety profiles for potential dietary supplement classification. Guadalajara metropolitan area attracts preliminary extraction investment targeting domestic wellness market development.
North America Hemp-Derived Cannabidiol Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream controlling extraction capacity and certified sourcing claims. The vendor base stratifies across three tiers: established wellness brands with pharmacy channel presence, mid-scale extractors competing on third-party testing protocols, and regional cultivators selling crude biomass to downstream formulators. Dominant competitive moves include backward integration into captive hemp cultivation and telehealth platform partnerships that embed subscription replenishment workflows.
Among US-based operators, Charlotte's Web Holdings, Inc. and CV Sciences, Inc. exemplify the platform-integrator archetype with sustained mass-market retail presence, while Kazmira occupies a position representing upstream extraction specialists competing through capacity control rather than consumer brand equity.
| Leading Market Players |
|---|
| CV Sciences, Inc. |
| Charlotte's Web Holdings, Inc. |
| Elixinol |
| ENDOCA |
| CBD American Shaman |
| Kazmira |
| Bluebird Botanicals |
| HempMeds |
| Medterra CBD |
| Others |
Cost & Logistics Intelligence
Commodity price volatility in American Midwest hemp biomass determines both margin compression thresholds and geographic sourcing patterns across extraction tiers. This input cost instability widens spreads between certified organic premium positioning and standard-grade economy offerings while forcing downstream formulators toward multi-origin supply hedging.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade isolate contracts from bulk crude extract spot purchases. Three-tier pricing stratification across premium, standard, and economy levels reflects certification grade differentiation and CO2 extraction method premiums. Cost compression in standard tiers intensifies as ethanol-extracted alternatives flood Texas and Florida retail corridors. Retail consumers show highest price sensitivity, whereas manufacturers procuring bulk distillate prioritize batch consistency over per-kilogram savings.
Supply Chain Analysis
Extended payment terms from California wellness brands strain Colorado extraction facility cash conversion cycles. American hemp cultivation draws from Kentucky, Oregon, and Colorado prairie zones, with Canadian prairie biomass supplementing peak season shortfalls. Supply chain risk centers on single-source dependency for USDA organic certified biomass. Distribution runs through vertically integrated processor-retailer networks rather than traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with telehealth-integrated subscription models driving penetration beyond legacy retail pharmacy discovery patterns.
For Market Incumbents: Harden quality-tier differentiation through captive CO2 extraction capacity in Colorado and California clusters. Defend shelf position against synthetic cannabinoid substitution by embedding third-party testing protocols into consumer-facing packaging. Backward integration into certified organic hemp cultivation secures margin protection against biomass price spikes. For New Entrants and Emerging Players: Establish a beachhead in Texas and Florida mass-market retail corridors where CBD shelf density lags California benchmarks. Target employer wellness program integrations as an underpenetrated B2B channel beyond conventional e-commerce. Lead with telehealth partnership propositions that bundle subscription replenishment with remote consultation access. For Investors and Strategic Acquirers: Pending FDA safety assessment rulemaking reshapes the acquisition landscape by determining whether interstate distribution networks consolidate or fragment. Five-to-ten year viability favors upstream extraction specialists with verified THC compliance infrastructure over brand-dependent retailers. Monitor state-level alignment decisions following federal rulemaking as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Embedding remote consultation workflows captures subscription-driven customer lifetime value in California and Colorado corridors. |
| USDA Organic Certification Investment | Eighteen-to-twenty-four month certification timelines lock in premium positioning before competitor supply maturation. |
| Multi-State Compliance Infrastructure | Parallel registration systems in California and New York enable uninterrupted interstate distribution network operation. |
| Supercritical CO2 Capacity Expansion | Higher cannabinoid retention rates than ethanol alternatives command mass-market pharmacy channel shelf placement. |
| Blockchain Supply Chain Verification | Immutable batch records reduce third-party laboratory verification costs in direct-to-consumer channels. |
Research Approach
Desk research of FDA enforcement discretion records, state agricultural department hemp cultivation reports, and third-party laboratory certification databases preceded structured interviews with extraction facility operations managers, retail pharmacy category buyers, wellness brand supply chain directors, and telehealth platform commercial leads. Primary fieldwork across Denver-Boulder and Los Angeles-San Diego processing clusters combined with customs trade data and SEC 10-K filings from publicly traded operators. Bottom-up volume modeling and top-down market sizing triangulation validated segment-level estimates.
Assumption sets held FDA prohibition on disease claims constant while varying state-level THC threshold alignment scenarios across the projection horizon. Segmentation dimensions included product format, extraction method, certification tier, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline penetration estimates, with hemp biomass yield volatility and subscription model adoption rates as industry-specific forecast inputs.
Sensitivities concentrate around FDA safety assessment timing, state-level registration mandate harmonization, and synthetic cannabinoid formulation pipeline acceleration. Forecasts reflect documented assumptions regarding telehealth integration velocity and mass-market retail normalization trajectories. Macroeconomic contraction, regulatory reversal, or biotechnology substitution breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market