
 US Minor Cannabinoids Market | 2026-2036
US Minor Cannabinoids Market Size, Share, and Industry Trends Forecast 2026-2036
US Minor Cannabinoids Market Intelligence
Colorado extraction facilities is rebalancing output toward minor cannabinoid fractions as hemp biomass processing capacity expands beyond CBD saturation. Mile High Labs leverages in-house chromatography to sustain pharmaceutical-grade CBG isolate production. Laurelcrest anchors West Coast supply through controlled-environment cultivation partnerships. GCM Holdings competes on bulk volume across multiple minor cannabinoid SKUs.
US minor cannabinoids comprise non-THC, non-CBD phytochemicals—cannabigerol, cannabinol, cannabichromene, and tetrahydrocannabinolic acid—typically present at concentrations below one percent in raw hemp, requiring multi-stage extraction and purification to achieve ninety-five percent-plus purity for commercial use. These compounds serve as active ingredients in precision-dosed therapeutics, cosmeceuticals, and functional formulations where specific receptor binding profiles determine product positioning. CBG dominates current pharmaceutical offtake due to its demonstrated affinity for alpha-2 adrenergic and 5-HT1A receptor modulation. CO2 extraction commands premium positioning among end users demanding residual-solvent-free certification, while hydrocarbon methods occupy cost-sensitive bulk supply tiers.
FDA oversight of cannabinoid-containing drug products, USDA hemp production rules under the 2018 Farm Bill, and state-level cannabis regulatory frameworks collectively determine permissible channels, labeling requirements, and interstate shipment legality for minor cannabinoid goods. Product developers must navigate this overlapping jurisdiction to secure compliant market access. Stakeholders should monitor pending FDA enforcement discretion policies and emerging state THCA thresholds that could abruptly reclassify currently legal inventory.
Market Dynamics
Pharmaceutical formulators are pulling minor cannabinoid supply chains toward GMP-certified isolation capacity as FDA drug-approval pathways harden purity requirements beyond nutraceutical baselines.
Growth Catalysts
- 2018 Farm Bill interstate commerce provisions:Non-THC hemp derivatives now ship across state lines without Controlled Substances Act friction, unlocking multi-state formulation contracts for CBG and CBN isolates.
- Alpha-2 adrenergic receptor targeting:CBG's demonstrated binding affinity drives pharmaceutical pipeline prioritization for anxiety and pain modulation therapeutics.
- California biotech corridor clustering:Extraction laboratories co-locate with ISO 17025 testing facilities in San Diego and Oakland, compressing batch-release timelines for clinical-grade material.
Market Restraints
- Sub-one-percent raw hemp concentrations:Cannabigerol and cannabinol occur at trace levels requiring multi-stage chromatography, inflating unit costs versus CBD isolation.
- FDA enforcement discretion uncertainty:Pending cannabinoid-containing drug product policies create inventory risk for distributors holding non-NDI-notified isolates.
- Hemp biomass oversupply concentration:CBD market saturation has stranded processing capacity in Kentucky and Colorado, limiting capital redeployment toward minor cannabinoid retooling.
Strategic Opportunities
- THCA regulatory threshold arbitrage:State-level tetrahydrocannabinolic acid limits below federal hemp definitions create compliant product categories in Texas and Florida markets.
- Cosmeceutical receptor-specific positioning:Cannabichromene's TRPV1 modulation supports topical formulations targeting dermatological inflammation without drug-claim triggers.
- CO2 residual-solvent-free certification:Supercritical extraction methods command premium pricing from pharmaceutical buyers rejecting hydrocarbon-processed bulk supply.
Industry Challenges
- Chromatography operator scarcity:Preparative HPLC and simulated moving bed purification require specialized skill sets concentrated in analytical chemistry programs with limited cannabinoid-specific training pipelines.
- USDA hemp production rule batch testing:Total THC compliance windows create harvest-timing risk for cultivators supplying minor cannabinoid feedstock, disrupting isolate production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Minor Cannabinoids Market |
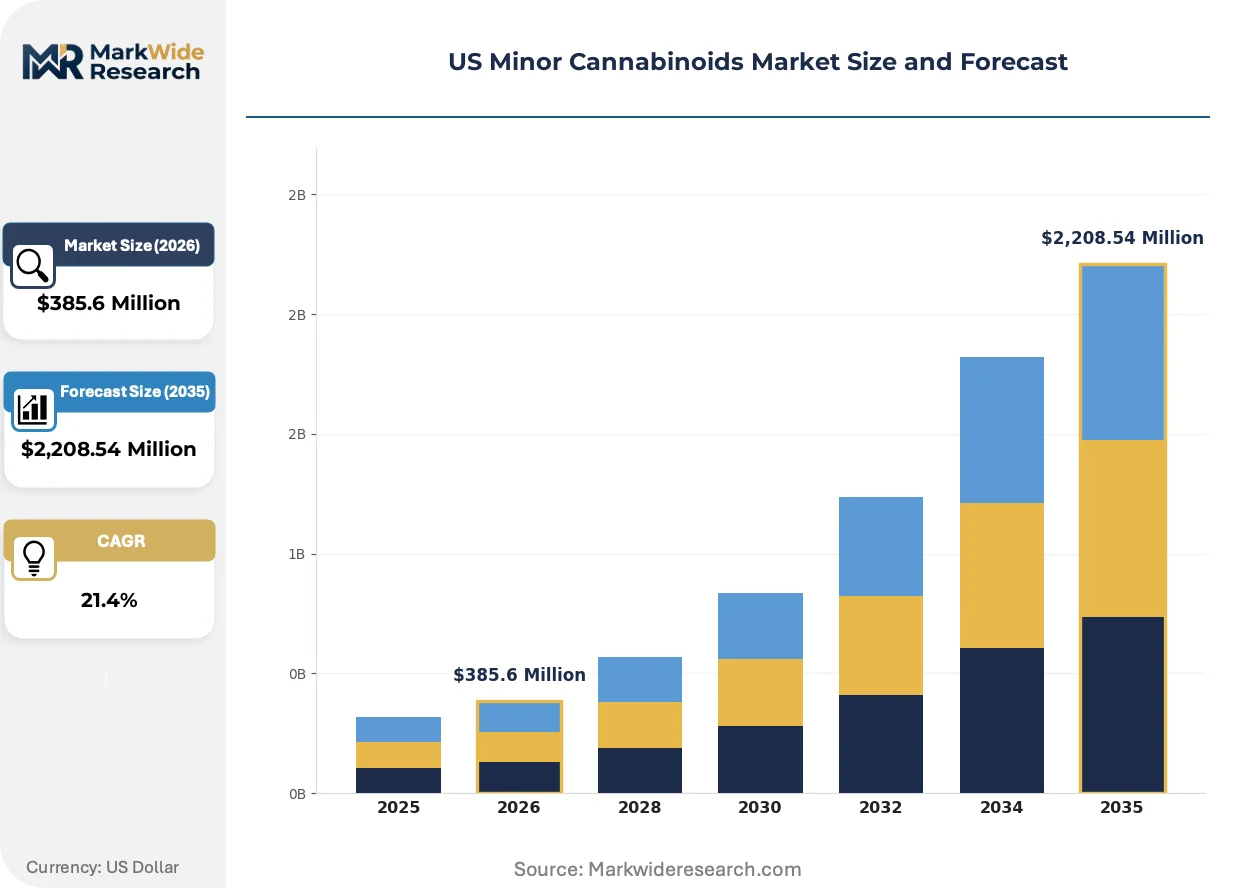
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $2,208.54 Million |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
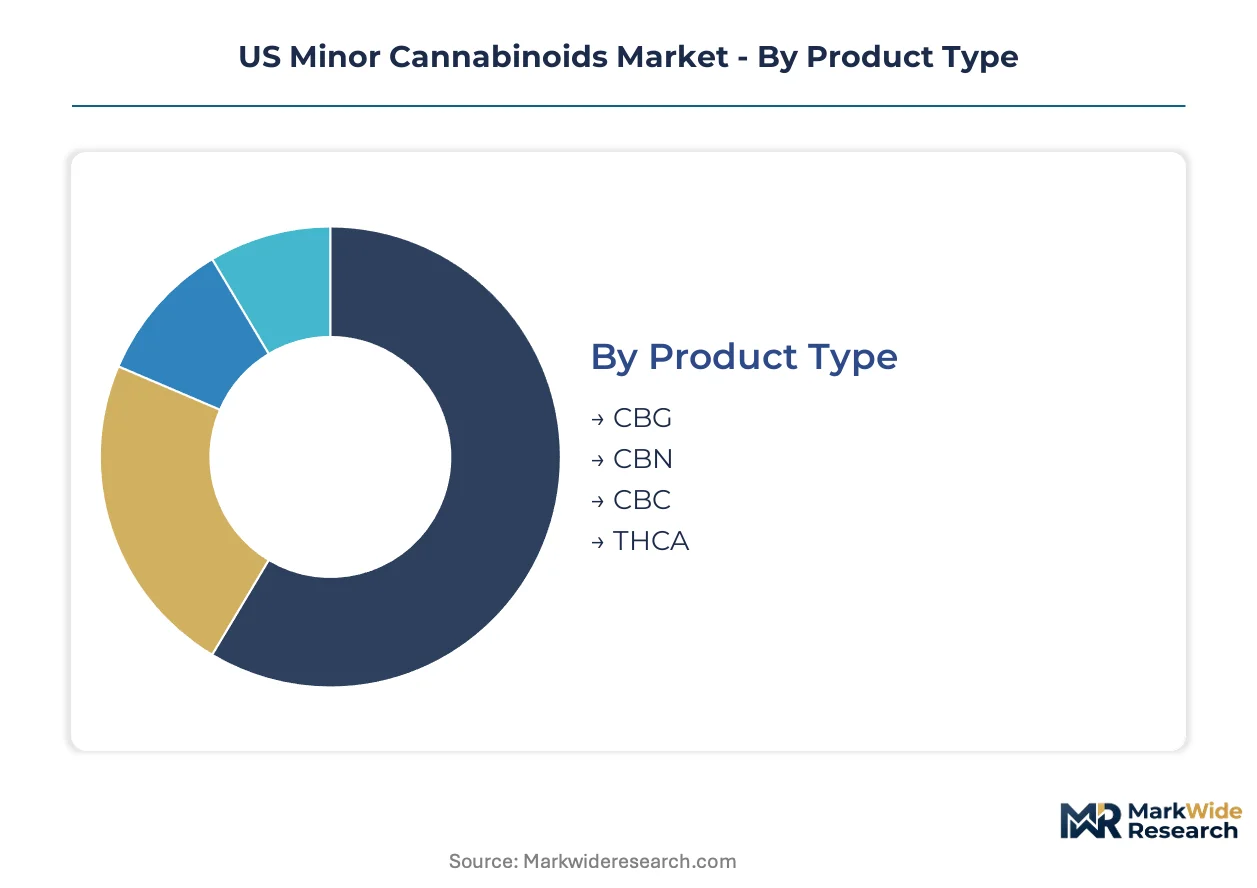
| Segmentation | Product Type: CBG, CBN, CBC, THCA Extraction Method: CO2 Extraction, Solvent Extraction, Hydrocarbon Extraction, Olive Oil Extraction End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Food & Beverage Formulation Type: Oils, Edibles, Topicals, Capsules |
| Companies Covered | CBD. INC., Laurelcrest, Mile High Labs, High Purity Natural Products, Fresh Bros Hemp Company, GCM Holdings, LLC (Global Cannabinoids), Rhizo Sciences, BulKanna, GenCanna, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Minor Cannabinoids Market Strategic Shifts & Innovations
Continuous processing technologies and receptor-targeted formulation science are compressing the gap between agricultural hemp output and pharmaceutical-grade isolate specifications.
Simulated moving bed chromatography is decentralizing purification capacity away from centralized toll-processing facilities toward integrated extraction-cultivation operations. Mid-scale hemp processors in Oregon and Vermont now deploy in-house SMB systems to capture CBG fractions previously sent to third-party refiners. This technology diffusion is collapsing minimum efficient scale thresholds for pharmaceutical-grade isolate production.
FDA cannabinoid-containing drug product guidance development is forcing IND-enabling study investments before commercial scale-up. Formulators now commission stability and toxicology packages earlier in development cycles to secure pre-approval inspection readiness. Biotech sponsors in Massachusetts and North Carolina are front-loading regulatory capital to preempt enforcement discretion shifts.
Certificate-of-analysis-driven supplier selection is consolidating procurement authority among quality-assurance functions previously managed by commodity sourcing teams. Pharmaceutical buyers now mandate third-party testing for residual solvents, heavy metals, and pesticide panels before contract execution. This verification burden favors vertically integrated extractors with captive analytical laboratories over merchant distributors in California and Colorado supply chains.
US Minor Cannabinoids Market Segmentation
Minor cannabinoid procurement decisions hinge on purity thresholds that vary dramatically across end-use applications. FDA drug-approval pathways impose GMP certification requirements that filter supplier eligibility differently for each segment category.
Product Type:
FDA oversight intensity scales with therapeutic claims, forcing pharmaceutical-grade isolates through IND-enabling toxicology packages while nutraceutical-grade material navigates less stringent New Dietary Ingredient notification paths.
- CBG:Cannabigerol serves as the precursor molecule for all other cannabinoid biosynthesis, requiring specialized chromatography to isolate from decarboxylated hemp extract. Pharmaceutical formulators in Massachusetts and North Carolina prioritize CBG for alpha-2 adrenergic receptor modulation programs targeting anxiety therapeutics.
- CBN:Cannabinol emerges from THC oxidation during storage and processing, delivering sedative properties through distinct CB1 partial agonism. Sleep-aid nutraceutical brands in Colorado's Front Range corridor drive CBN isolate offtake despite sub-zero-percent natural abundance forcing costly synthetic conversion or extended biomass aging.
- CBC:Cannabichromene modulates TRPV1 and TRPA1 ion channels for dermatological applications without triggering FDA drug-claim scrutiny.
- THCA:Tetrahydrocannabinolic acid occupies a regulatory threshold zone where state-level limits below federal hemp definitions create compliant market access in Texas and Florida.
Leading the category by volume: CBG. Growing fastest: THCA.
Extraction Method:
Residual solvent certification requirements fragment procurement patterns across pharmaceutical and nutraceutical buyer tiers, with supercritical methods commanding premium positioning.
- CO2 Extraction:Supercritical carbon dioxide systems deliver residual-solvent-free certification essential for FDA pre-approval inspection readiness. California biotech corridor formulators mandate CO2-processed CBG isolate for IND-submission material, accepting 40-60% cost premiums over hydrocarbon alternatives.
- Solvent Extraction:Ethanol-based methods balance throughput efficiency with tunable polarity for broad-spectrum cannabinoid recovery. Mid-scale Oregon processors deploy ethanol systems for CBG crude production feeding downstream simulated moving bed chromatography units.
- Hydrocarbon Extraction:Butane and propane methods dominate bulk CBN production for cost-sensitive nutraceutical applications where residual solvent thresholds remain below pharmaceutical specifications.
- Olive Oil Extraction:Cold-infusion techniques serve artisanal cosmetics brands seeking organic certification alignment without industrial processing infrastructure.
Highest certification burden: CO2 Extraction. Steepest expansion trajectory: Solvent Extraction.
End User:
Regulatory pathway complexity stratifies supplier relationships, with pharmaceutical buyers front-loading compliance investments and cosmetics brands exploiting topical claim flexibility.
- Pharmaceuticals:IND-enabling studies and stability protocols dominate CBG procurement specifications. Biotech sponsors commission third-party heavy metals and pesticide panels before contract execution, consolidating authority within quality-assurance functions.
- Nutraceuticals:New Dietary Ingredient notification gaps create inventory risk for CBN distributors as FDA enforcement discretion policies remain pending.
- Cosmetics:TRPV1-targeting CBC topicals exploit dermatological inflammation positioning without crossing into drug-claim territory.
- Food & Beverage:GRAS self-determination pathways for cannabinoid ingredients face state-level THC contamination thresholds that disrupt interstate shipment legality.
Deepest compliance investment: Pharmaceuticals. Gaining share fastest: Cosmetics.
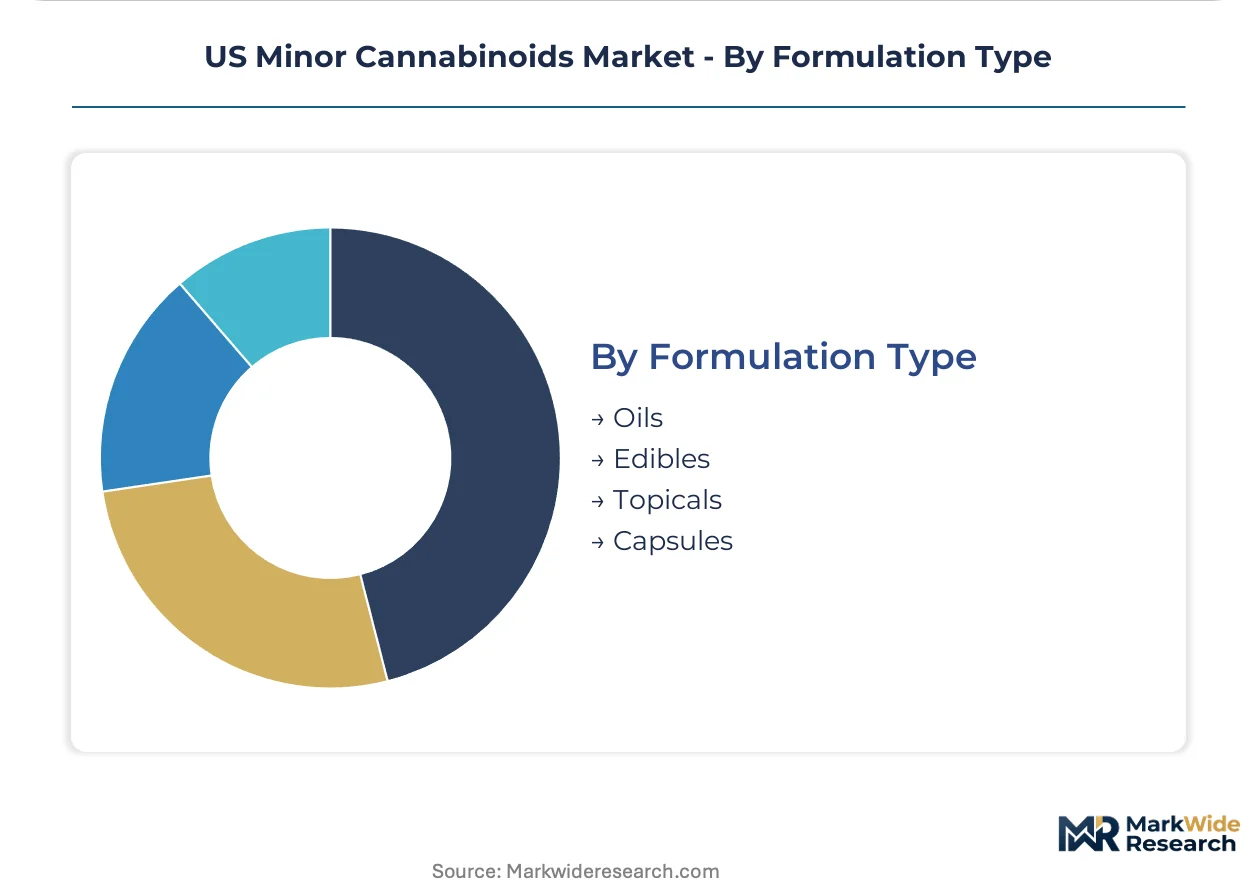
Formulation Type:
Dosage precision requirements and shelf-stability demands shape isolate specification sheets differently across delivery mechanisms.
- Oils:Sublingual tinctures demand high-purity CBG isolate with defined terpene profiles for entourage effect positioning in premium nutraceutical tiers.
- Edibles:Gummy and beverage applications require water-compatible nanoemulsion technology for bioavailability enhancement, concentrating demand among processors with in-house formulation chemistry capabilities.
- Topicals:CBC-infused creams leverage TRPV1 modulation for inflammation claims without FDA drug-approval pathways, attracting cosmeceutical brands seeking receptor-specific positioning.
- Capsules:Hard-shell and soft-gel formats prioritize batch-to-batch consistency for pharmaceutical sponsors conducting clinical trials with precise dosing requirements.
Most technically demanding: Oils. Expanding most quickly: Topicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hemp biomass from Kentucky and Colorado anchors US minor cannabinoid feedstock supply. FDA and USDA frameworks reshape interstate commerce corridors. State-level THCA thresholds fragment compliant market access.
California
San Diego and Oakland extraction laboratories cluster near ISO 17025 testing facilities, compressing batch-release timelines for clinical-grade CBG isolate. California's biotech corridor attracts pharmaceutical formulators demanding GMP-certified supply chains. State cosmetic regulations permit TRPV1-targeting CBC topicals without drug-claim triggers.
Colorado
Front Range processors retool CBD-saturated capacity toward minor cannabinoid fractionation. Mile High Labs leverages in-house chromatography for pharmaceutical-grade isolate production. State hemp rules align with federal thresholds, enabling interstate CBN shipments for sleep-aid nutraceutical brands.
Kentucky
Stranded CBD processing infrastructure limits capital redeployment toward minor cannabinoid retooling. USDA hemp production rules create harvest-timing risk for cultivators supplying CBG feedstock. Central Appalachian biomass concentration supports bulk crude production for downstream refiners.
Texas
State THCA limits below federal hemp definitions create compliant product categories for acid-form cannabinoid distribution. Texas distributors exploit regulatory arbitrage gaps to supply Florida and adjacent markets. Dallas-Fort Worth logistics hubs anchor interstate shipment consolidation points.
Massachusetts
Biotech sponsors front-load IND-enabling study investments to preempt FDA enforcement discretion shifts. Cambridge and Boston pharmaceutical clusters prioritize alpha-2 adrenergic receptor targeting programs. State cannabis regulations impose stricter contaminant panels than federal baselines.
US Minor Cannabinoids Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cosmeceutical specialization and regional distribution partnerships. The vendor base stratifies across pharmaceutical-grade certification holders, bulk commodity suppliers, and formulation-integrated brands. Three archetypes dominate: vertically integrated extractors with captive analytical labs, toll processors leveraging third-party chromatography, and brand marketers outsourcing all production. Competitive moves concentrate on GMP certification acquisition and multi-state distribution licensing.
Among Colorado-based extraction specialists, Mile High Labs and Laurelcrest exemplify the vertically integrated archetype, while GCM Holdings occupies a position emphasizing bulk volume across multiple minor cannabinoid SKUs. These entities represent contrasting strategic postures within a market where purification capability and regulatory compliance credentials determine supplier selection authority.
| Leading Market Players |
|---|
| CBD. INC. |
| Laurelcrest |
| Mile High Labs |
| High Purity Natural Products |
| Fresh Bros Hemp Company |
| GCM Holdings, LLC (Global Cannabinoids) |
| Rhizo Sciences |
| BulKanna |
| GenCanna |
| Others |
Cost & Logistics Intelligence
Hemp biomass spot pricing in Kentucky and Colorado compression zones cascades through three distinct purification cost tiers, with pharmaceutical-grade CBG isolate commanding premiums that reflect chromatography intensity and residual-solvent certification burdens downstream.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical buyers from nutraceutical procurement tiers, with CO2-extracted CBG isolates carrying 40-60% premiums over hydrocarbon-processed alternatives. Price differentiation hinges on GMP certification status and third-party heavy metals panel inclusion. Pricing pressure stems from stranded CBD processing capacity in Colorado and Kentucky limiting capital redeployment toward minor cannabinoid retooling. Nutraceutical distributors exhibit highest price sensitivity, while Massachusetts and North Carolina biotech sponsors prioritize purity guarantees over unit cost.
Supply Chain Analysis
CBG feedstock supply rests on Kentucky and Colorado hemp cultivation clusters, with Oregon and Vermont emerging as secondary biomass sources through controlled-environment partnerships. Multi-stage chromatography equipment and preparative HPLC operator pools constitute critical input dependencies. Supply chain risk concentrates in USDA total THC compliance windows that disrupt harvest timing and isolate production schedules. Distribution runs through California biotech corridor laboratories co-located with ISO 17025 testing facilities, compressing batch-release timelines for clinical-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US minor cannabinoids market is consolidating around GMP-certified isolation capacity as FDA enforcement discretion uncertainty forces undercapitalized toll processors toward exit. Chromatography operator scarcity and IND-enabling study cost burdens accelerate this filtering mechanism.
For Market Incumbents: Lock in pharmaceutical-grade certification moats through captive analytical laboratory investments and IND-submission track records that emerging competitors cannot replicate quickly. Defend margin position by securing multi-year offtake agreements with Massachusetts and North Carolina biotech sponsors before enforcement discretion policies harden. Prioritize simulated moving bed chromatography deployment to collapse minimum efficient scale thresholds and preempt regional processor competition. For New Entrants and Emerging Players: Launch via cosmeceutical CBC topical formulations exploiting TRPV1 positioning without FDA drug-claim scrutiny, bypassing pharmaceutical compliance capital requirements entirely. Target Texas and Florida THCA regulatory arbitrage gaps where state-level limits below federal hemp definitions create compliant distribution channels underserved by established Colorado and California suppliers. Pursue white-label partnerships with stranded Kentucky CBD processors seeking minor cannabinoid retooling revenue streams. For Investors and Strategic Acquirers: The window for entry favors vertically integrated extractors with captive analytical laboratories and existing GMP infrastructure over brand-marketing plays dependent on toll processing. Long-term viability hinges on regulatory pathway optionality across pharmaceutical, nutraceutical, and cosmeceutical end uses. Watch FDA cannabinoid-containing drug product guidance development as the critical inflection signal determining inventory risk exposure for non-NDI-notified isolate holdings.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Acquisition | FDA pre-approval inspection readiness unlocks pharmaceutical offtake contracts with Massachusetts biotech sponsors. |
| Simulated Moving Bed Chromatography Deployment | In-house purification capacity collapses minimum efficient scale thresholds for CBG isolate production. |
| Multi-State Distribution Licensing | Interstate CBN shipment legality under 2018 Farm Bill provisions enables sleep-aid nutraceutical brand contracts. |
| THCA Regulatory Arbitrage Positioning | Texas and Florida state limit compliance creates acid-form cannabinoid market access underserved by incumbent suppliers. |
| CBC Cosmeceutical Formulation Development | TRPV1-targeting topical claims bypass FDA drug-approval pathways while capturing dermatological inflammation positioning. |
Research Approach
Independent corroboration across extraction facility operators, pharmaceutical formulators, and regulatory affairs specialists underwrites the qualitative findings presented in this study. Primary interviews with Colorado and Kentucky hemp processors, California biotech corridor laboratory directors, and FDA regulatory consultants combined with secondary validation from USDA hemp production rule filings, FDA enforcement discretion policy dockets, and ISO 17025 laboratory accreditation databases. Bottom-up triangulation across state-level hemp program registrations and top-down cross-checks against pharmaceutical IND submission patterns anchored volume estimates.
Rate-of-change decomposition across the projection horizon separates cannabinoid-specific demand drivers from general hemp sector trends. Segmentation modeling incorporated product type, extraction method, end user, and formulation type dimensions alongside regional regulatory cluster variations. CAGRs were derived from supply-side capacity buildout trajectories and demand-pull indicators from biotech sponsor pipeline disclosures. Forecast inputs included chromatography equipment installation rates and simulated moving bed technology diffusion patterns among mid-scale processors.
The model assumes a particular technology adoption path; alternative pathways for continuous processing chromatography would alter the outlook if diffusion accelerates beyond Oregon and Vermont pilot deployments. Forecasts reflect assumptions regarding FDA enforcement discretion stability and USDA total THC testing protocol consistency. A small set of triggers warrants ongoing watch: pending cannabinoid-containing drug product guidance release, state-level THCA threshold adjustments, and IND-enabling study investment patterns among Massachusetts and North Carolina sponsors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Electric Cannabis Grinders Market