
 Middle East and Africa CBD Patch Market | 2026-2036
Middle East and Africa CBD Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa CBD Patch Market Foresight
Local extraction capacity in Morocco and Lesotho is decoupling from finished-goods import dependence across the Middle East and Africa CBD Patch landscape. Mary's Medicinals leverages its transdermal specialization to anchor premium positioning in South African pharmacy channels. Pure Ratio Wellness competes through formulation breadth spanning isolate to full spectrum portfolios. Green Roads controls distribution scale across Gulf markets through regulatory-compliant import partnerships.
A CBD patch constitutes an adhesive transdermal delivery system containing cannabidiol in a reservoir or matrix configuration, typically releasing active compounds over 24-96 hours through controlled skin permeation for localized or systemic therapeutic effect. Transdermal patches dominate product type architecture due to superior bioavailability and dosing precision versus oral alternatives. Pain relief patches capture the largest end-use volume, while sleep patches represent the fastest-expanding application segment driven by wellness-oriented consumer migration from pharmaceutical sedatives. Controlled release delivery modes command margin premiums over topical formats by enabling sustained plasma concentration profiles.
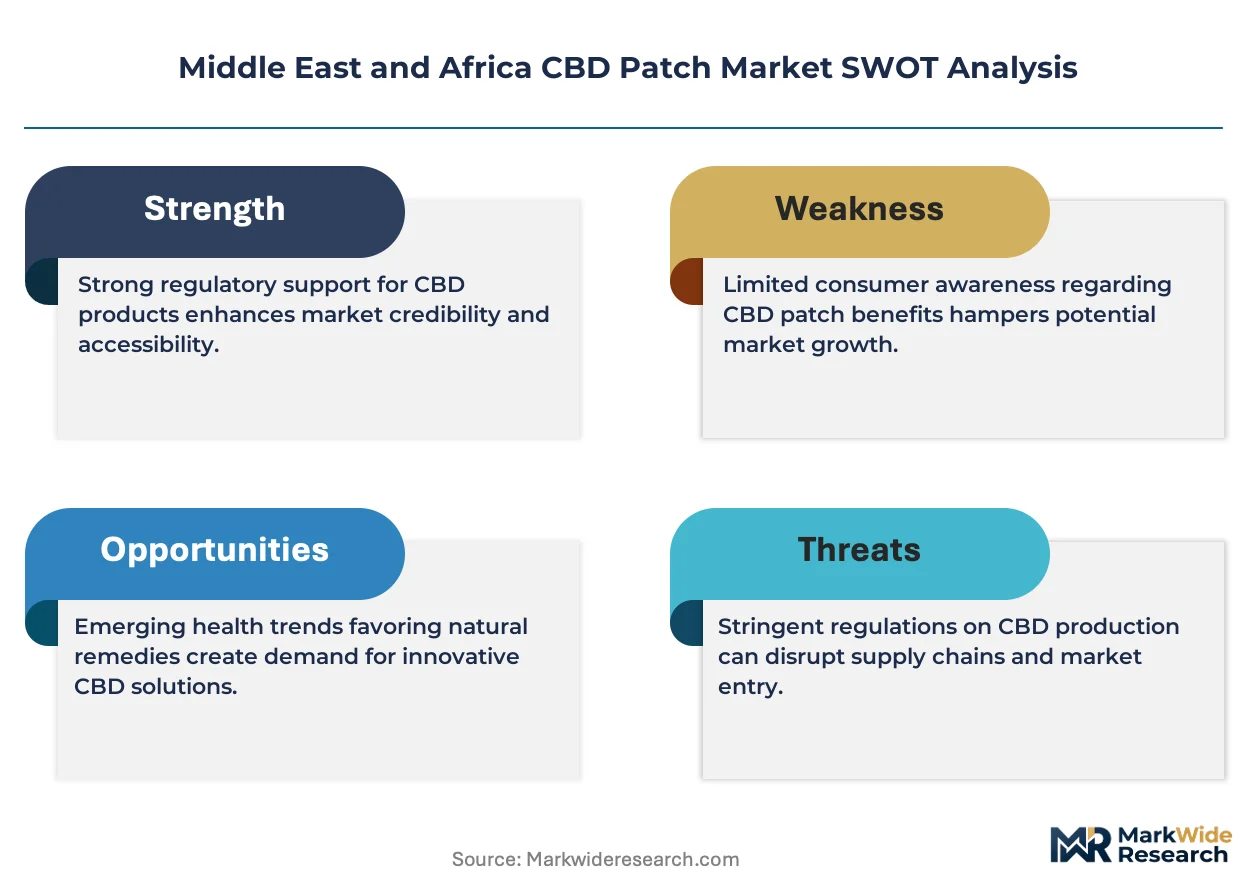
South Africa's SAHPRA and the UAE's Ministry of Health and Prevention operate divergent cannabinoid approval pathways that fragment product registration requirements across the region. The Gulf Cooperation Council's gradual standardization of CBD import thresholds under SFDA and MOHAP guidance is reshaping market access protocols for international suppliers. Stakeholders must monitor regulatory divergence between progressive African jurisdictions and conservative Gulf states when allocating product development and distribution investments.
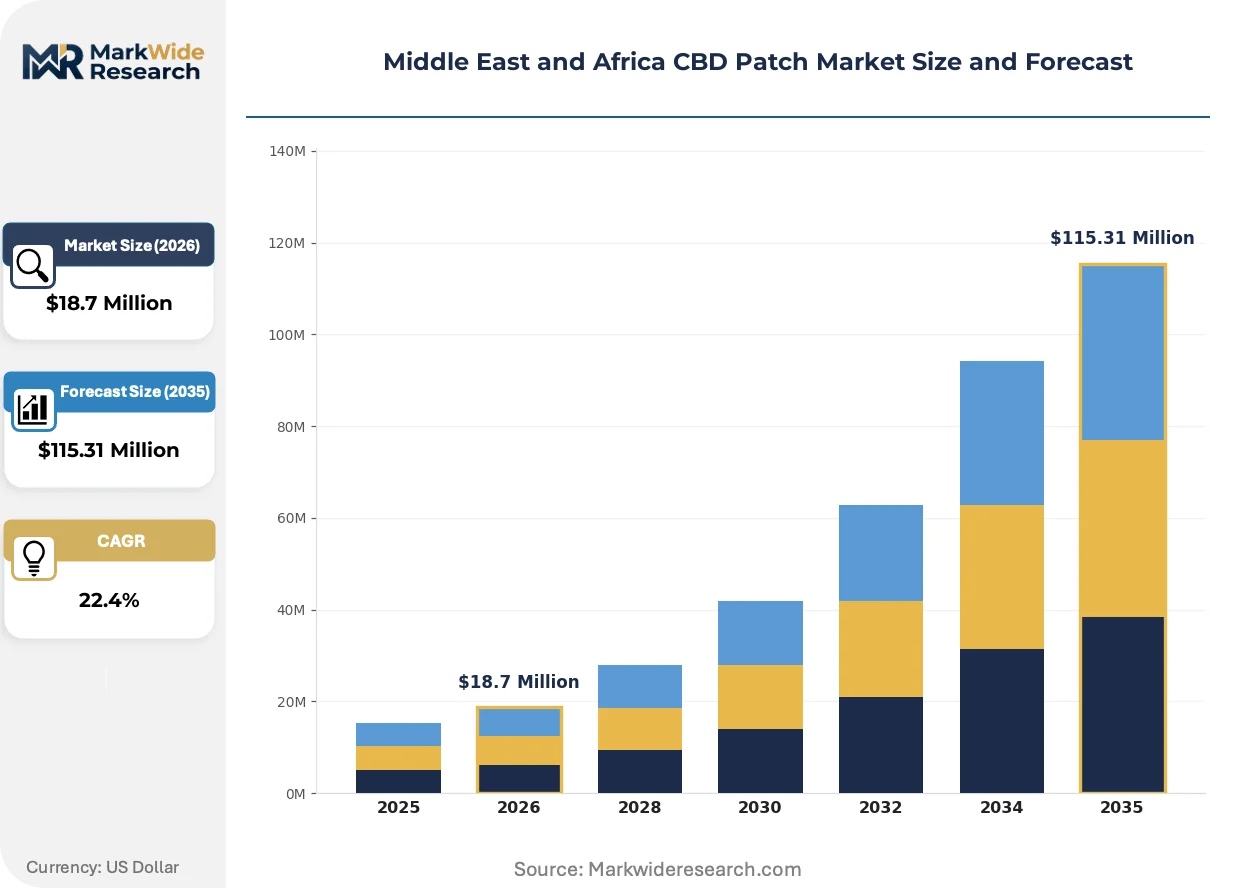
Market Dynamics
Transdermal reservoir technology maturation is compressing formulation development cycles while regulatory divergence between Gulf Cooperation Council states and progressive African jurisdictions fragments market access protocols for international suppliers.
Growth Catalysts
- SAHPRA Controlled Substances Scheduling:South Africa's rescheduling of CBD products enables pharmacy channel distribution and pain management clinic procurement at scale.
- Matrix polymer advances:Hydrophilic polyurethane backing materials improve skin adhesion duration from 24 to 96 hours in humid Gulf climates.
- Pain management clinics:South African specialty clinics drive institutional volume through physician-directed transdermal protocols replacing oral NSAID regimens.
Market Restraints
- Import duty volatility:UAE customs classification inconsistencies for hemp-derived inputs create landed cost unpredictability for finished patch formulations.
- SFDA threshold fragmentation:Saudi Arabia's 0.3% THC limit diverges from UAE MOHAP guidelines, forcing dual formulation SKUs for Gulf market access.
- Topical cream substitution:Lower-unit-cost balms and salves capture price-sensitive wellness consumers in Moroccan and Egyptian retail channels.
Strategic Opportunities
- Lesotho extraction hub:Local GMP-certified processing capacity eliminates EU import dependency for active pharmaceutical ingredient sourcing.
- Sleep application white space:Melatonin-CBD combination patches address wellness consumer migration from pharmaceutical sedatives in UAE and Qatar urban centers.
- Direct-to-clinic distribution:Bypassing wholesale pharmaceutical distributors captures margin in South African private healthcare networks.
Industry Challenges
- Stability testing timelines:SAHPRA requires 24-month accelerated stability data for novel transdermal formulations, extending product launch cycles.
- Pharmacokinetic specialist scarcity:Regional shortage of transdermal absorption modeling expertise forces reliance on European contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa CBD Patch Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $115.31 Million |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transdermal Patch, Pain Relief Patch, Sleep Patch, Anti-Anxiety Patch Delivery Mode: Topical, Dermatological, Direct Release, Controlled Release End User: Individuals, Clinics, Pharmacies, Healthcare Providers Formulation: Isolate, Broad Spectrum, Full Spectrum, Others |
| Companies Covered | Mary's Medicinals, Pure Ratio Wellness, Always Pure Organics, Pure Kana, Pacific Roots, CBD Living, Green Roads, HempFusion, Transdermal Therapeutics, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa CBD Patch Market Shifts & Advancements
Micro-needle array technology and controlled-release polymer science are converging to extend therapeutic windows while regulatory sandbox frameworks in select Gulf states accelerate product registration pathways.
Iontophoresis-assisted CBD delivery is automating plasma concentration management through electronically modulated skin permeation. Pain management clinics in Johannesburg and Cape Town pilot prescription-grade systems for chronic neuropathy patients. This automation is compressing the dosing frequency gap between transdermal patches and intravenous administration.
MOHAP's 2023 herbal product registration pathway establishes THC quantification standards for CBD patch import approvals into UAE pharmaceutical channels. Industrial consequence includes mandatory third-party laboratory certification for all Gulf-bound shipments. Sleep and wellness patch categories face the steepest compliance cost escalation as batch-testing requirements multiply.
Hospital procurement committees in South Africa and UAE are consolidating vendor lists around suppliers with dual GMP and ISO 13485 certification. This concentration is displacing single-facility manufacturers from institutional tenders. Pain management and post-surgical recovery verticals demonstrate the most pronounced supplier rationalization.
Middle East and Africa CBD Patch Market Segmentation
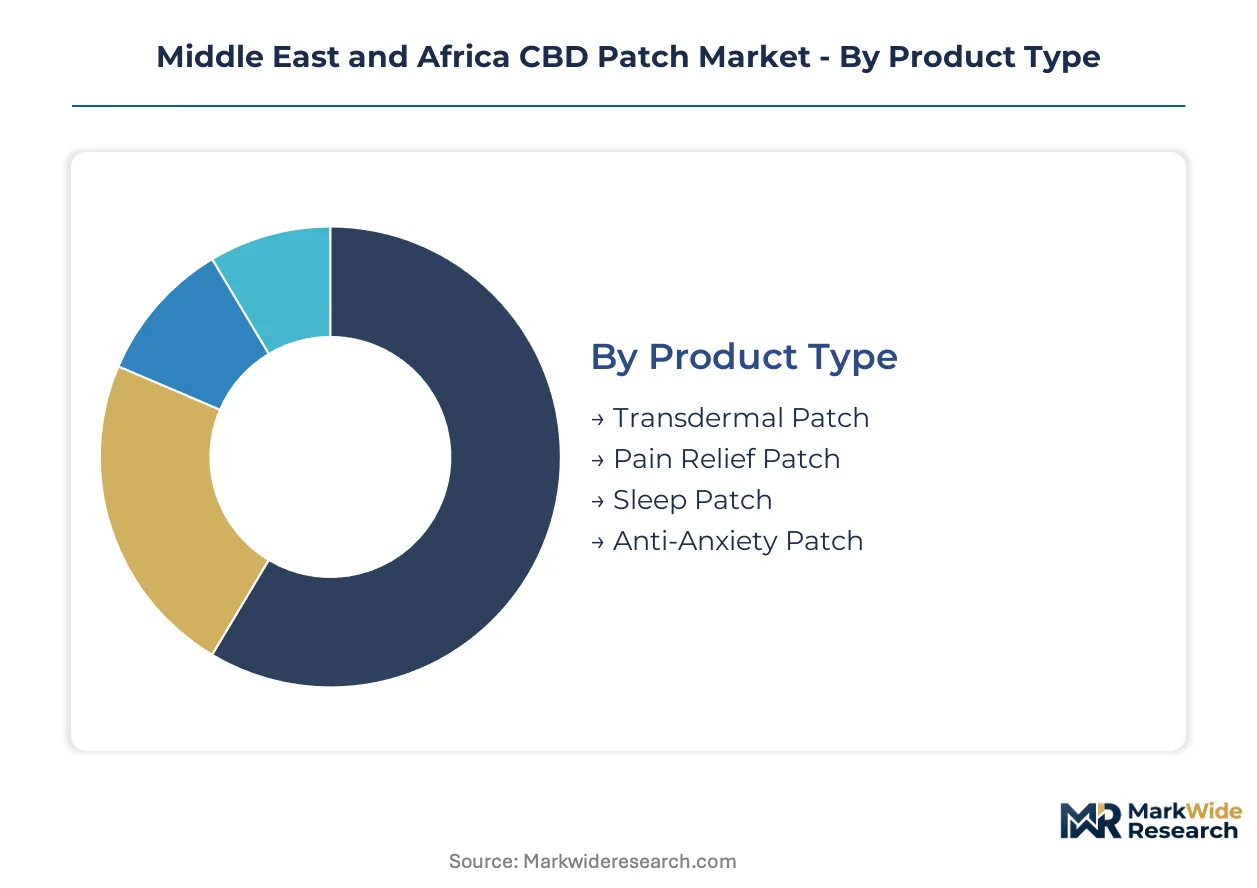
Segmentation in the Middle East and Africa CBD Patch market reveals divergent technology adoption patterns between institutional procurement channels and direct-to-consumer retail. Understanding which product configurations align with pharmacy distribution versus clinic-directed protocols enables suppliers to optimize formulation investments across South African, Gulf, and North African regulatory environments.
Product Type:
Transdermal patches function as standalone therapeutic systems with embedded reservoir or matrix architectures, while pain relief and sleep variants represent application-specific configurations optimized for distinct clinical endpoints.
- Transdermal Patch:Reservoir or matrix configurations release cannabidiol through controlled skin permeation over 24-96 hour windows. Johannesburg pain management clinics specify these for chronic neuropathy protocols requiring sustained plasma concentration profiles without peak-trough variability.
- Pain Relief Patch:Formulations combine CBD with counterirritants or anti-inflammatory adjuncts for musculoskeletal applications. UAE pharmacy chains stock these as first-line alternatives to oral NSAIDs for wellness consumers seeking non-pharmaceutical options.
- Sleep Patch:Melatonin-CBD combination matrices target sleep-onset insomnia. Qatar and Dubai urban centers show concentrated demand from expatriate professionals migrating off prescription sedatives.
- Anti-Anxiety Patch:Lower-dose formulations designed for daytime anxiolytic effect without sedation. South African psychiatric clinics pilot these for generalized anxiety disorder adjunct therapy.
Transdermal patches lead volumes today; sleep patches are gaining share fastest.
Delivery Mode:
Cost tiering separates immediate-release formats accessible through Moroccan retail channels from precision-dosing systems commanding institutional premiums in Gulf hospital procurement.
- Controlled Release:Polymer matrix or membrane-reservoir architectures maintain therapeutic plasma levels over extended durations. SAHPRA-registered South African clinics specify these for post-surgical pain protocols to reduce opioid dependency.
- Topical:Surface-acting formulations provide localized effect without systemic absorption. Egyptian and Moroccan mass-market retailers favor these for price-sensitive consumers unwilling to pay transdermal premiums.
- Dermatological:Skin-condition-specific delivery optimized for eczema or psoriasis co-treatment. UAE dermatology clinics represent the concentrated demand node.
- Direct Release:Immediate-permeation formats for acute symptom onset. Limited adoption outside experimental protocols.
Controlled release commands margin premiums; topical formats dominate unit volumes through North African retail.
End User:
Customer type segmentation tracks procurement authority concentration, with clinic and pharmacy channels subject to divergent regulatory oversight compared to individual direct purchases.
- Clinics:Pain management and specialty care facilities in South Africa and UAE drive prescription-grade volume through physician-directed protocols. SAHPRA scheduling enables pharmacy-level procurement at scale.
- Pharmacies:Retail dispensaries across Gulf Cooperation Council states operate under MOHAP and SFDA import licensing. Dual GMP-ISO 13485 certification increasingly gates vendor list inclusion.
- Healthcare Providers:Hospital procurement committees consolidate purchasing for post-surgical and chronic care wards. Vendor rationalization favors suppliers with regional distribution infrastructure.
- Individuals:Direct-to-consumer e-commerce and wellness retail. Lesotho and Moroccan extraction hub proximity reduces landed costs for isolate-based products.
Clinics anchor institutional revenue; individual channels are expanding most quickly through e-commerce platform penetration.
Formulation:
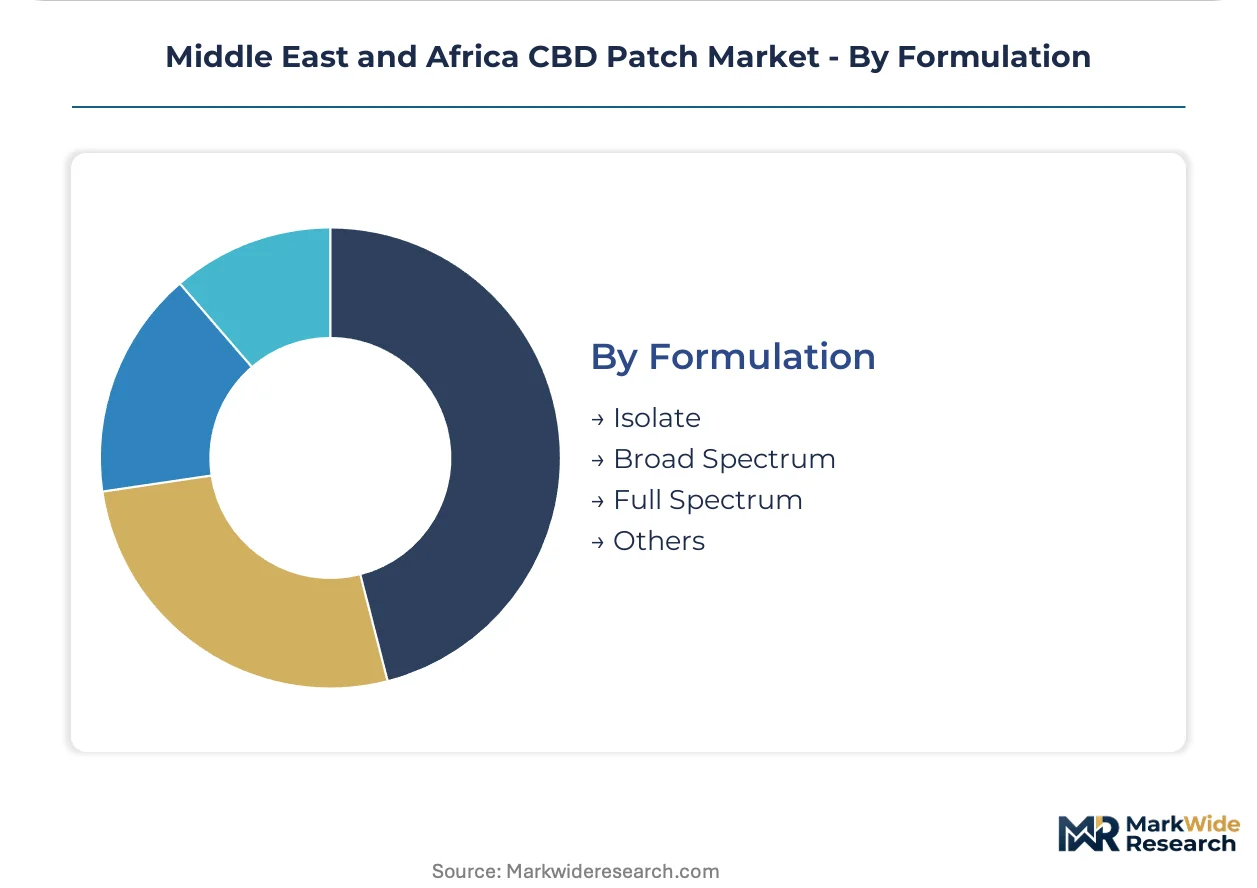
Maturity gradients separate established isolate processing from full spectrum formats facing THC threshold fragmentation across Saudi, UAE, and South African regulatory jurisdictions.
- Broad Spectrum:THC-free formulations retaining minor cannabinoids and terpenes. Gulf markets concentrate demand as MOHAP and SFDA guidelines diverge on permissible thresholds, making zero-THC positioning the safest compliance pathway.
- Isolate:Pure CBD formulations with standardized potency. Lesotho GMP-certified extraction capacity supplies regional manufacturers at cost advantage versus EU import dependence.
- Full Spectrum:Whole-plant extracts containing trace THC below 0.3%. South African SAHPRA framework accommodates these, but dual SKU requirements raise complexity for Gulf market access.
- Others:Nano-emulsion and liposomal delivery formats. Early-stage adoption limited to premium wellness positioning.
Broad spectrum formulations lead Gulf volumes; isolate production is climbing the fastest through Lesotho and Moroccan supply base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production cost differentials between Lesotho and Gulf markets are redirecting extraction capacity toward Southern Africa while finished-goods import dependence persists in the Middle East. This regulatory-arbitrage dynamic concentrates upstream investment in jurisdictions with streamlined hemp licensing while downstream value capture remains fragmented across divergent national approval pathways.
South Africa
Pain management clinics in Johannesburg and Cape Town drive institutional procurement through SAHPRA-registered pharmacy channels. SAHPRA's controlled substances rescheduling enables physician-directed transdermal protocols at scale. GMP-certified manufacturing clusters in Gauteng Province supply regional markets with broad-spectrum formulations.
United Arab Emirates
MOHAP's herbal product registration pathway concentrates demand among wellness-oriented expatriate professionals in Dubai and Abu Dhabi. The 2023 THC quantification standards mandate third-party laboratory certification for all pharmaceutical channel imports. Hospital procurement committees consolidate vendor lists around dual-certified suppliers.
Saudi Arabia
SFDA's 0.3% THC threshold diverges from neighboring Gulf states, forcing formulation adaptations for market access. Riyadh-based healthcare networks pilot prescription-grade patches for post-surgical recovery protocols. The Eastern Province industrial corridor hosts import distribution hubs serving the broader GCC.
Lesotho
GMP-certified extraction facilities supply active pharmaceutical ingredients to regional patch manufacturers at cost advantage versus EU sourcing. The country's streamlined hemp licensing framework attracts backward-integrating producers from South African markets. Maseru industrial zones anchor Southern Africa's cannabinoid processing capacity.
Morocco
Traditional cannabis cultivation regions near Chefchaouen and the Rif Mountains transition toward licensed hemp extraction for CBD isolate production. The country's national pharmaceutical regulator establishes quality standards for export-oriented processing facilities. Casablanca logistics clusters coordinate Maghreb distribution networks.
Middle East and Africa CBD Patch Market Competitive Landscape
South African producers anchor one tier; Gulf import specialists hold another. The market structures around three distinct competitive layers: domestic manufacturers with SAHPRA registration, regional distributors with MOHAP import licenses, and international suppliers with multi-jurisdiction compliance capabilities. Strategic archetypes include transdermal technology specialists, formulation breadth players, and regulatory compliance aggregators. Dominant competitive moves center on GMP certification acquisition and direct-to-clinic distribution bypass.
Within the transdermal specialization tier, Mary's Medicinals occupies a position exemplifying premium pharmacy channel positioning. Among formulation breadth competitors, Pure Ratio Wellness and Green Roads represent archetypes spanning isolate to full-spectrum portfolios. These three companies anchor the competitive landscape across divergent Gulf and African regulatory environments without vertical integration into upstream extraction.
| Leading Market Players |
|---|
| Mary's Medicinals |
| Pure Ratio Wellness |
| Always Pure Organics |
| Pure Kana |
| Pacific Roots |
| CBD Living |
| Green Roads |
| HempFusion |
| Transdermal Therapeutics |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient costs from Lesotho extraction facilities flow through formulation tiers, with GMP-certified isolate commanding pharmacy-channel premiums while unprocessed hemp imports feed price-sensitive North African retail segments.
Pricing Analysis
Distributor margins in Gulf Cooperation Council states absorb compliance burdens from dual GMP-ISO 13485 certification requirements, creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates SAHPRA-registered clinic supplies from wellness retail imports, with certification grade and volume scale as primary drivers. Cost compression in topical formats is intensifying because Moroccan extraction hub proximity enables isolate-based economy positioning. Egyptian retail channels exhibit highest price sensitivity; UAE hospital procurement committees show lowest.
Supply Chain Analysis
Polymer matrix feedstock supply rests on German and Japanese specialty chemical producers, with hydrophilic polyurethane backing materials as critical inputs. Raw material dependencies include cannabidiol isolate, adhesive polymers, and release liners. Single-source vulnerability concentrates in European contract research organizations providing pharmacokinetic modeling. Distribution runs through Johannesburg pharmaceutical distributors and Dubai import-logistics clusters serving Gulf markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa CBD Patch market compounds steadily as transdermal delivery technology matures across divergent regulatory jurisdictions, with pain management clinic adoption anchoring institutional revenue streams.
For Market Incumbents: Deepen direct-to-clinic distribution relationships in South African private healthcare networks to bypass wholesale margin erosion. Acquire GMP-certified extraction capacity in Lesotho to secure captive supply of active pharmaceutical ingredients and insulate against EU import cost volatility. SAHPRA registration timelines represent a structural moat against unlicensed competitors. For New Entrants and Emerging Players: E-commerce platform penetration offers the most accessible route for wellness-oriented sleep patch categories in Qatar and Dubai urban centers. Target melatonin-CBD combination formulations where pharmaceutical sedative migration creates white-space demand. Direct-to-consumer positioning bypasses MOHAP import licensing barriers for early revenue traction. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-certification requirements displace single-facility manufacturers from institutional tenders. Long-term viability favors transdermal technology specialists with backward integration into Southern African extraction capacity. Watch SAHPRA scheduling expansions beyond pain management as inflection signal for addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Acquisition | SAHPRA and MOHAP compliance gates institutional procurement channels across Johannesburg and Dubai. |
| Lesotho Extraction Hub Investment | Local API sourcing eliminates EU import dependency and compresses landed costs for regional manufacturers. |
| Direct-to-Clinic Distribution Buildout | Bypassing wholesale pharmaceutical distributors captures margin in South African private healthcare networks. |
| Sleep Application Formulation Launch | Melatonin-CBD combinations address wellness consumer migration from pharmaceutical sedatives in Gulf urban centers. |
| Dual GMP-ISO 13485 Certification | Hospital procurement committee vendor rationalization favors suppliers with comprehensive quality credentials. |
Research Methodology
Multiple input streams — regulatory affairs specialists at SAHPRA and MOHAP, pain management clinic procurement officers, and transdermal formulation scientists — were reconciled against customs trade records, pharmaceutical import licensing databases, and GMP facility registries. Secondary validation drew from SAHPRA controlled substances scheduling documents, SFDA herbal product guidelines, and Lesotho hemp licensing frameworks. Bottom-up patch volume estimates and top-down regional market sizing were cross-checked for convergence.
Data-stream reconciliation across product type, delivery mode, end user, and formulation segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory pathway acceleration. Modeled inputs included SAHPRA registration timelines, polymer matrix technology maturation rates, and clinic procurement committee vendor consolidation patterns.
The model assumes a particular technology adoption path; alternative pathways for iontophoresis-assisted delivery would alter the outlook if physician-directed protocols shift toward electronically modulated systems. Forecasts incorporate assumptions around regulatory divergence persistence and extraction capacity buildout timing. A small set of triggers — SAHPRA scheduling expansion, GCC regulatory harmonization, and micro-needle array commercialization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
Morocco Medical Cannabis Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Cannabis Cultivation Market