
 Chronic Obstructive Pulmonary Disease Therapeutics Market | 2026-2036
Chronic Obstructive Pulmonary Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Obstructive Pulmonary Disease Therapeutics Market Insights
The EU Green Deal's pharmaceutical sustainability criteria is pivoting procurement standards across European hospital networks. GlaxoSmithKline leverages its respiratory manufacturing scale to supply triple-therapy inhalers across multiple continents. AstraZeneca anchors its position through sustained R&D investment in biologics for eosinophilic COPD phenotypes. Boehringer Ingelheim differentiates through vertical control over inhaler device engineering and active pharmaceutical ingredient production.
Chronic Obstructive Pulmonary Disease therapeutics comprise pharmaceutical agents designed to dilate airways, reduce inflammation, and prevent acute exacerbations in patients with progressive airflow limitation, typically administered via metered-dose inhalers, dry powder devices, or nebulized formulations requiring specific particle size distributions for optimal lung deposition. Combination therapies now capture the dominant share of new prescriptions as clinicians prioritize dual and triple bronchodilator regimens over monotherapy, while nebulized delivery modes retain critical importance in acute exacerbation settings where patient coordination is compromised. The therapy area of disease modification represents the fastest-expanding margin pool as developers target interleukin pathways and mucus-clearance mechanisms beyond symptomatic relief.
The FDA maintains stringent bioequivalence standards for generic inhaled products through its Office of Generic Drugs, while the EMA's MDR framework imposes escalating clinical evidence requirements on connected inhaler devices. Health Canada and Australia's TGA coordinate on recognition pathways for respiratory drug approvals, reducing redundant trials across Anglo-Pacific markets. Stakeholders must monitor how payer formularies weigh the clinical value of biologic add-ons against the cost efficiency of optimized bronchodilator backbone therapy.
Market Dynamics
The FDA's accelerated approval pathways for respiratory biologics are compressing development timelines while simultaneously intensifying evidence requirements for post-market surveillance, fundamentally altering how manufacturers allocate R&D capital across the COPD pipeline.
Growth Catalysts
- Aging demographics in the United States:The patient pool requiring maintenance bronchodilator therapy expands as diagnostic rates improve through spirometry screening programs in primary care networks.
- EMA's MDR framework for connected devices:Digital inhaler platforms gain reimbursement traction as clinical evidence requirements validate adherence monitoring data for payers.
- Home care delivery expansion:Nebulized formulations and portable oxygen systems shift treatment administration from acute settings to residential environments, extending therapy reach.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for long-acting muscarinic antagonists clusters in specific Asian manufacturing zones, creating single-source vulnerabilities.
- Bioequivalence testing costs:The FDA's stringent pharmacokinetic study requirements for generic inhaled products impose capital barriers that limit competitor entry.
- Device engineering complexity:Particle size distribution specifications for optimal lung deposition demand specialized aerosol science expertise that constrains formulation development.
Strategic Opportunities
- Underpenetrated eosinophilic phenotypes:Biologic add-on therapies for targeted inflammatory subtypes remain below prescription potential in United States pulmonology practices.
- EU Green Deal pharmaceutical criteria:Sustainable manufacturing certifications create procurement advantages for inhaler producers with reduced propellant carbon footprints.
- Telemedicine integration:Remote patient monitoring platforms combine with electronic prescribing systems to enable direct-to-home therapy initiation.
Industry Challenges
- Aerosol formulation expertise scarcity:The specialized knowledge required for respiratory drug-device combination products creates recruitment bottlenecks in pharmaceutical development teams.
- Cross-border regulatory misalignment:Divergent bioequivalence standards between the FDA and Health Canada force redundant clinical programs for North American market access.
- Legacy inhaler disposal infrastructure:Pressurized metered-dose device recycling systems remain underdeveloped, complicating environmental compliance for high-volume prescribers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Obstructive Pulmonary Disease Therapeutics Market |
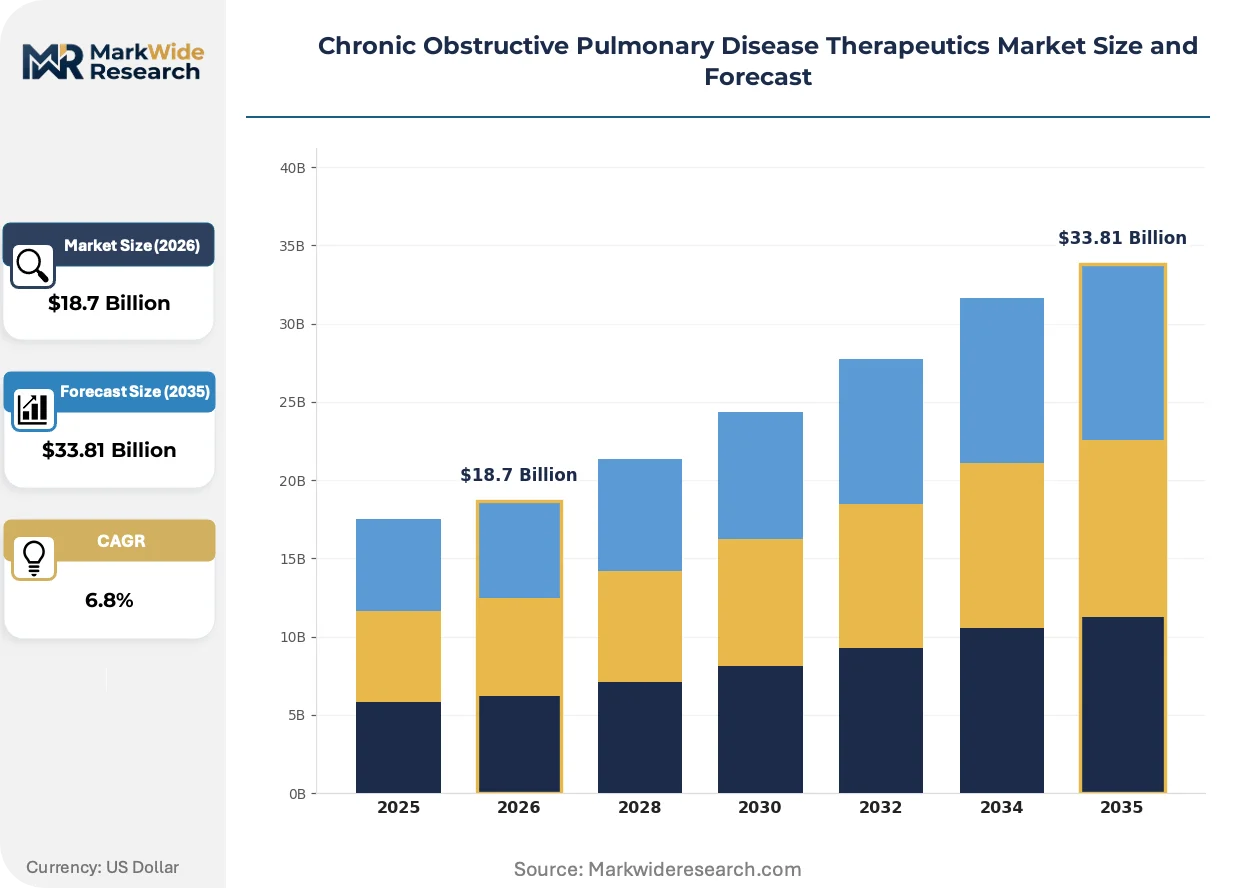
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Combination Therapies, Anticholinergics Therapy Area: Symptomatic Relief, Disease Modification, Maintenance Treatment, Acute Exacerbation Delivery Mode: Inhalation, Oral, Injectable, Nebulized End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Boehringer Ingelheim, Novartis, Teva Pharmaceutical Industries, Pfizer, Chiesi Farmaceutici, Merck & Co., Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Obstructive Pulmonary Disease Therapeutics Market Trends and Innovations
Digital therapeutics and connected inhaler platforms are absorbing capital allocation previously directed toward conventional formulation research, while regulatory frameworks on both sides of the Atlantic simultaneously tighten evidence standards for device-software combinations.
Dry powder inhaler technology is absorbing market share from pressurized metered-dose systems as propellant environmental concerns intensify under the EU F-Gas Regulation. Pulmonology practices in Germany and France are adopting these devices at accelerating rates for maintenance therapy initiation. The structural consequence is that manufacturing investment is absorbing capacity from chlorofluorocarbon-free transition programs toward advanced powder engineering and capsule filling automation.
The FDA's Office of Generic Drugs maintains stringent pharmacokinetic endpoint requirements for abbreviated new drug applications in the inhaled space. This policy compresses generic entry timelines for complex respiratory products while elevating development costs. Manufacturers targeting the United States market are responding by prioritizing 505(b)(2) hybrid pathways that leverage existing clinical data rather than pursuing full bioequivalence demonstrations.
Hospital procurement departments are consolidating vendor relationships for respiratory therapeutics around integrated device-drug-service bundles. The traditional separation between pharmaceutical purchasing and durable medical equipment sourcing is dissolving as value-based contracts bundle inhaler provision with adherence monitoring and patient education. This pattern is most visible in United States integrated delivery networks where pharmacy benefit managers negotiate directly with pharmaceutical manufacturers for population-level contracts.
Chronic Obstructive Pulmonary Disease Therapeutics Market Segmentation
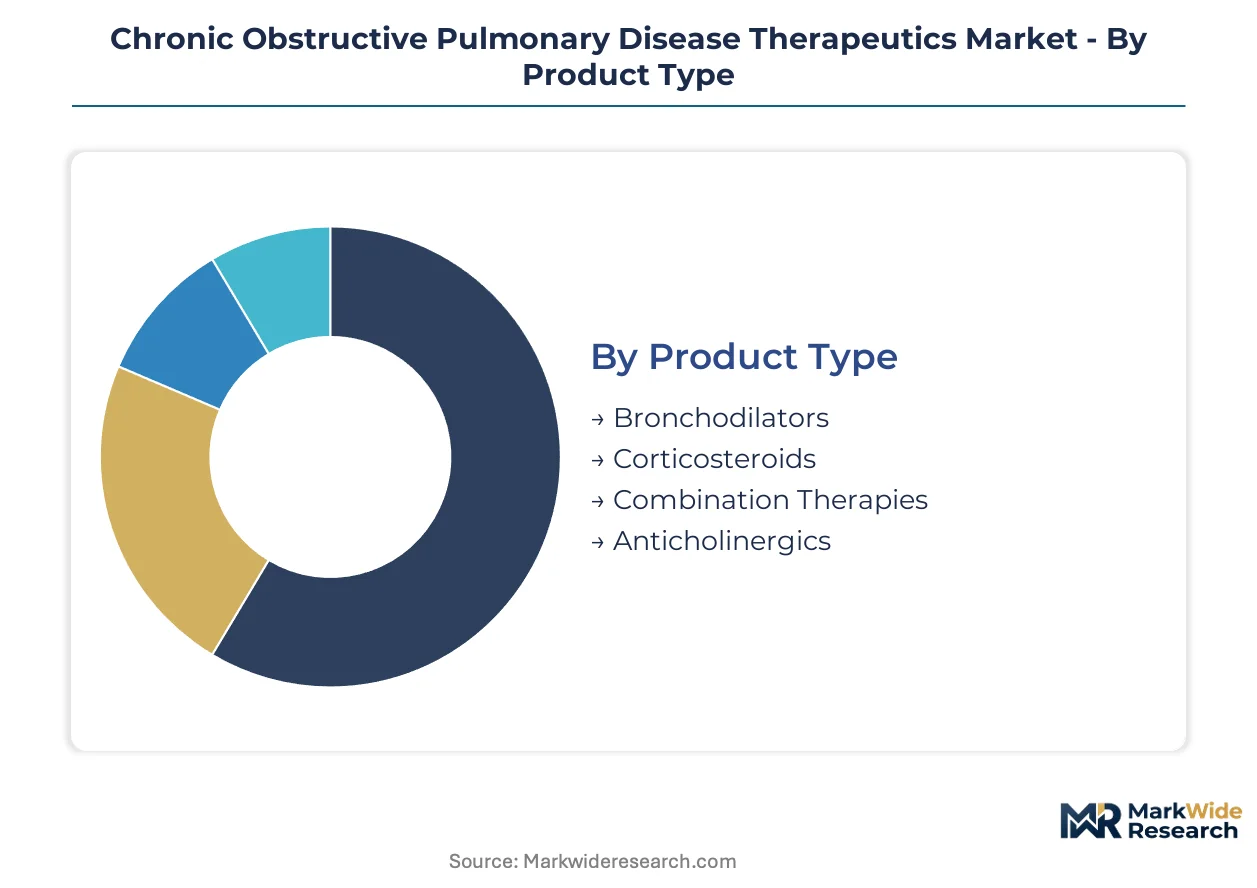
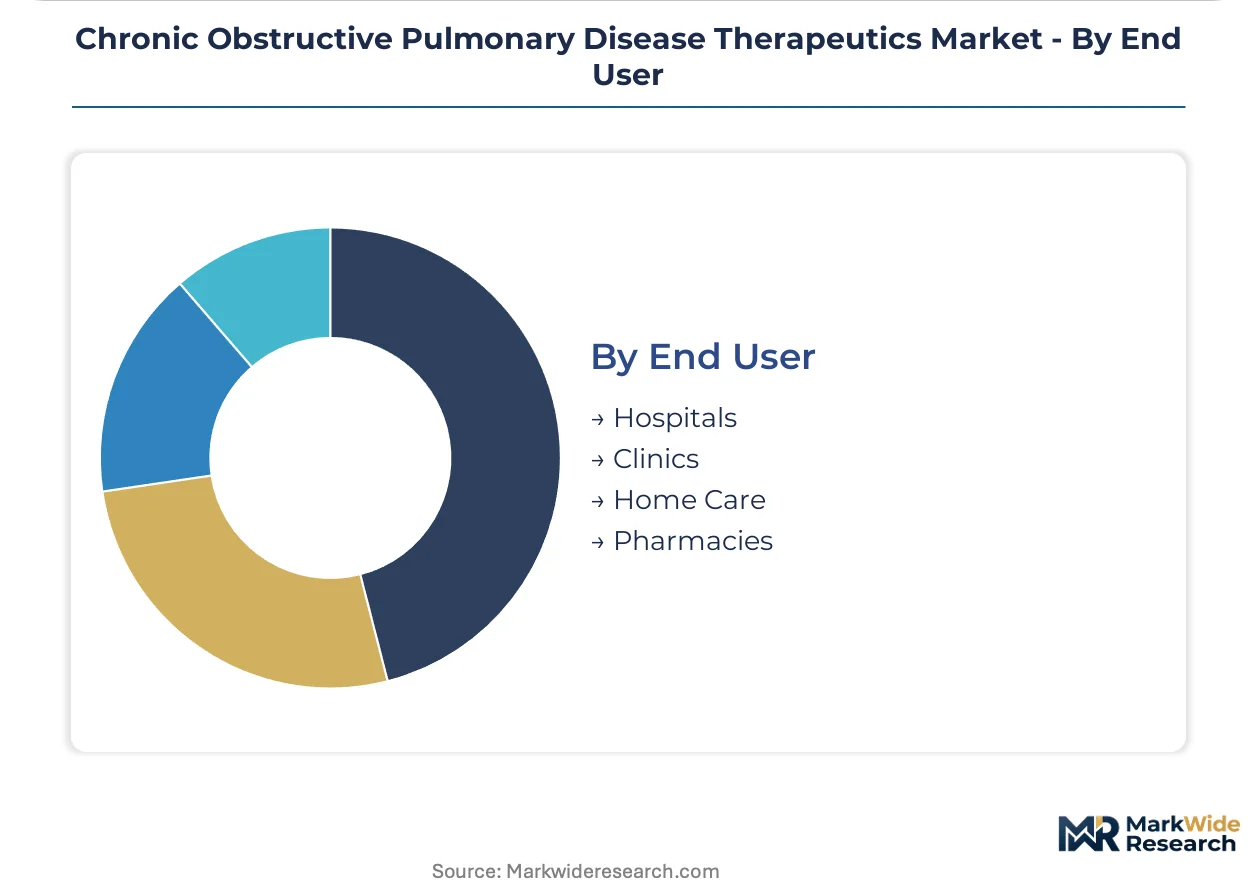
COPD therapeutics segmentation reveals how formulation science, delivery engineering, and care setting economics intersect to determine prescription patterns. Manufacturers allocate R&D capital across these axes based on reimbursement pathways and patient coordination capabilities.
Product Type:
Formulation chemistry and receptor pharmacology define competitive positioning in this axis.
- Bronchodilators:Long-acting beta-agonists and muscarinic antagonists relax airway smooth muscle through distinct G-protein coupled receptor pathways. Demand concentrates in United States Medicare Part D formularies where maintenance therapy prior authorization favors established bronchodilator backbones over experimental classes.
- Combination Therapies:Fixed-dose combinations of dual or triple bronchodilator mechanisms reduce pill burden while improving adherence metrics. United States pulmonology practices in Texas and Florida are expanding prescriptions for triple-therapy inhalers as GOLD guideline updates elevate combination therapy to first-line maintenance status.
- Corticosteroids:Inhaled anti-inflammatory agents suppress eosinophilic airway inflammation through glucocorticoid receptor activation.
- Anticholinergics:Muscarinic receptor antagonists block acetylcholine-mediated bronchoconstriction in peripheral airways.
Combination therapies lead on scale; bronchodilators lead on momentum.
Therapy Area:
Clinical objectives range from symptom control to structural disease intervention.
- Symptomatic Relief:Short-acting bronchodilators provide rapid rescue from dyspnea and wheezing through transient receptor activation. Demand clusters in emergency departments and urgent care networks where rapid onset overrides duration considerations.
- Disease Modification:Biologic agents targeting interleukin-5 and interleukin-4/13 pathways interrupt inflammatory cascades underlying airway remodeling. United States academic medical centers in Boston and San Francisco are establishing specialized clinics for eosinophilic phenotype identification to qualify patients for biologic add-on therapy.
- Maintenance Treatment:Long-acting formulations administered on scheduled regimens prevent symptom progression and exacerbation frequency.
- Acute Exacerbation:Systemic corticosteroids and nebulized bronchodilators manage sudden airflow deterioration requiring clinical intervention.
Symptomatic relief leads on scale; disease modification is expanding most quickly.
Delivery Mode:
Device engineering and patient coordination requirements segment this axis.
- Inhalation:Dry powder and metered-dose inhalers deposit aerosolized drug directly to conducting airways and alveolar regions. Germany and France are absorbing manufacturing capacity for next-generation dry powder devices as the EU F-Gas Regulation phases down hydrofluorocarbon propellants in pressurized systems.
- Nebulized:Compressed air or ultrasonic systems generate respirable droplets for patients lacking hand-breath coordination. Home care settings in the United States are absorbing nebulized delivery systems as telemedicine platforms enable remote monitoring of adherence and technique.
- Oral:Systemic administration through tablets or capsules bypasses pulmonary deposition variability.
- Injectable:Subcutaneous or intravenous biologic delivery enables precise dosing of large-molecule therapeutics.
Inhalation leads on scale; nebulized delivery is gaining share fastest.
End User:
Care setting economics and reimbursement structures determine procurement patterns.
- Home Care:Residential administration of maintenance therapies through portable nebulizers and oxygen concentrators. United States Medicare Advantage plans in Arizona and Florida are expanding remote patient monitoring reimbursement to capture adherence data from home-based inhaler use.
- Hospitals:Inpatient management of acute exacerbations requiring IV corticosteroids and continuous nebulization. United States integrated delivery networks are consolidating respiratory therapeutics procurement around device-drug bundles that include adherence monitoring services.
- Clinics:Outpatient pulmonology and primary care sites for diagnosis and maintenance therapy initiation.
- Pharmacies:Retail and specialty pharmacy channels for prescription fulfillment and patient counseling.
Hospitals lead on scale; home care shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulmonology specialists concentrate in United States academic medical centers, German university hospitals, and Japanese respiratory research institutes, anchoring prescription volume and clinical trial recruitment across major markets.
United States
Medicare Advantage expansion in Arizona and Florida drives home-based nebulizer demand through remote patient monitoring reimbursement. FDA accelerated approval pathways compress biologic development timelines while intensifying post-market surveillance obligations. Boston and San Francisco academic medical centers establish specialized eosinophilic phenotype clinics to qualify patients for interleukin-targeted therapies.
Germany
Pulmonology practices in Bavaria and North Rhine-Westphalia adopt dry powder inhalers at accelerating rates for maintenance therapy initiation. EU F-Gas Regulation phase-down of hydrofluorocarbon propellants redirects manufacturing investment toward advanced powder engineering. Frankfurt and Munich hospital networks consolidate procurement around integrated device-drug-service bundles with adherence monitoring.
Japan
Aging demographics in Kanto and Kansai regions expand the maintenance bronchodilator patient pool through improved spirometry screening in primary care. PMDA recognition pathways align with FDA standards to reduce redundant clinical trials for respiratory drug approvals. Tokyo and Osaka medical centers lead adoption of connected inhaler platforms with digital adherence tracking.
United Kingdom
NHS England integrated care systems in London and the Midlands bundle respiratory therapeutics with patient education services under value-based contracts. MHRA post-Brexit regulatory autonomy enables faster approval timelines for novel inhaler devices while maintaining EMA-equivalent safety standards. Manchester and Birmingham hospital networks pilot telemedicine-integrated home care programs for COPD exacerbation prevention.
India
CDSCO streamlined approval processes for respiratory generics attract multinational manufacturing investment to Gujarat and Maharashtra pharmaceutical zones. Government spirometry screening programs in urban primary care networks improve diagnostic penetration among high-risk populations. Hyderabad and Bangalore specialty hospitals expand interventional pulmonology capacity for biologic therapy administration.
Chronic Obstructive Pulmonary Disease Therapeutics Market Competitive Landscape
Capital-heavy producers with integrated manufacturing compete with asset-light developers licensing formulation technology to contract manufacturers. The market structure consolidates around three to five vertically integrated pharmaceutical groups controlling device engineering and active pharmaceutical ingredient supply. Strategic archetypes include full-stack respiratory specialists, biologic-focused innovators, and generic inhaler challengers. Competitive dynamics center on M&A for aerosol science capabilities and capacity expansion for dry powder inhaler production.
Among UK-based pharmaceutical groups, GlaxoSmithKline occupies a position exemplifying manufacturing scale advantages across triple-therapy inhaler supply. AstraZeneca represents the biologic-specialist archetype through sustained research investment in eosinophilic phenotype targeting. Boehringer Ingelheim anchors the integrated-device-engineering tier with captive control over inhaler mechanism design and active pharmaceutical ingredient production.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Boehringer Ingelheim |
| Novartis |
| Teva Pharmaceutical Industries |
| Pfizer |
| Chiesi Farmaceutici |
| Merck & Co. |
| Roche |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap inhaler device specialists in Germany and Italy anchor manufacturing clusters that combine captive propellant chemistry with precision aerosol engineering, creating pricing discipline through backward integration into active pharmaceutical ingredient production and limited spot-market exposure for long-acting muscarinic antagonist feedstocks.
Pricing Analysis
The bundled-vs-unbundled service split separates hospital procurement contracts that wrap device provision with adherence monitoring and patient education from retail pharmacy transactions for standalone inhaler units. Pricing stratifies across premium, standard, and economy tiers based on device connectivity certification and glucocorticoid potency grade. Cost compression in the economy tier intensifies as Indian and Chinese generic manufacturers secure abbreviated new drug application approvals for complex respiratory products. Hospital systems and integrated delivery networks exhibit the lowest price sensitivity due to value-based contract structures, while independent retail pharmacies face the highest margin pressure from reimbursement rate compression.
Supply Chain Analysis
Reverse-logistics flows for pressurized metered-dose inhalers remain underdeveloped across European and North American markets, complicating environmental compliance for high-volume prescribers and creating stranded asset risks for device inventories approaching propellant phase-out deadlines. Active pharmaceutical ingredient production for long-acting beta-agonists and muscarinic antagonists concentrates in India, China, and Switzerland, with formulation finishing distributed across Germany, the United Kingdom, and the United States. Hydrofluorocarbon propellant supply hinges on regulatory quota allocations under the EU F-Gas Regulation and EPA phasedown schedules. Single-source vulnerability characterizes the nebulizer compressor motor segment, where East Asian manufacturing clusters feed global demand. Distribution runs through three-tier structures: direct-to-hospital contracts for acute care settings, wholesale pharmaceutical distributors for retail pharmacy networks, and durable medical equipment suppliers for home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chronic Obstructive Pulmonary Disease Therapeutics Market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations requiring maintenance bronchodilator therapy across developed economies.
For Market Incumbents: Deploy connected inhaler platform integration as the primary defensive lever. Incumbents should deepen backward integration into dry powder device engineering to secure manufacturing capacity ahead of EU F-Gas Regulation propellant phase-downs, while simultaneously building adherence data partnerships with United States Medicare Advantage plans to lock in formulary positioning against biologic-focused challengers. For New Entrants and Emerging Players: The premium-to-economy price-point gap in nebulized delivery systems creates entry opportunity for mid-tier device manufacturers. New entrants should target underpenetrated eosinophilic phenotype identification services in United States community pulmonology practices, leveraging telemedicine-integrated home care programs as the go-to-market angle to bypass entrenched hospital procurement relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light developers licensing aerosol formulation technology to contract manufacturers, relative to vertically integrated respiratory specialists with captive device production. The five-to-ten-year viability framing favors acquisition targets with demonstrated bioequivalence pathway expertise for generic inhaled products. The signal to watch is FDA Office of Generic Drugs guidance shifts on pharmacokinetic endpoint requirements, which would recalibrate competitive moats across the abbreviated new drug application landscape.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval for respiratory biologics compresses development timelines while intensifying post-market surveillance obligations. |
| Manufacturing Scale-Up | Dry powder inhaler capacity expansion in Germany and France absorbs investment redirected from hydrofluorocarbon propellant systems. |
| Licensing Agreement | Technology partnerships for connected device platforms enable adherence data monetization with United States payer contracts. |
| Pipeline Diversification | Interleukin pathway targeting expands addressable patient pools beyond symptomatic relief into disease modification. |
| Reimbursement Strategy | Medicare Advantage remote patient monitoring coverage in Arizona and Florida extends therapy reach into residential settings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at pharmacy benefit managers, and hospital procurement managers with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare Part D formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Segment-weighting approaches distributed value across formulation chemistry, delivery device engineering, therapy area objectives, and care setting economics. The analytical framework modeled patient population stratification, administration route preferences, regional regulatory clusters, and reimbursement pathway differentiation across the projection horizon. CAGRs derived from epidemiological trend extrapolation, therapy penetration curves, and pricing trajectory assumptions for bronchodilator and biologic classes.
Caveats apply where FDA bioequivalence standard revisions, EMA MDR framework enforcement intensity, or API supply concentration disruptions could materially shift the outlook. Forecasts reflect assumptions about diagnostic rate improvement, generic entry timelines, and connected device adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Papillary Thyroid Cancer Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market