
 Cannabis Capsules Market | 2026-2036
Cannabis Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Capsules Market Outlook
Aftermarket formulation services is narrowing as licensed producers bring encapsulation in-house. Curaleaf leverages vertical integration across cultivation through finished dose manufacturing to capture margin pools previously held by contract developers. Green Thumb Industries anchors its position through controlled distribution networks in limited-license states. Tilray competes on pharmaceutical-grade certification pathways that differentiate medical from wellness positioning.
Cannabis capsules are oral dosage forms containing measured quantities of cannabinoids—typically tetrahydrocannabinol, cannabidiol, or both—encapsulated in gelatin or plant-based shells with standardized dissolution profiles for predictable bioavailability. These products serve medical patients requiring dose precision and recreational consumers seeking discrete, smoke-free administration methods. Full-spectrum formulations retain the complete cannabinoid and terpene matrix of the source cultivar, attracting consumers prioritizing the entourage effect over isolated compounds. Medical patients represent the fastest-expanding target audience as physicians in regulated jurisdictions issue cannabis recommendations for qualifying conditions. Dispensaries dominate distribution channel value capture where state regulations restrict pharmacy participation.
The FDA maintains Schedule I restrictions on cannabis while permitting Epidiolex and select investigational cannabinoid drugs through controlled clinical trial frameworks. State-level regulators in jurisdictions with medical or adult-use programs impose testing mandates for potency, contaminants, and label accuracy that determine market access eligibility. Health Canada and Germany's BfArM provide reference regulatory models for export-oriented producers seeking GMP certification. Stakeholders must monitor how rescheduling proceedings and international treaty reclassification reshape cross-border supply chain legality.
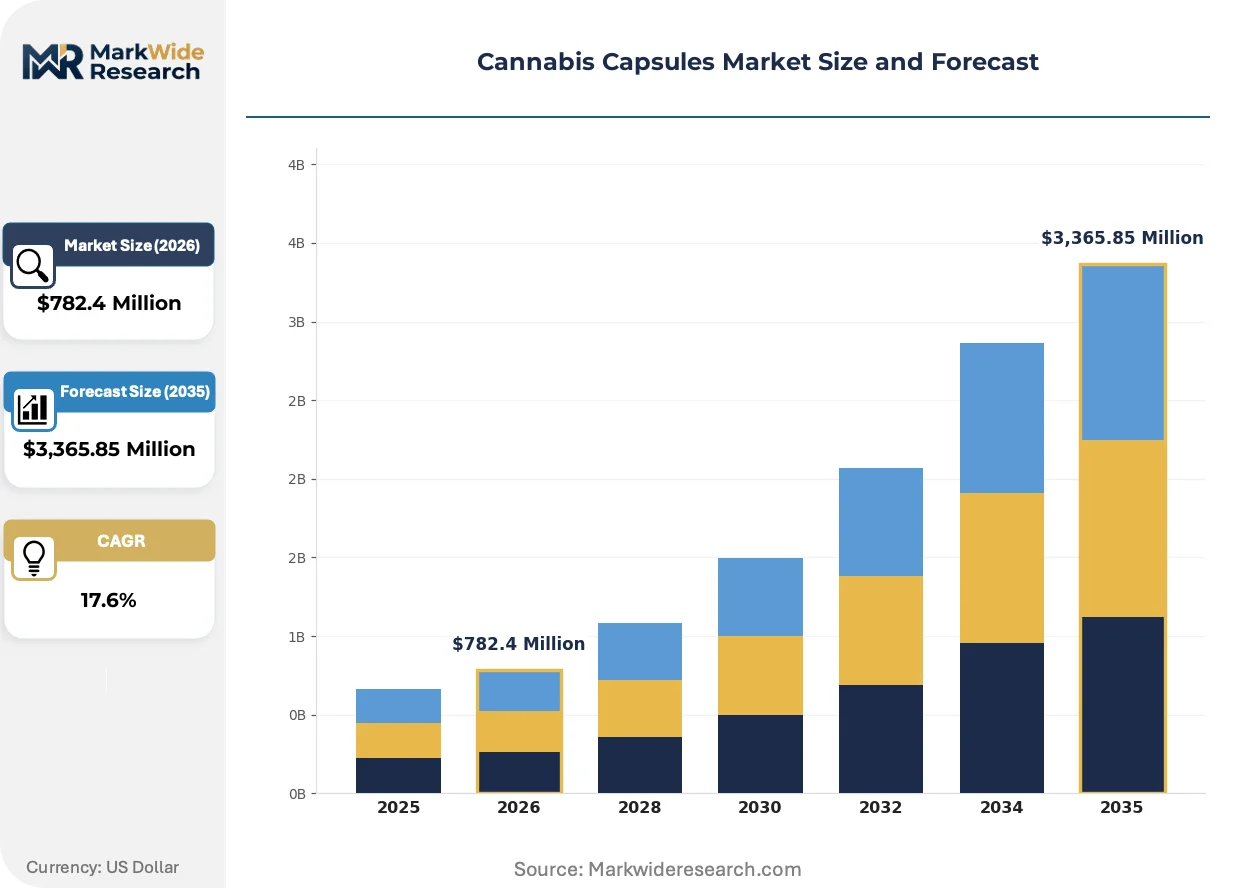
Market Dynamics
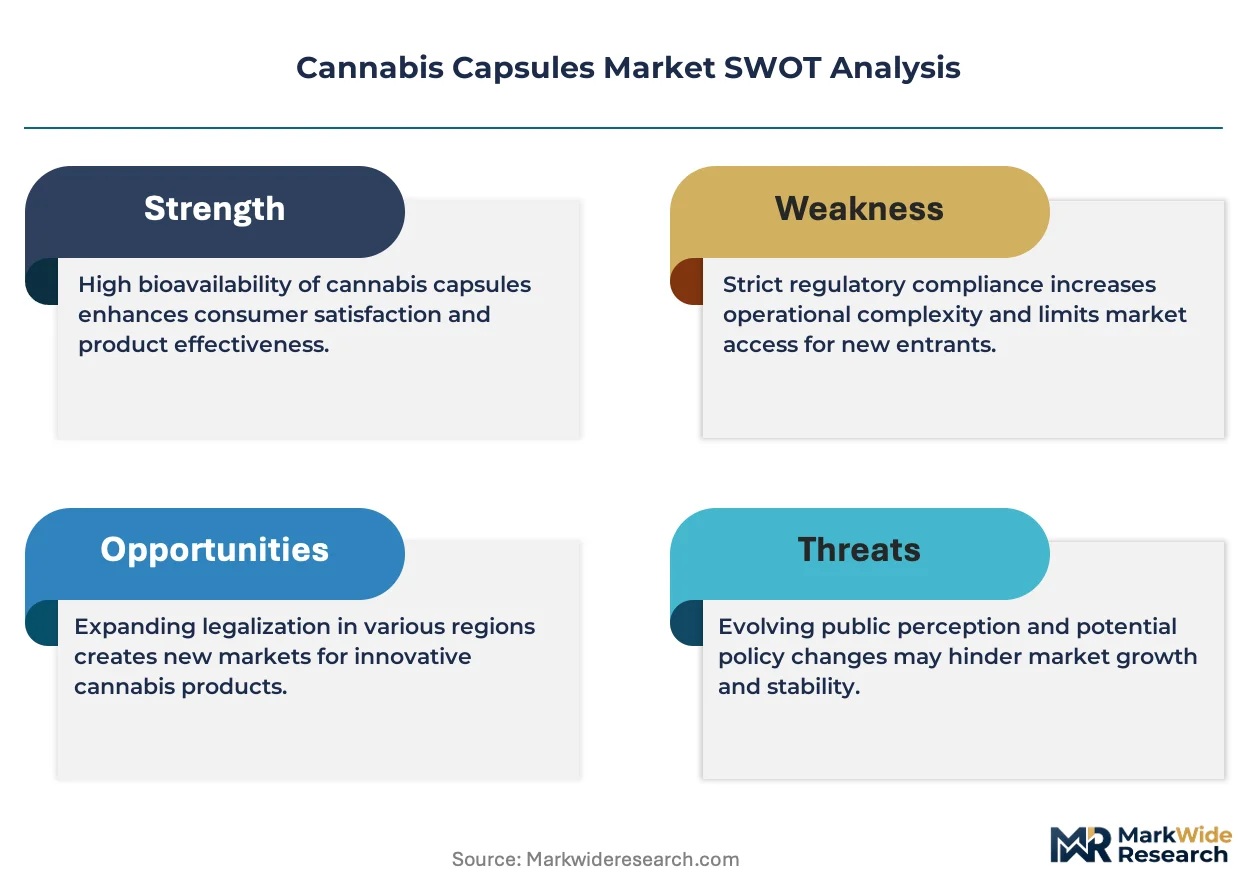
State-level medical program expansions across the United States are fragmenting distribution frameworks, forcing manufacturers to navigate incompatible testing standards and labeling requirements while competing for limited shelf space in vertically integrated dispensary networks.
Growth Catalysts
- Medical program enrollment:Physician cannabis recommendation frameworks in regulated US states are expanding qualifying condition lists, pulling new patient cohorts into measured-dose oral formats.
- Smoke-free administration preference:Pulmonology guidelines and workplace drug testing protocols are steering recreational consumers toward discrete capsule alternatives to inhaled products.
- Encapsulation automation:High-speed capsule filling lines with in-line weight verification are reducing per-unit labor costs for licensed producers scaling output.
Market Restraints
- Schedule I banking exclusion:US federal classification blocks standard financial services access, forcing cash-intensive operations and elevated security expenditures.
- Input biomass volatility:Outdoor cultivation exposure to climate stressors in California and Oregon creates cannabinoid potency variance that complicates standardized formulation.
- Interstate commerce prohibition:The 2018 Farm Act's hemp provisions do not extend to THC-containing products, trapping inventory within single-state supply webs.
Strategic Opportunities
- German pharmacy channel:BfArM's domestic cultivation licensing and pharmacy distribution mandate for medical cannabis creates a high-margin, compliance-driven entry point for certified producers.
- Minor cannabinoid isolation:CBN and CBG extraction refinement is opening condition-specific indications beyond THC/CBD dominance in sleep and inflammation applications.
- Plant-based shell conversion:Pullulan and HPMC capsule alternatives to gelatin are capturing vegan-identified consumer segments in California and Colorado adult-use markets.
Industry Challenges
- GMP certification timelines:EU-GMP and PIC/S facility audits for export eligibility require 18-36 month preparation cycles that delay revenue recognition.
- Analytical method standardization:Inconsistent HPLC potency reporting protocols across state laboratories create label claim disputes and product recall exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Capsules Market |
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $3,365.85 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Spectrum, Broad-Spectrum, Isolate, Capsules with Additives Therapy Area: Chronic Pain, Anxiety Relief, Sleep Disorders, Epilepsy Target Audience: Recreational Users, Medical Patients, Health-Conscious Consumers, Wellness Seekers Distribution Channel: Online Retail, Dispensaries, Health Stores, Pharmacies |
| Companies Covered | Curaleaf, Green Thumb Industries, Trulieve Cannabis, Tilray, Aurora Cannabis, Canopy Growth Corporation, Cronos Group, Verano Holdings, Ascend Wellness Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Capsules Market Strategic Shifts
Formulation science and regulatory science are converging to redefine competitive differentiation, with bioavailability enhancement and certification-grade manufacturing separating premium positioning from commodity extraction.
Nanoemulsion technology is hybridizing lipid-soluble cannabinoid delivery into water-compatible matrices, enabling faster onset times that rival inhaled products. Beverage and capsule manufacturers are licensing these lipid-dispersion patents to compress the traditional 45-90 minute edible onset window. Medical patients with acute symptom management needs are driving adoption, forcing legacy oil-in-capsule formats into price-competitive positioning.
The FDA's cannabidiol enforcement policy update is creating investigational new drug exclusivity pathways that block dietary supplement positioning for isolated CBD. Drug developers are prioritizing synthetic cannabinoid analogs over botanical extracts to secure orphan disease indications. Capsule manufacturers serving the wellness segment are pivoting toward full-spectrum hemp formulations below the 0.3% THC threshold to avoid pharmaceutical regulatory capture.
Physician education requirements are restructuring wholesale purchasing patterns in medical-only states. Dispensary buyers now prioritize SKU portfolios with clinical trial citations and pharmacist consultation support over unbranded bulk flower. Arizona and Florida markets demonstrate this most visibly, where medical cardholder growth correlates directly with pharmaceutical-detail-style promotional investment from licensed producers.
Cannabis Capsules Market Segmentation
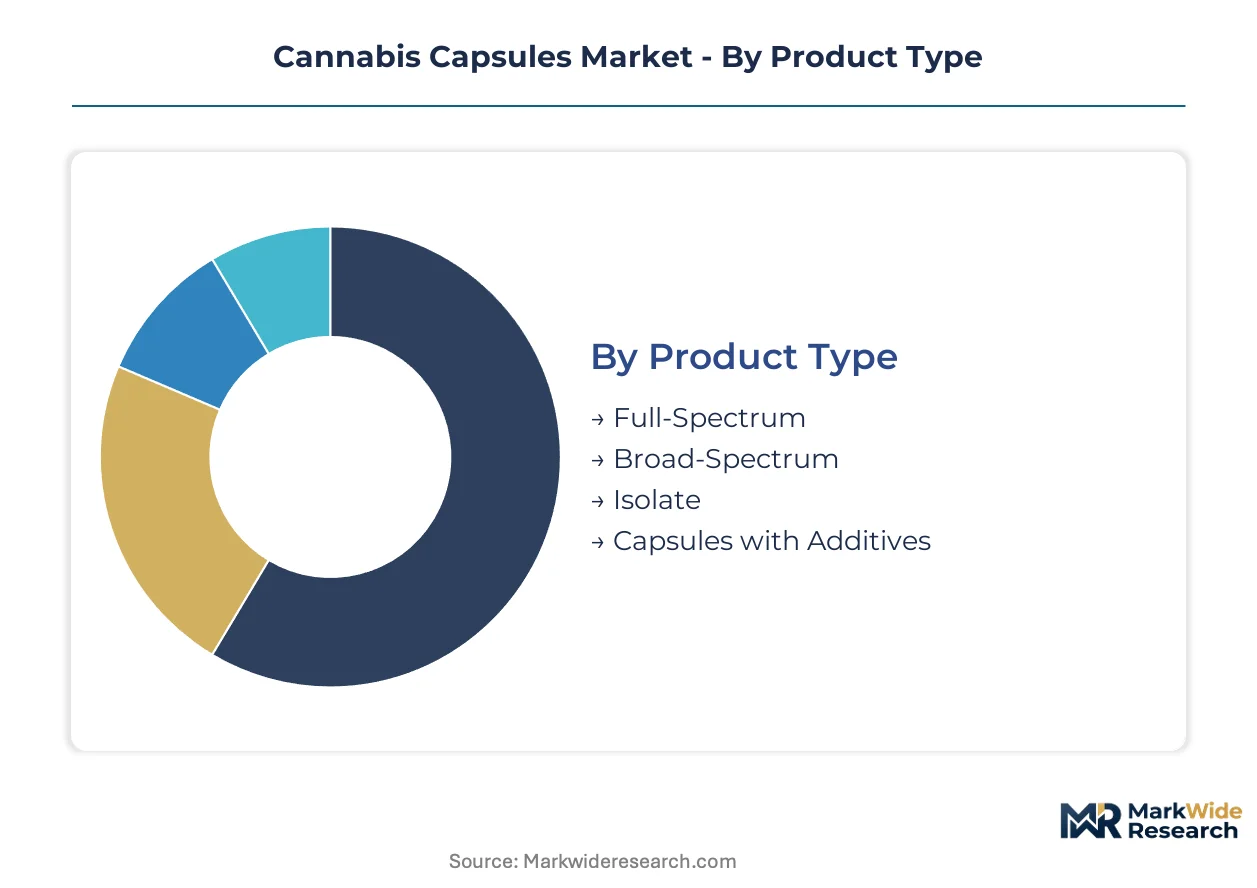
Cannabis capsules fragment across four intersecting dimensions that determine formulation priorities, regulatory pathways, and margin capture. Product chemistry and therapy indication together dictate whether manufacturers pursue pharmaceutical certification or wellness positioning.
Product Type:
Mature extraction technologies dominate the base, while emerging isolation methods are reshaping premium tier composition.
- Full-Spectrum:Retains the complete cannabinoid and terpene matrix from source cultivar, delivering the entourage effect through lipid-based encapsulation. Demand concentrates among medical patients in California and Colorado seeking whole-plant efficacy over isolated compounds.
- Broad-Spectrum:Preserves multiple cannabinoids with THC removed or reduced below detectable thresholds, enabling workplace-compliant consumption. Health-conscious consumers in adult-use states drive adoption where drug testing protocols restrict THC exposure.
- Isolate:Crystalline single-compound formulations, typically CBD or CBG, with standardized purity above 99%.
- Capsules with Additives:Enhanced formulations incorporating melatonin, turmeric, or omega fatty acids for condition-specific positioning.
Full-Spectrum handles the majority of throughput; Isolate is climbing the fastest on share as pharmaceutical developers prioritize single-molecule regulatory pathways.
Therapy Area:
Application focus shifts from symptom management toward chronic disease protocols as physician education expands.
- Chronic Pain:THC-dominant or balanced formulations addressing neuropathic and inflammatory pain mechanisms through CB1 receptor modulation. Medical program enrollment in Florida and Arizona pulls patients from opioid alternatives into measured-dose oral formats.
- Anxiety Relief:CBD-forward or low-THC ratios targeting GABAergic modulation without psychoactive impairment. Wellness seekers in adult-use markets favor these for daytime functional use.
- Sleep Disorders:CBN-enhanced or indica-terpene formulations targeting sleep latency reduction.
- Epilepsy:Pharmaceutical-grade CBD isolates following FDA-approved Epidiolex protocols for Dravet and Lennox-Gastaut syndromes.
Chronic Pain commands the largest patient volume; Sleep Disorders are gaining share fastest as CBN extraction scales.
Target Audience:
Customer type stratifies across regulatory access tiers, from restricted medical cardholders to open adult-use consumers.
- Medical Patients:Cardholders in state-regulated programs requiring physician recommendations and dose precision for qualifying conditions. Pulmonology guidelines steering away from inhaled products reinforce oral format adoption.
- Recreational Users:Adult-use consumers prioritizing discrete, smoke-free administration and predictable dosing over rapid onset.
- Health-Conscious Consumers:Demographic segment seeking clean-label, organic-certified, or vegan-shell alternatives.
- Wellness Seekers:Subclinical users targeting stress management, recovery, or general wellbeing without formal medical diagnosis.
Medical Patients anchor revenue stability; Wellness Seekers are expanding most quickly as hemp-derived formulations circumvent prescription requirements.
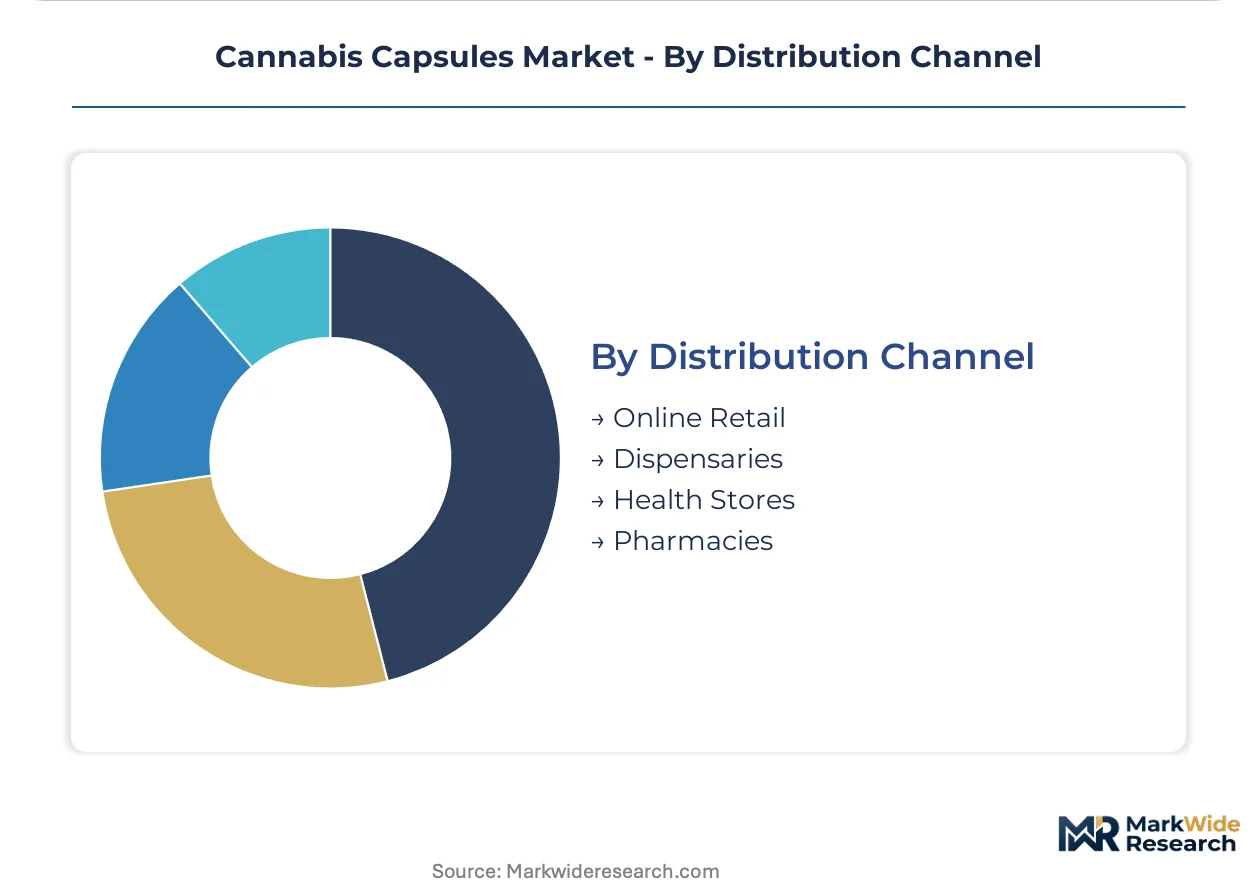
Distribution Channel:
Channel selection determines regulatory burden, margin retention, and customer relationship depth.
- Dispensaries:Vertically integrated retail in limited-license states where state regulations restrict pharmacy participation. Curaleaf and Green Thumb Industries control shelf access through captive distribution networks.
- Online Retail:Direct-to-consumer platforms for hemp-derived formulations below 0.3% THC, leveraging interstate commerce protections.
- Health Stores:Natural products retailers carrying hemp-CBD capsules with third-party certification requirements.
- Pharmacies:German BfArM-mandated distribution for medical cannabis, requiring EU-GMP certification and prescription fulfillment.
Dispensaries capture the dominant share of THC-containing product value; Pharmacies are expanding fastest as Germany and Australia broaden medical access frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmacy-dispensed medical cannabis framework diverges sharply from the United States' vertically integrated dispensary model, while Canada occupies a hybrid position with dual medical and adult-use channels operating under federal oversight.
United States
State-level medical program expansions in Florida and Arizona are pulling chronic pain patients into measured-dose oral formats. The FDA maintains Schedule I restrictions while permitting Epidiolex through controlled clinical trial frameworks. California's Central Valley cultivation clusters supply biomass to Los Angeles and San Francisco Bay Area encapsulation facilities.
Germany
BfArM's domestic cultivation licensing and pharmacy distribution mandate for medical cannabis creates high-margin access for certified producers. The country's national pharmaceutical regulator requires EU-GMP certification for import eligibility. Berlin and Cologne anchor the pharmacy dispensing network where prescription fulfillment concentrates.
Canada
Health Canada's dual-track licensing supports both medical and adult-use capsule production under federal oversight. The regulator imposes testing mandates for potency and contaminants that determine market access. Ontario's Greater Toronto Area hosts the majority of licensed producer processing capacity.
Australia
TGA's Special Access Scheme and Authorised Prescriber pathways are expanding medical patient access to standardized oral formulations. The national pharmaceutical regulator aligns with international GMP standards for import approval. Melbourne and Sydney clusters concentrate compounding pharmacy distribution.
United Kingdom
MHRA's cannabis-based medicinal products framework restricts capsules to Schedule II prescribing for specific epilepsy and chemotherapy indications. The national pharmaceutical regulator requires novel food authorization for CBD wellness positioning. London's Harley Street medical district anchors specialist prescription concentration.
Cannabis Capsules Market Competitive Environment
Capability concentration sits with pharmaceutical-certified producers; scale advantage sits with vertically integrated multi-state operators. The vendor base stratifies across three tiers: GMP-certified exporters serving regulated pharmacy channels, limited-license state operators controlling captive distribution, and wellness-positioned hemp extractors competing on price. Dominant competitive moves include backward integration into cultivation to secure biomass supply and technology licensing for bioavailability enhancement.
Among North American multi-state operators, Curaleaf, Green Thumb Industries, and Tilray exemplify contrasting strategic archetypes. Curaleaf represents the vertically integrated model spanning cultivation through finished dose manufacturing. Green Thumb Industries anchors position through controlled distribution networks in limited-license jurisdictions. Tilray occupies the pharmaceutical-grade certification pathway, differentiating medical from wellness positioning through regulatory compliance investment.
| Leading Market Players |
|---|
| Curaleaf |
| Green Thumb Industries |
| Trulieve Cannabis |
| Tilray |
| Aurora Cannabis |
| Canopy Growth Corporation |
| Cronos Group |
| Verano Holdings |
| Ascend Wellness Holdings |
| Others |
Value Chain & Pricing Dynamics
California's Central Valley cultivation clusters anchor North American biomass supply, with Los Angeles and San Francisco Bay Area encapsulation facilities translating input concentration into downstream pricing leverage for THC-dominant formulations. State-level testing mandates and limited-license dispensary networks amplify margin capture where vertical integration controls shelf access.
Pricing Analysis
Long-term offtake contracts between licensed cultivators and encapsulation facilities dominate California and Colorado, while spot market transactions persist in fragmented Oregon and Washington supply webs. Price differentiation centers on EU-GMP certification tier and organic cultivation designation, with pharmaceutical-grade isolates commanding substantial premiums over wellness-positioned hemp derivatives. Cost compression in broad-spectrum and isolate tiers is intensifying as Green Thumb Industries and Curaleaf scale in-house extraction capacity. Medical patients exhibit lowest price sensitivity due to insurance-adjacent reimbursement frameworks, whereas wellness seekers in adult-use states drive aggressive price shopping.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing relationships between Canadian licensed producers and German pharmacy distributors, reflecting BfArM-mandated distribution complexity. Geographic supply concentrates in Canada, the United States, and Colombia, with Ontario's Greater Toronto Area hosting dominant processing infrastructure. Raw material dependencies center on outdoor cannabis flower, ethanol extraction solvents, and gelatin or pullulan capsule shells. Single-source vulnerability runs through California climate exposure and Oregon outdoor crop volatility. Distribution runs through vertically integrated dispensary networks in limited-license US states, pharmacy channels in Germany and Australia, and direct-to-consumer platforms for hemp-derived formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cannabis capsules occupy an early-cycle expansion trajectory as state-level medical program enrollment accelerates physician-supervised adoption beyond legacy inhaled formats.
For Market Incumbents: Entrench market position through backward integration into climate-controlled indoor cultivation that stabilizes cannabinoid potency variance threatening standardized formulation. Secure EU-GMP certification ahead of German and Australian pharmacy channel expansion to preempt competitor eligibility. Counter emerging nanoemulsion bioavailability threats by licensing lipid-dispersion patents or acquiring encapsulation technology specialists. For New Entrants and Emerging Players: Pursue white-space opportunity in CBN and CBG condition-specific formulations for sleep and inflammation applications where THC/CBD dominance has not yet consolidated. Target Australia's TGA Special Access Scheme expansion as the most penetrable regulatory pathway among pharmacy-mandated jurisdictions. Establish go-to-market presence through compounding pharmacy partnerships rather than dispensary network competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-certified producers with EU-GMP infrastructure over commodity-scale wellness extractors facing hemp-CBD price erosion. Long-term viability hinges on regulatory compliance investment rather than cultivation scale alone. Acquisition targets should demonstrate BfArM or Health Canada import eligibility with established pharmacy distribution relationships. Monitor FDA rescheduling proceedings as the critical inflection signal for interstate commerce legalization and standard financial services access.| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Investment | BfArM mandates this standard for German pharmacy distribution access, creating exclusive high-margin channel eligibility. |
| Minor Cannabinoid Pipeline Expansion | CBN and CBG extraction refinement opens sleep and inflammation indications beyond saturated THC/CBD markets. |
| Nanoemulsion Technology Licensing | Faster onset profiles rival inhaled products, forcing legacy oil-in-capsule formats into price-competitive repositioning. |
| Plant-Based Shell Conversion | Pullulan and HPMC alternatives capture vegan-identified consumer segments in California and Colorado adult-use markets. |
| Physician Education Program Deployment | Arizona and Florida demonstrate direct correlation between pharmaceutical-detail-style investment and medical cardholder conversion rates. |
Study Parameters
A spread of perspectives from licensed producer operations executives, state regulatory affairs directors, dispensary procurement managers, and pharmaceutical formulation scientists converged on the working assumptions underpinning this analysis. Primary interview insights were cross-validated against secondary sources including FDA enforcement policy updates, Health Canada licensing disclosures, BfArM import authorization records, and state-level medical program enrollment statistics. Bottom-up patient population modeling and top-down manufacturer capacity assessments were triangulated to anchor volume projections.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product chemistry spectrum, therapy indication, regulatory access tier, and distribution channel type. CAGRs were derived from patient enrollment trajectory analysis and per-capita consumption intensity patterns. Key forecast inputs included state-level qualifying condition expansion schedules, EU-GMP audit completion timelines, and nanoemulsion patent licensing velocity.
Sensitivities concentrate around FDA rescheduling outcomes, German domestic cultivation licensing volume, and California climate stressor frequency. Forecasts reflect documented assumptions regarding state program expansion continuity and international treaty reclassification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
US Cannabinoids Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Missouri Legal Cannabis Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
US Minor Cannabinoids Market