
 North America Medical Cannabis Market | 2026-2036
North America Medical Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Cannabis Market Analytics
Asset-light licensing and royalty-based cultivation partnerships are reshaping capital deployment across the North America medical cannabis sector. Curaleaf Holdings leverages multi-state operating licenses to sustain geographic coverage without owning every cultivation facility. Green Thumb Industries anchors its position through controlled retail distribution in tightly regulated state markets. Tilray Brands competes via pharmaceutical-grade production standards that differentiate its supply for clinical channels.
North America medical cannabis comprises pharmacologically active cannabis-derived formulations—primarily THC and CBD extracts standardized to specific cannabinoid concentrations, terpene profiles, and contaminant thresholds—manufactured through supercritical CO2 extraction or ethanol processing for therapeutic administration under physician supervision. Oils and tinctures dominate current prescription volumes due to established dosing precision and pharmacy familiarity, while edibles represent the fastest-expanding category as manufacturers resolve bioavailability and onset-time limitations. Pain Management applications command the largest patient base and reimbursement traction, though Neurological Disorders—including epilepsy and multiple sclerosis—are attracting accelerated clinical trial investment and specialist prescribing.
The US Food and Drug Administration and Health Canada's Cannabis Act framework jointly govern product safety, clinical evidence requirements, and distribution channel access across the continent. State medical marijuana programs and provincial retail systems layer additional operational constraints that fragment compliance obligations and create localized market access barriers. Stakeholders must monitor evolving federal rescheduling deliberations and cross-border trade policy developments that could fundamentally restructure competitive positioning.
Market Dynamics
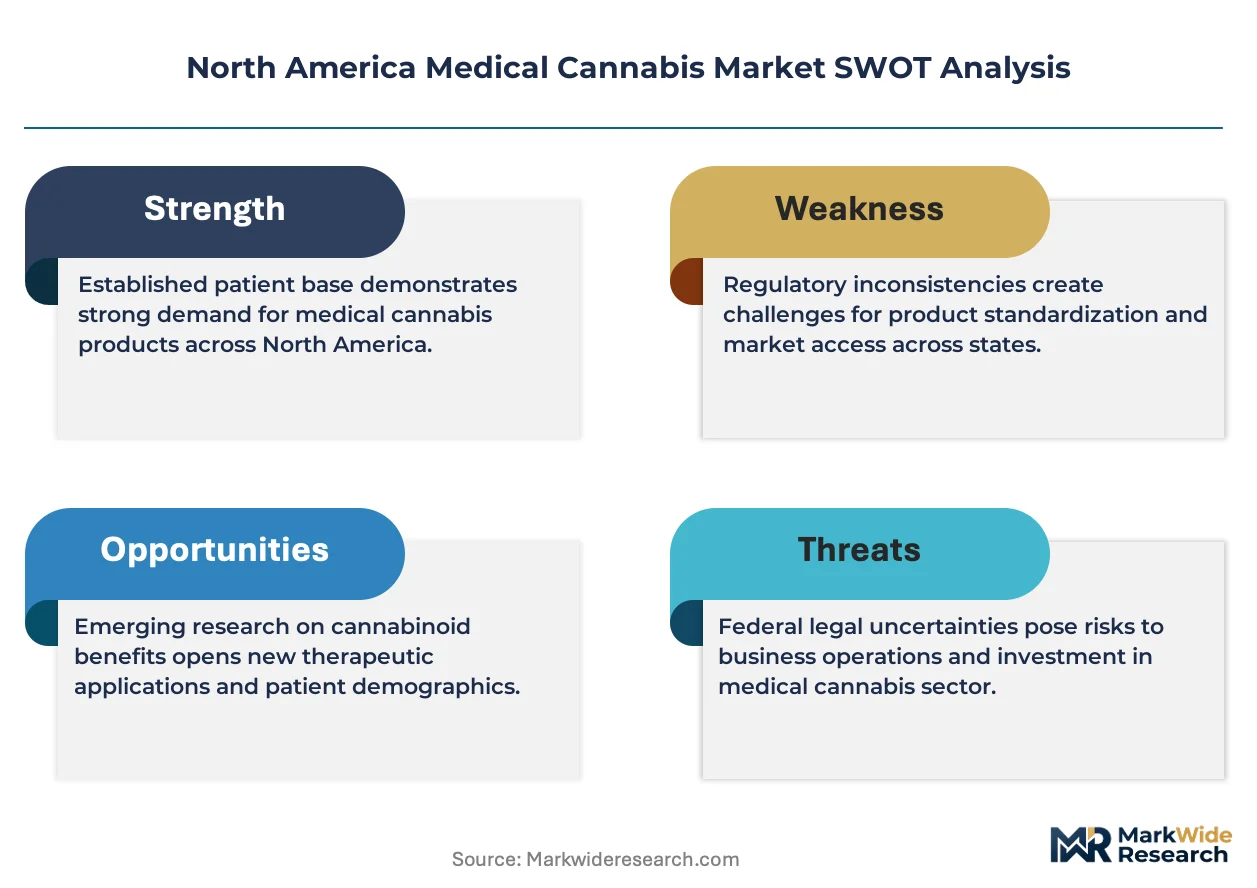
Federal rescheduling deliberations in the United States are compressing capital timelines and forcing multi-state operators to restructure debt covenants ahead of anticipated tax code changes. This regulatory overhang dominates strategic planning across cultivation and retail assets.
Growth Catalysts
- FDA Drug Approval Pathways:The FDA's expanded access program and IND-enabling studies for cannabinoid pharmaceuticals are channeling institutional investment toward GMP-certified production facilities in California and Colorado.
- Chronic Pain Clinics:Hospital-affiliated pain management centers across Florida and Texas are integrating cannabis-based therapy protocols into standard care pathways, expanding reimbursable indications.
- Supercritical CO2 Extraction:Equipment manufacturers report twelve-month order backlogs as processors upgrade from ethanol systems to achieve pharmaceutical-grade contaminant thresholds for clinical channels.
Market Restraints
- 280E Tax Code Burden:US Internal Revenue Code Section 280E prohibits standard business expense deductions for cannabis enterprises, inflating effective tax rates above seventy percent for plant-touching operations.
- Input Cost Volatility:Electricity rates in Ontario and California cultivation zones have spiked forty percent since 2022, compressing margins for indoor growing operations dependent on climate control.
- Interstate Commerce Barriers:The US Controlled Substances Act maintains state-quarantine requirements that prevent bulk wholesale transfers across state lines, forcing redundant inventory positioning.
Strategic Opportunities
- Veterans Health Administration:The VA's expanding research authorization for PTSD and chronic pain creates a federal procurement channel currently served by fewer than twelve qualified suppliers.
- Neurological Disorder Applications:Epilepsy and multiple sclerosis specialist practices represent underpenetrated prescribing segments with higher reimbursement rates than general pain management.
- Health Canada Export Permits:Licensed producers holding EU-GMP certification can access German and Australian medical cannabis markets through bilateral trade agreements with preferential tariff treatment.
Industry Challenges
- Analytical Chemistry Talent Scarcity:ISO 17025-accredited testing laboratories face recruitment gaps for cannabinoid quantification and terpene profiling specialists, extending batch release timelines.
- Seed-to-Sale Integration Complexity:State-mandated track-and-trace systems require real-time API connections between cultivation software, distribution platforms, and retail POS systems with incompatible data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Cannabis Market |
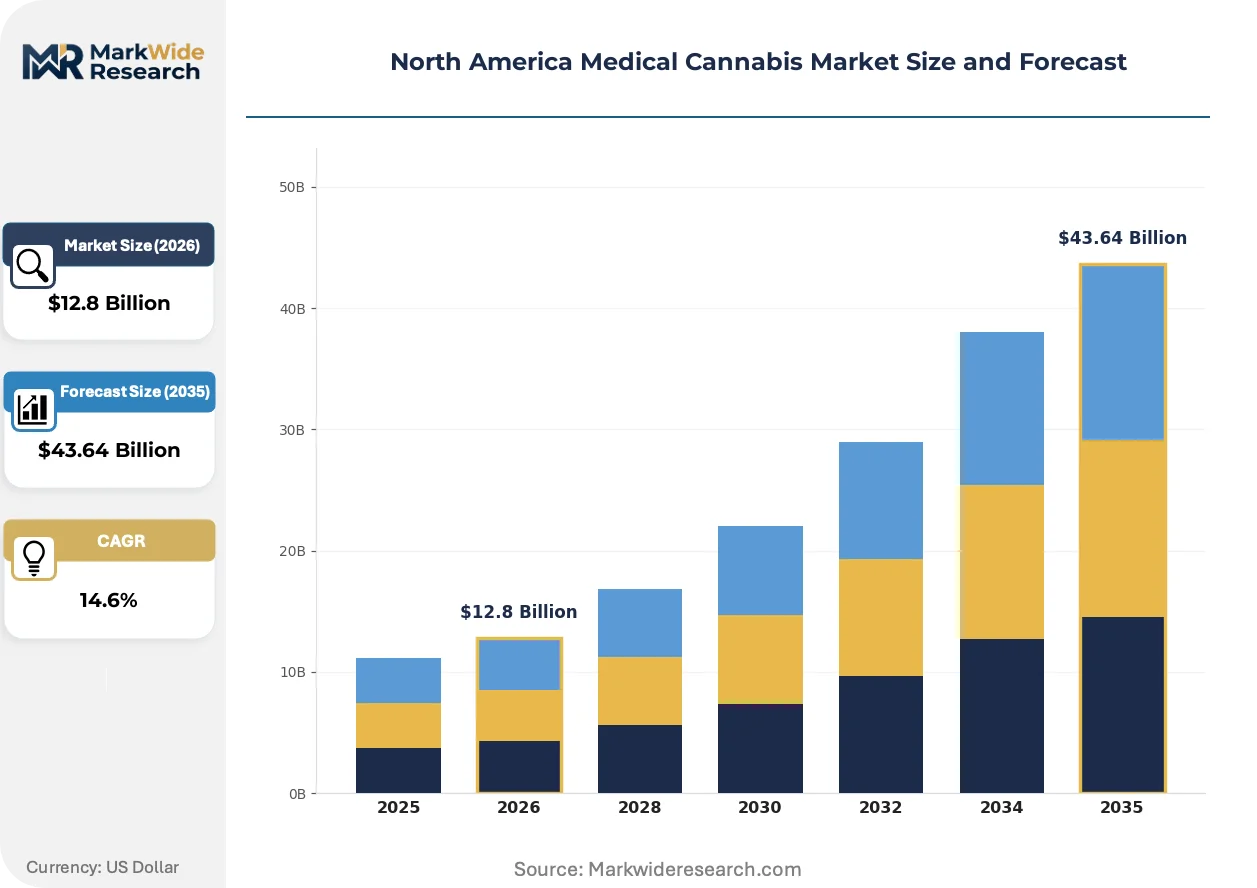
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Capsules, Edibles, Tinctures Application: Pain Management, Neurological Disorders, Cancer Care, Mental Health End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Inhalation, Oral, Sublingual, Topical |
| Companies Covered | Curaleaf Holdings, Trulieve Cannabis, Green Thumb Industries, Acreage Holdings, Tilray Brands, Aurora Cannabis, Canopy Growth Corporation, Cronos Group, Vireo Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Cannabis Market Evolving Landscape
Processing technology and distribution infrastructure are converging to enable pharmaceutical-grade supply chains that satisfy institutional procurement standards previously inaccessible to cannabis-derived products.
Nanotechnology encapsulation systems are migrating from nutraceutical applications into medical cannabis manufacturing. California-based processors now employ lipid nanoparticle formulations to achieve sub-fifteen-minute onset times previously unattainable with conventional oils. Pain management specialists at Cleveland Clinic and Mayo Clinic-affiliated practices are prescribing these formulations for breakthrough cancer pain, compressing the competitive window for conventional edible manufacturers.
Health Canada's Cannabis Act amendment streamlining research licenses is accelerating clinical trial enrollment. The regulatory change reduces approval timelines from eighteen months to ninety days for Phase II studies, enabling Toronto and Montreal academic medical centers to compete with US institutions for cannabinoid pharmaceutical development. Neurology and oncology departments are prioritizing these streamlined pathways for investigator-initiated trials.
Hospital procurement committees are consolidating vendor lists to single-source GMP-certified suppliers with DEA registration and FDA establishment identifiers. This certification-driven consolidation displaces multi-vendor purchasing arrangements common in early medical markets. The shift is most visible in Pennsylvania and New York health systems where integrated delivery networks manage formulary decisions for affiliated outpatient clinics.
North America Medical Cannabis Market Segmentation
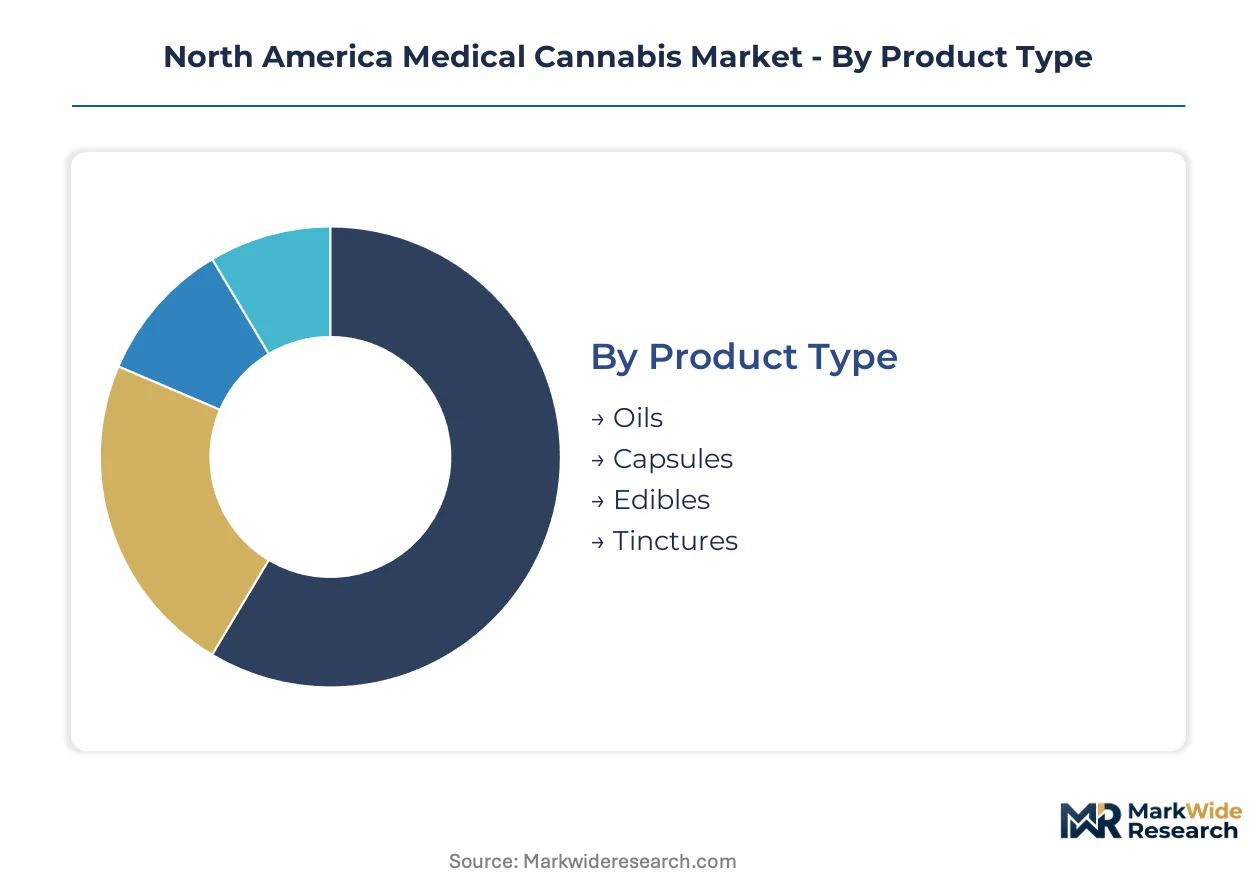
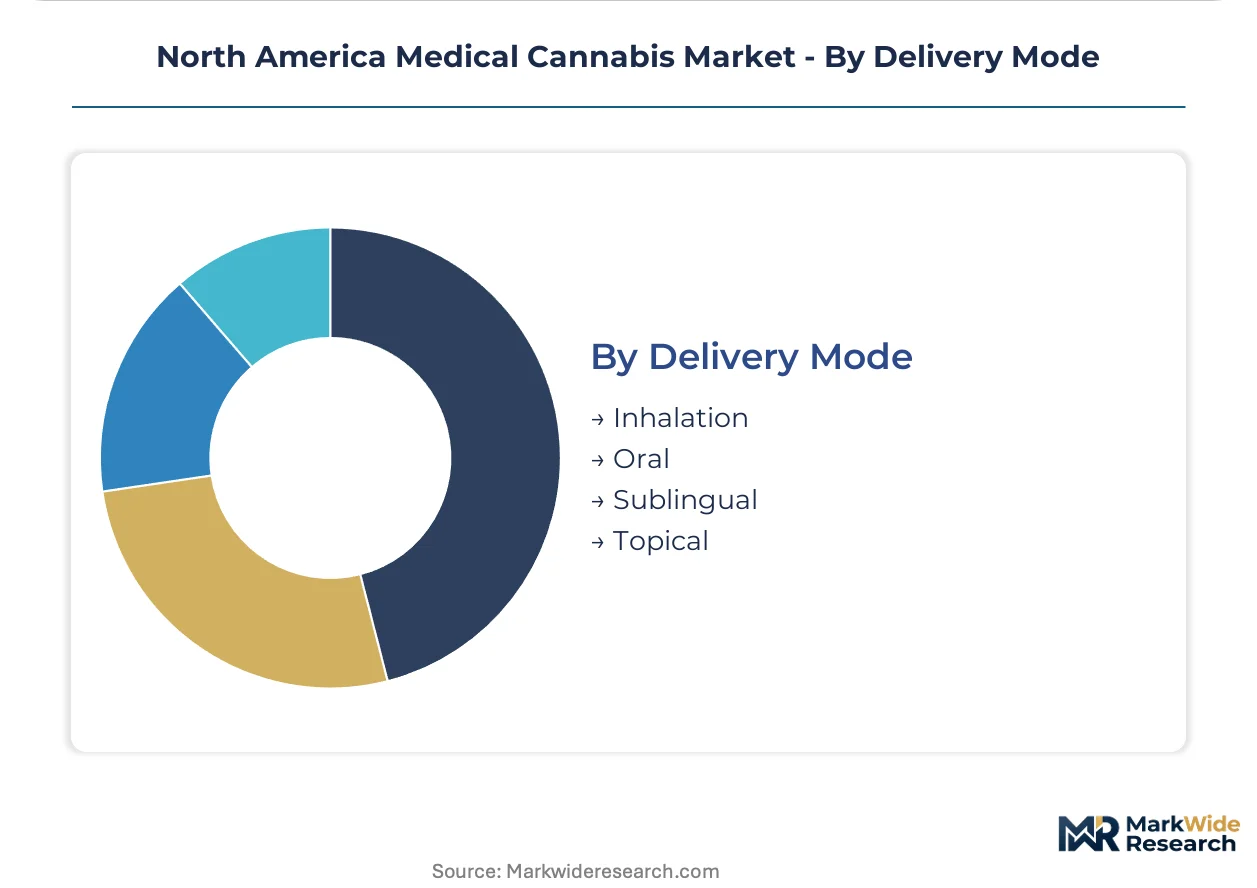
Medical cannabis segmentation reveals distinct procurement patterns across product formats, therapeutic applications, and institutional channels. Each dimension carries unique regulatory requirements, reimbursement pathways, and manufacturing standards that determine commercial viability.
Product Type:
The use-case spectrum spans acute symptom relief through chronic disease management, with formulation stability and dosing precision driving physician preference.
- Oils:Standardized cannabinoid concentrations in lipid-based carriers enable titratable dosing protocols. Hospital formularies in California and Florida prioritize these formulations for inpatient pain management due to established pharmacokinetic profiles and pharmacy familiarity.
- Edibles:Lipid nanoparticle encapsulation systems now achieve sub-fifteen-minute onset times previously unattainable with conventional matrices. Cleveland Clinic and Mayo Clinic-affiliated practices prescribe these for breakthrough cancer pain, compressing the competitive window for conventional manufacturers.
- Capsules:Gelatin and hypromellose shells deliver pre-measured doses with extended shelf stability. Retail pharmacies in Ontario and Colorado stock these as first-line options for geriatric patients.
- Tinctures:Alcohol or glycerin-based extracts with rapid buccal absorption. Compounding pharmacies in Texas and Pennsylvania customize these for pediatric epilepsy protocols.
Established volume favors oils; emerging adoption favors edibles.
Application:
Cost tier differentiation separates reimbursed hospital protocols from out-of-pocket wellness purchases, with clinical evidence requirements determining channel access.
- Pain Management:Chronic pain clinics across the United States and Canada have integrated cannabis-based therapy into standard care pathways. Hospital-affiliated centers in Florida and Texas command the largest patient base and strongest reimbursement traction.
- Neurological Disorders:Epilepsy and multiple sclerosis specialist practices represent underpenetrated segments with higher reimbursement rates. Toronto and Montreal academic medical centers are accelerating Phase II enrollment through Health Canada's streamlined research licenses.
- Cancer Care:Oncology departments prescribe cannabinoids for chemotherapy-induced nausea and appetite stimulation. Integrated delivery networks in Pennsylvania and New York consolidate vendor lists to GMP-certified suppliers.
- Mental Health:PTSD and anxiety protocols are expanding through Veterans Health Administration research authorization. Fewer than twelve qualified suppliers currently serve this federal procurement channel.
Pain management anchors current revenue; neurological applications are climbing the fastest.
End User:
Customer type determines compliance burden, with institutional procurement demanding GMP certification and DEA registration that excludes smaller cultivators.
- Hospitals:Formulary committees require FDA establishment identifiers and ISO 17025-accredited testing. These procurement standards displace multi-vendor arrangements common in early medical markets.
- Clinics:Pain management and neurology practices write the majority of new prescriptions. Florida and Texas lead in physician certification program enrollment.
- Homecare:Direct-to-patient delivery models dominate in California and Canada's Ontario province where dispensary density supports same-day fulfillment.
- Pharmacies:Community and specialty pharmacies handle reimbursed prescriptions with real-time insurance verification. State-mandated seed-to-sale tracking integrates with retail POS systems.
Institutional volume concentrates in hospitals; homecare is gaining share fastest.
Delivery Mode:
Margin structure varies with manufacturing complexity, from commodity extraction to precision encapsulation systems commanding premium pricing.
- Oral:Capsules and edibles dominate prescription volumes due to patient familiarity and discreet administration. Manufacturers are resolving bioavailability limitations through nanoemulsion technology.
- Inhalation:Vaporized flower and concentrates deliver rapid onset for acute symptom relief. Equipment manufacturers report twelve-month order backlogs for medical-grade devices.
- Sublingual:Tinctures and oromucosal sprays bypass first-pass metabolism. These formulations attract compounding pharmacy customization for precise cannabinoid ratios.
- Topical:Transdermal patches and creams target localized inflammation without systemic absorption. Dermatology and rheumatology practices in California are piloting these for osteoarthritis protocols.
Oral administration holds established volume; sublingual delivery shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of pharmaceutical-grade extracts from Canada into the United States now exceed outbound shipments of US-manufactured formulations to Canadian clinics. This trade asymmetry reflects Health Canada's EU-GMP certification advantage and the FDA's slower drug approval timelines for cannabinoid pharmaceuticals.
United States
California's chronic pain clinics and Florida's physician certification programs generate the highest prescription volumes nationally. The FDA's expanded access program channels institutional investment toward GMP-certified production facilities in Colorado and California. State-quarantine requirements under the Controlled Substances Act force redundant inventory positioning across state lines.
Canada
Ontario's dispensary density supports same-day fulfillment models that concentrate national distribution infrastructure. Health Canada's Cannabis Act amendment reduces research license approval timelines from eighteen months to ninety days for Phase II studies. Toronto and Montreal academic medical centers compete with US institutions for cannabinoid pharmaceutical development.
Mexico
Federal therapeutic use regulations enacted in 2017 remain underdeveloped compared to US and Canadian frameworks. The country's national pharmaceutical regulator has approved limited THC and CBD imports for hospital pharmacy dispensing. Mexico City Metro anchors early clinical trial activity for epilepsy and multiple sclerosis protocols.
North America Medical Cannabis Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The North America medical cannabis sector structures around multi-state operators with geographic coverage licenses and pharmaceutical-grade producers with GMP certification. Three archetypes dominate: asset-light licensing platforms, controlled retail distributors, and clinical-channel suppliers. Competitive moves concentrate on debt covenant restructuring ahead of federal rescheduling and consolidation of hospital vendor lists to single-source GMP-certified suppliers.
Among multi-state operators, Curaleaf Holdings, Green Thumb Industries, and Trulieve Cannabis exemplify the licensing-platform archetype. These entities sustain geographic coverage without owning every cultivation facility. Tilray Brands occupies a position within the pharmaceutical-grade tier, differentiating supply for clinical channels through production standards. The named companies represent the dominant competitive positioning patterns visible across the sector.
| Leading Market Players |
|---|
| Curaleaf Holdings |
| Trulieve Cannabis |
| Green Thumb Industries |
| Acreage Holdings |
| Tilray Brands |
| Aurora Cannabis |
| Canopy Growth Corporation |
| Cronos Group |
| Vireo Health |
| Others |
Value Network & Pricing Analysis
California and Colorado cultivation clusters anchor upstream supply for pharmaceutical-grade extracts, concentrating margin capture with GMP-certified processors while state-quarantine requirements fragment downstream pricing power across redundant distribution nodes. This geographic concentration of extraction capacity creates tiered value pools that favor certified manufacturers over commodity cultivators.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels, with FDA establishment identifiers and EU-GMP certification commanding substantial premiums over state-compliant alternatives. Price differentiation rests on analytical chemistry capabilities and DEA registration status, not raw biomass quality. Cost compression in standard-tier oils is intensifying because electricity rate spikes in Ontario and California cultivation zones have propagated downstream. Outpatient clinics and homecare delivery services exhibit the highest price sensitivity, while integrated delivery networks prioritize single-source GMP suppliers regardless of unit cost.
Supply Chain Analysis
US Controlled Substances Act interstate commerce prohibitions function as export-control regime analogs, restricting bulk wholesale transfers across state lines and forcing redundant inventory positioning. Geographic supply concentration centers on California, Colorado, and Ontario for extraction and formulation, with British Columbia and Oregon contributing raw biomass. Raw material dependencies include supercritical CO2 extraction equipment, pharmaceutical-grade ethanol, and lipid nanoparticle encapsulation inputs. Single-source vulnerability concentrates in ISO 17025-accredited testing laboratory capacity, where recruitment gaps for cannabinoid quantification specialists extend batch release timelines. Distribution runs through state-mandated seed-to-sale track-and-trace systems requiring real-time API integration across incompatible software architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Institutional procurement consolidation creates fragmentation opportunity for specialized clinical-channel suppliers, as hospital formulary committees displace multi-vendor arrangements and elevate certification requirements that exclude generalist cultivators.
For Market Incumbents: Insulate market position by deepening captive supply of pharmaceutical-grade extraction capacity in Colorado and California ahead of federal rescheduling, while accelerating DEA registration and FDA establishment identifier acquisition to defend against emerging GMP-certified competitors from Canada. Debt covenant restructuring represents the priority defensive lever as capital timelines compress. For New Entrants and Emerging Players: Veterans Health Administration PTSD and chronic pain protocols represent the most penetrable entry point, with fewer than twelve qualified suppliers currently serving this federal procurement channel. Neurological disorder applications for epilepsy and multiple sclerosis offer secondary white-space opportunity through Health Canada's streamlined research license pathway. A go-to-market angle anchored in investigator-initiated trial sponsorship with Toronto and Montreal academic medical centers accelerates clinical evidence generation. For Investors and Strategic Acquirers: Capital is best deployed toward asset-light licensing platforms with multi-state operating coverage and established physician certification program relationships, rather than capital-intensive cultivation infrastructure. Long-term viability hinges on regulatory optionality across federal rescheduling scenarios. The signal to watch as inflection indicator is Health Canada export permit issuance velocity for EU-GMP certified producers accessing German and Australian markets.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | DEA registration and FDA establishment identifiers unlock hospital procurement committee vendor consolidation. |
| Clinical Trial Advancement | Health Canada's ninety-day research license pathway accelerates Phase II enrollment for neurological applications. |
| Backward Integration into Extraction | Supercritical CO2 equipment order backlogs favor captive pharmaceutical-grade processing capacity. |
| Strategic Partnership | Hospital system partnerships with Cleveland Clinic and Mayo Clinic-affiliated practices validate nanoencapsulation formulations. |
| Geographic Expansion | EU-GMP certification enables preferential tariff access to German and Australian medical cannabis markets. |
Research Methodology
A spread of perspectives from regulatory affairs leads at multi-state operators, hospital formulary directors, chronic pain clinic physicians, GMP facility quality managers, and Health Canada licensing officers converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation from FDA expanded access program filings, Health Canada research license databases, ClinicalTrials.gov cannabinoid protocol registrations, and state medical marijuana program enrollment statistics. Bottom-up prescription volume modeling and top-down market sizing triangulated on segment-level estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product format, therapeutic application, end-user channel, and delivery mode. Patient population access curves and reimbursement pathway development trajectories informed volume build-ups. CAGRs derived from regression analysis against regulatory event timelines and clinical trial enrollment velocity, with cross-validation against electricity rate and input cost sensitivity scenarios for cultivation economics.
Practitioners should monitor federal rescheduling deliberations, FDA cannabinoid pharmaceutical approval timelines, and Health Canada export permit issuance rates for early signals of forecast revision. Material shifts in IRS Section 280E tax code treatment or interstate commerce authorization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Medical Cannabis Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Legal Marijuana Market