
 CBD Market | 2026-2036
CBD Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Market Analytics
Aftermarket education and certification revenue is reshaping how CBD brands monetize customer relationships beyond initial product sales. Charlotte's Web leverages its seed-to-shelf vertical integration to sustain premium positioning in a crowded retail environment. Lazarus Naturals anchors its competitive stance through accessibility-focused pricing and veteran discount programs that build defensible loyalty. Medterra differentiates via NSF Certified for Sport and US Hemp Authority certifications that command shelf space in regulated pharmacy channels.
Cannabidiol is a non-psychoactive phytocannabinoid extracted from hemp biomass, typically refined to contain less than 0.3% delta-9 THC by dry weight through CO2 or ethanol extraction processes, and functions primarily as an active ingredient in wellness and therapeutic formulations. Oils and tinctures occupy the mature core of the product mix with established household penetration, while gummies capture the fastest growth trajectory as flavor-masked delivery appeals to cannabinoid-naive consumers entering the category. The health supplements application dominates current volume, though personal care represents the emerging margin pool where topical bioavailability innovations command price premiums.
The FDA maintains enforcement discretion over CBD in dietary supplements while the 2018 Farm Bill's hemp legalization created a patchwork of state-level regulatory regimes that complicate interstate commerce. The US Hemp Authority certification program and NSF International testing standards increasingly function as de facto market access requirements for national retail distribution. Stakeholders must monitor whether the FDA establishes a formal regulatory pathway for CBD as a dietary supplement ingredient or continues channeling development toward pharmaceutical-grade isolation.
Market Dynamics
The FDA's enforcement discretion over CBD dietary supplements is compressing investment timelines and redirecting R&D capital toward pharmaceutical-grade isolation and compliant topical channels.
Growth Catalysts
- Clinical validation pathway:The FDA's Epidiolex approval framework establishes precedent for prescription-grade cannabidiol, accelerating pharmaceutical pipeline investment and legitimizing therapeutic claims in regulated channels.
- State-level policy divergence:Fragmented US state cannabis regulations create arbitrage opportunities for product developers who navigate compliant interstate distribution networks.
- CO2 extraction refinement:Supercritical fluid processing advances are lowering residual solvent thresholds below 50 ppm, satisfying NSF International standards for pharmacy shelf placement.
Market Restraints
- Input cost volatility:Hemp biomass pricing fluctuates with weather-driven yield variability in Kentucky and Colorado cultivation belts, squeezing margin predictability for mid-scale processors.
- Regulatory friction:The FDA's refusal to establish a dietary supplement pathway for CBD blocks mainstream retail distribution and forces reliance on specialty channels with higher customer acquisition costs.
- Technical limitation:Poor oral bioavailability of cannabidiol requires high-dose formulations that inflate unit costs and complicate label-claim substantiation.
Strategic Opportunities
- Underpenetrated pharmacy channel:Independent and chain pharmacies in Germany and Switzerland present first-mover potential for certified topical SKUs ahead of EU harmonization.
- Emerging application:Personal care formulations targeting skin barrier repair command price premiums in South Korean and Japanese beauty retail.
- Regulatory tailwind:The 2018 Farm Bill's hemp legalization framework, if matched by federal supplement rulemaking, would unlock mass-market grocery and convenience distribution.
Industry Challenges
- Analytical chemistry talent scarcity:Accredited labs capable of THC quantification below 0.3% dry weight are concentrated in Colorado and Oregon, creating testing bottlenecks for new market entrants.
- Certification timeline compression:US Hemp Authority and NSF Certified for Sport audits require 12-18 month preparation cycles that delay revenue recognition for reformulated product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Market |
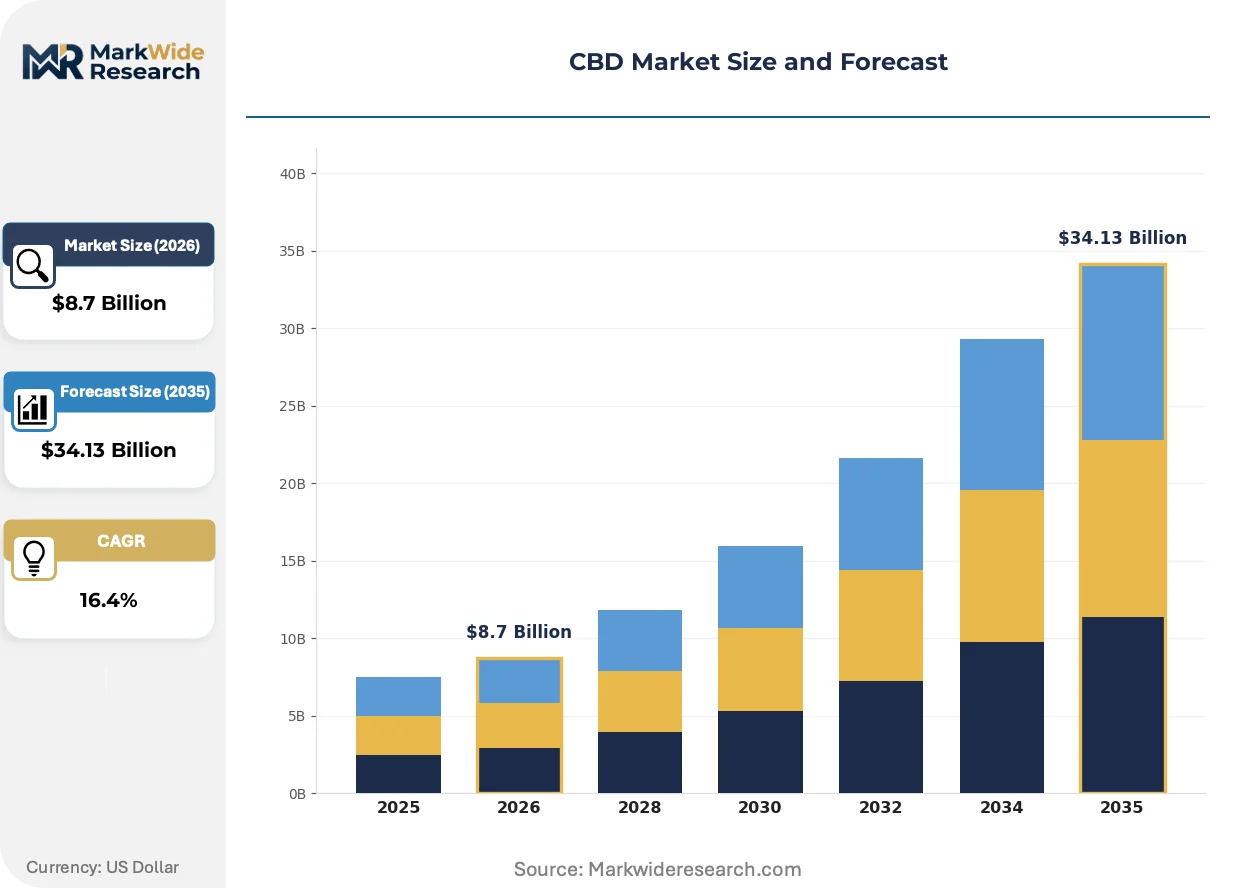
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Tinctures, Gummies, Capsules Application: Health Supplements, Personal Care, Pharmaceuticals, Food & Beverage Delivery Mode: Sublingual, Topical, Inhalation, Edible Customer Type: Retail Consumers, Wholesalers, Online Buyers, Medical Practitioners |
| Companies Covered | Charlotte’s Web, Lazarus Naturals, Medterra, CBD American Shaman, NuLeaf Naturals, CBDfx, cbdMD, CBDistillery, PlusCBD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Market Evolving Landscape
Formulation science and channel compliance are converging to reshape how cannabidiol reaches end consumers, with technology investments prioritizing bioavailability enhancement and regulatory pre-clearance.
Liposomal and nanoemulsion delivery systems are virtualizing the absorption profile of oral CBD, compressing the effective dose threshold from 25mg to 5-10mg equivalents. Pharmaceutical and nutraceutical formulators in Germany and Japan are adopting these platforms fastest, enabling smaller capsule sizes that improve patient compliance and reduce per-unit active ingredient costs. This virtualization of pharmacokinetics is collapsing the historical trade-off between efficacy and tolerability that constrained category expansion.
The FDA's ongoing evaluation of CBD safety data is reshaping capital allocation across the value chain, with enforcement discretion pushing developers toward New Drug Application pathways rather than supplement positioning. The industrial consequence is a bifurcation between pharmaceutical-grade isolates and wellness-positioned topicals, with the middle ground of ingestible supplements experiencing investment withdrawal. Personal care and cosmetic applications are absorbing this redirected R&D spend, particularly in formulations targeting dermatological endpoints where efficacy claims face lower evidentiary thresholds.
Pharmacy buyers are consolidating supplier relationships around vertically integrated producers who control seed genetics through retail shelf placement, displacing the prior model of fragmented white-label sourcing. This concentration is most visible in US independent pharmacy networks and German Apotheke chains, where procurement committees now require batch-level Certificates of Analysis and documented chain-of-custody documentation. The shift favors producers with captive cultivation and in-house analytical capabilities, compressing margins for toll processors and contract manufacturers lacking upstream asset control.
CBD Market Segmentation
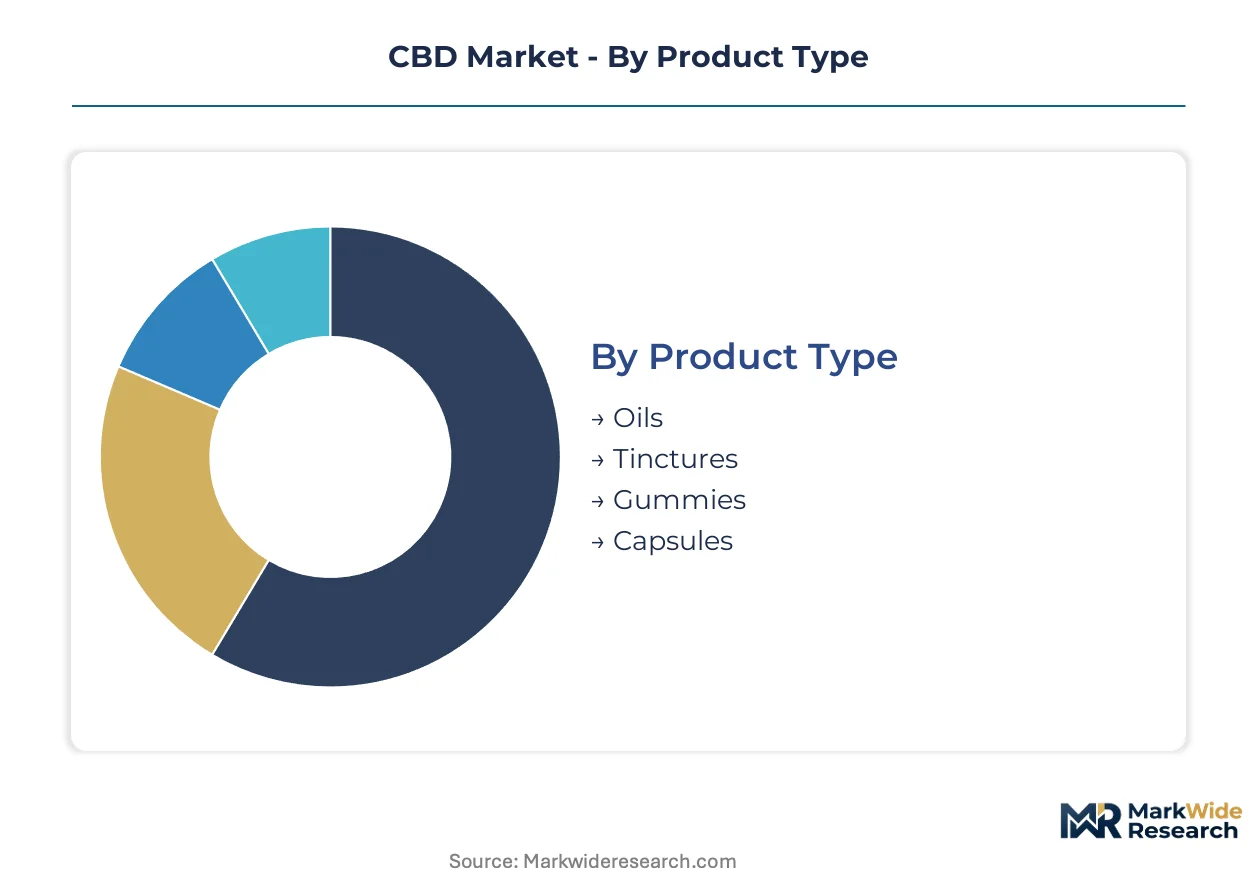
Product differentiation in the CBD market follows distinct consumption occasions and regulatory risk profiles. Each segmentation dimension reveals how formulators balance bioavailability, compliance pathways, and channel access.
Product Type:
The use-case spectrum spans therapeutic precision to casual wellness consumption, with delivery format determining both regulatory exposure and margin structure.
- Oils:Full-spectrum or isolate suspensions in carrier oils deliver measurable dosing for chronic condition management. Demand concentrates in German pharmacy channels where Apotheke procurement committees require USP-grade ethanol extraction documentation and batch-specific residual solvent reports.
- Gummies:Pectin or gelatin matrices mask hemp-derived bitterness through flavor engineering, appealing to cannabinoid-naive entrants. South Korean beauty retailers and Japanese convenience chains are absorbing volume fastest as these formats bypass the stigma associated with tincture bottles.
- Tinctures:Alcohol-based extracts with rapid sublingual absorption serve experienced users seeking dose titration precision.
- Capsules:Powder-filled gelatin shells standardize dosing for compliance-sensitive medical practitioners in Switzerland and Australia.
Established volume favors oils; emerging adoption favors gummies.
Application:
Margin concentration tracks regulatory clarity, with pharmaceutical pathways commanding certification premiums and personal care absorbing redirected R&D investment.
- Health Supplements:Ingestible formulations positioned below FDA drug thresholds dominate current tonnage. The US FDA's enforcement discretion blocks mainstream retail, forcing reliance on direct-to-consumer and specialty vitamin channels with elevated customer acquisition costs.
- Pharmaceuticals:Isolated cannabidiol meeting USP or EP monograph standards follows the Epidiolex approval precedent. Pipeline investment is accelerating in UK and Israeli research clusters where regulatory frameworks accommodate prescription-grade development.
- Personal Care:Topical formulations targeting dermatological endpoints face lower evidentiary barriers than ingestible claims.
- Food & Beverage:Infused beverages and functional snacks remain constrained by the FDA's position that CBD cannot be added to interstate commerce foods.
Health supplements anchor current revenue; pharmaceuticals command the steepest expansion trajectory.
Delivery Mode:
Absorption kinetics and onset timing segment users by urgency of therapeutic need and social acceptability constraints.
- Sublingual:Mucosal absorption bypasses hepatic first-pass metabolism, achieving bioavailability advantages critical for acute anxiety or seizure management protocols.
- Topical:Transdermal and surface applications target localized inflammation without systemic exposure. German and Swiss pharmacy buyers are consolidating supplier relationships around vertically integrated producers controlling seed genetics through shelf placement.
- Inhalation:Vaporized delivery offers rapid onset but faces mounting scrutiny from EPA air quality regulators and state-level flavor bans.
- Edible:Gastrointestinal absorption with delayed onset suits routine wellness maintenance rather than acute symptom relief.
Sublingual formats retain clinical credibility; topicals are gaining share fastest in regulated pharmacy channels.
Customer Type:
Purchasing authority and volume scale separate fragmented retail demand from concentrated institutional procurement with divergent compliance requirements.
- Retail Consumers:Individual purchasers through e-commerce and brick-and-mortar specialty stores drive unit volume. Colorado and Oregon testing bottlenecks create fulfillment delays for new market entrants lacking established lab relationships.
- Medical Practitioners:Prescribing clinicians and clinic networks in Australia and Switzerland require documented chain-of-custody and Certificate of Analysis documentation at batch level.
- Wholesalers:Distributors bridging processors and retail endpoints absorb inventory risk and manage state-level licensing fragmentation.
- Online Buyers:Direct-to-consumer channels capture subscription revenue with higher lifetime value but elevated payment processor scrutiny.
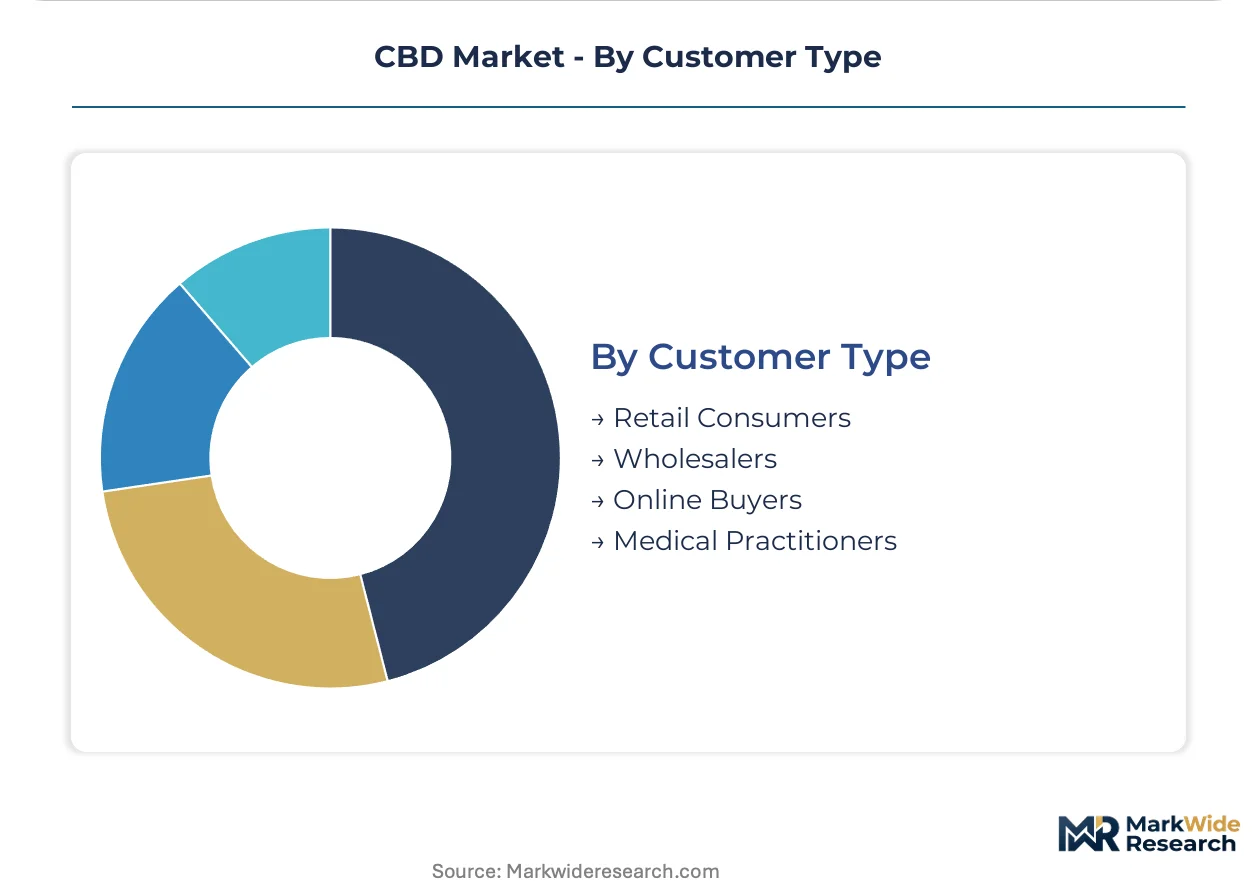
Retail consumers generate transaction volume; medical practitioners concentrate margin through certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes CBD predominantly through health supplements and topicals, while Germany and Switzerland favor pharmacy-distributed pharmaceutical-grade isolates, and South Korea absorbs gummy formats through beauty retail channels.
United States
Health supplements and topical creams dominate consumption patterns as the FDA maintains enforcement discretion over dietary supplement pathways. Kentucky and Colorado cultivation belts supply hemp biomass to processors facing state-level licensing fragmentation that complicates interstate distribution. Denver and Boulder host concentrated testing laboratory capacity for THC quantification below 0.3% dry weight.
Germany
Apotheke pharmacy chains absorb certified topical SKUs and isolate oils for chronic condition management protocols. The country's national pharmaceutical regulator evaluates CBD safety data under evolving EU frameworks that accommodate prescription-grade development. Cologne and Düsseldorf clusters concentrate vertically integrated producers controlling seed genetics through retail shelf placement.
Switzerland
Medical practitioners and clinic networks require documented chain-of-custody documentation at batch level for capsule and tincture formulations. Swissmedic maintains distinct cannabidiol regulations that permit broader retail distribution than neighboring EU jurisdictions. Zurich and Geneva house procurement committees consolidating supplier relationships around producers with captive cultivation.
South Korea
Beauty retailers and convenience chains absorb gummy formats as flavor-masked delivery appeals to cannabinoid-naive consumers entering the category. The country's national food and drug regulator restricts ingestible claims while permitting topical dermatological applications. Seoul-based personal care formulators command price premiums for skin barrier repair innovations.
United Kingdom
Research clusters accelerate pharmaceutical pipeline investment following the Epidiolex approval precedent for prescription-grade cannabidiol. The Medicines and Healthcare products Regulatory Agency evaluates novel food applications while permitting topical cosmetic positioning. London and Cambridge concentrate biotech development facilities targeting regulated therapeutic channels.
CBD Market Competitive Landscape
Capability concentration sits with vertically integrated specialists controlling seed genetics through analytical certification; scale advantage sits with diversified wellness brands leveraging existing retail relationships. The vendor base separates into three strategic archetypes: seed-to-shelf integrators sustaining premium positioning, accessibility-focused value players, and certification-driven pharmacy suppliers. Dominant competitive moves include backward integration into captive cultivation and 12-18 month certification preparation cycles for US Hemp Authority and NSF International standards.
Among seed-to-shelf integrators, Charlotte's Web occupies a position exemplifying vertical control over genetics and retail shelf placement. Lazarus Naturals and Medterra sit within the accessibility and certification tiers respectively, representing how discount programs and NSF Certified for Sport standards build defensible loyalty and command pharmacy channel access.
| Leading Market Players |
|---|
| Charlotte's Web |
| Lazarus Naturals |
| Medterra |
| CBD American Shaman |
| NuLeaf Naturals |
| CBDfx |
| cbdMD |
| CBDistillery |
| PlusCBD |
| Others |
Value Network & Pricing Analysis
Denver and Boulder laboratory clusters concentrate THC quantification capacity below 0.3% dry weight, creating testing bottlenecks that inflate certification costs and compress margins for processors lacking established lab relationships. This geographic concentration of analytical chemistry talent feeds directly into downstream pricing power for vertically integrated producers who control in-house testing capabilities.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade isolate procurement, while spot purchasing prevails in hemp biomass and toll processing services. Three-tier pricing structure across US Hemp Authority-certified, NSF International-verified, and uncertified product levels separates pharmacy-channel premiums from direct-to-consumer discounts. Pricing pressure stems from Kentucky and Colorado weather-driven yield variability squeezing mid-scale processor margins. Retail consumers exhibit highest price sensitivity, while medical practitioners in Switzerland and Australia absorb certification premiums without volume elasticity.
Supply Chain Analysis
Contract manufacturing concentrates among Colorado and Oregon-based processors with captive CO2 extraction infrastructure and in-house analytical capabilities. Raw material flows draw from Kentucky and Colorado cultivation belts, with German Apotheke chains and South Korean beauty retailers anchoring downstream demand. Single-source vulnerability sits with accredited labs capable of residual solvent quantification below 50 ppm. Distribution runs through vertically integrated seed-to-shelf producers, displacing fragmented white-label sourcing in pharmacy procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket education and certification revenue layers expand faster than core product sales, repositioning CBD brands around recurring-revenue customer relationships rather than transactional extract volume.
For Market Incumbents: Build regulatory moats through US Hemp Authority and NSF Certified for Sport certification cycles that lock out competitors for 12-18 month preparation windows. Deepen backward integration into captive cultivation in Kentucky and Colorado to secure biomass supply against weather-driven yield volatility. Channel control through independent pharmacy networks and German Apotheke chains defends margin position against direct-to-consumer price erosion. For New Entrants and Emerging Players: Build out white-space presence in South Korean and Japanese personal care channels where skin barrier repair formulations command price premiums with lower evidentiary thresholds than ingestible claims. Target underpenetrated independent pharmacy networks in Germany and Switzerland ahead of EU harmonization. Launch through certified topical SKUs rather than contested supplement positioning to bypass FDA enforcement discretion friction. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because state-level cannabis policy divergence and evolving FDA posture create windows for compliant channel development ahead of federal clarity. Acquisition focus should center on vertically integrated producers with in-house analytical capabilities and established pharmacy shelf placement. Monitor FDA dietary supplement pathway decisions as the critical inflection signal for mass-market grocery and convenience distribution unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Kentucky and Colorado biomass control secures supply against weather-driven yield volatility. |
| US Hemp Authority Certification Investment | 12-18 month audit cycles create de facto market access requirements for national retail distribution. |
| Pharmacy Channel Expansion | German Apotheke and Swiss pharmacy procurement committees consolidate supplier relationships around certified producers. |
| Nanoemulsion Delivery System Adoption | Liposomal platforms in Germany and Japan compress effective dose thresholds from 25mg to 5-10mg equivalents. |
| Personal Care Formulation Pivot | Topical dermatological applications absorb redirected R&D spend with lower evidentiary barriers than ingestible claims. |
Research Methodology
A spread of perspectives from hemp cultivation operators, CO2 extraction facility managers, pharmacy procurement committees, and NSF International certification auditors converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation against FDA enforcement discretion documentation, US Hemp Authority certification standards, and German Apotheke distribution records. Bottom-up volume modeling across product types and applications triangulated against top-down market sizing from trade flow analysis.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with segmentation dimensions spanning product type, application, delivery mode, and customer purchasing authority. CAGRs derived from elasticity-adjusted growth rate analysis incorporating bioavailability enhancement technology adoption curves and pharmacy channel penetration trajectories. Hemp biomass pricing volatility and certification timeline compression functioned as key forecast sensitivity inputs.
Stress conditions across FDA regulatory pathway decisions, Kentucky and Colorado weather patterns, and EU harmonization timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory shifts, input cost spikes, or analytical chemistry talent scarcity intensification. Quarterly review of FDA enforcement posture, state-level licensing fragmentation, and pharmacy procurement committee consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
North America Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Global Cannabis Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Thailand Legal Cannabis Market