
 Cannabinoid Therapy Market | 2026-2036
Cannabinoid Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabinoid Therapy Market Analysis
Hospital procurement committees are collapsing their historical skepticism toward cannabinoid-based protocols and gaining share as the dominant buyer archetype in institutional channels. Jazz Pharmaceuticals leverages its FDA-approved Epidiolex franchise to sustain dominance in the prescription epilepsy segment. Tilray Brands competes through backward integration into European cultivation assets that anchor its pharmaceutical-grade supply capacity. Curaleaf Holdings extends its retail footprint across state-legal US markets, where it controls one of the largest dispensary networks.
Cannabinoid therapy encompasses the clinical use of plant-derived and synthetic phytocannabinoids—primarily CBD, THC, and their analogs—formulated to precise purity thresholds and administered under medical supervision for therapeutic endpoints. These compounds interact with the endocannabinoid system to modulate pain signaling, seizure threshold, and inflammatory response, with standardized extraction and chromatographic purification ensuring batch-to-batch consistency for regulatory submission. The indication dimension shows pain management occupying the largest revenue pool due to chronic condition prevalence, while epilepsy commands premium pricing through orphan-drug positioning and FDA exclusivity. Oral delivery modes lead volume due to patient familiarity and dosing precision, though sublingual formats are capturing share among homecare users seeking faster onset.
The FDA maintains a bifurcated stance—approving specific cannabinoid isolates while leaving whole-plant extracts in enforcement discretion—creating compliance complexity for manufacturers with mixed product portfolios. Germany's BfArM and the EU's EMA framework for botanical drug substances are shaping quality standards that determine market access across European reimbursement systems. Stakeholders must monitor how the EU's novel food designation intersects with pharmaceutical pathway claims, as this regulatory boundary will determine which product formats achieve sustainable margin structures.
Market Dynamics
The 2018 Farm Bill fragmented US compliance into state-specific THC thresholds, forcing manufacturers to maintain parallel supply chains and quality systems for products crossing state lines.
Growth Catalysts
- Germany's BfArM reimbursement framework:The national health insurance system's coverage of cannabinoid prescriptions for neuropathic pain and spasticity creates institutional demand pull.
- Chronic pain clinics:Hospital formulary committees are expanding cannabinoid-based protocols as regulatory pathways stabilize in major jurisdictions.
- European cultivation assets:Backward integration into pharmaceutical-grade supply capacity anchors batch consistency for regulatory submission.
Market Restraints
- THC threshold volatility:Input cost uncertainty stems from state-level THC limits varying between 0.3% and 1% dry weight.
- Supply concentration:European pharmaceutical-grade cultivation clusters in Portugal and Denmark create geographic single-point vulnerability.
- Botanical drug substance complexity:The EU's EMA framework requires extensive impurity profiling that extends development timelines.
Strategic Opportunities
- Homecare sublingual formats:Faster onset delivery modes are capturing share among patients seeking alternatives to oral administration.
- Novel food designation overlap:The EU's regulatory boundary between pharmaceutical and wellness claims creates white space for margin-optimized positioning.
- Epilepsy orphan-drug pricing:FDA exclusivity for specific cannabinoid isolates enables premium positioning in seizure threshold modulation.
Industry Challenges
- Chromatographic purification talent:Batch-to-batch consistency requires specialized analytical chemists with botanical extraction experience.
- Dual-pathway compliance:Manufacturers with mixed portfolios must navigate FDA approval for isolates while managing enforcement discretion risk for whole-plant extracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabinoid Therapy Market |
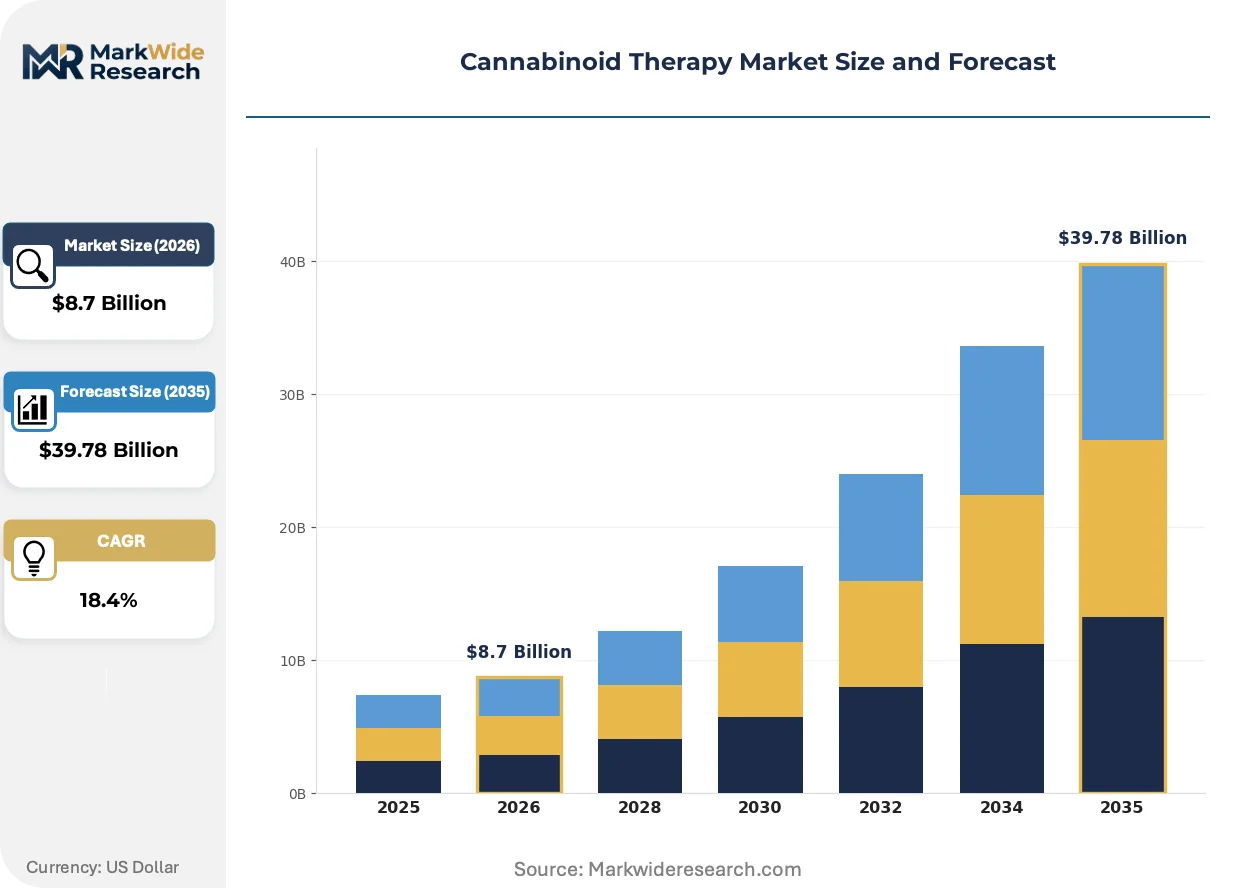
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cannabinoid Oils, Capsules, Tinctures, Edibles Indication: Pain Management, Anxiety Disorders, Epilepsy, Sleep Disorders Delivery Mode: Oral, Sublingual, Topical, Inhalation End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Jazz Pharmaceuticals plc, Canopy Growth Corporation, Tilray Brands, Inc., Aurora Cannabis Inc., Cronos Group Inc., AbbVie Inc., Corbus Pharmaceuticals Holdings, Inc., Curaleaf Holdings Inc., BOL Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabinoid Therapy Market Emerging Trajectories
Standardized extraction and chromatographic purification is compressing development timelines while regulatory clarity in Germany and select US states enables institutional procurement normalization.
Supercritical CO2 extraction technology is miniaturizing. Chronic pain clinics and hospital outpatient departments are adopting bench-scale systems for on-site formulation preparation. This distributed production model is compressing supply chain complexity and enabling point-of-care customization for patient-specific cannabinoid ratios.
The EU's novel food designation intersects with pharmaceutical pathway claims in ways that determine sustainable margin structures. Manufacturers must choose between wellness positioning with limited health claims or full drug development with reimbursement access. German and Dutch regulators are shaping quality standards that propagate across European reimbursement systems.
Hospital procurement committees are collapsing historical skepticism toward cannabinoid-based protocols. Institutional buyers now dominate channel volume, displacing legacy direct-to-patient dispensary models. This concentration is most visible in Germany, where national health insurance reimbursement requires pharmaceutical-grade certification that only institutional suppliers can maintain.
Cannabinoid Therapy Market Segmentation
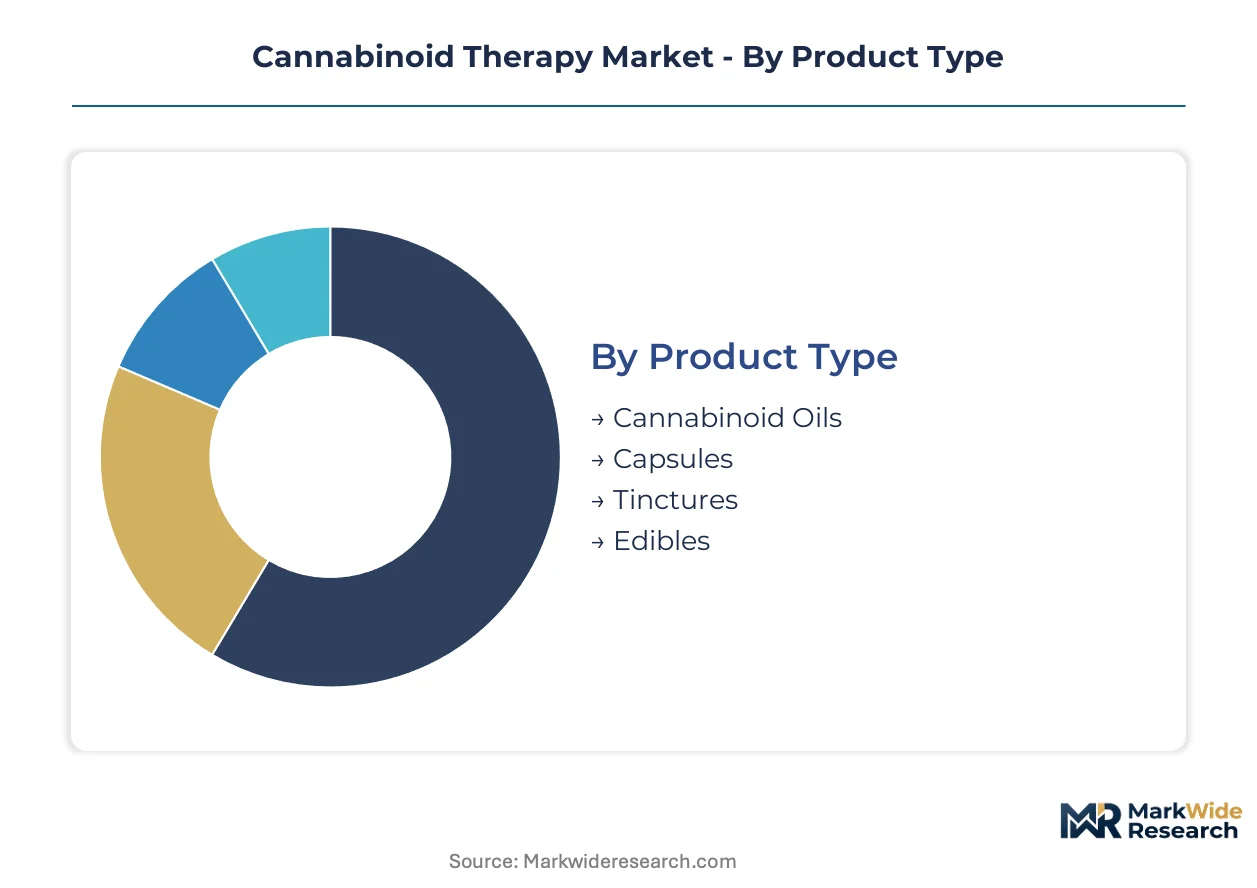
Cannabinoid therapy markets fragment across four dimensions that determine reimbursement access, regulatory pathway, and margin structure. Product format and delivery mode dictate whether manufacturers pursue pharmaceutical approval or wellness positioning, while indication and end-user concentration shape procurement dynamics.
Product Type:
Substitution pressure runs highest in formats competing with conventional pharmaceuticals for formulary slots, where purity certification and batch consistency determine access.
- Cannabinoid Oils:Lipid-based suspensions with defined CBD:THC ratios enable precise titration protocols. German hospital procurement committees favor pharmaceutical-grade oils for neuropathic pain reimbursement, though state-level THC thresholds in the US force parallel supply chains.
- Capsules:Gelatin or hypromellose shells containing standardized isolate powders offer dosing precision that satisfies FDA botanical drug substance requirements. Chronic pain clinics in Denmark and Portugal specify capsule formats for their institutional formularies.
- Tinctures:Alcohol or glycerin-based extracts with variable cannabinoid profiles serve wellness-channel positioning where EU novel food designation applies.
- Edibles:Food-matrix formulations face the steepest regulatory barriers under FDA enforcement discretion for whole-plant extracts.
Cannabinoid oils retain volume leadership; capsules hold the steepest expansion curve.
Indication:
Cost tier stratification separates orphan-drug pricing opportunities from commodity reimbursement pressure across therapeutic areas.
- Pain Management:Chronic condition prevalence drives the largest addressable population, though reimbursement rates vary sharply between Germany's BfArM-covered neuropathic indications and US state Medicaid variability.
- Epilepsy:FDA-approved isolates for Dravet and Lennox-Gastaut syndromes command premium pricing through orphan-drug exclusivity, with Jazz Pharmaceuticals' Epidiolex franchise setting the benchmark.
- Anxiety Disorders:Off-label prescribing dominates where regulatory frameworks lag clinical evidence generation.
- Sleep Disorders:Melatonin-cannabinoid combination products compete in wellness channels with limited health claim authorization.
Pain management retains volume leadership; epilepsy holds the steepest expansion curve.
Delivery Mode:
Patient type concentration shapes format preference, with institutional buyers favoring precision and homecare users prioritizing onset speed.
- Oral:Tablets, capsules, and ingestible oils dominate hospital procurement due to familiar administration protocols and measurable bioavailability. German national health insurance reimbursement requires pharmaceutical-grade oral formats.
- Sublingual:Mucosal sprays and drops bypass first-pass metabolism for faster onset, capturing share among homecare patients seeking alternatives to oral administration.
- Topical:Transdermal patches and creams target localized inflammation with limited systemic exposure, appealing to occupational health programs.
- Inhalation:Vaporization devices face the most restrictive institutional formulary scrutiny due to respiratory safety concerns and dosing variability.
Oral delivery retains volume leadership; sublingual formats hold the steepest expansion curve.
End User:
Supply concentration aligns with certification requirements, as pharmaceutical-grade capacity clusters in jurisdictions with harmonized GMP standards.
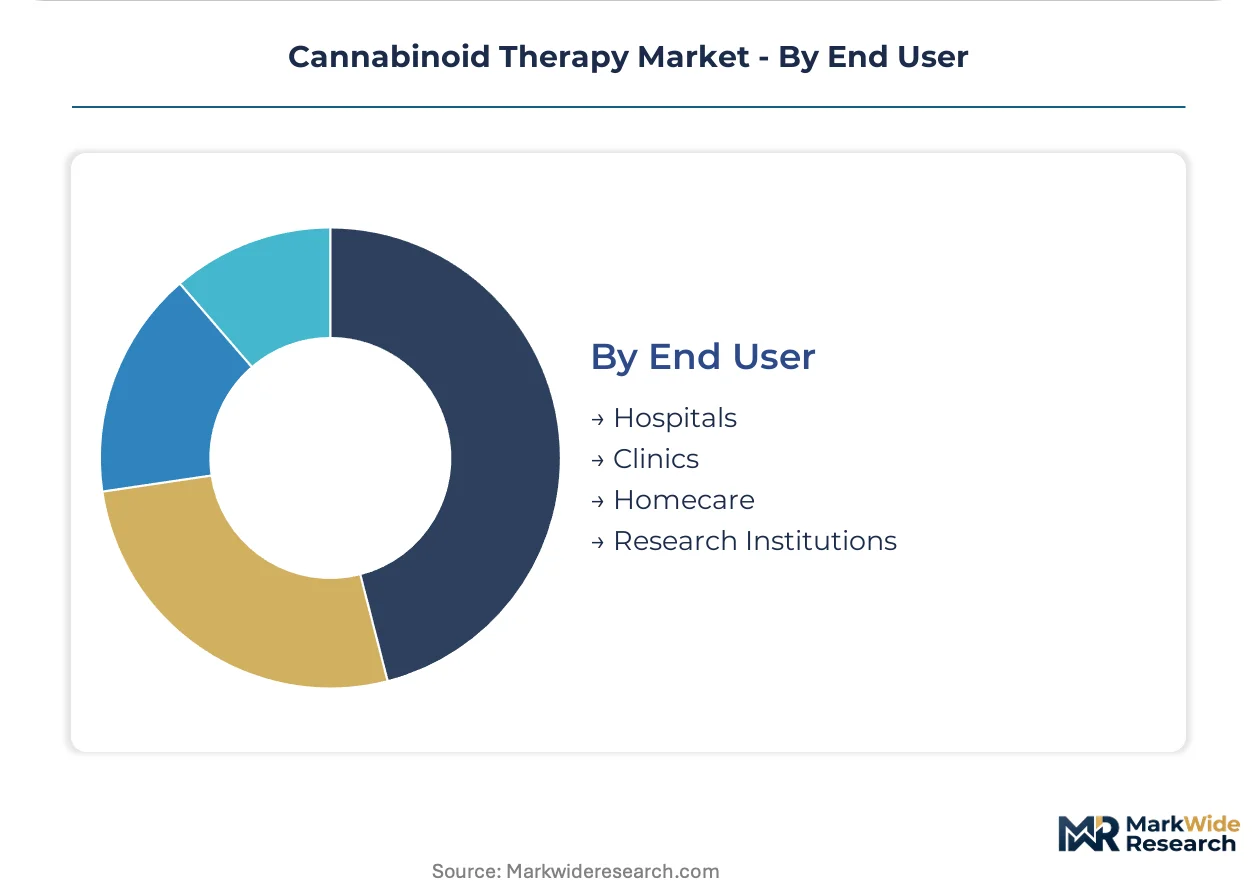
- Hospitals:Procurement committees now dominate channel volume, collapsing historical skepticism toward cannabinoid protocols where regulatory clarity enables formulary inclusion.
- Clinics:Chronic pain and spasticity specialists in Germany drive institutional demand through BfArM reimbursement frameworks.
- Homecare:Direct-to-patient models are losing share to institutional channels where insurance coverage determines access.
- Research Institutions:Academic medical centers conduct investigator-initiated trials that shape future indication expansion.
Hospitals retain volume leadership; clinics hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany now dominate institutional channel volume, displacing legacy direct-to-patient models as reimbursement frameworks mature across select jurisdictions.
Germany
BfArM reimbursement for neuropathic pain and spasticity indications pulls institutional demand through chronic pain clinics and hospital outpatient departments. The national health insurance system's pharmaceutical-grade certification requirements concentrate supply among GMP-certified domestic distributors. Cultivation clusters in North Rhine-Westphalia and Bavaria anchor pharmaceutical-grade production capacity for the broader EU market.
United States
State-legal dispensary networks face compression as hospital formulary committees expand cannabinoid-based protocol inclusion. The FDA maintains bifurcated enforcement discretion between approved isolates and whole-plant extracts, creating compliance complexity for manufacturers with mixed portfolios. California and Colorado cultivation regions supply raw material to pharmaceutical-grade processors seeking institutional channel access.
Canada
Health Canada licensing frameworks enable export-oriented pharmaceutical-grade production serving German and Australian demand. Federal legalization permits integrated cultivation-to-distribution models unavailable in US jurisdictions. Ontario and British Columbia host the primary extraction and formulation clusters supplying international institutional buyers.
Australia
The TGA's Special Access Scheme drives demand through hospital-based specialists rather than retail channels. Import dependence on Canadian and European supply creates logistics complexity for patient access programs. Sydney and Melbourne academic medical centers conduct investigator-initiated trials shaping future indication expansion.
United Kingdom
NHS England commissioning decisions restrict reimbursed access to narrow epilepsy and spasticity indications despite broader private prescribing. The MHRA's novel food and pharmaceutical boundary enforcement limits wellness-channel positioning for non-authorized products. London-based specialty pharmacies coordinate import and distribution for private-pay patients.
Cannabinoid Therapy Market Vendor Landscape
Player mix skews toward pharmaceutical incumbents with approved isolates and vertically integrated cultivators with GMP-certified European assets. The structure concentrates around two poles: FDA-approved epilepsy franchises commanding orphan-drug pricing, and state-legal US operators competing on retail footprint scale. Strategic archetypes include prescription pharmaceutical specialists, backward-integrated European cultivators, and multi-state US dispensary operators. Competitive moves center on M&A for cultivation capacity and strategic partnerships for institutional distribution access.
Among pharmaceutical specialists, Jazz Pharmaceuticals plc and Corbus Pharmaceuticals Holdings, Inc. exemplify the FDA-approved isolate archetype, while Tilray Brands, Inc. represents backward integration into European GMP cultivation assets. These three entities occupy distinct strategic positions: prescription drug development with reimbursement access, pharmaceutical-grade supply chain control, and institutional channel certification respectively.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals plc |
| Canopy Growth Corporation |
| Tilray Brands, Inc. |
| Aurora Cannabis Inc. |
| Cronos Group Inc. |
| AbbVie Inc. |
| Corbus Pharmaceuticals Holdings, Inc. |
| Curaleaf Holdings Inc. |
| BOL Pharma |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German hospital procurement committees and Portuguese cultivation facilities lock in pharmaceutical-grade supply access while anchoring price visibility against THC threshold volatility. These contracts index input costs to EU novel food certification benchmarks, insulating institutional buyers from spot-market fluctuations in raw biomass.
Pricing Analysis
Cost-plus contracts with EU GMP certification indexation dominate institutional procurement, where German BfArM reimbursement rates set the reference ceiling. Price differentiation separates FDA-approved isolates from whole-plant extracts, with orphan-drug exclusivity commanding premium positioning against commodity reimbursement pressure in pain management. Pricing pressure intensifies in US state-legal markets as hospital formulary committees consolidate volume and extract concession. Homecare patients demonstrate highest price sensitivity due to limited insurance coverage, while epilepsy specialists show lowest sensitivity where FDA exclusivity eliminates substitute availability.
Supply Chain Analysis
Inbound logistics costs from Canadian and Portuguese cultivation clusters to German processing facilities have tightened container availability on North Atlantic trade lanes, compressing margin for import-dependent distributors. Raw material supply concentrates in Portugal, Denmark, and Canada, with pharmaceutical-grade biomass drawing from GMP-certified greenhouse complexes. Chromatographic purification equipment and specialized analytical chemists constitute critical input dependencies. Single-source vulnerability runs through European cultivation clusters, where geographic concentration creates weather and regulatory disruption risk. Distribution runs through hospital procurement committees and specialty pharmacy networks, displacing legacy direct-to-patient dispensary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against synthetic cannabinoid analogs and next-generation neuromodulators that threaten to displace plant-derived protocols in institutional formularies.
For Market Incumbents: Consolidate pharmaceutical-grade cultivation capacity in Portugal and Denmark to secure batch consistency for BfArM certification. Deepen backward integration into chromatographic purification capabilities, locking in specialized analytical talent that synthetic competitors cannot replicate. Defend against synthetic analog substitution by accelerating FDA submission timelines for expanded indications. For New Entrants and Emerging Players: Lead with homecare sublingual formats in Germany's private-pay segment, where reimbursement gaps create accessible white space outside institutional procurement concentration. Target anxiety disorder applications with wellness-channel positioning under EU novel food designation, avoiding pharmaceutical development timelines. Deploy direct-to-clinic sampling programs that bypass hospital formulary gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward GMP-certified European cultivators with existing German distribution relationships, where regulatory moats sustain long-term viability against US state-legal volatility. Monitor FDA enforcement discretion signals as the critical inflection indicator—tightening discretion would compress whole-plant extract valuations while accelerating isolate-focused acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Dravet syndrome expansion protocols strengthen Epidiolex franchise exclusivity against biosimilar threat. |
| Backward Integration | Portuguese greenhouse acquisition secures pharmaceutical-grade biomass supply for BfArM certification requirements. |
| Regulatory Approval Pathway | FDA botanical drug substance submission unlocks Medicare reimbursement access for chronic pain indications. |
| Hospital System Partnership | Formulary committee relationships in North Rhine-Westphalia anchor institutional volume concentration. |
| Manufacturing Scale-Up | Supercritical CO2 extraction capacity expansion serves distributed clinic preparation demand compression. |
Methodological Framework
The analysis maps cannabinoid oils, capsules, tinctures, and edibles segments, each validated through hospital procurement managers, formulary directors, regulatory affairs leads, and chronic pain specialists. Primary interviews with German BfArM officials, Portuguese cultivation operators, and US state pharmacy board representatives combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down reimbursement spend analysis triangulate volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework models product type, indication, delivery mode, and end-user concentration dimensions, with CAGRs derived from reimbursement rate trajectories and patient access program expansion curves. Input assumptions include THC threshold regulatory stability, GMP certification timeline probabilities, and synthetic cannabinoid competitive entry scenarios.
The analysis sits within stated boundaries; outcomes outside stable German BfArM reimbursement, sustained FDA enforcement discretion, and intact EU novel food designations would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway clarity, cultivation yield consistency, and institutional procurement normalization velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabis Vaporizers Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
US Cannabinoids Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Global Marijuana Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
Europe CBD Oil Market