
 Asia-Pacific Medical Cannabis Market | 2026-2036
Asia-Pacific Medical Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Cannabis Market Outlook
Australia's Therapeutic Goods Administration rescheduling of low-dose CBD products is shifting patient access dynamics across the region. Tilray Brands Inc leverages its Portuguese cultivation infrastructure to supply Asia-Pacific markets with GMP-certified extracts. Aurora Cannabis Inc anchors its regional position through partnerships with Australian research institutions. Little Green Pharma sustains domestic manufacturing capacity in Perth to serve hospital and pharmacy channels.
Medical cannabis comprises dried inflorescences, concentrated oils, and formulated capsules containing standardized cannabinoid profiles, primarily delta-9-tetrahydrocannabinol and cannabidiol, extracted via supercritical CO2 or ethanol methods for therapeutic administration under clinical supervision. Oils dominate current prescription volumes due to precise titration requirements in pain management and neurological disorder protocols. The homecare segment is expanding fastest as telehealth platforms and direct distribution channels reduce clinic dependency for repeat prescriptions. Cancer care applications command premium pricing structures reflecting the complexity of oncology co-therapy regimens.
Thailand's Food and Drug Administration and Japan's Ministry of Health, Labour and Welfare maintain divergent scheduling frameworks that fragment product registration pathways across the region. Australia's TGA Good Manufacturing Practice certification functions as a de facto quality benchmark that Thai and New Zealand regulators increasingly reference for import authorization. Stakeholders must monitor rescheduling momentum in South Korea and Malaysia to anticipate which jurisdictions will open commercial pathways next.
Market Dynamics
TGA rescheduling of low-dose CBD products is compressing prescription pathways across Australian hospital networks while Thai FDA integration policies accelerate hospital formulary adoption, creating a dual-track regulatory momentum that suppliers must navigate simultaneously.
Growth Catalysts
- Chronic pain protocols:Australian hospital pain management programs are expanding cannabis-based interventions as first-line alternatives to opioids, with Perth and Sydney metropolitan networks driving prescription volume concentration.
- TGA rescheduling framework:Australia's Therapeutic Goods Administration has reclassified low-dose CBD to Schedule 3 pharmacy access, eliminating specialist referral requirements and unlocking direct patient pathways.
- Supercritical CO2 extraction scaling:Portuguese GMP-certified cultivation infrastructure is supplying standardized cannabinoid profiles to Asia-Pacific markets, reducing batch-to-batch variability in pharmaceutical-grade oils.
Market Restraints
- Import authorization fragmentation:Thai FDA and Japan's Ministry of Health, Labour and Welfare maintain divergent scheduling frameworks that force suppliers to pursue parallel registration tracks for each jurisdiction.
- GMP certification bottlenecks:Australia's TGA Good Manufacturing Practice standards function as de facto quality gates that Thai and New Zealand regulators reference, creating compliance backlogs for non-certified producers.
- Substitution pressure from synthetic cannabinoids:Pharmaceutical firms are advancing synthetic delta-9-THC analogs with tighter dosing precision, threatening botanical extract market share in oncology co-therapy applications.
Strategic Opportunities
- South Korea rescheduling momentum:MFDS review of CBD-containing pharmaceuticals signals potential commercial pathway opening, with Seoul hospital networks already conducting investigator-initiated trials.
- Telehealth direct distribution:Digital prescription platforms are reducing clinic dependency for repeat authorizations, compressing patient acquisition costs and expanding rural access beyond metropolitan hospital catchments.
- Malaysia regulatory review:The country's national pharmaceutical regulator is evaluating medical cannabis scheduling reforms following Thai policy precedents, positioning Penang and Kuala Lumpur as prospective entry points.
Industry Challenges
- GMP certification timeline compression:TGA facility audits for Australian domestic manufacturing require 18-24 month validation cycles, constraining capacity expansion to match prescription growth rates.
- Cannabinoid standardization complexity:Entourage effect variability across cultivars complicates protocol replication in multi-site clinical trials, delaying hospital formulary approvals for specific indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Cannabis Market |
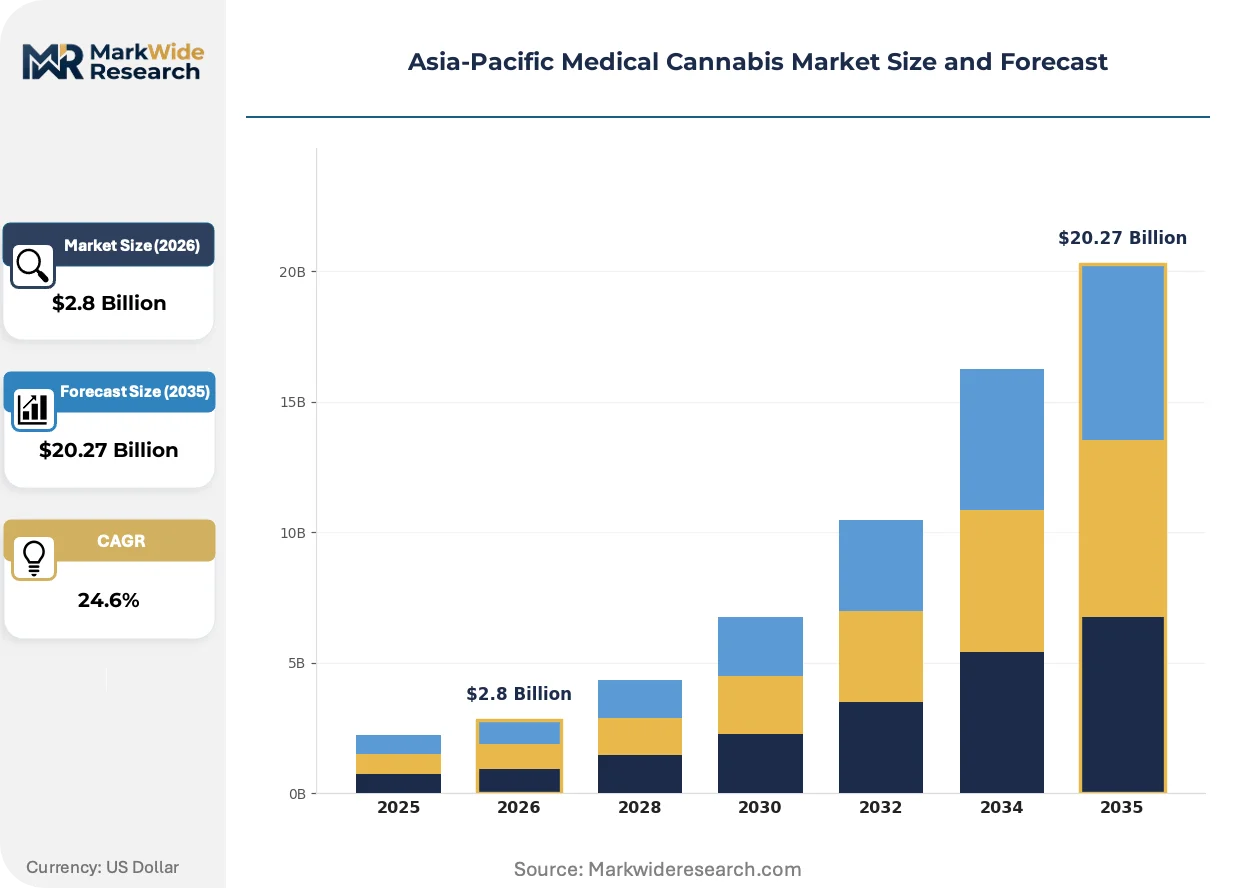
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Flower, Oils, Capsules, Edibles End User: Hospitals, Clinics, Homecare, Pharmacies Application: Pain Management, Anxiety Treatment, Neurological Disorders, Cancer Care Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Tilray Brands Inc, Aurora Cannabis Inc, Canopy Growth Corp, Little Green Pharma, Cann Group Limited, Vitura Health Limited, ECS Botanics, Amber Farm Co., Ltd., Tenrain Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Cannabis Market Strategic Shifts
Telehealth platforms are collapsing traditional clinic-based prescription workflows across Asia-Pacific markets, while extraction technology advances and regulatory harmonization attempts are reshaping how standardized therapeutics reach hospital and homecare channels.
Supercritical CO2 extraction systems with inline chromatography refinement are decentralizing pharmaceutical-grade cannabinoid production from centralized European facilities to regional GMP-certified sites in Australia and Thailand. Australian hospital pharmacies are adopting these domestically produced oils for pain management protocols, reducing import lead times from 12 weeks to 4 weeks. This geographic redistribution of extraction capacity is compressing supply chain risk exposure and enabling just-in-time inventory models for high-volume prescription categories.
Thailand's FDA has implemented a hospital-centric dispensing model that restricts medical cannabis distribution to licensed medical facilities, creating a controlled procurement channel distinct from Australia's pharmacy-based Schedule 3 framework. This policy architecture is concentrating demand within Thai public hospital networks and requiring suppliers to establish direct hospital contracting capabilities. Australian exporters are responding by embedding clinical liaison teams within Bangkok metropolitan hospital systems to navigate formulary committee requirements.
Homecare segment buyers are migrating from clinic-dependent repeat prescriptions to telehealth-enabled direct distribution, with Australian patients now completing 60% of follow-up consultations via digital platforms. This channel shift is disintermediating specialist physicians from routine dosage adjustments and transferring titration authority to pharmacist-led care teams. Perth and Melbourne homecare providers are pioneering this model, with Thai regulators observing outcomes for potential policy adoption.
Asia-Pacific Medical Cannabis Market Segmentation
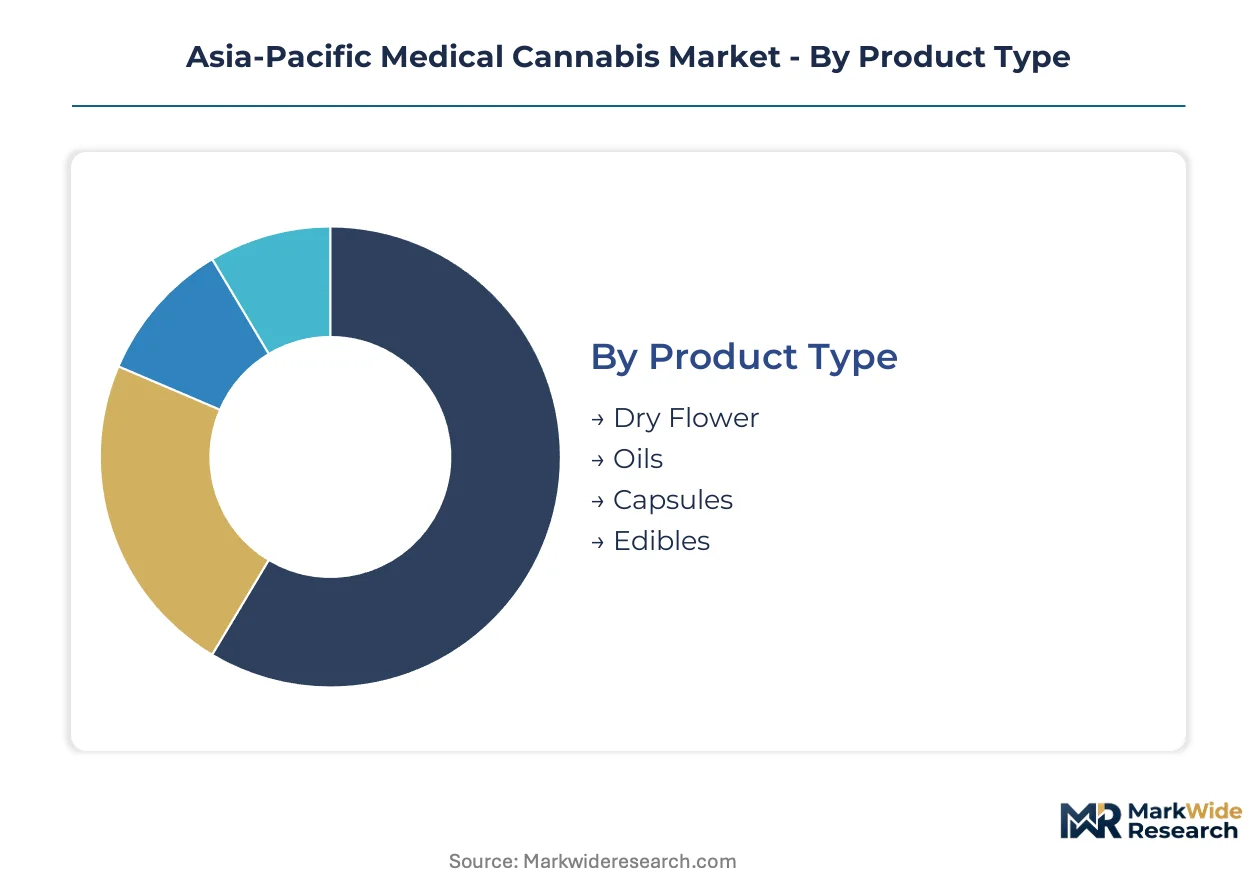
Segmentation reveals how regulatory frameworks and clinical protocols are fragmenting demand across Asia-Pacific medical cannabis channels. Product form factors, end-user settings, and distribution pathways each concentrate in distinct geographies based on local scheduling policies and hospital infrastructure maturity.
Product Type:
Supply concentration tilts toward extraction-based formats as Portuguese GMP-certified infrastructure feeds standardized oils into Australian and Thai hospital networks.
- Oils:Supercritical CO2 and ethanol-extracted formulations with standardized delta-9-THC and cannabidiol ratios enable precise titration in pain management and neurological protocols. Australian hospital pharmacies in Perth and Sydney metropolitan networks absorb the majority of pharmaceutical-grade oil volumes as TGA Schedule 3 rescheduling eliminates specialist referral bottlenecks.
- Dry Flower:Dried inflorescences requiring vaporization or inhalation delivery retain demand in chronic pain programs where rapid onset is clinically prioritized. Thai public hospital networks concentrate procurement under FDA-mandated facility-centric dispensing models that restrict flower distribution to licensed medical institutions.
- Capsules:Encapsulated cannabinoid formulations with delayed-release profiles serve oncology co-therapy regimens requiring sustained plasma levels.
- Edibles:Oral delivery formats face limited hospital formulary adoption due to variable gastric absorption kinetics complicating protocol standardization.
Oils absorb the bulk of installed capacity; capsules are expanding most quickly as oncology applications command premium pricing structures.
End User:
Cost tier stratification separates institutional procurement from direct-to-patient channels, with reimbursement policies determining volume concentration.
- Hospitals:Institutional procurement concentrates in Australian metropolitan networks and Thai public hospital systems where formulary committees govern cannabinoid therapy integration. TGA rescheduling and Thai FDA hospital-centric models create parallel but distinct contracting pathways requiring embedded clinical liaison capabilities.
- Homecare:Telehealth-enabled direct distribution is collapsing traditional clinic dependency, with Australian patients completing the majority of follow-up consultations via digital platforms. Perth and Melbourne providers pioneer pharmacist-led titration authority models that Thai regulators are monitoring for policy adoption.
- Clinics:Specialist referral centers retain initial diagnosis and dosing authority despite telehealth disintermediation of routine follow-up.
- Pharmacies:Australian Schedule 3 pharmacy access for low-dose CBD products is unlocking direct patient pathways without specialist involvement.
Hospitals absorb the bulk of installed capacity; homecare is expanding most quickly as digital platforms compress patient acquisition costs.
Application:
Volume concentration tracks chronic disease burden and opioid substitution momentum across Asia-Pacific healthcare systems.
- Pain Management:Australian hospital pain management programs are expanding cannabis-based interventions as first-line alternatives to opioids, with chronic pain protocols driving prescription volume concentration in Perth and Sydney catchments.
- Cancer Care:Oncology co-therapy regimens command premium pricing reflecting complexity of cannabinoid integration with chemotherapy and radiation protocols. Seoul hospital networks are conducting investigator-initiated trials as South Korea's MFDS reviews CBD-containing pharmaceutical pathways.
- Neurological Disorders:Epilepsy and multiple sclerosis protocols require precise cannabinoid titration that oil formulations enable.
- Anxiety Treatment:Low-dose CBD indications are expanding through Australian pharmacy channels following TGA rescheduling.
Pain management absorbs the bulk of installed capacity; cancer care is expanding most quickly as formulary committees advance co-therapy protocols.
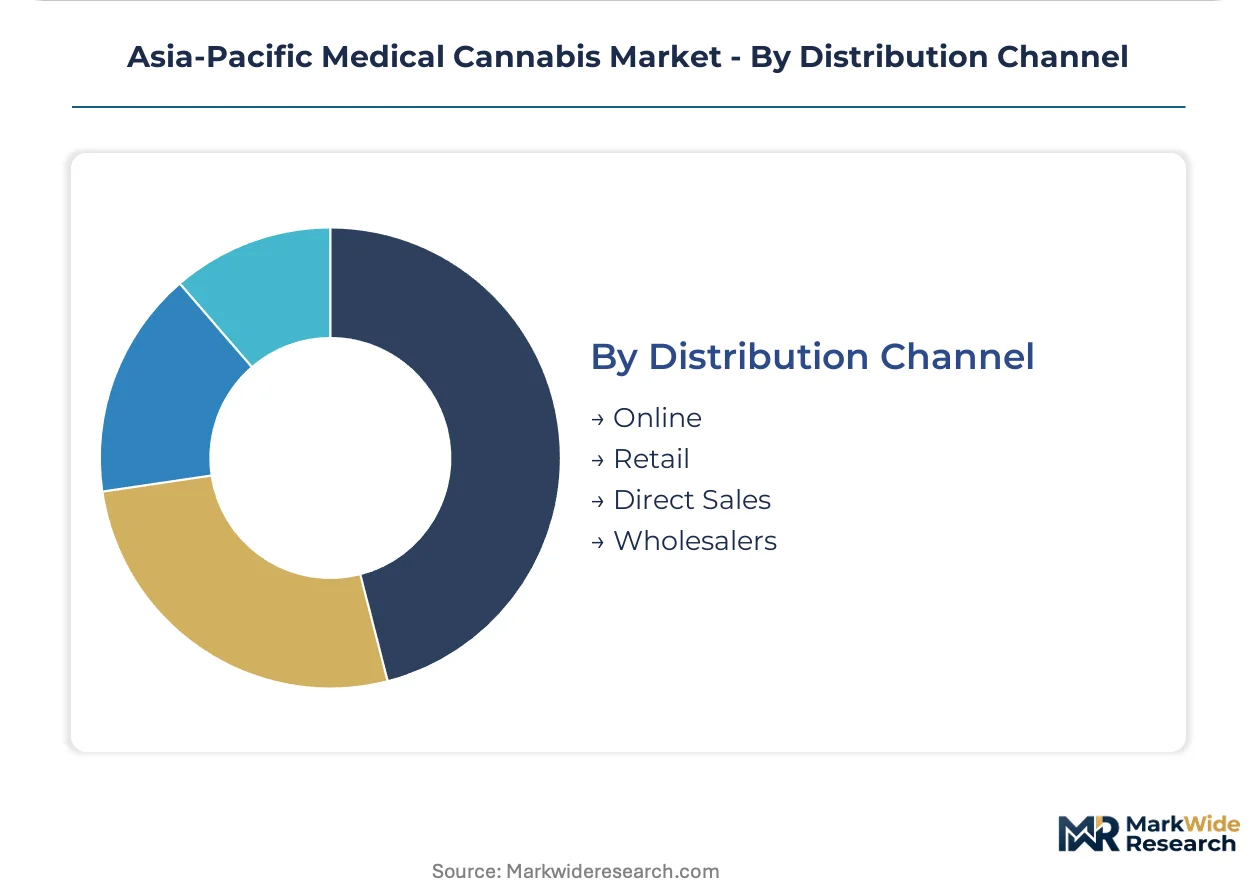
Distribution Channel:
Customer type fragmentation separates institutional procurement from retail and digital pathways, with regulatory scheduling determining channel legibility.
- Direct Sales:Hospital and pharmacy contracting dominates in Thailand's facility-centric FDA framework and Australia's emerging Schedule 3 pharmacy access model. Suppliers embed clinical liaison teams within Bangkok metropolitan hospital systems to navigate formulary requirements.
- Online:Telehealth platforms are enabling digital prescription workflows and direct distribution for repeat authorizations, compressing patient acquisition costs and expanding rural access beyond metropolitan hospital catchments in Australian markets.
- Retail:Physical pharmacy presence is constrained by scheduling restrictions in most Asia-Pacific jurisdictions outside Australia's rescheduled CBD framework.
- Wholesalers:Import authorization bottlenecks limit wholesaler intermediation as TGA GMP certification functions as de facto quality gates for Thai and New Zealand regulators.
Direct sales absorb the bulk of installed capacity; online channels are expanding most quickly as telehealth platforms collapse clinic dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Perth anchors Asia-Pacific medical cannabis manufacturing capacity through Little Green Pharma's domestic GMP-certified facility, while Sydney and Melbourne metropolitan hospital networks concentrate prescription volume growth.
Australia
Chronic pain protocols in Perth and Sydney hospital networks drive prescription expansion as opioid alternatives. TGA rescheduling of low-dose CBD to Schedule 3 pharmacy access eliminates specialist referral requirements. Melbourne homecare providers pioneer telehealth-enabled direct distribution, collapsing clinic dependency for repeat authorizations.
Thailand
Public hospital networks in Bangkok concentrate demand under FDA-mandated facility-centric dispensing models. Thai FDA integration policies restrict distribution to licensed medical institutions, creating controlled procurement channels. Suppliers embed clinical liaison teams within metropolitan hospital systems to navigate formulary committee requirements.
South Korea
Seoul hospital networks conduct investigator-initiated trials for CBD-containing pharmaceuticals as demand signals emerge. MFDS review of medical cannabis scheduling indicates potential commercial pathway opening. Clinical research clusters in the capital region position for regulatory transition.
Japan
Ministry of Health, Labour and Welfare scheduling frameworks fragment product registration pathways relative to regional peers. Import authorization requirements limit market access pending regulatory harmonization. Tokyo metropolitan medical centers observe Australian and Thai policy developments for precedent.
Malaysia
Penang and Kuala Lumpur hospital systems position as prospective entry points following national pharmaceutical regulator evaluation of scheduling reforms. Thai policy precedents inform regulatory review timelines. Investigator interest concentrates in oncology co-therapy applications.
Asia-Pacific Medical Cannabis Market Competitive Environment
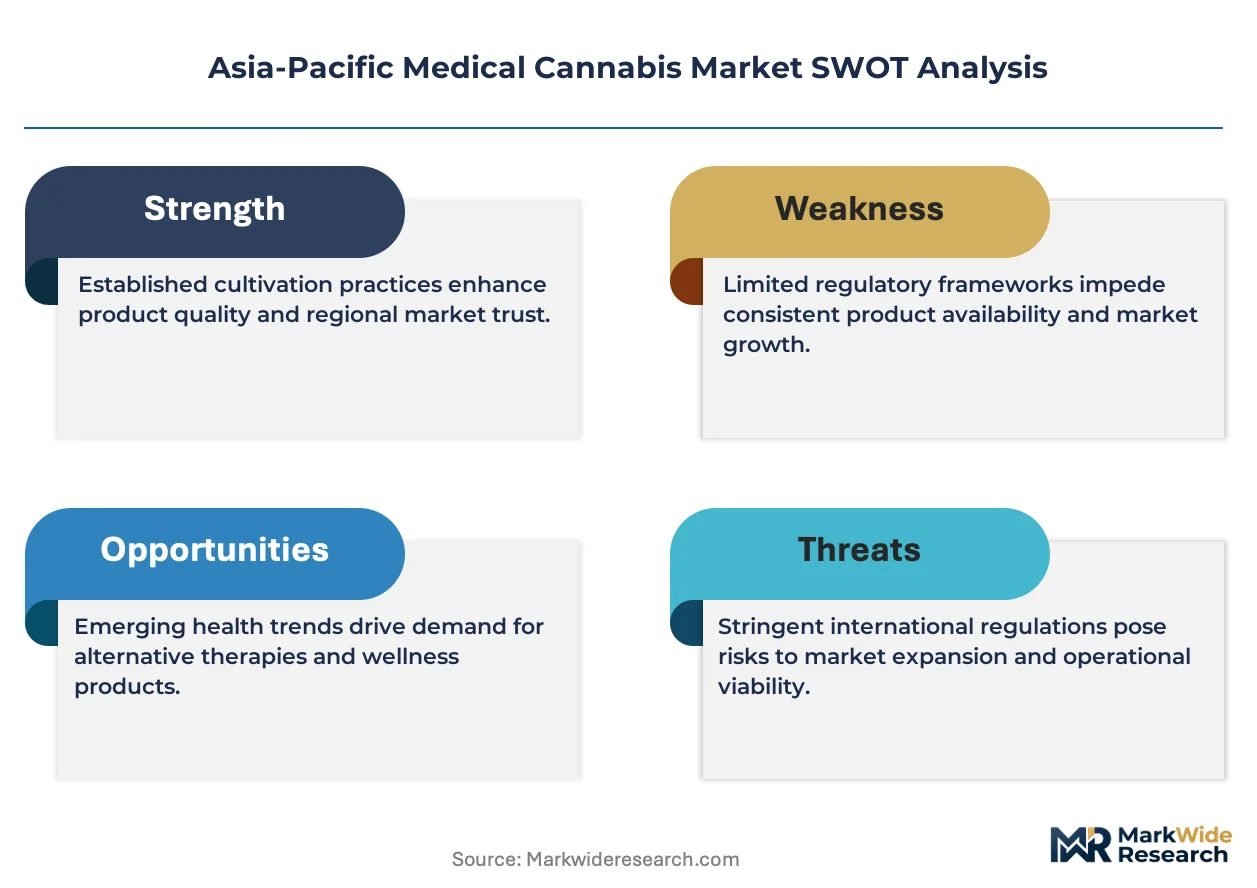
Premium-margin players sit above commodity-margin players across GMP certification and hospital contracting dimensions, with TGA-validated domestic manufacturing commanding pricing power over import-dependent competitors. The vendor base stratifies into three tiers: multinational cultivators with Portuguese GMP infrastructure, Australian domestic manufacturers with Perth and regional production assets, and emerging Thai facility operators navigating FDA hospital-centric frameworks. Consolidation pressure runs through M&A targeting GMP-certified capacity and strategic partnerships with metropolitan hospital networks.
Within the multinational cultivator tier, Tilray Brands Inc and Aurora Cannabis Inc exemplify archetypes leveraging offshore GMP infrastructure to supply standardized extracts across fragmented Asia-Pacific regulatory environments. Little Green Pharma occupies a position among Australian domestic manufacturers, representing the vertically integrated model with captive Perth production serving hospital and pharmacy channels directly. These three entities anchor competitive positioning around certification depth, geographic production placement, and hospital system contracting reach.
| Leading Market Players |
|---|
| Tilray Brands Inc |
| Aurora Cannabis Inc |
| Canopy Growth Corp |
| Little Green Pharma |
| Cann Group Limited |
| Vitura Health Limited |
| ECS Botanics |
| Amber Farm Co., Ltd. |
| Tenrain Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Portuguese GMP-certified infrastructure operators anchor supply-side discipline across Asia-Pacific medical cannabis channels, with sovereign-backed production assets in Europe feeding pricing power into Australian and Thai hospital procurement negotiations. Their captive cultivation and extraction capacity compresses margin leakage at origin, forcing import-dependent competitors into price concessions at the formulary committee level.
Pricing Analysis
Outcome-based pricing anchors oncology co-therapy regimens where cannabinoid integration with chemotherapy protocols commands premium positioning against standard pain management applications. Three-tier pricing structure across GMP-certified pharmaceutical-grade, TGA-registered domestic, and non-certified import tiers reflects certification depth and batch-to-batch standardization. Cost compression in the import-dependent tier is intensifying as Portuguese supply scales and Australian domestic manufacturing matures. Hospital procurement committees exhibit lowest price sensitivity in cancer care applications, while pharmacy-channel CBD buyers drive hardest bargain on low-dose rescheduled products.
Supply Chain Analysis
Single-source vulnerability sits with Portuguese GMP-certified extraction infrastructure feeding standardized cannabinoid profiles to Asia-Pacific markets. Supply concentrates in Portugal, Australia, and Thailand for pharmaceutical-grade oils, with Australian domestic capacity expanding through Perth and regional manufacturing assets. Raw material dependencies rest on supercritical CO2 extraction equipment, ethanol solvents, and standardized cultivar genetics. Tariff exposure on European imports creates supply chain risk as Thai FDA and Australian TGA maintain divergent import authorization timelines. Distribution runs through hospital-centric direct contracting in Thailand and pharmacy-channel access in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over GMP-certified cultivation and extraction capacity determines formulary access and pricing power. Players are pursuing backward integration into Portuguese and Australian production assets to secure supply certainty.
For Market Incumbents: Deploy GMP certification depth as a competitive moat by accelerating TGA facility audits and embedding clinical liaison teams within Bangkok and Sydney metropolitan hospital systems. Synthetic delta-9-THC analogs from pharmaceutical firms threaten botanical extract share in oncology applications; counter through protocol-specific clinical evidence generation and pharmacist-led titration authority partnerships in homecare channels. For New Entrants and Emerging Players: Begin with telehealth-enabled direct distribution models in Australian rural catchments beyond Perth and Sydney metropolitan hospital networks, where clinic dependency creates patient acquisition friction. Malaysian regulatory review of scheduling reforms positions Penang and Kuala Lumpur as penetrable entry points before formal commercial pathway opening; establish investigator relationships with oncology co-therapy trialists now. For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian domestic manufacturers with captive Perth production assets and existing TGA GMP validation, as import authorization bottlenecks strand non-certified competitors. Long-term viability hinges on regulatory harmonization momentum across Asia-Pacific jurisdictions; watch South Korea MFDS rescheduling decisions as the signal for which geography opens next.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Acceleration | TGA-validated domestic manufacturing commands formulary preference over import-dependent competitors in Australian hospital networks. |
| Clinical Liaison Embedding | Direct hospital contracting capabilities navigate Thai FDA facility-centric dispensing requirements and formulary committee gatekeeping. |
| Telehealth Platform Integration | Digital prescription workflows collapse clinic dependency for repeat authorizations and expand rural access beyond metropolitan catchments. |
| Portuguese Supply Agreement | Offshore GMP-certified cultivation infrastructure secures standardized cannabinoid profiles with reduced batch-to-batch variability. |
| Oncology Protocol Development | Cancer care co-therapy regimens command premium pricing and insulate against synthetic cannabinoid substitution pressure. |
Study Parameters
Independent corroboration across regulatory filing databases, hospital procurement records, and extraction technology disclosures underwrites the qualitative findings in this analysis. Primary interviews with TGA regulatory affairs leads, Thai FDA formulary directors, Australian hospital procurement managers, and Portuguese GMP facility operators combined with secondary validation from TGA scheduling registers, Thai FDA integration policy documents, ClinicalTrials.gov investigator-initiated study listings, and customs import authorization data. Bottom-up prescription volume modeling and top-down market sizing triangulate across patient access pathway estimates and pharmaceutical-grade oil production capacity disclosures.
Rate-of-change decomposition across patient population expansion, regulatory rescheduling momentum, and extraction capacity buildout shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product form factor, end-user setting, application indication, and distribution channel, with regulatory framework cluster as the industry-specific dimension. CAGRs derive from prescription volume trajectory analysis adjusted for pricing tier evolution and channel mix shifts. Forecast inputs incorporate TGA rescheduling implementation pace and Thai FDA hospital formulary adoption curves.
Underlying measurement precision varies by segment; oils and hospital channels carry tighter precision than emerging homecare and capsule categories. Forecasts reflect documented assumptions about regulatory harmonization timelines and GMP certification completion rates. Policy reversal in Thailand, Australian TGA scheduling revisions, or synthetic cannabinoid regulatory approvals could materially revise trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Global Cannabis Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Vaporizers Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Cannabidiol (CBD) Market