
 Cannabis Infused Edible Products Market | 2026-2036
Cannabis Infused Edible Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Infused Edible Products Market Intelligence
Market Context
State-level THC potency caps are shifting the cost-of-entry calculus for new edible manufacturers across North America. Canopy Growth Corporation leverages its beverage production infrastructure to navigate divergent provincial rules in Canada. Curaleaf Holdings sustains dispensary channel control in multiple U.S. states with operational scale. Kiva Confections specializes in precision-dosed confectionery that meets California's strict testing protocols.
Technical Definition and Segment Structure
Cannabis infused edible products are food and beverage items incorporating cannabinoids through lipid-based infusion, nanoemulsion, or solventless extraction, with THC or CBD concentrations typically measured in milligrams per serving for standardized dosing. These products serve medical users seeking smoke-free administration and recreational consumers preferring discrete consumption formats. Gummies dominate unit volume due to manufacturing scalability and shelf stability, while nanoemulsion formulations command premium positioning for faster onset times. Dispensaries anchor current distribution value, though online retail platforms are gaining regulatory traction in mature jurisdictions.
Regulatory Framework
The FDA maintains prohibition on interstate commerce of THC-infused foods, while Health Canada imposes strict packaging and labeling standards under the Cannabis Act. State regulators like California's Department of Cannabis Control and Colorado's Marijuana Enforcement Division set independent potency limits and testing requirements. Stakeholders must monitor pending federal rescheduling decisions and corresponding state rule harmonization efforts.
Market Dynamics
State-level THC potency caps across the United States are fragmenting product portfolios and forcing manufacturers to maintain multiple formulation variants for different jurisdictions, elevating compliance costs and compressing margins for mid-tier producers.
Growth Catalysts
- Smoke-free administration preference:Medical users in pain management and oncology settings are selecting edibles over inhalable formats to avoid respiratory irritation, expanding the clinical addressable base beyond traditional cannabis consumers.
- Nanoemulsion technology maturation:Lipid-based infusion processes are achieving sub-100 nanometer particle sizes, enabling beverage applications with rapid onset comparable to smoking and unlocking new consumption occasions.
- Canada's Cannabis Act retail expansion:Provincial regulators in Ontario and British Columbia are licensing additional brick-and-mortar locations, deepening physical access points for infused chocolates and mints.
Market Restraints
- Input cost volatility:Cannabis biomass prices fluctuate with seasonal harvest cycles and testing failure rates, creating margin unpredictability for manufacturers without captive cultivation.
- Interstate commerce prohibition:The FDA's stance against THC-infused food transport across state lines forces redundant production infrastructure in every jurisdiction where a brand operates.
- Technical shelf-life limitation:Lipid oxidation in chocolate and baked goods constrains distribution radius and inventory turnover, favoring local production over centralized manufacturing.
Strategic Opportunities
- Germany's evolving cannabis framework:The Bundestag's deliberation on adult-use legalization creates first-mover positioning for edible manufacturers establishing GMP-certified production ahead of formal market opening.
- Functional ingredient convergence:Formulators are integrating adaptogens and nootropics alongside cannabinoids, targeting wellness consumers seeking multi-functional products beyond recreational or purely medical positioning.
- Direct-to-patient pharmacy channels:Australia's TGA Special Access Scheme is creating a regulated pathway for precision-dosed medical edibles, bypassing the retail dispensary model entirely.
Industry Challenges
- Formulation chemistry talent scarcity:Food scientists with simultaneous expertise in lipid chemistry and cannabinoid stability are concentrated in California and Colorado, constraining expansion timelines for facilities in newer markets.
- Batch-to-batch homogeneity validation:Achieving consistent cannabinoid distribution across gummy matrices requires expensive near-infrared spectroscopy equipment and specialized quality control protocols that smaller entrants struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Infused Edible Products Market |
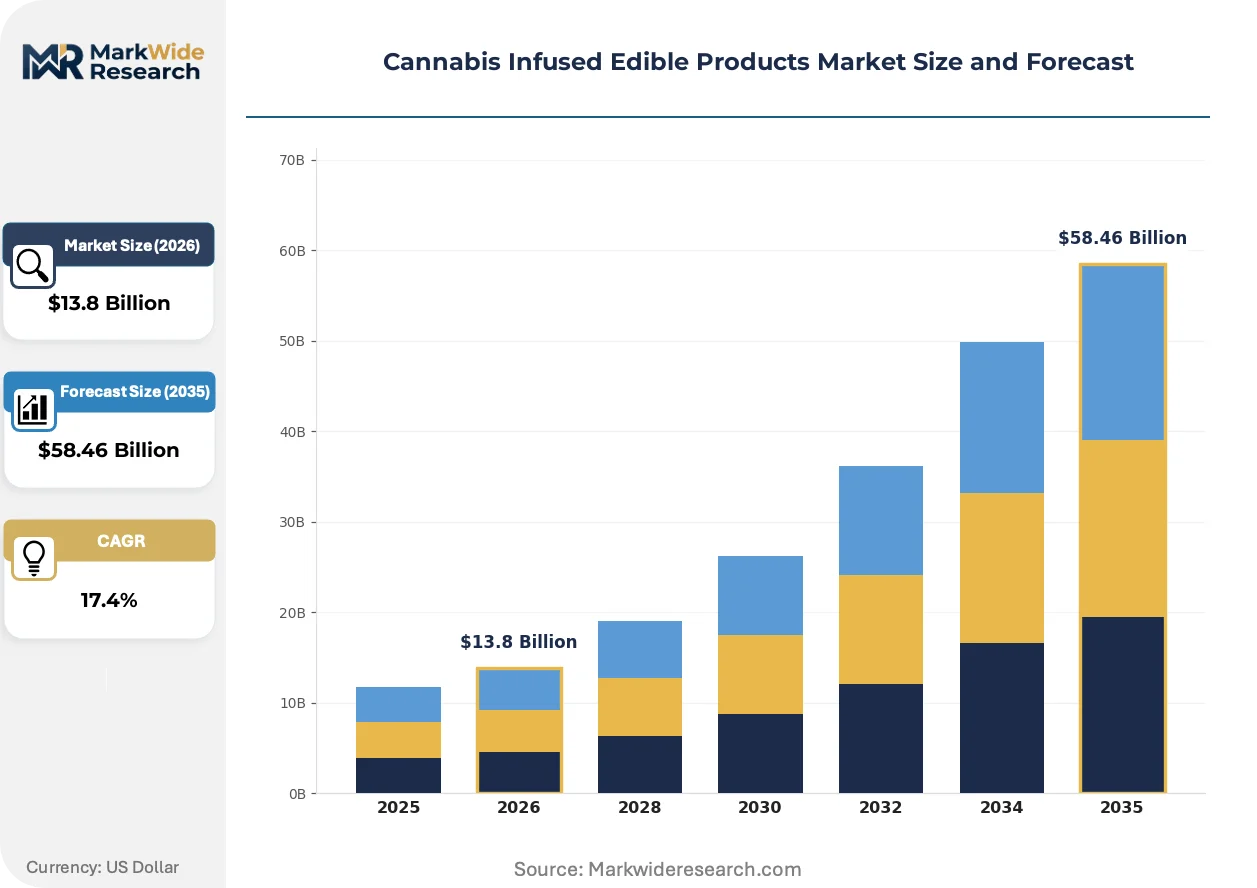
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $58.46 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummies, Chocolates, Cookies, Beverages Formulation: Full Spectrum, Broad Spectrum, Isolate, Nanoemulsion Distribution Channel: Online Retail, Dispensaries, Convenience Stores, Specialty Shops End User: Recreational Consumers, Medical Users, Health Enthusiasts, Seniors |
| Companies Covered | Canopy Growth Corporation, Curaleaf Holdings, Inc., Cresco Labs Inc., Green Thumb Industries Inc., Tilray Brands, Inc., Trulieve Cannabis Corp., Aurora Cannabis Inc., Kiva Confections, Grön Confections, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Infused Edible Products Market Strategic Shifts & Innovations
Manufacturing technology and regulatory adaptation are converging to reshape how edible products are formulated, tested, and brought to market across fragmented legal environments.
Water-soluble cannabinoid powders are modularizing beverage production workflows by enabling standard drink manufacturing equipment to handle infusion without dedicated lipid-handling infrastructure. Mid-sized producers in Colorado and Oregon are adopting these inputs to diversify beyond gummies without capital-intensive emulsion systems. This modularizing capability is compressing the traditional 18-month product development cycle for new beverage lines into sub-6-month iterations.
Health Canada's mandatory plain packaging and child-resistant requirements under the Cannabis Act are elevating production costs while flattening brand differentiation on retail shelves. Manufacturers are responding by investing in tactile finishing and structural packaging engineering to maintain shelf impact within regulatory constraints. Premium chocolate and mint segments bear the heaviest compliance burden, with packaging constituting 35-40% of unit economics in these categories.
Recreational consumers are fragmenting their purchase patterns across multiple low-dose products per transaction rather than single high-potency items, mirroring alcohol's session-drinking culture. Dispensaries in California are reconfiguring floor space to highlight microdose assortments and variety packs, displacing the legacy emphasis on maximum milligram-per-dollar positioning. This behavioral pivot is most pronounced among consumers aged 25-34 in Los Angeles and San Francisco metropolitan areas.
Cannabis Infused Edible Products Market Segmentation
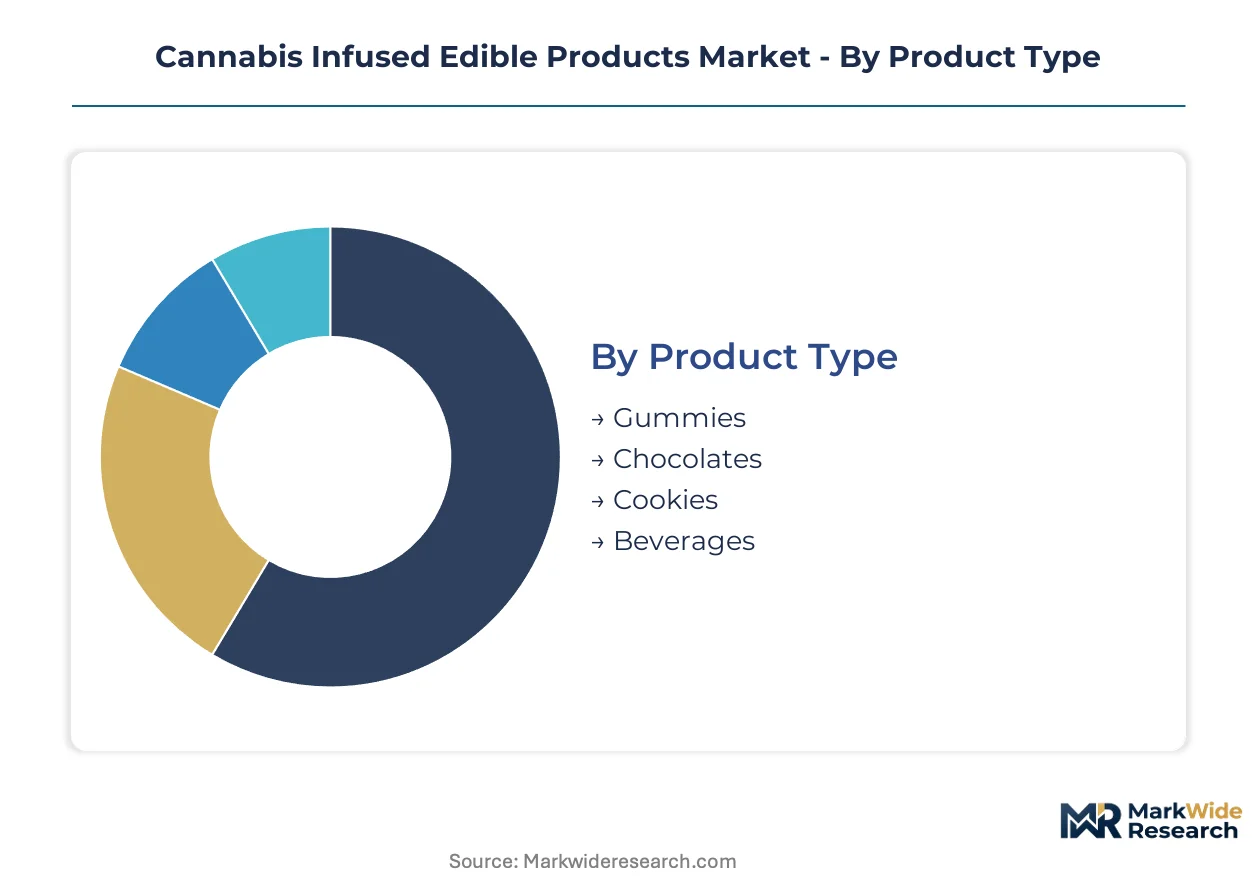
Segmentation in cannabis edibles reveals how manufacturing complexity and regulatory fragmentation create divergent margin structures across product formats. Each dimension—product type, formulation chemistry, channel access, and user motivation—imposes distinct operational requirements that shape competitive positioning.
Product Type:
Supply concentration in gummy manufacturing reflects scalable production infrastructure and extended shelf stability relative to lipid-based alternatives.
- Gummies:Gelatin or pectin matrices enable precise milligram dosing and uniform cannabinoid distribution through industrial depositing equipment. California and Colorado producers dominate volume through automated starch molding lines that achieve 50,000+ units per hour throughput.
- Chocolates:Cocoa butter lipid chemistry demands tempering expertise and climate-controlled distribution to prevent fat bloom and cannabinoid degradation. Premium positioning in Canada and California commands higher per-unit margins despite 35-40% packaging cost burdens from child-resistant mandates.
- Cookies:Baked goods face compressed distribution radii due to moisture migration and oxidation constraints, favoring localized production near urban consumption clusters.
- Beverages:Nanoemulsion or water-soluble powder inputs enable rapid onset positioning, though carbonation stability and emulsion shelf life limit formulation flexibility.
Gummies absorb the bulk of installed capacity; beverages are expanding most quickly.
Formulation:
Cost tier differentiation separates commodity-positioned isolates from premium full-spectrum offerings requiring sophisticated extraction and retention protocols.
- Full Spectrum:Whole-plant extract preserves terpene and minor cannabinoid profiles for entourage effect positioning. Health Canada's strict contaminant limits and California's residual solvent testing create compliance barriers that concentrate production among established processors with in-house analytical capabilities.
- Broad Spectrum:THC-free formulations target health enthusiasts and seniors in jurisdictions with strict workplace testing cultures or medical-only access frameworks.
- Isolate:Crystalline cannabinoid inputs offer batch consistency and simplified regulatory documentation for mass-market gummy production.
- Nanoemulsion:Sub-100 nanometer particle sizing enables water-compatible beverage applications with 10-15 minute onset timing. Patent-protected emulsion technologies from California and Colorado suppliers create input cost premiums that flow through to finished goods pricing.
Isolate formulations dominate unit economics through input standardization; nanoemulsion is climbing the fastest as beverage categories mature.
Distribution Channel:
Channel access patterns reflect regulatory maturity, with physical retail infrastructure concentrating value capture in jurisdictions with established licensing frameworks.
- Dispensaries:Controlled-access retail in California, Colorado, and Canada provides compliant purchase environments with trained staff and product verification. These locations anchor current revenue concentration despite limited geographic density.
- Online Retail:Provincial platforms in Ontario and British Columbia plus licensed delivery services in California are gaining regulatory traction, though interstate and international shipment prohibitions constrain scale.
- Convenience Stores:Limited to CBD-only or non-THC adjacent products in most jurisdictions, with experimental THC access emerging in select Canadian provinces under strict inventory controls.
- Specialty Shops:Wellness-focused retailers in California and Colorado curate premium edible assortments targeting health enthusiasts with functional ingredient positioning.
Dispensaries retain the dominant value share; online retail is gaining share fastest where regulatory frameworks permit direct-to-consumer fulfillment.
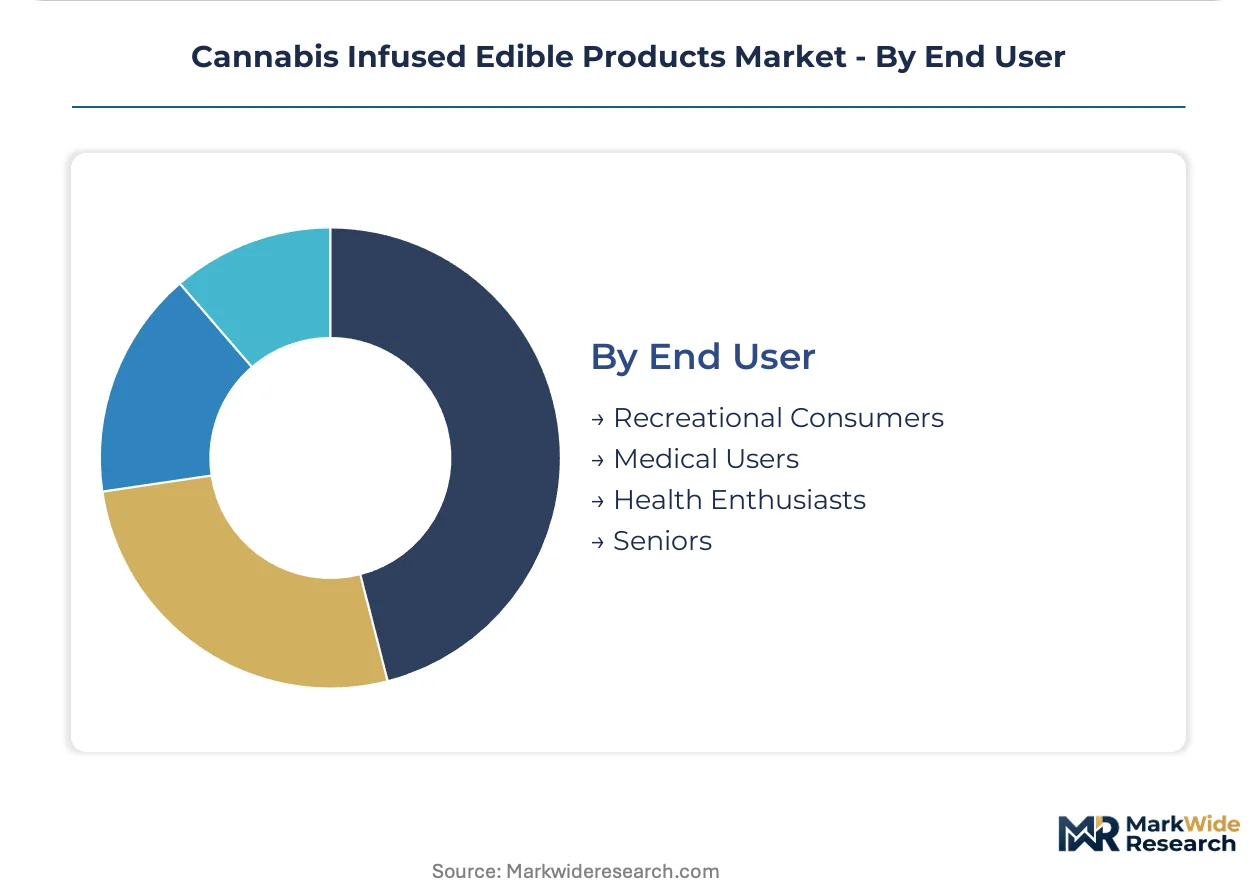
End User:
User motivation segmentation determines formulation priorities, with recreational and medical demand exhibiting divergent potency, onset, and consistency requirements.
- Recreational Consumers:Social and discrete consumption preferences drive demand for low-dose, rapid-onset formats. Los Angeles and San Francisco microdose purchasing patterns are displacing legacy high-milligram positioning among consumers aged 25-34.
- Medical Users:Pain management and oncology applications favor smoke-free administration with precise, repeatable dosing. Australia's TGA Special Access Scheme and Germany's evolving pharmacy channels are creating regulated pathways outside retail dispensary models.
- Health Enthusiasts:Adaptogen and nootropic convergence targets wellness positioning beyond pure recreational or medical framing, with premium pricing tolerance for functional ingredient complexity.
- Seniors:First-time cannabis adoption among aging populations favors familiar formats (chocolates, mints) with conservative dosing and clear labeling in jurisdictions with medical access frameworks.
Recreational consumers represent the largest addressable base; medical users are expanding most quickly through formalized pharmacy and clinician-prescribed channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's Cannabis Act framework created the first federally regulated adult-use market, drawing manufacturers to Ontario and British Columbia under standardized production licensing. Provincial retail expansion and export provisions continue shaping investment location decisions.
United States
California's Department of Cannabis Control maintains the strictest testing protocols for residual solvents and contaminants, forcing reformulation investments from multistate operators. Colorado's Marijuana Enforcement Division pioneered potency labeling standards now emulated elsewhere. Los Angeles and San Francisco metropolitan areas concentrate microdose product innovation and session-consumption retail formats.
Canada
Ontario and British Columbia provincial regulators license additional brick-and-mortar retail locations, deepening physical access for infused chocolates and mints. Health Canada's plain packaging and child-resistant mandates under the Cannabis Act elevate production costs while flattening brand differentiation. British Columbia's established craft cultivation infrastructure supplies biomass to adjacent edible manufacturing facilities.
Germany
The Bundestag's deliberation on adult-use legalization creates first-mover positioning for manufacturers establishing GMP-certified production ahead of formal market opening. Germany's Federal Institute for Drugs and Medical Devices currently oversees medical cannabis frameworks with strict pharmaceutical-grade requirements. Berlin and North Rhine-Westphalia host emerging production clusters targeting eventual recreational distribution.
Australia
The TGA Special Access Scheme creates a regulated pharmacy pathway for precision-dosed medical edibles, bypassing retail dispensary models entirely. Victoria and New South Wales concentrate compounding pharmacy infrastructure capable of cannabinoid formulation. Sydney and Melbourne metropolitan areas anchor clinician-prescribed distribution networks for oncology and pain management applications.
United Kingdom
The Medicines and Healthcare products Regulatory Agency permits specialist clinician prescriptions for specific epilepsy indications under narrow frameworks. London's private healthcare corridor concentrates early adoption of pharmaceutical-grade cannabis extracts. Regulatory uncertainty around broader adult-use access constrains manufacturing investment relative to continental European developments.
Cannabis Infused Edible Products Market Key Industry Players
Canadian producers anchor one tier through federal licensing advantages and export permissions; United States specialists hold operational scale across fragmented state-by-state frameworks. The vendor base clusters around three strategic archetypes: multistate operators with captive cultivation, beverage-focused manufacturers leveraging existing production infrastructure, and precision-dose confectionery specialists. Competitive dynamics center on geographic expansion through state license acquisitions and formulation diversification beyond dominant gummy formats.
Within the precision-dose tier, Kiva Confections and Grön Confections exemplify California-based specialists navigating strict Department of Cannabis Control protocols. Among integrated operators with broader portfolios, Canopy Growth Corporation occupies a position leveraging beverage production infrastructure across Canadian provincial markets, while Curaleaf Holdings represents multistate dispensary channel control through operational scale in multiple United States jurisdictions. These three archetypes—specialist confectionery, beverage-leveraged integration, and multistate retail control—capture distinct margin structures and regulatory compliance capabilities across North American markets.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Curaleaf Holdings, Inc. |
| Cresco Labs Inc. |
| Green Thumb Industries Inc. |
| Tilray Brands, Inc. |
| Trulieve Cannabis Corp. |
| Aurora Cannabis Inc. |
| Kiva Confections |
| Grön Confections |
| Others |
Cost & Logistics Intelligence
Cannabis biomass costs cascade through formulation chemistry tiers into finished goods pricing, with lipid oxidation sensitivity in chocolates and baked goods compressing distribution radii and elevating regional production premiums. State-level THC potency caps fragment manufacturing footprints, forcing redundant facility investments that flow through to per-unit economics across California, Colorado, and Canadian provincial markets.
Pricing Analysis
Short lead-time premiums attach to nanoemulsion beverage inputs and rapid-onset formulations, while spot inventory discounts emerge in seasonal biomass surplus windows. Three-tier pricing structure across premium, standard, and economy levels separates nanoemulsion beverages from full-spectrum chocolates and isolate-based gummies. Price differentiation hinges on certification grade and volume scale, with Health Canada GMP and California Department of Cannabis Control compliance commanding substantial premiums. Cost compression in mid-tier gummy production is intensifying because automated depositing equipment lowers barriers to entry. Medical users through Australia's TGA Special Access Scheme exhibit lowest price sensitivity; recreational microdose consumers in Los Angeles demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for nanoemulsion inputs and water-soluble cannabinoid powders mandate multi-supplier qualification across California, Colorado, and British Columbia extraction facilities. Geographic supply concentration centers on Canada for federal licensing advantages, California for precision-dose expertise, and Colorado for beverage formulation infrastructure. Raw material dependencies include seasonal cannabis biomass, lipid carriers for chocolate matrices, and pectin or gelatin for gummy substrates. Supply chain risk rests on regulatory restriction, with FDA interstate commerce prohibition fragmenting production footprints. Distribution runs through licensed dispensaries in mature state markets, with provincial online platforms gaining regulatory traction in Ontario and British Columbia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry talent scarcity in California and Colorado props pricing power for manufacturers with captive technical capabilities, creating durable margin structures against commodity competition.
For Market Incumbents: Deepen backward integration into nanoemulsion technology and GMP-certified production infrastructure to defend against beverage-focused entrants and German first-movers. Acquire state-level manufacturing licenses in emerging jurisdictions before Bundestag legalization formalizes. Prioritize channel control through dispensary network density in California and Colorado where regulatory compliance complexity concentrates value capture. For New Entrants and Emerging Players: Health enthusiasts seeking adaptogen-cannabinoid convergence represent an underserved buyer archetype with premium pricing tolerance and limited incumbent specialization. Australia's TGA Special Access Scheme pharmacy channel offers the most penetrable regulatory pathway, bypassing saturated retail dispensary competition. Pursue direct-to-patient positioning through compounding pharmacy partnerships in Victoria and New South Wales. For Investors and Strategic Acquirers: Germany's Bundestag adult-use legalization vote is the leading indicator that European production capacity will command acquisition premiums within the 5-10 year viability window. Target vertically integrated specialists with Health Canada export permissions and California Department of Cannabis Control compliance track records. Monitor Health Canada packaging regulation amendments as the specific signal for margin structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Nanoemulsion Patent Licensing | Secures rapid-onset beverage positioning against lipid-based competitors in California and Colorado. |
| GMP Certification Investment | Unlocks German pharmacy channel access ahead of Bundestag recreational framework formalization. |
| Provincial Retail License Acquisition | Deepens physical access points in Ontario and British Columbia under Cannabis Act expansion. |
| Water-Soluble Powder Input Sourcing | Enables modular beverage production without dedicated emulsion infrastructure in Oregon and Colorado. |
| Adaptogen Formulation Development | Captures wellness consumer segmentation beyond recreational and medical positioning in California. |
Research Approach
Independent corroboration across licensed edible manufacturers, provincial regulatory officials, and dispensary procurement managers underwrites the qualitative findings on formulation chemistry constraints and channel access patterns. Primary interviews with food scientists specializing in lipid stability, cannabis compliance attorneys, and Ontario cannabis retail operators combined with secondary validation from Health Canada licensing databases, California Department of Cannabis Control enforcement reports, and SEC filings from publicly traded operators. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical biomass pricing cycles and regulatory amendment timelines structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type, formulation chemistry, distribution channel, and end-user motivation alongside jurisdiction-specific regulatory cluster. CAGRs derived from installed capacity expansion rates and per-capita consumption penetration curves. Industry-specific inputs encompass seasonal harvest yield variability and provincial retail license issuance velocity.
Revisions become necessary when federal rescheduling decisions, German legalization implementation delays, or nanoemulsion patent expiry clusters materialize. Forecasts reflect assumptions on regulatory harmonization pace and biomass input cost stability. Deviation in FDA interstate commerce stance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Legal Cannabis Market
Cannabis/Marijuana
Cannabinoid CB2 Products Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
Cannabis Vaporizers Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Germany and Netherlands Medical Marijuana Market