
 Cannabis Cultivation Market | 2026-2036
Cannabis Cultivation Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Cultivation Market Intelligence
Premium-grade flower with verified terpene profiles and contaminant-free certifications is bifurcating the competitive landscape between craft cultivators and industrial operators. Curaleaf leverages multi-state vertical integration to control distribution from propagation through retail dispensary shelves. Green Thumb Industries anchors its position through branded product lines that command shelf space in limited-license states. Tilray competes on pharmaceutical-grade cultivation standards that satisfy Health Canada and emerging European medical import requirements.
Cannabis cultivation denotes the controlled agricultural production of Cannabis sativa and Cannabis indica for commercial flower, resin extraction, or derivative manufacturing, with critical quality parameters including cannabinoid potency, microbial load limits, and residual solvent thresholds. Indoor cultivation under artificial lighting and climate control dominates premium flower supply chains where batch consistency commands wholesale premiums, while greenhouse methods exploit solar supplementation to reduce energy intensity in mid-tier supply. Hydroponics and aeroponics represent the fastest-expanding technique categories as water-efficient closed-loop systems address drought-prone growing regions and ESG scrutiny from institutional capital.
US state cannabis regulators, Health Canada under the Cannabis Act, and Germany's BfArM impose divergent testing matrices for pesticides, heavy metals, and mycotoxins that determine market access eligibility for cross-border suppliers. The FDA maintains investigational drug pathways for cannabis-derived compounds that constrain medical marketing claims and channel R&D investment toward pharmaceutical rather than wellness positioning. Stakeholders must track how THC potency caps, environmental compliance mandates, and interstate commerce restrictions reshape facility location decisions and capital deployment timelines.
Market Dynamics
THC potency caps and pesticide testing mandates from state-level regulators are compressing margins for non-compliant operators while concentrating production among facilities with in-house analytical laboratories and certified clean-room infrastructure.
Growth Catalysts
- Medical enrollment expansion:Patient registration programs in Germany under BfArM and state-level frameworks in the US are expanding addressable demand for pharmaceutical-grade flower.
- Hydroponic system adoption:Closed-loop water recirculation technology is reducing input costs in drought-prone cultivation zones and attracting ESG-focused institutional capital.
- Terpenoid verification protocols:Third-party certification of volatile compound profiles is commanding wholesale premiums from dispensary buyers seeking product differentiation.
Market Restraints
- Energy cost volatility:Indoor facilities dependent on HVAC and high-intensity discharge lighting face margin compression from electricity price swings in jurisdictions without agricultural rate exemptions.
- Input supply concentration:Specialized nutrient formulations and climate-control equipment concentrate among a limited supplier base, creating procurement bottlenecks during demand surges.
- Interstate commerce prohibition:US federal restrictions on cross-border cannabis shipment force redundant facility construction in each state, duplicating capital deployment.
Strategic Opportunities
- European medical import channels:Health Canada-certified producers are accessing German and Australian pharmaceutical distribution networks as domestic supply falls short of patient demand.
- Derivative product expansion:Extraction infrastructure investments are capturing value from trim and biomass previously discounted as waste streams.
- Automation convergence:Machine vision and robotic harvesting systems are reducing labor dependency in high-wage jurisdictions.
Industry Challenges
- Analytical chemist scarcity:Facilities struggle to hire personnel qualified in HPLC and mass spectrometry methods required for state-mandated contaminant screening.
- Compliance timeline compression:Rapidly evolving testing matrices from regulators force frequent equipment recalibration and protocol revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Cultivation Market |
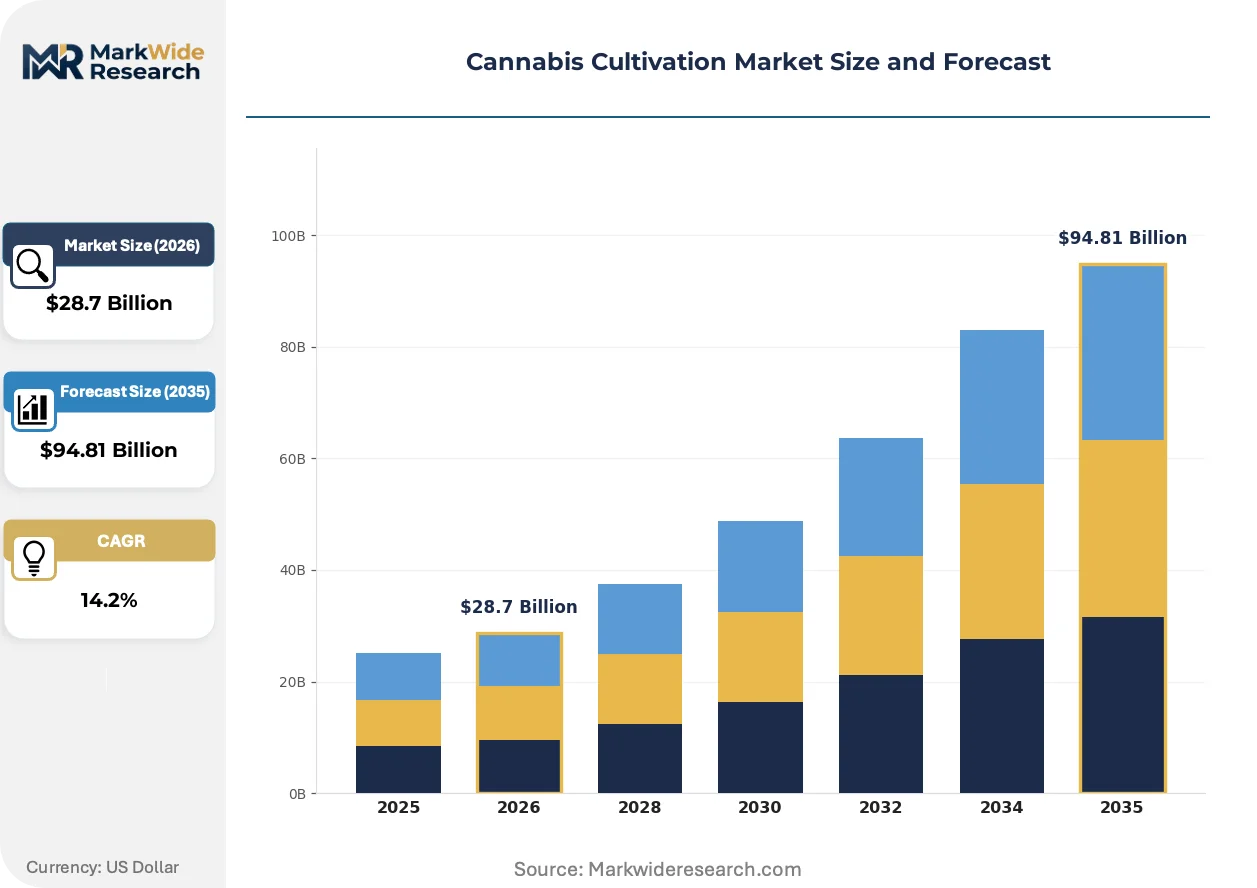
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeds, Clones, Edibles, Concentrates Cultivation Method: Indoor, Outdoor, Greenhouse, Hydroponics Growing Technique: Soil-based, Aeroponics, Aquaponics, Vertical Farming End User: Recreational Users, Medical Patients, Retailers, Distributors |
| Companies Covered | Curaleaf, Trulieve Cannabis, Green Thumb Industries, Verano Holdings, Tilray, Ascend Wellness Holdings, Glass House Brands, Aurora Cannabis, TerrAscend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Cultivation Market Strategic Shifts & Innovations
Automation and precision agriculture tools are compressing the cost gap between craft and industrial cultivation, while regulatory data transparency requirements are forcing investments in seed-to-sale tracking infrastructure.
LED spectral tuning technology is displacing high-pressure sodium fixtures in controlled-environment agriculture. Premium flower cultivators in California and Colorado are retrofitting facilities to capture energy rebates and reduce heat-load management costs. This transition is displacing legacy HVAC-dependent designs that dominated the 2010s facility construction wave.
Health Canada's Cannabis Act amendments are tightening microbial and solvent residue thresholds for derivative products. Licensed producers are responding with pharmaceutical-grade extraction infrastructure that exceeds current requirements. The edibles and concentrates segments face the steepest compliance cost escalation as testing frequency increases.
Dispensary procurement committees are consolidating supplier lists to favor vertically integrated operators with batch-level traceability. Independent craft cultivators without captive retail channels face shelf-space compression in limited-license states. This concentration is most visible in California's Central Valley, where greenhouse clusters now supply multiple retail banners under long-term offtake agreements.
Cannabis Cultivation Market Segmentation
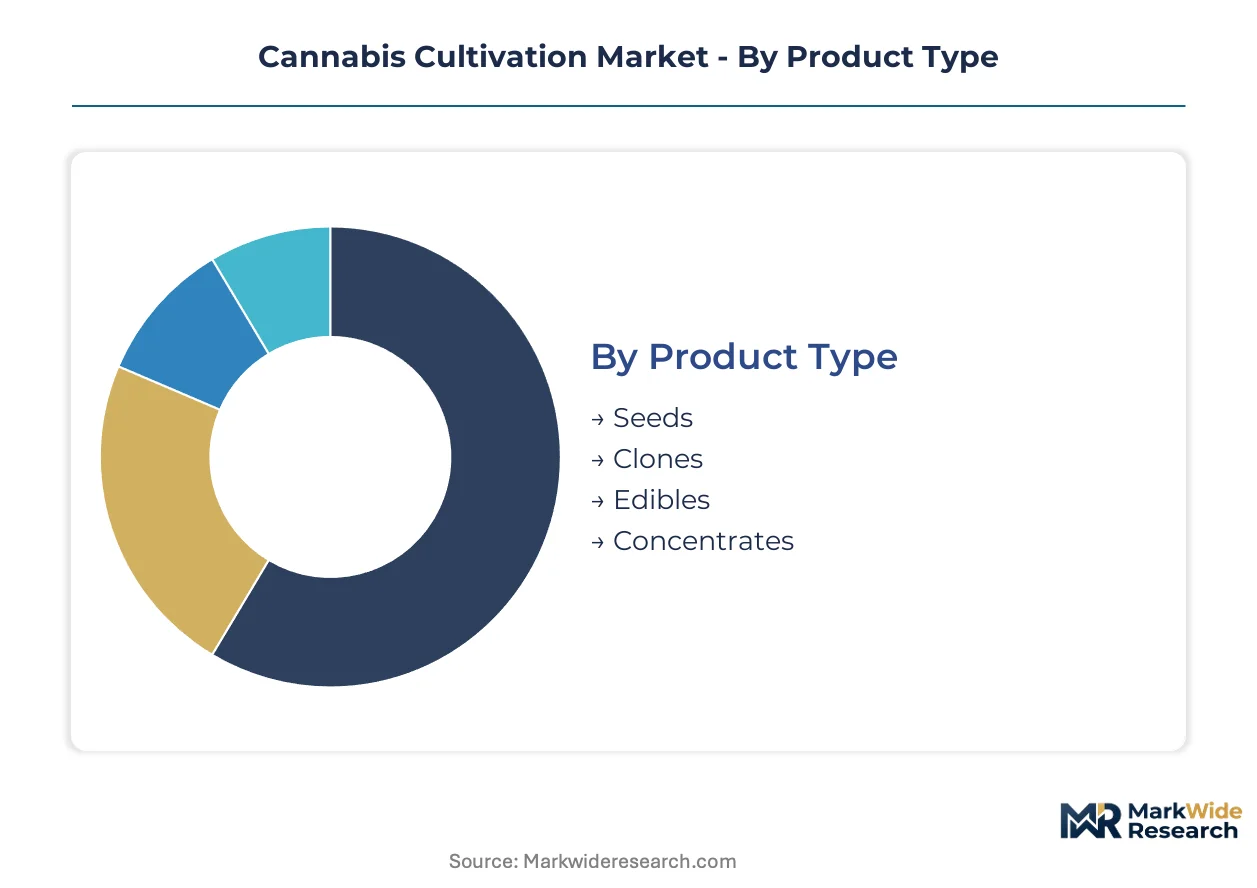
Cultivation method and product type determine capital intensity and margin durability in cannabis agriculture. Segmentation reveals where ESG capital and pharmaceutical-grade compliance are reshaping competitive position.
Product Type:
Margin pools concentrate in derivative manufacturing where extraction technology creates value from biomass previously treated as waste.
- Seeds:Feminized and auto-flowering genetics command wholesale premiums from commercial operators seeking phenotypic consistency. Demand clusters in California's Central Valley breeding facilities serving multi-state operators, constrained by intellectual property fragmentation around proprietary cultivars.
- Concentrates:Resin extraction for vape cartridges and dabbable products captures the highest per-gram margins through solvent and solventless processing methods. Medical patient enrollment in Germany under BfArM and state-level US frameworks is expanding demand for pharmaceutical-grade distillate.
- Clones:Vegetative cuttings from verified mother plants reduce crop cycle risk for craft cultivators lacking in-house breeding programs.
- Edibles:Infused food and beverage products face steep compliance cost escalation as Health Canada and US state regulators tighten microbial and homogeneity testing mandates.
Concentrates holds installed capacity. Seeds is rotating up the share rankings.
Cultivation Method:
Energy cost exposure varies dramatically across these approaches, with solar-supplemented methods attracting institutional capital in drought-prone jurisdictions.
- Indoor:Artificial lighting and climate-controlled environments dominate premium flower supply chains where batch consistency commands wholesale premiums. Facilities in Colorado and Michigan face margin compression from electricity price volatility without agricultural rate exemptions.
- Hydroponics:Closed-loop water recirculation systems reduce input costs and address ESG scrutiny from institutional investors. Adoption is climbing the fastest in California's Central Valley where water scarcity amplifies regulatory risk for soil-based operations.
- Outdoor:Sun-grown cultivation exploits seasonal photoperiods for lowest-cost biomass production, concentrated in Oregon and Washington heritage growing regions.
- Greenhouse:Hybrid solar-supplemented structures balance capital efficiency with environmental control, dominating new construction in limited-license states requiring redundant in-state production.
Indoor dominates revenue contribution. Hydroponics is expanding most quickly on a percentage basis.
Growing Technique:
Water efficiency and labor automation potential differentiate these approaches for capital deployment in high-wage jurisdictions.
- Aeroponics:Mist-based root delivery systems maximize oxygen exposure and nutrient uptake efficiency. Installations in Singapore and the Netherlands demonstrate viability in premium pharmaceutical-grade operations where space constraints dominate location decisions.
- Vertical Farming:Stacked cultivation layers multiply productive capacity per square meter in urban-proximate facilities. Canadian licensed producers are retrofitting warehouse infrastructure to capture municipal energy rebates and reduce last-mile distribution costs.
- Soil-based:Conventional substrate cultivation retains cost advantages in craft and heritage markets where organic certification commands retail shelf placement.
- Aquaponics:Integrated fish-cannabis systems remain niche, constrained by operational complexity and regulatory ambiguity around dual-species agricultural facilities.
Soil-based retains volume leadership. Vertical Farming is gaining share fastest among capital-intensive entrants.
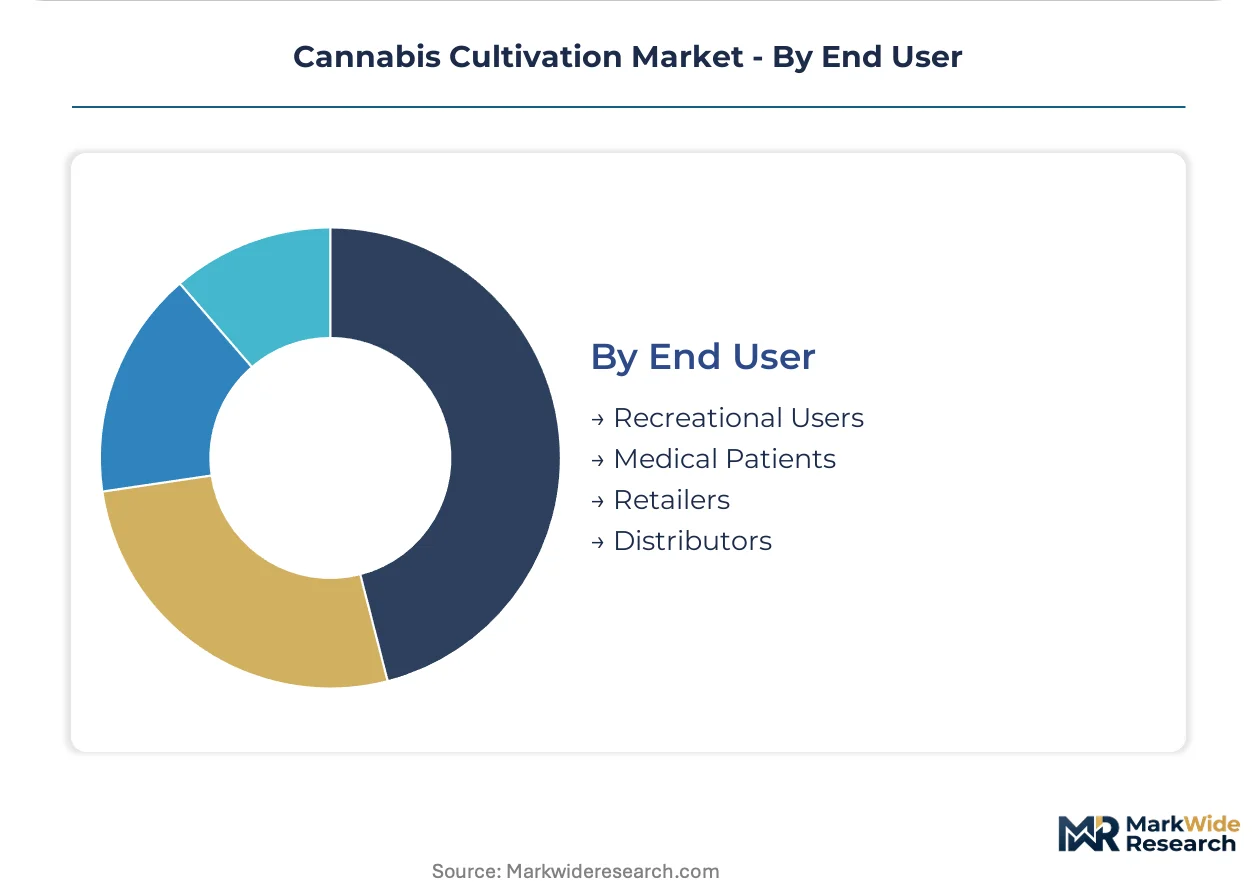
End User:
Purchasing power and compliance requirements create divergent margin profiles across these demand channels.
- Medical Patients:Prescription-based procurement through pharmacy and dispensary channels requires pharmaceutical-grade testing documentation. German BfArM and Australian TGA import channels are expanding addressable demand for Health Canada-certified producers.
- Retailers:Dispensary procurement committees are consolidating supplier lists to favor vertically integrated operators with batch-level traceability. California's Central Valley greenhouse clusters now supply multiple retail banners under long-term offtake agreements.
- Recreational Users:Adult-use demand concentrates in flower and pre-roll formats where brand recognition and terpene verification protocols drive repeat purchase.
- Distributors:Third-party logistics providers face margin compression as state-level seed-to-sale tracking mandates require specialized compliance infrastructure.
Medical Patients anchor pricing power. Retailers is rotating up the share rankings through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping cultivation geography. Health Canada-certified producers supply German and Australian medical markets where domestic output lags patient enrollment. California's Central Valley greenhouse clusters now anchor North American wholesale distribution through long-term offtake agreements with multi-state operators.
United States
State-level limited-license frameworks concentrate production among vertically integrated operators with captive retail channels. FDA investigational drug pathways constrain medical marketing claims while channeling R&D toward pharmaceutical positioning. California's Central Valley hosts the densest greenhouse concentration, with operations exploiting Mediterranean climate conditions and Interstate 5 distribution corridors.
Germany
BfArM patient registration expansion outpaces domestic cultivation capacity, opening import channels for foreign-certified producers. The country's national pharmaceutical regulator maintains strict microbial and potency testing matrices that determine market access eligibility. Rhineland-Palatinate and Baden-Württemberg host emerging greenhouse facilities serving pharmacy distribution networks.
Canada
Health Act amendments tighten contaminant thresholds for derivative products, forcing pharmaceutical-grade extraction infrastructure investments. The national cannabis regulator's certification serves as passport credential for European medical import markets. Ontario and British Columbia anchor licensed producer concentration, with Quebec facilities expanding solventless extraction capacity.
Australia
TGA import pathways expand addressable demand as domestic patient enrollment climbs faster than local cultivation permits. The national therapeutic goods regulator mandates batch-level traceability that favors producers with seed-to-sale tracking infrastructure. Victoria and New South Wales host the majority of licensed greenhouse operations serving pharmacy channels.
Netherlands
Medical cannabis pilot programs create controlled demand expansion within strict production quota frameworks. The country's national pharmaceutical regulator oversees cannabis agency distribution monopoly that constrains private cultivation licensing. North Brabant greenhouse clusters supply the domestic pharmacy system under government-mandated quality protocols.
Cannabis Cultivation Market Key Industry Players
Concentration sits with multi-state operators controlling propagation-to-retail distribution chains. The vendor base stratifies across three tiers: vertically integrated giants with captive retail networks, regional greenhouse specialists with long-term offtake agreements, and craft cultivators competing on terpene verification and organic certification. Dominant competitive moves include backward integration into breeding facilities and strategic partnerships with extraction technology providers.
Within the vertically integrated tier, Curaleaf and Green Thumb Industries exemplify multi-state footprint strategies, while Tilray anchors pharmaceutical-grade positioning for Health Canada and European medical import channels. These operators represent contrasting archetypes: Curaleaf and Green Thumb Industries occupy positions built on state-level license accumulation and retail shelf-space control, whereas Tilray sits within the compliance-intensive medical export segment where certification credentials determine market access.
| Leading Market Players |
|---|
| Curaleaf |
| Trulieve Cannabis |
| Green Thumb Industries |
| Verano Holdings |
| Tilray |
| Ascend Wellness Holdings |
| Glass House Brands |
| Aurora Cannabis |
| TerrAscend |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between California's Central Valley greenhouse clusters and multi-state operators lock in supply access while providing wholesale price visibility across volatile state-level markets. These contracts insulate buyers from spot-market swings in electricity-dependent indoor cultivation zones where agricultural rate exemptions remain contested.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on terpene verification protocols and contaminant-free certifications. Price differentiation stems from batch-level traceability documentation and Health Canada pharmaceutical-grade compliance status. Pricing pressure stems from energy cost volatility in jurisdictions without agricultural rate exemptions, compressing margins for HVAC-dependent indoor facilities. Craft cultivators with organic certification exhibit lowest price sensitivity due to dispensary shelf-space premiums, while biomass suppliers to extraction operations face highest sensitivity to input cost swings.
Supply Chain Analysis
Specialized nutrient formulation suppliers in the Netherlands and climate-control equipment manufacturers in Germany create procurement chokepoints that constrain rapid capacity expansion. Raw material dependencies center on feminized seed genetics, high-purity solvent formulations for extraction, and LED spectral tuning hardware. Supply chain risk concentrates in single-source vulnerability for pharmaceutical-grade testing equipment subject to HPLC and mass spectrometry recalibration mandates. Distribution runs through vertically integrated operators controlling propagation-to-retail channels, with third-party logistics providers facing margin compression from seed-to-sale tracking infrastructure requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified analytical chemists capable of HPLC and mass spectrometry methods represent the critical capability gap constraining facility expansion timelines, with demand outpacing supply across North American and European jurisdictions.
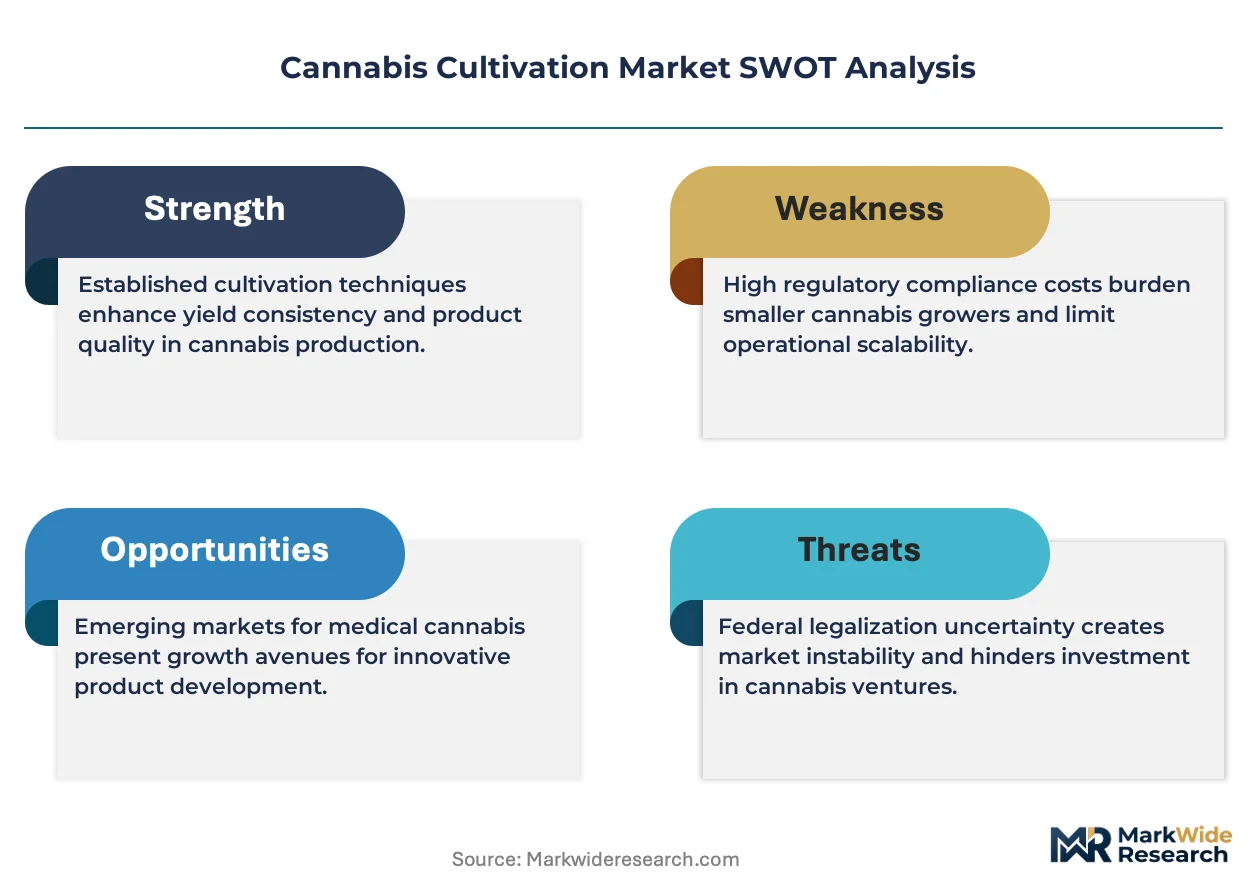
For Market Incumbents: Shield market position by securing in-house breeding facilities that control feminized seed supply chains against genetic IP fragmentation. Prioritize certification investment for Health Canada and BfArM pharmaceutical-grade standards to defend margin structures against commodity biomass competitors. Curaleaf and Green Thumb Industries demonstrate how captive retail channels insulate pricing power from procurement committee consolidation. For New Entrants and Emerging Players: Lead with hydroponic system specialization targeting drought-prone cultivation zones in California's Central Valley where water scarcity amplifies regulatory risk for soil-based competitors. White-space targets include solventless extraction capacity serving German BfArM medical import channels and automated harvesting technology for high-wage jurisdictions. Go-to-market positioning should emphasize ESG credentials attracting institutional capital. For Investors and Strategic Acquirers: Regional greenhouse specialists with long-term offtake agreements to multiple retail banners offer acquisition exposure to procurement consolidation trends without full vertical integration burden. Long-term viability over the next decade hinges on regulatory arbitrage between state-level limited-license frameworks and potential federal interstate commerce liberalization. Signal to monitor: THC potency cap harmonization across US jurisdictions that would reshape facility location economics.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Extraction Infrastructure | Health Canada amendments tightening microbial thresholds force capital deployment exceeding current compliance requirements. |
| LED Spectral Tuning Retrofit Programs | California and Colorado facilities capture energy rebates while displacing legacy HVAC-dependent designs from the 2010s construction wave. |
| Seed-to-Sale Tracking Platform Integration | Dispensary procurement committees consolidate supplier lists to favor operators with batch-level traceability documentation. |
| European Medical Import Channel Partnerships | German BfArM and Australian TGA pathways expand addressable demand for certified producers as domestic supply lags enrollment. |
| Automation and Robotic Harvesting Deployment | Machine vision systems reduce labor dependency in high-wage jurisdictions where analytical chemist scarcity compounds staffing pressure. |
Research Approach
The analysis maps indoor, greenhouse, and outdoor cultivation segments, each validated through cultivation facility operators, dispensary procurement managers, extraction technology providers, and regulatory compliance consultants. Primary interviews with these stakeholders combined secondary validation from Health Canada licensing databases, US state regulator testing mandate filings, BfArM import authorization records, and customs trade data for equipment imports. Bottom-up facility capacity modeling and top-down patient enrollment demand estimates provided cross-verification.
Consistency checks validated volume and value outputs against external benchmarks including state-level production caps, electricity consumption patterns in major cultivation zones, and European medical import authorization trajectories. The analytical framework modeled cultivation method, product type, growing technique, and end-user segmentation dimensions across the projection horizon. CAGRs derived from facility construction permitting velocity, patient registration program expansion rates, and technology adoption curves for hydroponic and LED systems.
The analysis sits within stated boundaries; outcomes outside current regulatory fragmentation and interstate commerce prohibition would require recalibration. Forecasts reflect assumptions around state-level license issuance rates, testing matrix stability, and capital availability for ESG-focused institutional deployment. Practitioners should keep alternative scenarios live as federal policy evolution and German domestic cultivation capacity expansion reshape import demand patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Legal Cannabis Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
US Cannabinoids Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Legal Marijuana Market