
 CBD Gummies Market | 2026-2036
CBD Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Gummies Market Intelligence
A shift from outsourced white-label production toward in-house formulation and extraction is realigning supply economics for premium gummy lines. Charlotte's Web leverages its Colorado hemp cultivation to control cannabinoid consistency from seed to finished product. CBDfx competes through vertical integration into vegan and specialty-diet formulations. Medterra CBD anchors its position with third-party certification programs that satisfy pharmacy and clinician channels.
CBD gummies are chewable confectionery products infused with cannabidiol extract, typically containing 10–50 mg per unit, manufactured through pectin or gelatin-based gelling processes with lipid-based emulsification to enhance bioavailability. Full Spectrum and Broad Spectrum categories dominate current volume, with Isolate formulations occupying higher-margin niches in zero-THC and professional-sports segments. The 25 mg and 50 mg dosage tiers are expanding fastest as consumers graduate from entry-level wellness trials toward targeted therapeutic use cases.
The FDA maintains a restrictive stance on CBD as a dietary supplement ingredient, while the 2018 Farm Bill and state-level cannabis frameworks create a patchwork of permissible claims and channels. EFSA in Europe has suspended novel food authorizations, constraining market access despite consumer interest. Stakeholders must monitor pending FDA rulemaking and state attorney general enforcement patterns to determine whether pharmacy and mass retail expansion will outpace regulatory clarification.
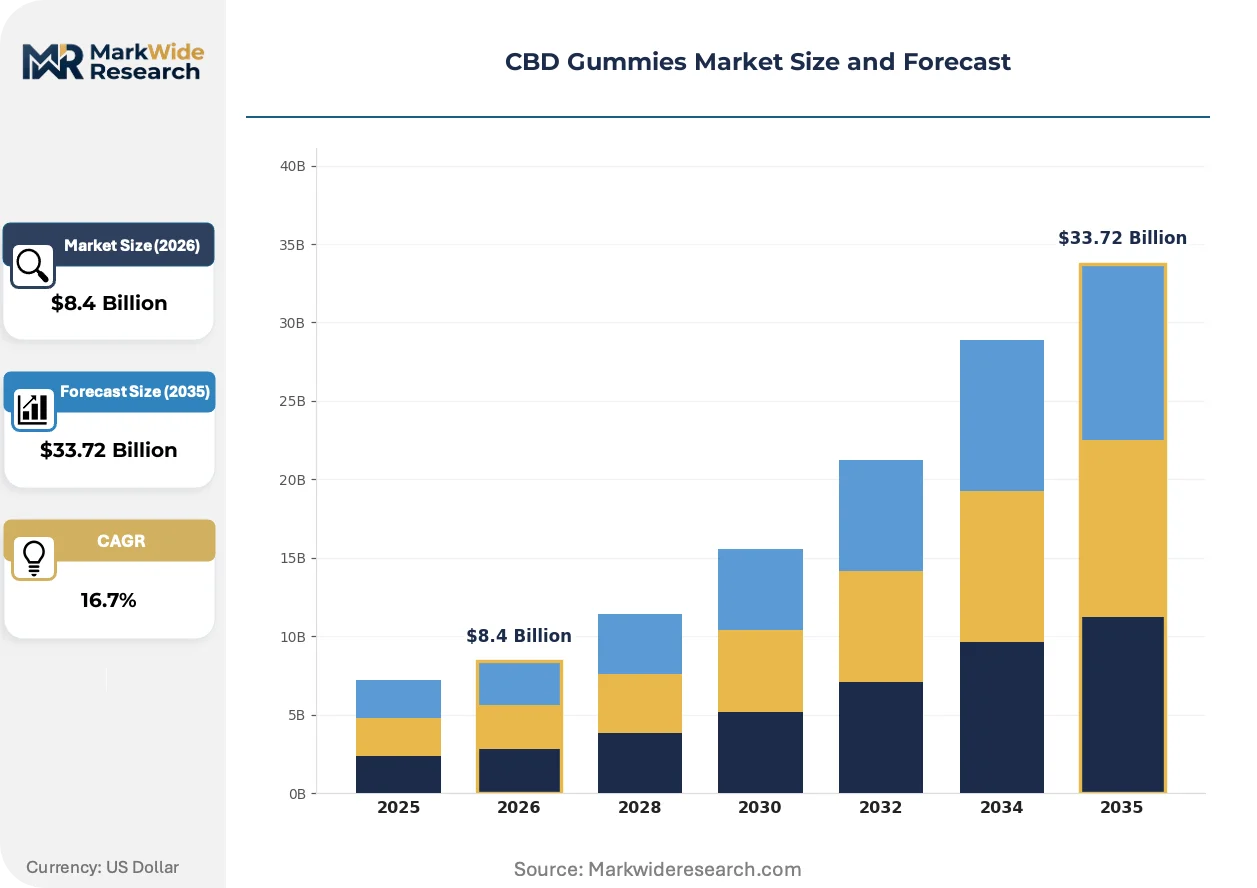
Market Dynamics
The 2018 Farm Bill's reclassification of hemp-derived CBD triggered a supply-side reconfiguration as interstate commerce opened and pharmacy channels became accessible, forcing manufacturers to choose between mass retail scale and premium positioning.
Growth Catalysts
- California dispensary-direct overlap:The state's dual-channel structure—where licensed dispensaries and direct-to-consumer platforms serve overlapping wellness demographics—creates demand density that justifies localized production investment.
- EFSA novel food pathway:Europe's suspended authorization framework, once clarified, will unlock pharmacy and health food retail access across Germany, Netherlands, and UK markets where consumer interest already outpaces legal supply.
- Broad-spectrum formulation technology:Lipid-based emulsification methods that preserve minor cannabinoids while eliminating THC are expanding the addressable market to professional athletes and zero-tolerance workplace segments.
Market Restraints
- FDA dietary supplement exclusion:The agency's refusal to recognize CBD as a Generally Recognized As Safe ingredient blocks mainstream food and beverage fortification, constraining volume growth to specialty channels.
- Hemp biomass price volatility:Colorado and Kentucky cultivation output fluctuates with weather and federal crop insurance availability, compressing margin predictability for extraction-dependent manufacturers.
- Pharmacy channel certification requirements:USP verification and cGMP compliance add 18-24 month qualification timelines that filter out smaller white-label suppliers.
Strategic Opportunities
- Japan's PMDA cosmetics pathway:Topical and ingestible beauty-positioned CBD products bypass pharmaceutical registration, creating a premium skincare-adjacent market with limited domestic competition.
- Sports nutrition crossover:NSF Certified for Sport and Informed Sport programs enable placement in collegiate and professional athletic facilities where THC-free isolate formulations command price premiums.
- Clinical trial infrastructure:Partnerships with academic medical centers for anxiety and sleep disorder studies generate peer-reviewed efficacy data that supports pharmacy reimbursement conversations.
Industry Challenges
- Extraction technician scarcity:Supercritical CO2 and ethanol extraction operations require specialized chemical engineering expertise that outpaces vocational training program output in Colorado and Oregon.
- Lot-to-lot cannabinoid variance:Natural hemp phytochemical variation complicates label claim accuracy, forcing manufacturers to over-formulate or absorb costly re-work when third-party assays deviate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Gummies Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Spectrum, Broad Spectrum, Isolate, Vegan Flavor: Fruit, Mint, Chocolate, Sour, Herbal Dosage Form: 10 mg, 25 mg, 50 mg, 100 mg Distribution Channel: Retail, Online, Pharmacies, Health Stores |
| Companies Covered | Charlotte's Web, CV Sciences, CBD American Shaman, Medterra CBD, Sunday Scaries, CBDfx, Hemp Bombs, Diamond CBD, Premium Jane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Gummies Market Strategic Shifts & Innovations
Formulation science and channel access protocols are diverging as manufacturers split between pharmaceutical-grade certification investments and fast-moving consumer goods scale economics.
Lipid nanoparticle emulsification is consolidating bioavailability claims across premium gummy lines. Wellness consumers seeking measurable onset times are migrating toward water-compatible formulations that bypass first-pass metabolism. This technology compression is eliminating oil-based tincture adjacencies and forcing gummy specialists to invest in in-house nanotechnology capabilities or surrender the high-margin performance segment.
EFSA's suspended novel food authorization process in Europe is freezing mass market entry while preserving pharmacy-adjacent positioning. German and Dutch regulators are permitting cosmetic and topical applications, creating a bifurcated compliance strategy where manufacturers maintain separate formulation portfolios. The professional sports and clinical wellness segments are responding by accelerating third-party certification investments that preempt future purity standards.
Certification-driven purchasing is compressing switching behavior among pharmacy and clinician channels. Buyers in California and Colorado health retail are prioritizing USP-verified and NSF-certified SKUs over price-competitive alternatives, consolidating shelf space toward vertically integrated suppliers with captive laboratory infrastructure. This preference shift is most visible in the 25-50 mg therapeutic dosage tier where efficacy claims require analytical substantiation.
CBD Gummies Market Segmentation
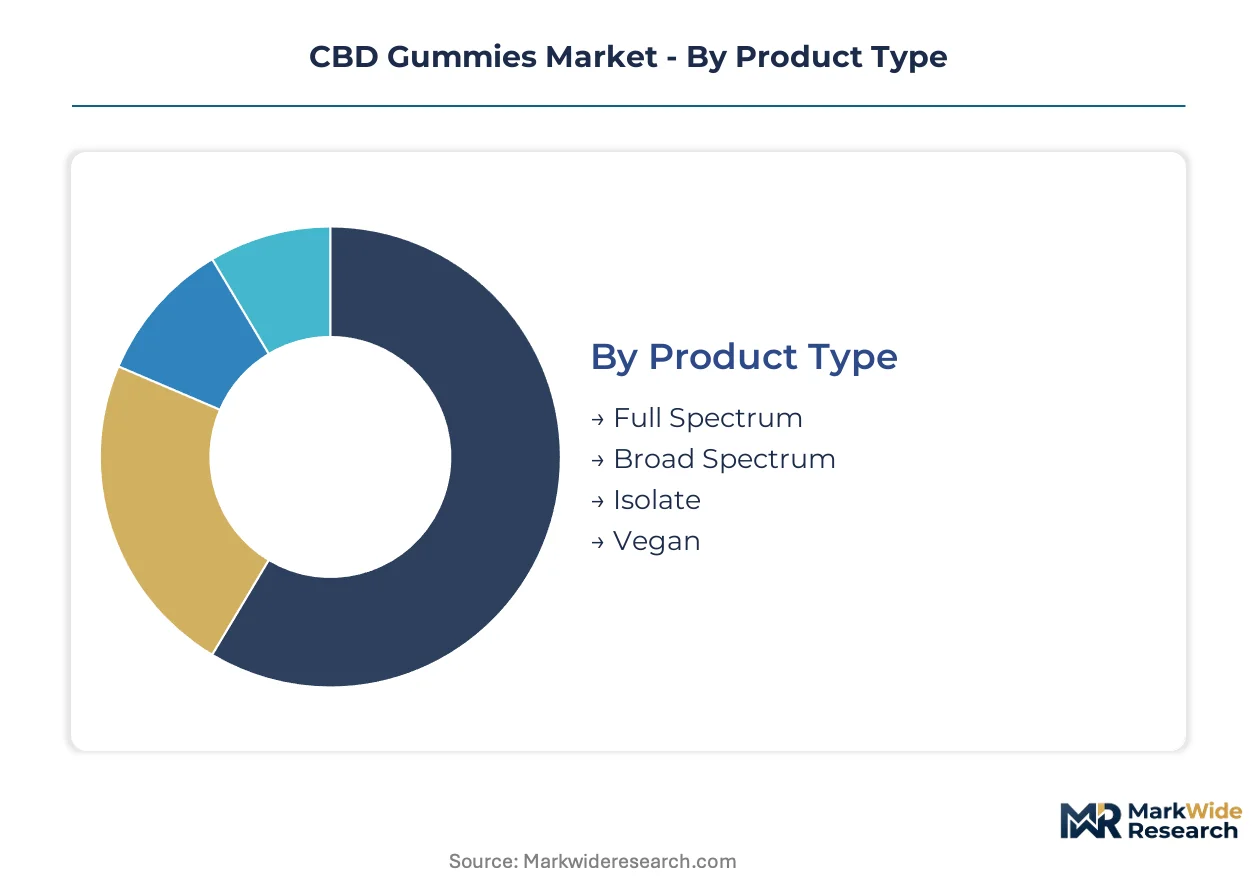
CBD gummy manufacturers align product architecture with distinct consumer risk tolerances and channel compliance requirements. Segmentation strategy determines whether brands pursue pharmacy certification, mass retail scale, or direct-to-consumer agility.
Product Type:
Volume concentrates in THC-inclusive formulations while premium positioning migrates toward guaranteed zero-THC alternatives.
- Full Spectrum:Contains all hemp-derived cannabinoids including trace THC below 0.3%, leveraging entourage effect claims for wellness consumers seeking comprehensive plant chemistry. California dispensary channels and Colorado health retail drive demand density where regulatory familiarity reduces purchase friction.
- Broad Spectrum:Preserves minor cannabinoids and terpenes through refined extraction that eliminates THC entirely, addressing professional athletes and zero-tolerance workplace segments. Lipid-based emulsification technology expands bioavailability claims in this tier.
- Isolate:Pure CBD crystalline form with absolute THC absence commands highest per-milligram pricing in clinical and sports nutrition channels. NSF Certified for Sport programs anchor placement in collegiate athletic facilities.
- Vegan:Pectin-based gelling systems replace gelatin to capture specialty-diet consumers and European markets with stricter ingredient standards. Clean-label positioning supports pharmacy channel entry.
Mature deployment sits with Full Spectrum. Newer deployment is concentrated in Broad Spectrum.
Flavor:
Application context determines flavor architecture—recreational occasions favor bold profiles while clinical positioning demands subtlety.
- Fruit:Berry and citrus profiles dominate mass retail and online channels where palatability drives trial conversion. California and Florida consumers show strongest preference density.
- Mint:Positioned for sleep and anxiety use cases where cooling sensation reinforces relaxation claims. Pharmacy-adjacent health stores favor this profile for clinical credibility.
- Chocolate:Premium positioning targets gifting occasions and evening ritual consumption. Higher cocoa content masks hemp earthiness for novice users.
- Sour:Youth-skewing demographic in recreational-legal states favors tart profiles that differentiate from conventional confectionery. Colorado dispensaries stock this variant heavily.
- Herbal:Chamomile, lavender, and botanical infusions support functional claims around sleep and stress without artificial flavoring. Appeals to ingredient-conscious wellness consumers.
Established penetration centers on Fruit. Accelerating development targets Herbal.
Dosage Form:
Customer maturity progression from wellness trial to therapeutic use reshapes SKU concentration across milligram tiers.
- 10 mg:Entry-level wellness trial format dominates first-time purchaser acquisition and subscription program onboarding. Online direct-to-consumer channels favor this accessible threshold.
- 25 mg:Therapeutic use case graduation point where consumers seek measurable efficacy for sleep and anxiety management. Fastest-expanding tier in California health retail.
- 50 mg:Clinical-strength positioning targets experienced users with established tolerance and specific symptom targets. Pharmacy channel placement requires third-party assay substantiation.
- 100 mg:Maximum-strength format for severe symptom management and medical cannabis patients transitioning to hemp-derived alternatives. Limited distribution to licensed dispensaries and clinician-directed channels.
Volume leadership rests with 25 mg. Steepest expansion trajectory belongs to 50 mg.
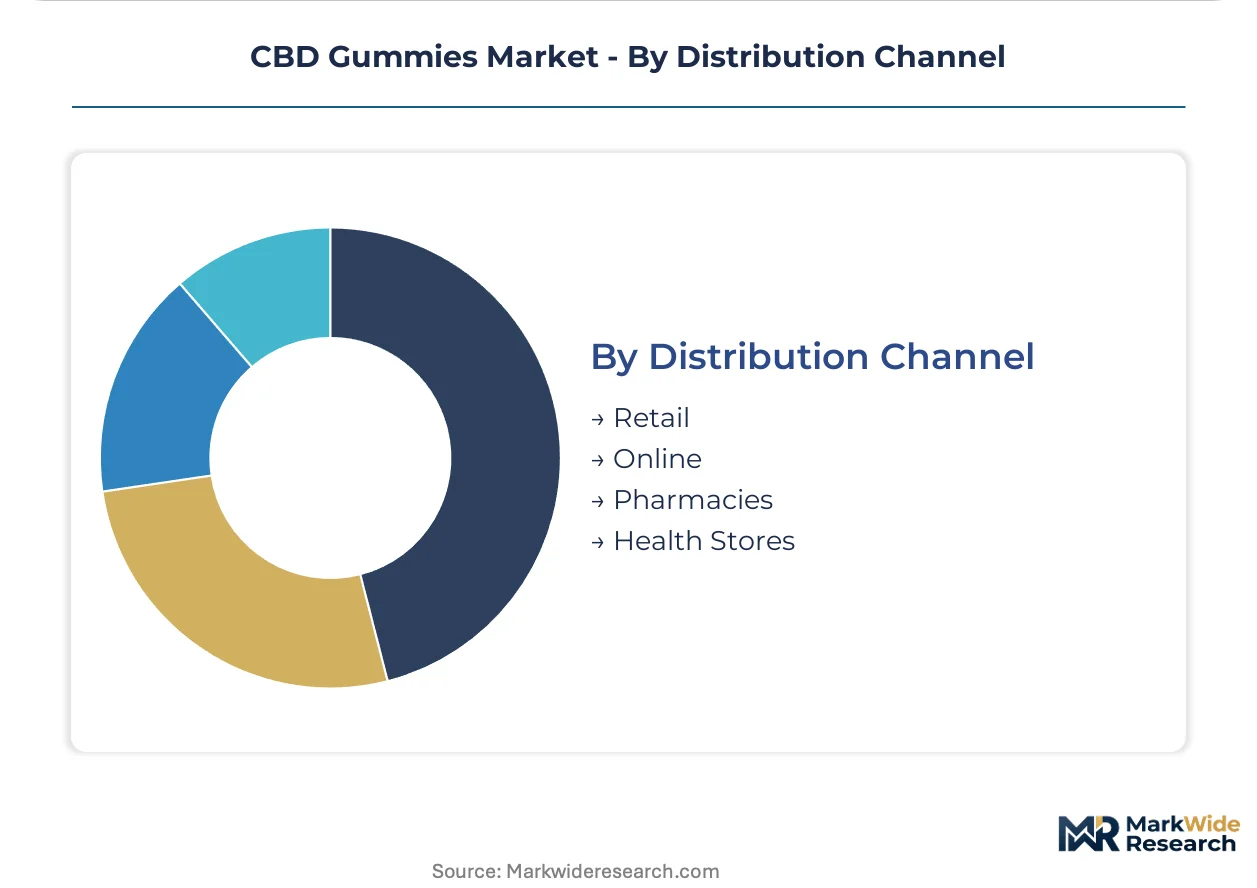
Distribution Channel:
Margin structure and compliance burden split manufacturer focus between mass accessibility and controlled clinical positioning.
- Retail:Mass merchant and convenience store placement requires FDA-compliant labeling without disease claims, constraining marketing language to general wellness. Scale economics favor white-label suppliers.
- Online:Direct-to-consumer platforms enable subscription models and educational content that supports higher-margin specialty formulations. California and New York consumers drive highest per-customer lifetime value.
- Pharmacies:CVS, Walgreens, and independent drugstore placement demands USP verification and cGMP compliance that filters out smaller manufacturers. Clinician recommendation programs accelerate adoption.
- Health Stores:Whole Foods, Sprouts, and regional natural grocers occupy middle ground between mass retail and pharmacy with educated staff and ingredient transparency requirements.
Dominant infrastructure resides in Retail. Emerging investment flows toward Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wellness consumers in California and Colorado are driving the highest per-capita consumption rates, with dispensary-direct channels overlapping mainstream health retail to create unique demand density that justifies localized production investment.
United States
The 2018 Farm Bill reclassified hemp-derived CBD, unlocking interstate commerce and pharmacy channel access across all fifty states. FDA maintains restrictive dietary supplement classification, blocking mainstream food fortification while permitting topical and ingestible wellness positioning. Colorado's Boulder County and California's Los Angeles Basin host the densest extraction and formulation clusters, with vertically integrated manufacturers controlling supply from cultivation through finished goods.
Germany
Consumer interest in CBD wellness products outpaces legal supply channels, creating pharmacy-adjacent demand that manufacturers position toward through cosmetic and topical pathways. EFSA's suspended novel food authorization framework constrains mass retail entry while preserving specialized health store placement. Cologne and Berlin health retailers stock broad-spectrum formulations targeting sleep and anxiety use cases, awaiting regulatory clarity for ingestible expansion.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks permits faster novel food authorization timelines for compliant applicants. The Food Standards Agency maintains an active public list of validated CBD products, creating a two-tier market of authorized versus unauthorized suppliers. London and Manchester direct-to-consumer platforms drive subscription model adoption, with educated consumers prioritizing third-party assay documentation over price competition.
Canada
Health Canada and provincial cannabis authorities maintain separate regulatory tracks for recreational and wellness-positioned CBD, complicating multi-channel distribution strategies. British Columbia and Ontario licensed producers leverage existing extraction infrastructure to supply both adult-use and emerging wellness segments. Vancouver's concentration of cannabis expertise supports formulation innovation, though pharmacy channel penetration remains limited by scheduling restrictions.
Japan
PMDA cosmetics pathway enables topical and ingestible beauty-positioned CBD products to bypass pharmaceutical registration requirements. Tokyo and Osaka premium skincare retailers stock cannabinoid-infused formulations targeting urban professionals seeking stress management alternatives. Domestic hemp cultivation restrictions force reliance on imported isolate, compressing margins for finished goods manufacturers.
CBD Gummies Market Key Industry Players
Vertical integration dominates the current landscape as manufacturers abandon outsourced white-label production to capture margin and control cannabinoid consistency. The vendor base splits between pharmaceutical-grade certification seekers and fast-moving consumer goods scale players. Three archetypes have emerged: vertically integrated cultivator-formulators, specialty-diet positioning specialists, and third-party certification anchors. Capacity expansion and backward integration into extraction represent the dominant competitive moves, with pharmacy channel qualification timelines filtering smaller participants.
Within the vertically integrated tier, Charlotte's Web and CBDfx exemplify contrasting geographic and formulation strategies, while Medterra CBD occupies a certification-focused position. Charlotte's Web represents the cultivator-formulator archetype through its Colorado-based hemp operations. CBDfx exemplifies specialty-diet positioning through vegan and pectin-based formulation development. Medterra CBD anchors the third-party certification vector with USP-verified and clinician-channel positioning. These three companies illustrate how supply chain control, dietary accommodation, and analytical substantiation serve as alternative bases for competitive differentiation in a market where regulatory clarity remains pending.
| Leading Market Players |
|---|
| Charlotte's Web |
| CV Sciences |
| CBD American Shaman |
| Medterra CBD |
| Sunday Scaries |
| CBDfx |
| Hemp Bombs |
| Diamond CBD |
| Premium Jane |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between USP-verified pharmacy SKUs and white-label mass retail units manifests in both margin structures and supply chain configurations, with Colorado and California extraction clusters feeding divergent downstream channels. Premium formulations command analytical substantiation investments that commodity tiers bypass, while FDA dietary supplement exclusion compresses pricing power across all segments dependent on interstate hemp biomass flows.
Pricing Analysis
Volume concentrates in entry-level 10 mg and 25 mg tiers where subscription models and direct-to-consumer platforms compete on accessibility, while 50 mg and 100 mg clinical-strength SKUs retain margin through pharmacy channel scarcity and third-party certification requirements. Price differentiation hinges on USP verification status and lipid nanoparticle emulsification technology adoption, with NSF Certified for Sport programs adding further premiums. Pricing pressure stems from hemp biomass volatility in Kentucky and Colorado cultivation zones, compressing extraction-dependent manufacturers. Mass retail buyers exhibit highest price sensitivity, whereas pharmacy and clinician-directed channels prioritize analytical documentation over per-milligram cost.
Supply Chain Analysis
Direct-to-consumer platforms and pharmacy-adjacent health stores handle differentiated product flows, with California dispensary-direct overlap creating unique channel complexity for manufacturers serving both wellness demographics. Supply concentrates in Colorado, California, and Kentucky, where vertically integrated cultivator-formulators control cannabinoid consistency from seed through finished gummy production. Raw material dependencies include hemp biomass, pectin or gelatin gelling agents, and lipid-based emulsification compounds. Single-source vulnerability sits with supercritical CO2 extraction equipment and specialized chemical engineering labor pools in Boulder County and Los Angeles Basin clusters. Distribution runs through three distinct pathways: mass merchant retail, subscription-based direct-to-consumer, and USP-verified pharmacy channels with 18-24 month qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive hemp cultivation and in-house extraction capabilities has become the defining competitive race, with backward integration determining margin capture and lot-to-lot consistency for pharmacy channel qualification.
For Market Incumbents: Deepen control over Colorado and Kentucky cultivation assets to insulate against hemp biomass price volatility and secure cannabinoid consistency for USP verification programs. Accelerate investment in supercritical CO2 extraction capacity before technician scarcity intensifies, while defending pharmacy shelf space through clinician-directed sampling programs that emerging white-label suppliers cannot replicate.
For New Entrants and Emerging Players: The 2018 Farm Bill's interstate commerce provisions open a window for specialized-diet formulation plays in vegan and pectin-based gummy segments where incumbent gelatin infrastructure creates switching costs. Target Japan's PMDA cosmetics pathway and Germany's topical-adjacent health store channels as penetrable geographies with limited domestic competition, deploying beauty-positioned stress management claims that bypass pharmaceutical registration requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-caps possessing captive laboratory infrastructure given pending FDA rulemaking clarity that will determine pharmacy channel expansion velocity. Long-term viability over a multi-year horizon favors acquisition targets with USP verification already achieved and NSF certification pipelines active, rather than scale-dependent white-label operators exposed to margin compression. Watch EFSA novel food authorization resumption as the critical inflection signal for European mass market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Achievement | Unlocks CVS and Walgreens placement while filtering smaller competitors through 18-24 month qualification timelines. |
| Lipid Nanoparticle Emulsification Investment | Captures bioavailability-focused wellness consumers migrating from oil-based tinctures toward water-compatible gummy formats. |
| Clinical Trial Partnership Development | Generates peer-reviewed anxiety and sleep efficacy data supporting pharmacy reimbursement conversations with clinician channels. |
| Vegan Formulation Line Expansion | Addresses European EFSA ingredient standards and specialty-diet consumer segments with pectin-based gelling systems. |
| Sports Certification Program Enrollment | Enables NSF Certified for Sport placement in collegiate athletic facilities where THC-free isolate commands price premiums. |
Research Approach
Multi-period observation of hemp biomass pricing, extraction capacity utilization, and pharmacy channel SKU proliferation anchored the trend analysis, supplemented by interviews with cultivation operations managers, supercritical CO2 extraction technicians, USP verification program directors, and health store category buyers. Secondary validation drew from FDA warning letter databases, state attorney general enforcement patterns, EFSA novel food submission registers, and customs records of hemp-derived product flows. Bottom-up manufacturer capacity assessments and top-down channel revenue estimates were triangulated to constrain forecast variance.
Segment-weighting across product type, dosage tier, distribution channel, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to observed adoption patterns in California and Colorado health retail, with trajectory adjustments for pending FDA rulemaking and EFSA authorization timelines. Industry-specific forecast inputs included hemp cultivation yield variability, third-party certification program expansion rates, and clinician recommendation program adoption curves.
The model assumes a particular technology adoption path for lipid nanoparticle emulsification; alternative pathways for bioavailability enhancement would alter the outlook for premium tier migration and oil-based tincture displacement. Forecasts reflect assumptions regarding regulatory clarity timelines, hemp biomass price stabilization, and pharmacy channel penetration velocity that warrant periodic reassessment. Periodic stress-testing of base assumptions against FDA enforcement patterns and state-level cannabis framework evolution is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Medical Marijuana Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Medical Cannabis Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Cannabinoid CB2 Products Market
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market